
 Cosmetics ODM Market | 2026-2036
Cosmetics ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics ODM Market Analysis
EU REACH is restructuring ingredient sourcing requirements for third-party cosmetic manufacturers across Europe. Cosmax leverages integrated R&D campuses in South Korea to sustain formulation leadership for global beauty brands. Kolmar Korea anchors high-volume production of skincare and color cosmetics for both established houses and emerging labels. Intercos competes through specialized fragrance and makeup capabilities across Italian and French facilities.
Cosmetics ODM designates the business model wherein original design manufacturers formulate, develop, and produce beauty products under client branding, typically operating with minimum order thresholds ranging from 5,000 to 50,000 units depending on complexity and packaging format. The primary commercial purpose centers on enabling beauty brands to launch products without capital-intensive manufacturing infrastructure or in-house formulation laboratories. Skincare commands the largest revenue share among product types due to higher per-unit margins and repeat purchase frequency, while airless bottle packaging attracts premium positioning as brands emphasize preservation of active ingredients and extended shelf stability. Online retail distribution is expanding fastest among channels, though specialty stores retain margin concentration through personalized consultation and exclusive placement arrangements.
FDA oversees cosmetic safety substantiation and labeling requirements in the United States, while EU REACH and the EU Green Deal impose stringent ingredient disclosure and sustainability benchmarks across European markets. Japan's Ministry of Health, Labour and Welfare maintains distinct quasi-drug classification standards that ODM partners must navigate for functional skincare claims. South Korea's Ministry of Food and Drug Safety enforces rigorous manufacturing facility certifications that shape export eligibility for K-beauty contract producers. Stakeholders must monitor evolving microplastic restrictions and digital product passport mandates as these frameworks increasingly determine which ODM facilities qualify for brand partnerships.
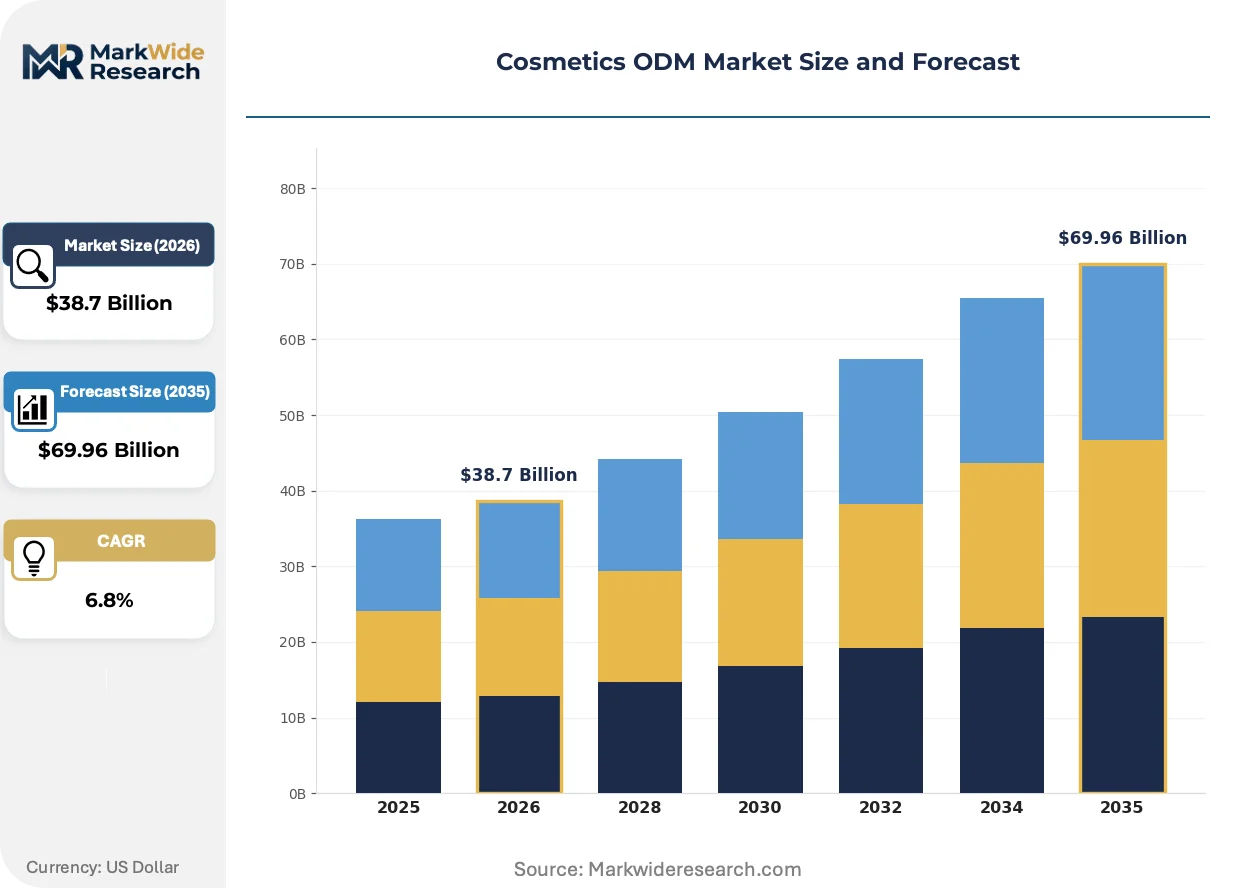
Market Dynamics
EU REACH ingredient disclosure mandates are restructuring formulation partnerships as indie beauty brands outsource compliance-heavy R&D to South Korean contract manufacturers with integrated testing campuses.
Growth Catalysts
- REACH compliance outsourcing:European indie brands redirect formulation investment toward ODM partners holding pre-certified ingredient libraries.
- Airless packaging technology:Premium skincare brands demand active-preservation formats that extend shelf stability without synthetic stabilizers.
- Seoul production clusters:Concentrated R&D-to-manufacturing campuses in South Korea reduce client onboarding cycles for export-bound beauty labels.
Market Restraints
- Raw material concentration:Specialty active ingredient supply chains cluster in Basel and Lyon, creating single-source vulnerability for niacinamide and peptide formulations.
- Facility certification timelines:MFDS export eligibility audits require 18-24 month validation cycles that delay new ODM market entry.
- Quasi-drug classification friction:Japan's PMDA functional claim standards force separate formulation runs for whitening and anti-aging SKUs.
Strategic Opportunities
- Microplastic-free formulation mandates:EU Green Deal restrictions on synthetic polymers create first-mover advantage for bio-based emulsifier specialists.
- Direct-to-consumer channel integration:Beauty brands seek ODM partners with in-house content studios for TikTok-native product storytelling.
- Digital product passport readiness:Early compliance with EU battery-style traceability requirements positions facilities for 2027 enforcement windows.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation specialists with dual expertise in K-beauty trends and EU regulatory filing command 40% salary premiums.
- Cleanroom capex intensity:ISO 22716 certification requires dedicated air-handling infrastructure that smaller ODMs cannot finance.
- Cross-border IP enforcement:Fragrance duplication disputes between Italian and South Korean facilities strain bilateral arbitration frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics ODM Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrances, Haircare Packaging Type: Airless Bottles, Jars, Tubes, Sachets Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores End User: Beauty Brands, Retailers, E-commerce Platforms, Distributors |
| Companies Covered | L'Oréal, Shiseido, Cosmax, Toyo Beauty, Nox Bellcow Cosmetics, Intercos, Estée Lauder Companies, Fareva, Kolmar Korea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics ODM Market Emerging Trajectories
Contract manufacturing is pivoting from volume execution to formulation co-creation as beauty brands compress launch timelines and demand exclusive ingredient access.
Biotechnology-derived actives are modularizing traditional cosmetic chemistry. Fermentation-based ceramides and postbiotic complexes now replace petroleum-derived emollients in mass-market moisturizers. Indie skincare labels in Berlin and Los Angeles specify biotech origin certificates in supplier scorecards. This shift is modularizing how ODMs structure R&D teams, separating synthetic chemists from bio-process engineers.
EU Green Deal microplastic restrictions are eliminating polyethylene microbeads and synthetic film-formers from rinse-off products. French color cosmetics manufacturers reformulate mascara and eyeliner with rice powder and mineral wax substitutes. Italian fragrance houses face parallel pressure on synthetic musk biodegradability. The regulation is compressing formulation iteration cycles as brands race to relaunch portfolios before 2026 enforcement.
Beauty brand procurement is fragmenting across micro-ODM specialists rather than consolidating with full-service giants. Niche Korean manufacturers with single-category expertise in sun care or lip tint now win contracts from direct-to-consumer labels in São Paulo and Jakarta. These partnerships prioritize speed-to-sample over minimum order thresholds. The pattern is most visible in Southeast Asian markets where local influencers drive weekly product drops.
Cosmetics ODM Market Segmentation
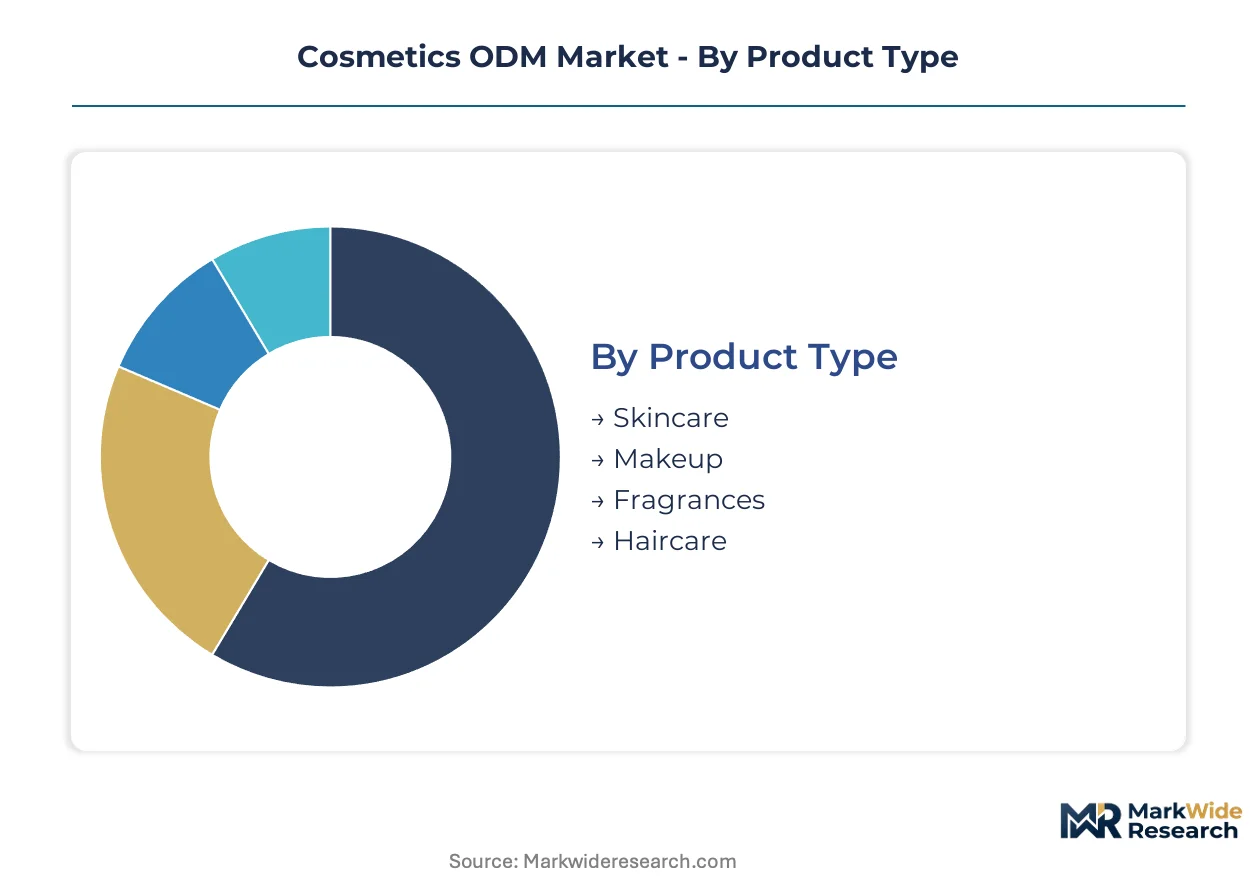
Segmentation in Cosmetics ODM reveals how regulatory certification burdens, packaging technology requirements, and channel-specific compliance protocols reshape contract manufacturer selection criteria across beauty brand portfolios.
Product Type:
Skincare formulations demand MFDS facility certification and REACH pre-registration for active ingredient libraries, while color cosmetics face separate stability testing protocols.
- Skincare:Serum and cream formulations require airless-compatible viscosity engineering and documented preservative efficacy testing under ISO 22716. Demand concentrates in Seoul R&D campuses serving EU indie brands navigating REACH disclosure mandates. The segment commands premium unit economics through repeat purchase cycles and active-ingredient complexity.
- Makeup:Color cosmetics involve pigment dispersion chemistry and film-former selection now pressured by EU Green Deal microplastic restrictions. Italian and French ODM facilities specialize in texture innovation for luxury brand partnerships. Reformulation timelines compress as synthetic polymer replacements enter qualification pipelines.
- Fragrances:Fine fragrance compounding demands IFRA compliance and biodegradability documentation for synthetic musk alternatives.
- Haircare:Shampoo and conditioner production scales through high-volume liquid filling lines with sulfate-free and silicone-free certification options.
Skincare sits at the top of the volume ranking, with makeup climbing the fastest as clean color cosmetics capture direct-to-consumer brand investment.
Packaging Type:
Packaging selection drives per-unit cost tiering and shelf-stability performance, with certification requirements varying by material contact regulations.
- Airless Bottles:Pump-dispensed formats with oxygen-barrier engineering preserve retinol and vitamin C potency without synthetic stabilizers. Korean manufacturers integrate blow-fill-seal automation for 5,000-unit minimum orders. Premium skincare brands specify these for active-preservation positioning.
- Jars:Wide-mouth containers suit thick cream rheologies and spatula-access consumption rituals. European glass jar suppliers face energy cost volatility affecting ODM quoting structures.
- Tubes:Laminate and extruded formats enable precise dosing for sunscreen and cleanser applications with flip-cap or screw-cap closure options.
- Sachets:Single-use foil pouches support sample distribution and travel-size SKUs with minimal per-unit material cost.
Airless bottles lead margin contribution, with sachets expanding most quickly through influencer-driven sampling campaigns.
Distribution Channel:
Channel selection determines batch size flexibility, labeling complexity, and the regulatory jurisdictions triggering compliance obligations.
- Online Retail:Direct-to-consumer fulfillment demands small-batch agility and TikTok-optimized content creation from ODM partners. South Korean contract manufacturers now embed in-house studios for native video production. Berlin and Los Angeles indie brands prioritize 72-hour sample turnaround over volume discounts.
- Specialty Stores:Sephora and Ulta placement requires prestige packaging specifications and exclusive formulation access agreements. Italian fragrance ODMs maintain dedicated lines for retailer-owned brand programs.
- Supermarkets:Mass-market retail mandates high-volume production thresholds and simplified SKU matrices for shelf-space efficiency.
- Department Stores:Counter-based distribution involves gift-with-purchase assembly and seasonal limited-edition coordination.
Specialty stores anchor current revenue concentration, with online retail gaining share fastest as micro-ODM specialists enable weekly product drops.
End User:
End-user type structures the commercial relationship, with beauty brands demanding exclusivity clauses that retailers and platforms typically waive.
- Beauty Brands:Label owners seek formulation IP protection and minimum order flexibility across indie, mid-market, and luxury tiers. Korean ODMs differentiate through integrated R&D campus access and export certification support. Contract terms increasingly specify biotech active sourcing and digital product passport readiness.
- Retailers:Private label programs for Sephora Collection or Target's in-house beauty lines require white-label agility and rapid line extension capabilities.
- E-commerce Platforms:Amazon and Tmall proprietary brands demand supply chain traceability documentation and automated replenishment integration.
- Distributors:Regional wholesalers in Southeast Asia and Latin America aggregate fragmented brand demand into consolidated production runs.
Beauty brands dominate contract value, with e-commerce platforms ascending fastest as platform-owned beauty labels multiply across Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with dual EU-REACH and K-beauty certification cluster in Seoul, Lyon, and New Jersey, anchoring regional production capabilities. These talent concentrations determine which contract manufacturers qualify for cross-border brand partnerships. Facility certification timelines and regulatory filing expertise now outweigh labor cost in site selection decisions.
South Korea
MFDS-certified campuses in Songdo and Osong attract European indie brands seeking REACH-compliant formulation outsourcing. The Ministry of Food and Drug Safety enforces 18-24 month export eligibility audits that screen new market entrants. Seoul Capital Area manufacturers integrate blow-fill-seal automation for airless packaging minimum orders of 5,000 units.
Italy
Lombardy-based fragrance compounders specialize in IFRA-compliant fine fragrance with synthetic musk biodegradability documentation. The country's national chemical regulator ANSM enforces EU Green Deal microplastic restrictions on color cosmetics. Milan-area facilities reformulate mascara and eyeliner with rice powder substitutes ahead of 2026 enforcement deadlines.
United States
New Jersey and California formulation houses serve direct-to-consumer brands demanding 72-hour sample turnaround. FDA cosmetic safety substantiation requirements pressure brands to outsource preservative efficacy testing. Greater Los Angeles micro-ODMs embed TikTok-native content studios for influencer-driven product drops.
France
Auvergne-Rhône-Alpes clusters specialize in premium skincare with documented active-ingredient sourcing for Sephora placement. ECHA REACH pre-registration requirements favor manufacturers with certified ingredient libraries. Lyon-area peptide and niacinamide suppliers create single-source vulnerability for global formulation pipelines.
Japan
Osaka and Tokyo contract manufacturers navigate PMDA quasi-drug classification for whitening and anti-aging functional claims. METI standards force separate formulation runs for products making efficacy assertions. Kansai-region facilities maintain dedicated lines for retailer-owned brand programs serving domestic department store counters.
Cosmetics ODM Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated R&D-to-manufacturing campuses command premium positioning. The vendor base stratifies between full-service giants with multi-category capabilities and micro-ODM specialists with single-category speed advantages. Three archetypes dominate: Seoul-based integrated campus operators, European fragrance and color cosmetics specialists, and agile direct-to-consumer enablers with content studios. Capacity expansion and strategic partnerships represent the dominant competitive moves as brands compress launch timelines.
Among Korean integrated manufacturers, Cosmax, Kolmar Korea, and Toyo Beauty exemplify the campus-based archetype with MFDS-certified export eligibility. These Seoul-area entities anchor formulation leadership for global beauty brands navigating REACH compliance. European fragrance and color specialists such as Intercos occupy positions serving luxury house partnerships with IFRA-compliant compounding capabilities. Fareva represents the diversified manufacturing group structure with multi-site European presence.
| Leading Market Players |
|---|
| L'Oréal |
| Shiseido |
| Cosmax |
| Toyo Beauty |
| Nox Bellcow Cosmetics |
| Intercos |
| Estée Lauder Companies |
| Fareva |
| Kolmar Korea |
| Others |
Supply Flow & Price Mechanics
Indie beauty brands with compressed R&D budgets anchor pricing power among South Korean ODMs with pre-certified REACH ingredient libraries. These buyers accept volume-scaled contracts that stratify across MFDS certification tiers, ISO 22716 compliance levels, and airless packaging integration depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract manufacturer selection, with differentiation hinging on MFDS export eligibility and biotech active sourcing certificates. Premium tiers command positioning through integrated R&D campus access and digital product passport readiness, while economy tiers compete on minimum order flexibility alone. Cost compression in standard-tier skincare runs through energy-intensive cleanroom certification requirements. Direct-to-consumer labels in Berlin and Los Angeles show highest price sensitivity, whereas Sephora-bound prestige brands prioritize formulation exclusivity over unit economics.
Supply Chain Analysis
Regional distribution centers in Seoul Capital Area, Lyon, and Milan orchestrate hub-and-spoke fulfillment patterns for EU and North American brand clients. Specialty active ingredient production clusters in Basel and Lyon create single-source vulnerability for niacinamide and peptide formulations. Peptide suppliers and fermentation-based ceramide producers draw from concentrated biotech processing infrastructure. Tariff exposure on Chinese-sourced packaging components threatens margin stability for airless bottle programs. Distribution runs through MFDS-certified export channels with 18-24 month audit validation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as beauty brands shift procurement toward ODMs with documented biotech active certificates and EU Green Deal compliance pipelines.
For Market Incumbents: Deepen backward integration into fermentation-based ceramide production to offset petroleum-derived emollient cost volatility. Anchor capacity expansion in Songdo and Osong to compress client onboarding cycles for REACH-compliant export orders. Defend against micro-ODM specialists by embedding in-house TikTok content studios for direct-to-consumer brand partnerships. For New Entrants and Emerging Players: Enter via single-category specialization in sun care or lip tint formulations for Southeast Asian influencer-driven markets. Target São Paulo and Jakarta direct-to-consumer labels prioritizing 72-hour sample turnaround over volume thresholds. Deploy speed-to-sample positioning with sub-5,000-unit minimum orders and native video production capabilities. For Investors and Strategic Acquirers: Beauty platform operators are the most active acquirer in this space, consolidating micro-ODM specialists with TikTok-native content infrastructure. Long-term viability centers on facilities with early digital product passport compliance and biotech active sourcing relationships. Watch EU Green Deal microplastic enforcement timelines as the signal for reformulation capacity scarcity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Export Certification Investment | 18-24 month audit cycles gate EU brand partnerships for Korean campus operators. |
| Biotech Active Sourcing Integration | Fermentation-based ceramides displace petroleum emollients in clean beauty scorecards. |
| Digital Product Passport Readiness | EU battery-style traceability mandates reshape 2027 qualification criteria for brand contracts. |
| Direct-to-Consumer Content Studio Buildout | TikTok-native video production compresses launch timelines for Berlin and Los Angeles indie labels. |
| Microplastic-Free Formulation Pivot | Rice powder and mineral wax substitutes capture reformulation demand ahead of 2026 enforcement. |
Methodological Framework
Direct dialogue with ODM procurement directors, cosmetic chemists, beauty brand supply chain managers, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from MFDS facility certification databases, ECHA REACH pre-registration filings, EU Green Deal implementation trackers, and customs trade records for cosmetic ingredient flows. Bottom-up volume estimates from individual facility capacities triangulated against top-down market sizing from beauty brand procurement spend patterns.
Segmented outputs across the projection horizon reflect product type, packaging technology, distribution channel, and end-user archetype dimensions. CAGRs derived from facility capacity expansion announcements, brand partnership pipeline visibility, and regulatory compliance timeline modeling. Forecast inputs incorporated REACH disclosure mandate adoption curves and K-beauty export certification queue lengths.
The model holds under stable EU-Japan regulatory convergence assumptions; deviation in MFDS audit timeline acceleration or microplastic enforcement delays would shift capacity utilization projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Medicated Shampoo Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Nail Polish Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Beauty Facial Mask Market