
 Vietnam Skin Care Products Market | 2026-2036
Vietnam Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Skin Care Products Market Insights
Young professional demand is decoupling from traditional mass-market distribution as Vietnamese consumers prioritize ingredient transparency and K-beauty influenced routines. L'Oréal leverages its dermatological science positioning to anchor premium shelf space in urban specialty stores. Shiseido competes through localized R&D facilities that adapt Japanese fermentation technologies to tropical skin concerns. Unilever sustains volume leadership via multi-brand portfolios spanning affordable cleansers to mid-tier moisturizers across rural and urban channels.
Vietnam skin care products encompass topical formulations designed to cleanse, protect, and improve skin health through active ingredients such as niacinamide, hyaluronic acid, and botanical extracts manufactured under ASEAN Cosmetic Directive stability and safety protocols. Moisturizers and serums lead value contribution as consumers layer multi-step routines, while sunscreens represent the fastest-growing product type driven by UV awareness campaigns and year-round tropical exposure. Natural and herbal ingredient segments command premium positioning as local consumers associate plant-derived actives with gentler efficacy, though synthetic formulations still dominate mass-market cleansers through cost-optimized supply chains. Online retail channels are capturing share from supermarkets as TikTok Shop and Shopee Live enable direct brand-to-consumer education and sampling.
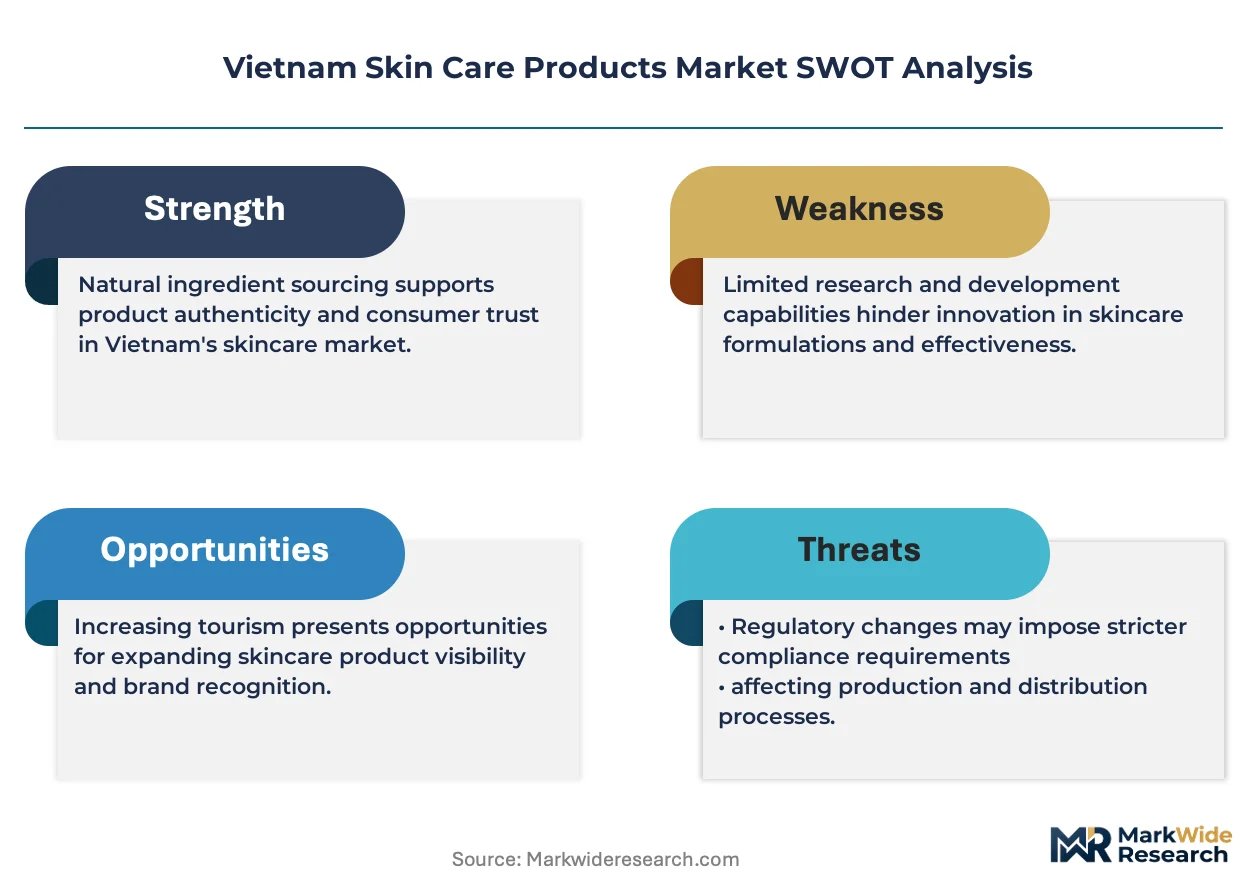
Vietnam's Ministry of Health enforces ASEAN Cosmetic Directive compliance for all imported and domestically manufactured skin care products, requiring ingredient disclosure and safety assessments that elevate formulation costs for new market entrants. The country's national standards body applies GB-aligned testing protocols for heavy metals and microbiological contaminants, creating a dual compliance burden for brands sourcing raw materials from China. Stakeholders must monitor evolving digital commerce tax regulations and cross-border import rules that could reshape pricing architecture and channel profitability in Southeast Asia's most dynamic beauty economy.
Market Dynamics
Vietnam's skin care market is restructuring around ASEAN Cosmetic Directive compliance costs and the migration of consumer education onto TikTok Shop and Shopee Live, where algorithmic personalization is compressing traditional brand-building timelines.
Growth Catalysts
- ASEAN Cosmetic Directive enforcement:Vietnam's Ministry of Health mandates ingredient disclosure and safety assessments that elevate quality standards and favor established formulators with testing infrastructure.
- Urban millennial routine complexity:Consumers in Ho Chi Minh City and Hanoi now layer six to ten product steps daily, expanding addressable SKU volume per household.
- Social commerce livestreaming:TikTok Shop and Shopee Live enable real-time dermatological education and sampling, collapsing the discovery-to-purchase funnel from weeks to minutes.
Market Restraints
- Dual compliance burden:Brands sourcing raw materials from China face GB-aligned heavy metals testing叠加 atop ASEAN protocols, inflating quality assurance costs.
- Import tariff volatility:Cross-border e-commerce tax regulations remain unsettled, threatening margin structures for direct-to-consumer brands.
- Natural ingredient supply concentration:Premium botanical extracts depend on Mekong Delta agricultural output vulnerable to climate disruption and pesticide residue variability.
Strategic Opportunities
- Central Highlands penetration:Da Nang and secondary cities lack premium specialty retail density, creating whitespace for localized pop-up and pharmacy partnerships.
- Male-specific formulation:Underpenetrated men's skin care segments offer expansion paths beyond the female-skewed current base.
- Fermentation technology convergence:Japanese-derived fermentation processes adapted to tropical humidity profiles enable differentiated positioning against standard emulsion technologies.
Industry Challenges
- Formulation chemist scarcity:Vietnam produces insufficient cosmetic science graduates to staff expanding R&D facilities and quality control laboratories.
- Stability testing bottlenecks:Accelerated tropical climate validation requires 12-18 month timelines that delay product launches versus temperate-market equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Skin Care Products Market |
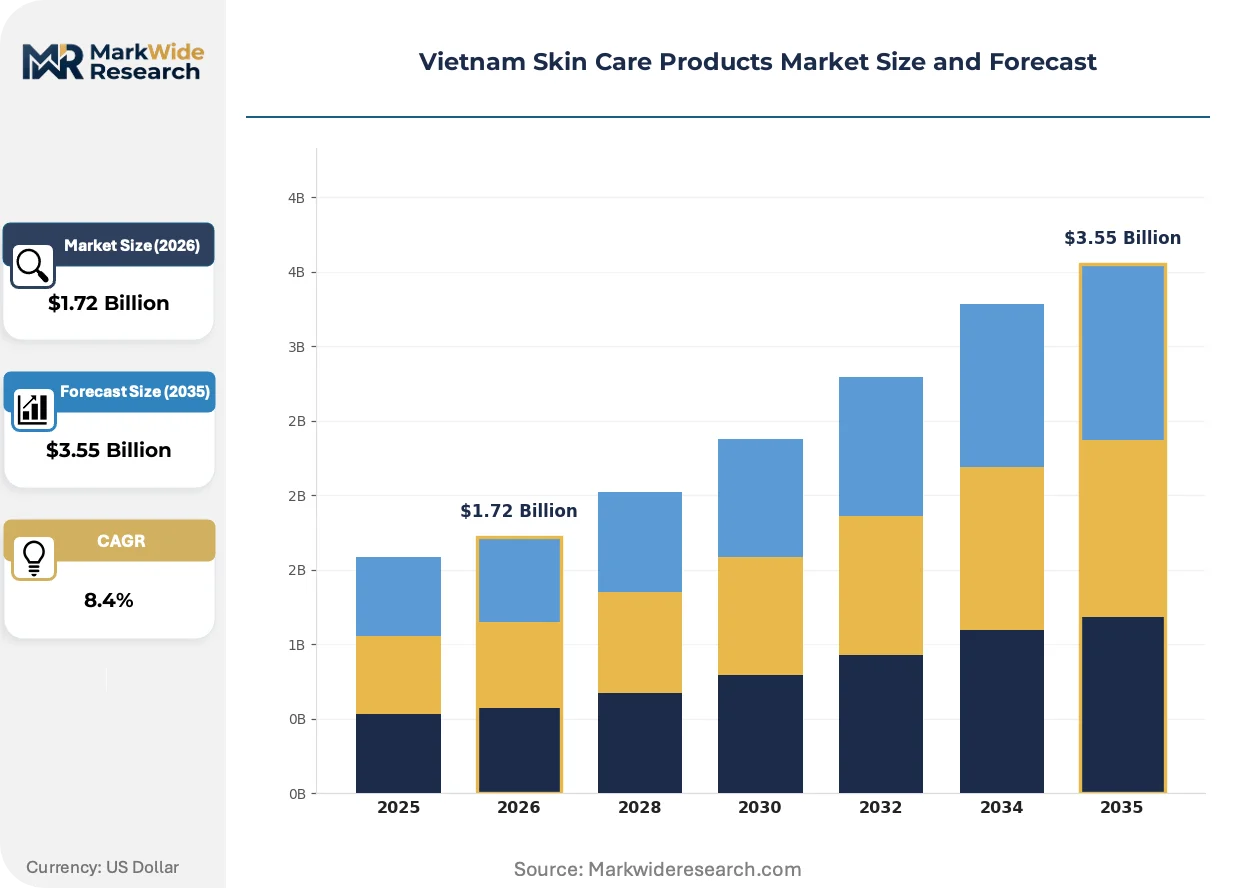
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Sunscreens Customer Type: Millennials, Gen Z, Professionals, Parents Ingredient Type: Natural, Synthetic, Organic, Herbal Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Salons |
| Companies Covered | Procter & Gamble, L'Oréal, Unilever, Shiseido, Estée Lauder Companies, AmorePacific, Beiersdorf, Johnson & Johnson, Kao Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Skin Care Products Market Trends and Innovations
Biotechnology-derived actives and algorithmic commerce are converging to reshape how Vietnamese consumers discover, validate, and purchase skin care formulations.
Biotech fermentation platforms are unifying traditional botanical extraction with precision-controlled microbial synthesis. Domestic manufacturers and joint-venture facilities are adopting these systems to produce standardized niacinamide and peptide complexes. This convergence is compressing batch-to-batch variability while enabling claims substantiation that satisfies both ASEAN Cosmetic Directive requirements and K-beauty-influenced consumer skepticism.
Vietnam's Ministry of Health is tightening digital commerce disclosure mandates for cross-border skin care imports. The regulatory friction is forcing direct-to-consumer brands to establish domestic legal entities and local testing partnerships. Premium segments are responding fastest, absorbing compliance costs into pricing architecture while mass-market cross-border sellers face margin compression.
Algorithmic personalization on TikTok Shop is displacing static shelf-based discovery for urban Vietnamese consumers. Shopee Live hosts now function as dermatological educators, demonstrating texture and absorption in real tropical conditions. This behavioral pivot concentrates demand spikes around livestreaming events, requiring brands to reconfigure inventory positioning and influencer contracting toward flash-sale economics rather than sustained retail presence.
Vietnam Skin Care Products Market Segmentation
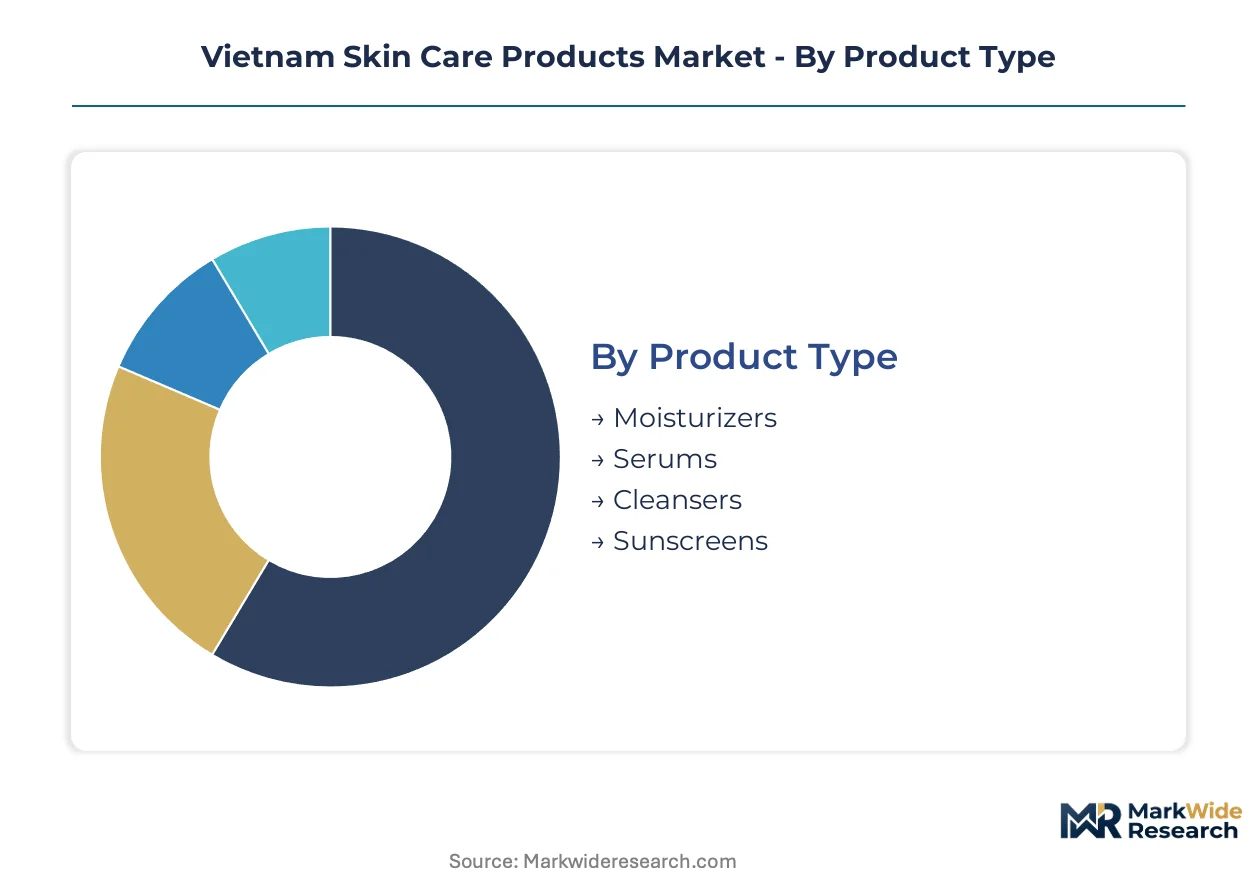
Vietnamese consumers are fragmenting skin care demand across multiple axes simultaneously, layering product sophistication, ingredient provenance, and channel convenience into purchase decisions that defy simple demographic targeting. The report maps four intersecting dimensions that collectively determine pricing architecture and go-to-market economics.
Product Type:
Replacement cycles accelerate where tropical humidity degrades formulation stability fastest, compressing repurchase windows for water-based products versus oil-based alternatives.
- Moisturizers:Emulsion and gel-cream formats dominate bathroom counters in Ho Chi Minh City and Hanoi, where air-conditioned indoor environments create artificial dehydration that drives daily reapplication. Demand concentrates among office workers seeking non-greasy textures compatible with makeup layering and tropical commutes.
- Sunscreens:PA++++ and broad-spectrum SPF formulations are displacing single-function day creams as Vietnamese consumers absorb Korean and Japanese UV education through TikTok dermatology creators. The segment gains share fastest where outdoor employment and motorcycle exposure create year-round photodamage anxiety.
- Serums:Concentrated active delivery systems—niacinamide, vitamin C, and peptide complexes—command premium shelf positioning in urban specialty retail.
- Cleansers:Oil-based and micellar formats compete with traditional foaming products across mass-market supermarket aisles and pharmacy chains.
Moisturizers sit at the top of the volume ranking, with sunscreens climbing the fastest.
Customer Type:
Margin structures diverge sharply between digitally native cohorts who discover products through algorithmic feeds and older segments still dependent on in-person pharmacy consultation.
- Millennials:Ho Chi Minh City-based professionals aged 28-38 drive premium serum and eye cream adoption, combining K-beauty influenced multi-step routines with disposable income expansion in fintech and corporate services sectors.
- Gen Z:TikTok-native consumers prioritize ingredient transparency and viral texture formats, collapsing traditional brand loyalty cycles through rapid experimentation enabled by Shopee sampling programs and livestream flash pricing.
- Professionals:Male and female white-collar workers in Hanoi finance and tech corridors seek dermatologist-endorsed solutions for stress-induced sensitivity and pollution defense.
- Parents:Family purchasing agents prioritize gentle, pediatrician-recommended formulations for household use, often defaulting to established pharmacy brands with generational trust equity.
Millennials anchor current revenue contribution, while Gen Z expands most quickly as a share of transaction volume.
Ingredient Type:
Supply chain provenance is becoming a primary filter as Vietnam's Ministry of Health tightens disclosure mandates and Mekong Delta agricultural output faces climate volatility.
- Natural:Plant-derived extracts from Vietnamese turmeric, lotus, and green tea command premium positioning in domestic and ASEAN export markets, though batch consistency challenges elevate quality assurance costs.
- Herbal:Traditional medicine-inspired formulations—licorice root, ginseng, and centella asiatica—resonate with consumers associating botanical heritage with gentler efficacy profiles.
- Synthetic:Cost-optimized niacinamide, hyaluronic acid, and peptide complexes dominate mass-market cleansers and basic moisturizers through standardized manufacturing scale.
- Organic:Certified organic segments remain niche, constrained by limited domestic certification infrastructure and import dependency for raw material verification.
Synthetic ingredients retain volume leadership, with herbal segments gaining share fastest through localization of East Asian fermentation technologies.
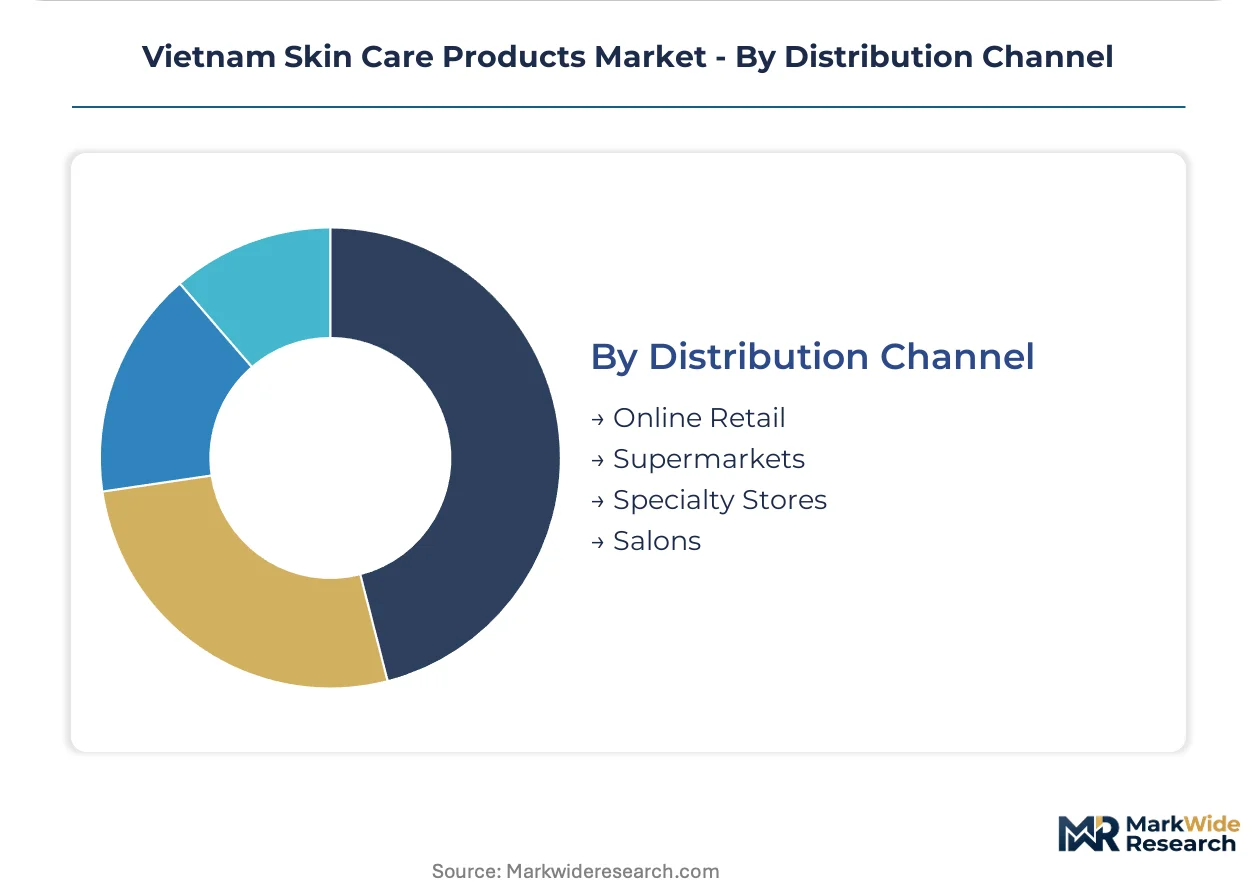
Distribution Channel:
Inventory positioning is restructuring around algorithmic demand spikes rather than sustained retail presence, compressing working capital requirements for agile direct-to-consumer operators.
- Online Retail:TikTok Shop and Shopee Live have collapsed the discovery-to-purchase funnel from weeks to minutes, concentrating demand around influencer-led livestreaming events that require flash-sale logistics infrastructure.
- Specialty Stores:Watsons, Guardian, and domestic pharmacy chains in Ho Chi Minh City and Hanoi maintain premium brand anchoring through dermatologist consultation counters and sampling programs.
- Supermarkets:Co.opmart and VinMart locations sustain mass-market cleanser and moisturizer volume through promotional stacking and family-pack economics.
- Salons:Professional facial clinics and spa channels distribute medical-grade and treatment-adjacent products with higher service-embedded margins.
Online retail sits at the top of the volume ranking, with specialty stores climbing the fastest as premium brands invest in localized pop-up and consultation formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as ASEAN Cosmetic Directive compliance costs diverge across Southeast Asian manufacturing bases, drawing formulation and packaging investment toward jurisdictions with established testing infrastructure and bilateral mutual recognition agreements.
Ho Chi Minh City
Urban millennials in District 1 and District 7 drive premium serum and sunscreen adoption through TikTok-influenced multi-step routines. Vietnam's Ministry of Health maintains ASEAN Cosmetic Directive enforcement offices in the city, streamlining product registration for domestic manufacturers. The Thu Duc City corridor hosts concentrated contract manufacturing facilities serving both local brands and regional export markets.
Hanoi
Finance and tech professionals in Cau Giay and Tay Ho districts prioritize dermatologist-endorsed pollution-defense formulations. The national standards body applies GB-aligned heavy metals testing protocols alongside ASEAN requirements, elevating quality assurance costs for brands sourcing raw materials from China. Long Bien district clusters domestic R&D facilities adapting Japanese fermentation technologies to tropical humidity profiles.
Da Nang
Secondary-city consumers exhibit rising premium brand awareness without matching specialty retail density. Central region tax incentives for cosmetic manufacturing investment remain underdeveloped compared to northern and southern industrial zones. The Hoa Khanh Industrial Zone attracts packaging material suppliers serving brands testing Central Highlands market penetration.
Can Tho
Mekong Delta agricultural output supplies turmeric, lotus, and green tea extracts for natural ingredient segments. Climate disruption and pesticide residue variability threaten batch consistency for premium botanical formulations. The city anchors regional distribution networks reaching secondary provinces where pharmacy chains sustain mass-market cleanser volume.
Hai Phong
Northern port infrastructure supports import-dependent raw material flows for synthetic active manufacturers. Cross-border e-commerce tax regulation uncertainty complicates direct-to-consumer fulfillment models through the city's logistics corridors. Cat Hai district industrial zones host filling and packaging operations for brands avoiding Ho Chi Minh City congestion costs.
Vietnam Skin Care Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational portfolio companies commanding premium shelf space in urban specialty retail while domestic formulators capture volume through pharmacy and supermarket channels. The market exhibits tiered concentration: three to four global beauty conglomerates anchor dermatological science positioning, mid-tier Asian specialists compete on localized fermentation adaptations, and fragmented local assemblers serve price-sensitive rural demand. Strategic archetypes include science-forward dermatological brands, K-beauty-influenced fermentation specialists, and multi-brand mass-market portfolio operators. Dominant competitive moves center on localized R&D facility establishment and social commerce influencer network construction.
Among global beauty conglomerates, L'Oréal and Unilever occupy positions exemplifying divergent strategic archetypes: the former anchoring premium dermatological science positioning through urban specialty store penetration, the latter sustaining volume leadership across rural and urban channels via multi-brand portfolio economics. Shiseido represents the fermentation-technology convergence archetype, with its localized R&D adaptation of Japanese processes to tropical skin concerns. These three companies collectively illustrate how regulatory compliance infrastructure, social commerce integration capability, and tropical formulation expertise determine competitive positioning in Vietnam's restructuring distribution landscape.
| Leading Market Players |
|---|
| Procter & Gamble |
| L'Oréal |
| Unilever |
| Shiseido |
| Estée Lauder Companies |
| AmorePacific |
| Beiersdorf |
| Johnson & Johnson |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
Cosmetic formulation chemist concentration in Ho Chi Minh City and Hanoi widens pricing-tier spreads, as labor-cost differentials between these urban R&D hubs and secondary cities force brands to absorb premium talent premiums or offshore quality control functions.
Pricing Analysis
Distributor margins on cross-border e-commerce imports face compression as Vietnam's Ministry of Health mandates domestic legal entity establishment and local testing partnerships. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-endorsed specialty serums from pharmacy-chain moisturizers and supermarket cleansers. Price differentiation hinges on ASEAN Cosmetic Directive compliance certification and volume scale, with mass-market synthetic formulations absorbing cost compression while premium botanical segments pass through quality assurance premiums. Gen Z consumers exhibit highest price sensitivity through TikTok Shop flash-sale dependency, whereas millennial professionals in corporate services show lowest sensitivity for fermentation-technology positioning.
Supply Chain Analysis
ASEAN Cosmetic Directive ingredient disclosure mandates are reshaping sourcing toward domestic testing partnerships and local legal entity establishment. Raw material flows draw from China for synthetic actives, South Korea for fermentation-derived inputs, and the Mekong Delta for turmeric and lotus botanical extracts. Single-source vulnerability concentrates in climate-dependent agricultural output from Can Tho province, where pesticide residue variability threatens batch consistency. Distribution runs through TikTok Shop and Shopee Live algorithmic channels for urban millennials, pharmacy chain consolidation for family purchasers, and supermarket promotional stacking for rural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam skin care represents a late-cycle quality story as urban millennials pivot from basic cleansing toward six-to-ten-step premium routines with dermatological validation requirements.
For Market Incumbents: Cement ASEAN Cosmetic Directive compliance infrastructure as a competitive moat against cross-border direct-to-consumer entrants facing domestic entity establishment costs. Lock in Mekong Delta agricultural partnerships through forward-contracting to secure turmeric and green tea extract supply against climate disruption. Prioritize fermentation technology R&D in Long Bien district facilities to differentiate from standard emulsion competitors.
For New Entrants and Emerging Players: TikTok Shop algorithmic personalization offers the most penetrable route for brands lacking legacy retail shelf presence. Target male-specific formulation whitespace in Hanoi finance and tech corridors where dermatologist endorsement gaps persist. Anchor go-to-market through Shopee Live dermatological education events demonstrating tropical humidity absorption profiles.
For Investors and Strategic Acquirers: Asian fermentation-technology specialists are the most active acquirer in this space, seeking Vietnamese facilities to adapt Japanese processes to tropical skin concerns. Five-to-ten-year viability hinges on social commerce integration capability and localized R&D infrastructure ownership. Watch for inflection in cross-border e-commerce tax regulation finalization that would compress pure-import model margins and accelerate domestic entity M&A.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized R&D Facility Establishment | Japanese fermentation adaptation to tropical humidity enables differentiated serum positioning against standard emulsion competitors. |
| Social Commerce Influencer Network Construction | TikTok Shop and Shopee Live education events collapse discovery-to-purchase funnels for algorithmic-native Gen Z cohorts. |
| Mekong Delta Agricultural Partnership Lock-in | Forward-contracting turmeric and lotus supply secures natural ingredient batch consistency against climate volatility. |
| Domestic Legal Entity Establishment | ASEAN Cosmetic Directive compliance through Vietnam Ministry of Health registration insulates against cross-border tax uncertainty. |
| Premium Male-Specific Formulation Launch | Underpenetrated men's segments in Hanoi tech corridors offer expansion beyond current female-skewed customer base. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic brand managers, pharmacy chain category buyers, contract manufacturing facility directors, and Ministry of Health regulatory affairs specialists with secondary validation against ASEAN Cosmetic Directive filing databases, customs import records, and Shopee Live transaction analytics. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption indicators.
Segment-weighting approaches distributed volume and value across product type, ingredient provenance, customer cohort, and distribution channel dimensions throughout the forecast period. CAGRs derived from trend extrapolation of urban millennial routine complexity expansion and Gen Z social commerce adoption curves, incorporating tropical climate stability testing timeline constraints and fermentation technology penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for biotech-derived fermentation platforms would alter the outlook if batch-to-batch variability compression accelerates faster than projected. Forecasts reflect assumptions around regulatory enforcement consistency and Mekong Delta agricultural output stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Makeup Remover Pen Market
Cosmetics & Skincare
Silicone Makeup Sponge Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Body Cream Jars Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Pillow Spray Market