
 North America Moringa Products Market | 2026-2036
North America Moringa Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Moringa Products Market Outlook
Subscription-based replenishment programs for moringa powder and capsules is decoupling unit sales from traditional retail velocity in North America. Kuli Foods leverages its direct-to-consumer platform to control customer lifetime value through recurring revenue models. Moringa Source anchors its competitive position with vertically integrated cultivation partnerships in Central America that supply its U.S. processing facilities. True Moringa differentiates through social-impact branding tied to African sourcing networks, which resonates with ethically motivated purchasers in premium channels.
Moringa products encompass dried leaf powder, cold-pressed seed oil, encapsulated extracts, and infusion-grade teas derived from Moringa oleifera, a drought-resistant tree containing quercetin, chlorogenic acid, and all nine essential amino acids. Powder formulations dominate volume due to lower processing thresholds and broader incorporation into smoothies, baked goods, and protein blends. Nutritional Supplements captures the largest margin pool as consumers pay premiums for standardized polyphenol content and organic certification, while Cosmetics applications are expanding fastest among indie beauty brands seeking plant-derived alternatives to synthetic emollients.
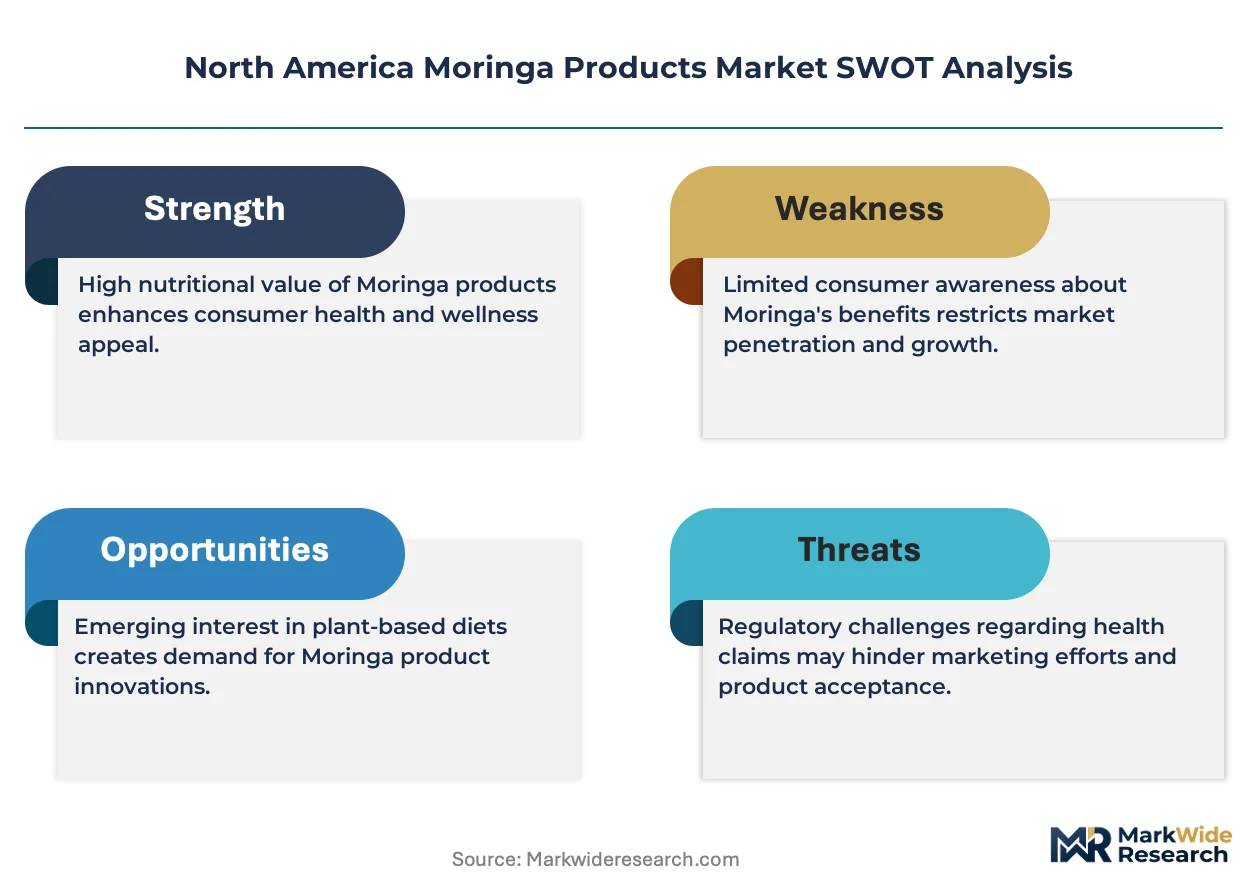
The FDA's Current Good Manufacturing Practice regulations and the USDA National Organic Program standards govern product claims, contaminant thresholds, and label integrity across U.S. moringa commerce. Health Canada and the Natural and Non-prescription Health Products Directorate enforce comparable purity and safety requirements for Canadian market access. Stakeholders must monitor evolving enforcement priorities around adaptogenic and anti-inflammatory claims, as regulatory scrutiny of functional food messaging intensifies without harmonized federal guidance.
Market Dynamics
Subscription-based replenishment programs are decoupling unit sales from traditional retail velocity across the United States and Canada, forcing manufacturers to build direct-to-consumer infrastructure and recurring revenue capabilities that reshape capital allocation and customer acquisition economics.
Growth Catalysts
- Functional beverage fortification:Plant-based protein demand from U.S. and Canadian manufacturers is expanding moringa procurement for smoothie and ready-to-drink formulations. This pull concentrates in California's natural products corridor near Los Angeles and San Francisco.
- FDA New Dietary Ingredient pathway:The notification framework for novel moringa extracts is creating compliant entry routes for standardized polyphenol supplements. Supplement brands leverage this to differentiate through verified bioactive content claims.
- Social-impact sourcing narratives:Ethically motivated purchasers in premium channels respond to African supply network transparency. This demand pattern supports price premiums for certified fair-trade and organic leaf powder.
Market Restraints
- Central American supply concentration:Vertically integrated cultivation partnerships in Guatemala and Nicaragua create geographic risk exposure for U.S. processing facilities. Climate volatility in these regions threatens raw material continuity.
- Adaptogenic claim scrutiny:The FDA and FTC enforcement priorities around anti-inflammatory and adaptogenic messaging intensify without harmonized federal guidance. Brands face label revision costs and warning letter risk.
- Synthetic emollient substitution:Petrochemical-derived cosmetic ingredients maintain cost advantages over cold-pressed moringa seed oil in mass-market beauty formulations. Indie brands absorb the premium; mainstream adoption lags.
Strategic Opportunities
- Canadian natural health product expansion:Health Canada's Natural and Non-prescription Health Products Directorate offers a distinct regulatory pathway with less crowded competitive positioning than the U.S. supplement market. Early entrants capture shelf space in Toronto and Vancouver wellness retail.
- Encapsulated extract standardization:Technology convergence between supercritical CO2 extraction and HPLC fingerprinting enables verified polyphenol dosing. This supports medical-grade positioning in clinical nutrition channels.
- Direct-to-consumer platform consolidation:Recurring revenue models for powder and capsules reduce customer acquisition cost dependence on Amazon and Whole Foods. Brands with proprietary subscription infrastructure control lifetime value data.
Industry Challenges
- USDA National Organic Program certification timelines:Three-year transition requirements for conventional farmland conversion create working capital strain for new cultivation partners. Supply contracts face execution risk during the gap period.
- Quercetin and chlorogenic acid assay standardization:Analytical method variability across third-party laboratories generates batch-to-batch claim inconsistency. Manufacturers must build in-house HPLC capability or accept margin erosion from specification disputes.
- Legacy retail slotting fee structures:Traditional natural products distributors demand upfront payments that conflict with direct-to-consumer cash flow profiles. Hybrid brands face channel conflict resolution costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Moringa Products Market |
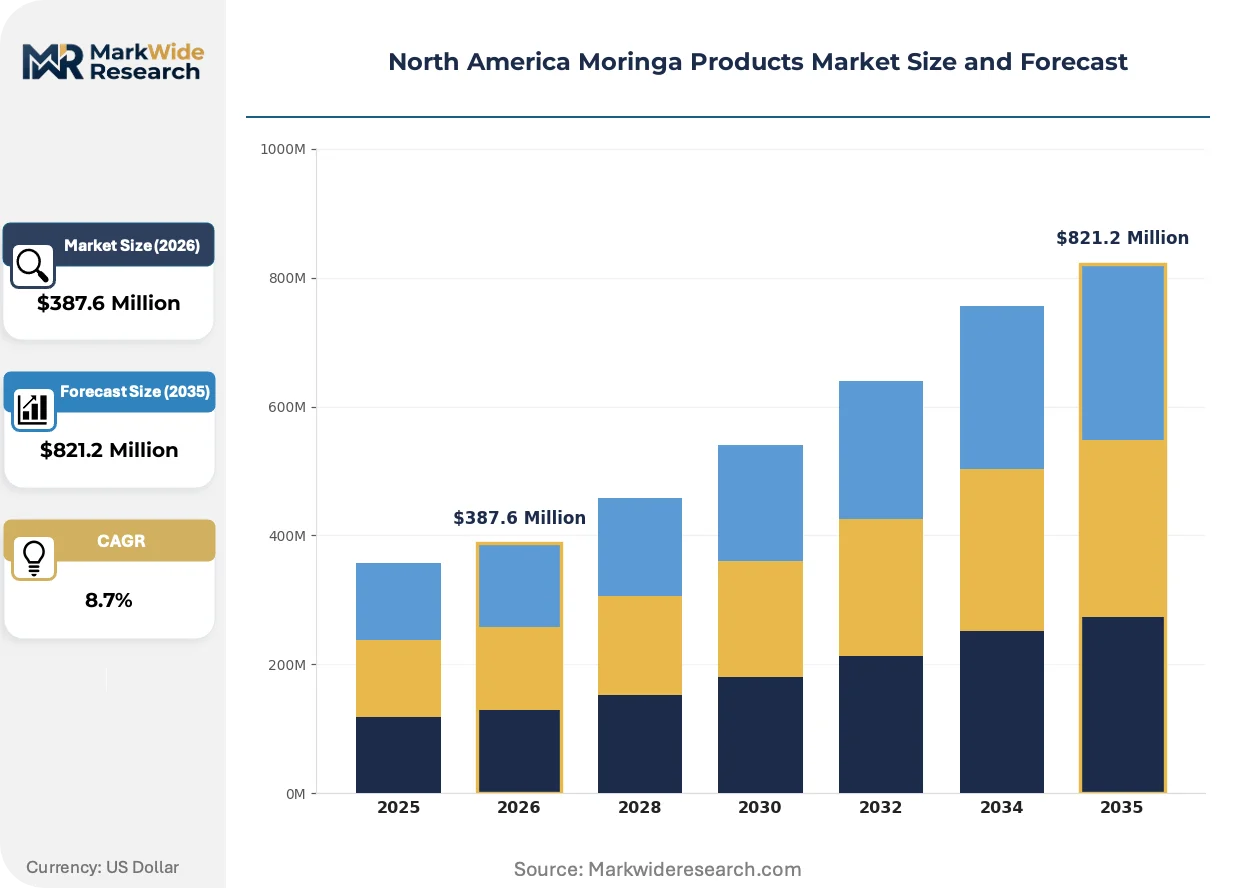
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil, Capsules, Tea Application: Nutritional Supplements, Cosmetics, Food and Beverages, Pharmaceuticals Distribution Channel: Online Stores, Specialty Shops, Supermarkets, Health Food Stores End User: Individuals, Fitness Enthusiasts, Healthcare Professionals, Retailers |
| Companies Covered | Kuli Foods, Moringa Source, Moringa Farms, Moringa Life, MoringaConnect, GreenVirgin Products, True Moringa, The Moringa Company, KiliFi Moringa, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Moringa Products Market Strategic Shifts
Technology, regulatory enforcement, and procurement model evolution are simultaneously compressing traditional supply chains and opening premium positioning pathways for moringa-derived ingredients across North American nutrition and cosmetics applications.
Supercritical CO2 extraction for moringa leaf bioactives is converging with HPLC-based polyphenol standardization to enable medical-grade supplement positioning. Functional beverage manufacturers in California and Colorado are adopting these verified extracts at accelerating pace. This convergence compresses the gap between commodity leaf powder and pharmaceutical-adjacent ingredient pricing tiers.
The FDA's intensified scrutiny of adaptogenic and anti-inflammatory claims under its Current Good Manufacturing Practice enforcement is forcing label revision cycles across U.S. supplement brands. Health Canada's comparable vigilance through the Natural and Non-prescription Health Products Directorate creates parallel compliance burdens for cross-border sellers. Nutritional Supplements segment participants are responding by shifting marketing emphasis toward USDA Organic certification and amino acid completeness rather than unverified therapeutic claims.
Buyer concentration among direct-to-consumer wellness platforms is displacing traditional natural products distributor relationships for powder and capsule formats. Indie beauty brands in Los Angeles and Brooklyn are bypassing legacy cosmetic ingredient suppliers to source cold-pressed seed oil through vertically integrated processors. This channel disintermediation is most visible in California's natural products corridor, where brand founders prioritize supply chain transparency over established vendor reliability scores.
North America Moringa Products Market Segmentation
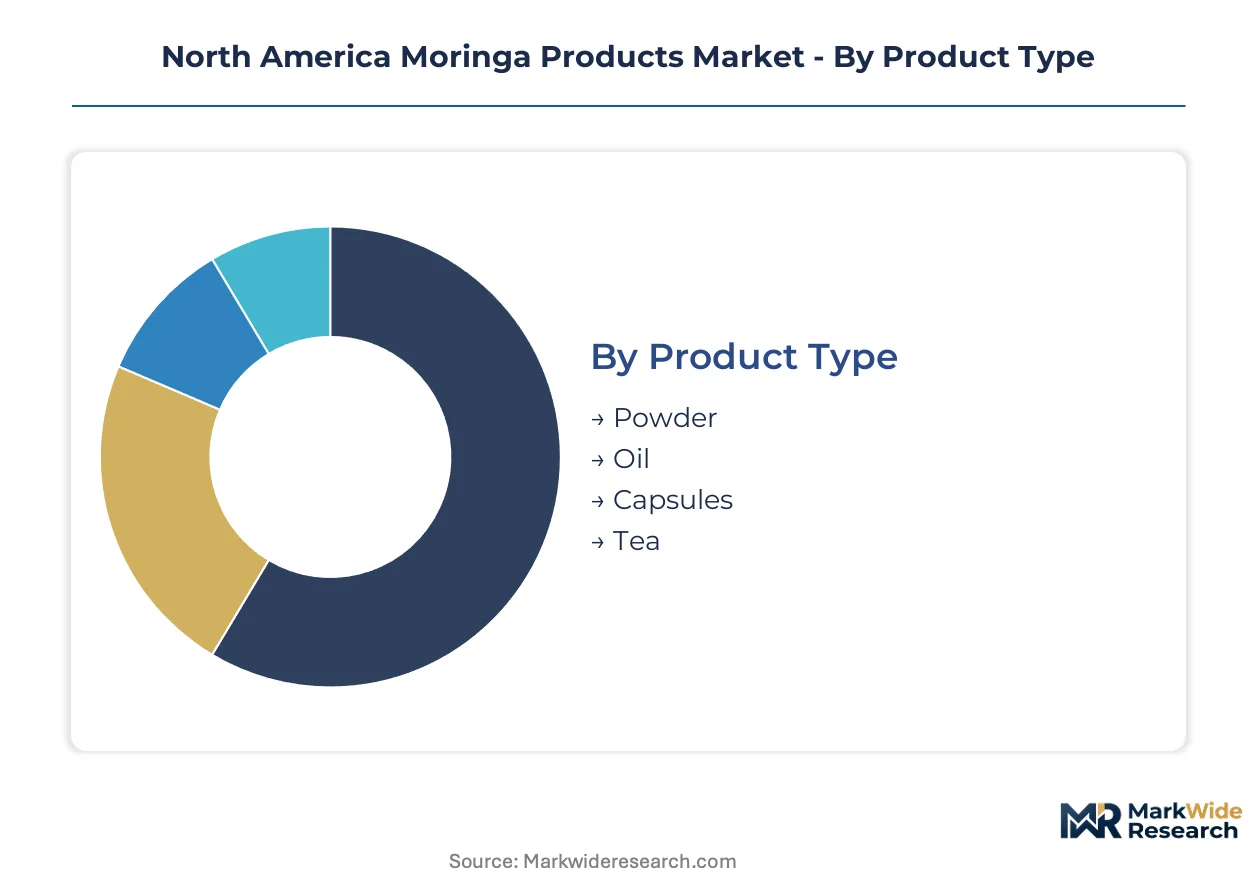
Segmentation in North American moringa commerce reveals how regulatory thresholds, extraction complexity, and channel economics partition value capture across distinct product tiers. Each dimension carries specific compliance burdens that reshape competitive positioning and margin distribution.
Product Type:
USDA National Organic Program certification and FDA New Dietary Ingredient notifications apply differentially across these formats, with processed derivatives facing steeper analytical and documentation requirements than raw agricultural commodities.
- Powder:Dried leaf powder requires minimal processing beyond dehydration and milling, keeping unit economics accessible for mass-market penetration. Demand clusters in California's natural products corridor where smoothie and protein blend manufacturers prioritize cost-efficient fortification. The format dominates volume throughput across U.S. and Canadian direct-to-consumer platforms.
- Oil:Cold-pressed seed oil extraction demands specialized mechanical or supercritical CO2 infrastructure, elevating capital intensity and quality verification costs. Indie beauty brands in Los Angeles and Brooklyn source directly from vertically integrated processors, bypassing legacy cosmetic ingredient distributors to secure supply chain transparency.
- Capsules:Encapsulation triggers FDA Current Good Manufacturing Practice compliance for supplement positioning, including batch-level polyphenol standardization.
- Tea:Infusion-grade leaf products fall under lighter agricultural commodity regulation, though organic certification remains prevalent for premium positioning.
Leading the category by volume: Powder. Growing fastest: Oil.
Application:
Margin structures diverge sharply across these end-use contexts, with pharmaceutical-adjacent positioning commanding premium pricing tiers unavailable to commodity food ingredients.
- Nutritional Supplements:Standardized polyphenol content and verified bioactive assays support medical-grade positioning in clinical nutrition channels. Health Canada's Natural and Non-prescription Health Products Directorate creates a distinct regulatory pathway with less crowded competitive positioning than the U.S. supplement market.
- Cosmetics:Plant-derived emollient demand from indie beauty brands accelerates fastest as synthetic substitution pressures intensify. Cold-pressed moringa seed oil captures premium placement in clean beauty formulations across Toronto and Vancouver wellness retail.
- Food and Beverages:Functional beverage manufacturers in California and Colorado integrate verified extracts at accelerating pace, compressing the gap between commodity and pharmaceutical-adjacent pricing tiers.
- Pharmaceuticals:HPLC fingerprinting requirements and supercritical extraction convergence enable the steepest expansion trajectory for verified bioactive applications.
Widest margin capture: Nutritional Supplements. Expanding most quickly: Cosmetics.
Distribution Channel:
Customer acquisition economics and recurring revenue capabilities vary dramatically by channel, with proprietary platform control reducing dependence on third-party marketplace fees.
- Online Stores:Direct-to-consumer subscription infrastructure enables customer lifetime value optimization through replenishment program data capture. Kuli Foods and comparable platforms decouple unit sales from traditional retail velocity across the United States and Canada.
- Specialty Shops:Curated wellness retail in San Francisco and Toronto supports premium pricing for certified fair-trade and organic leaf powder with transparent sourcing narratives.
- Supermarkets:Mass-market penetration demands price competitiveness that conflicts with organic certification cost structures.
- Health Food Stores:Legacy natural products distributors impose slotting fee structures that conflict with direct-to-consumer cash flow profiles.
Highest growth trajectory: Online Stores. Most concentrated margin pool: Specialty Shops.
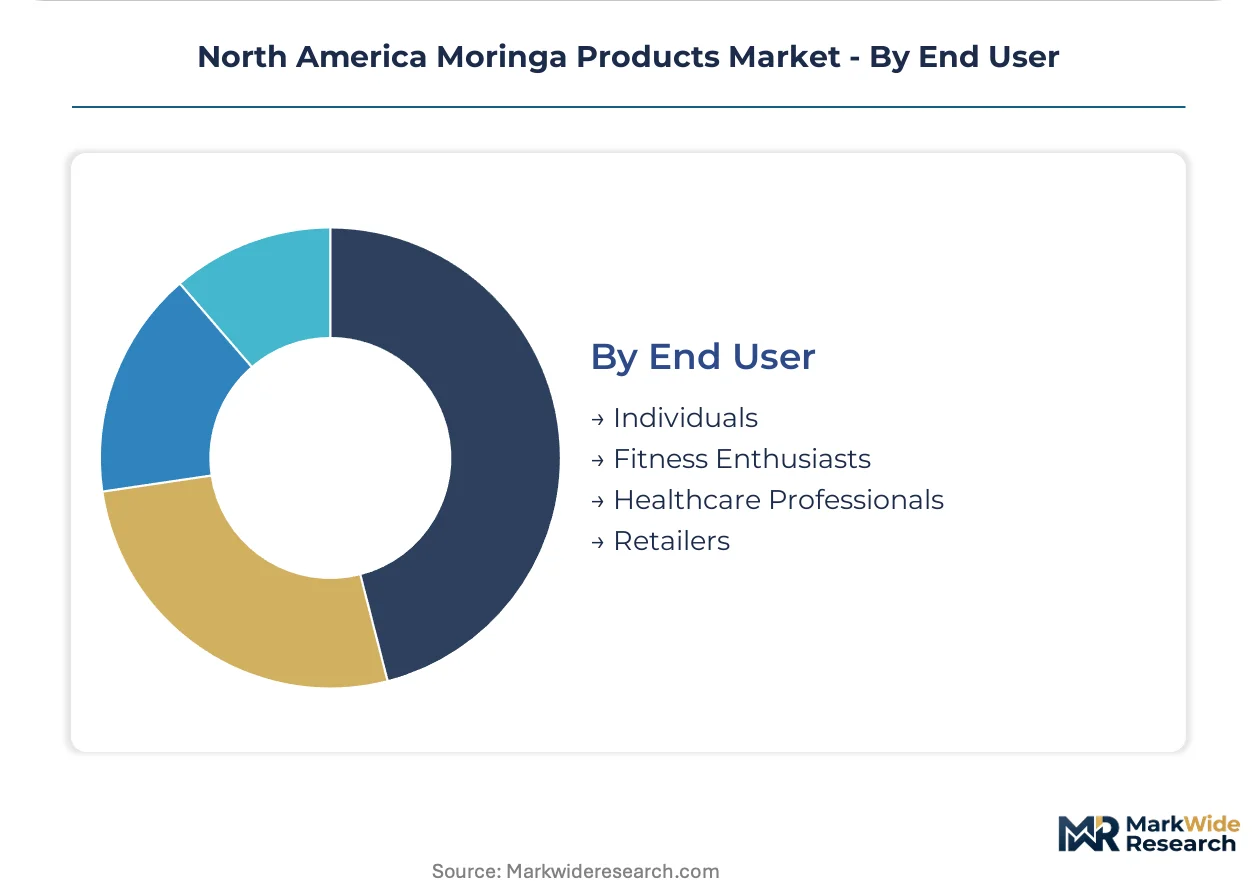
End User:
Procurement authority and volume scale separate institutional purchasers from individual consumers, with professional intermediaries driving standardization requirements.
- Individuals:Ethically motivated purchasers in premium channels respond to African supply network transparency, supporting price premiums for certified fair-trade positioning.
- Fitness Enthusiasts:Plant-based protein demand concentrates in California's natural products corridor near Los Angeles, where smoothie culture drives powder incorporation.
- Healthcare Professionals:Clinical nutrition channels require medical-grade supplement positioning with verified polyphenol dosing and HPLC standardization.
- Retailers:Inventory risk and working capital constraints shape procurement relationships with vertically integrated cultivation partnerships.
Volume concentration: Individuals. Fastest-expanding demand: Healthcare Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Central American cultivation partnerships while consumption clusters in U.S. and Canadian urban wellness corridors. This geographic separation creates supply chain complexity for North American processors.
United States
California's natural products corridor near Los Angeles and San Francisco drives powder demand from functional beverage manufacturers seeking plant-based protein fortification. The FDA's Current Good Manufacturing Practice regulations govern supplement claims and batch-level polyphenol standardization for encapsulated extracts. Brooklyn and Colorado indie beauty brands source cold-pressed seed oil directly from vertically integrated processors, bypassing legacy cosmetic ingredient distributors.
Canada
Toronto and Vancouver wellness retail channels support premium pricing for certified organic leaf powder with transparent African sourcing narratives. Health Canada's Natural and Non-prescription Health Products Directorate enforces purity requirements that create a less crowded competitive pathway than the U.S. supplement market. Prairie Provinces cultivation trials explore domestic moringa production to reduce import dependence from Central American supply networks.
Mexico
Bajío Region agricultural cooperatives supply raw leaf material to U.S. processing facilities under vertically integrated contracts. Mexico's national health regulator, COFEPRIS, oversees import documentation for moringa-derived supplements entering through California border logistics hubs. Yucatán Peninsula climate conditions support year-round cultivation that buffers seasonal supply volatility from Guatemalan sources.
North America Moringa Products Market Competitive Environment
Top-tier vendors anchor direct-to-consumer subscription infrastructure, while mid-tier processors compete on organic certification and sourcing transparency. The vendor base stratifies across three functional tiers: vertically integrated cultivators with Central American farm partnerships, pure-play wellness brands with proprietary e-commerce platforms, and private-label manufacturers serving mass-market retail. Dominant competitive moves include backward integration into cultivation assets and geographic expansion into Canadian natural health product channels.
Within the social-impact sourcing tier, True Moringa exemplifies African supply network transparency, while Kuli Foods occupies a position defined by recurring revenue platform control. Moringa Source anchors the vertically integrated archetype through captive Central American cultivation partnerships. These three entities collectively represent the strategic segmentation between ethical branding, digital-native distribution, and upstream supply security.
| Leading Market Players |
|---|
| Kuli Foods |
| Moringa Source |
| Moringa Farms |
| Moringa Life |
| MoringaConnect |
| GreenVirgin Products |
| True Moringa |
| The Moringa Company |
| KiliFi Moringa |
| Others |
Value Chain & Pricing Dynamics
Specialized supercritical CO2 extraction technicians in California's natural products corridor command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy levels. Labor-cost differentials between Los Angeles processing facilities and Guatemalan cultivation sites widen spreads between medical-grade encapsulated extracts and commodity leaf powder.
Pricing Analysis
Cost-down pressure on standard-grade leaf powder accelerates because Central American cultivation expansion outpaces North American dehydration capacity. Subscription-based replenishment programs dominate the pricing model, with price differentiation resting on USDA Organic certification tier and verified polyphenol assay precision. Margin tightening in mass-market powder reflects Amazon marketplace fee compression, while healthcare professionals demonstrate least price sensitivity for HPLC-standardized capsules.
Supply Chain Analysis
Moringa oleifera leaf supply rests on vertically integrated cultivation partnerships in Guatemala, Nicaragua, and Mexico's Bajío Region. Raw material dependencies include drought-resistant sapling stock, organic-compliant fertilizers, and cold-press mechanical infrastructure for seed oil extraction. Single-source vulnerability concentrates in Guatemalan highland farms exposed to climate volatility. Distribution runs through direct-to-consumer platforms and California natural products corridor processors before reaching Toronto and Vancouver wellness retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification backlog at USDA-accredited bodies constrains new supplier entry, propping pricing power for incumbent certified processors. This supply-constrained structure favors asset control over pure brand plays.
For Market Incumbents: Acquire dormant Central American farmland with completed three-year organic transition to preempt competitor cultivation expansion. Secure captive dehydration capacity in California's natural products corridor to defend against emerging vertically integrated entrants from Colorado functional beverage clusters. For New Entrants and Emerging Players: Supercritical CO2 extraction convergence with HPLC fingerprinting offers defensible positioning in clinical nutrition channels underserved by commodity powder suppliers. Target Health Canada's Natural and Non-prescription Health Products Directorate pathway for less crowded competitive positioning than FDA-regulated U.S. supplement markets. Lead with medical-grade polyphenol standardization narratives to bypass legacy retail slotting fee barriers. For Investors and Strategic Acquirers: Re-rating potential sits with processors holding captive Central American cultivation and proprietary subscription infrastructure given direct-to-consumer platform consolidation acceleration. Long-term viability favors asset-heavy archetypes over pure-brand wellness plays. Watch Health Canada enforcement intensity around adaptogenic claims as inflection indicator for cross-border regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Captive Guatemalan and Nicaraguan farmland secures organic-certified supply continuity for U.S. processing facilities. |
| Direct-to-Consumer Platform Launch | Proprietary subscription infrastructure reduces Amazon fee dependence and captures customer lifetime value data. |
| Health Canada Regulatory Pathway Entry | Natural and Non-prescription Health Products Directorate approval unlocks less crowded Toronto and Vancouver retail positioning. |
| Supercritical CO2 Extraction Scale-Up | Medical-grade polyphenol standardization enables pharmaceutical-adjacent pricing tiers in clinical nutrition channels. |
| Organic Certification Pipeline Investment | Pre-transitioned farmland acquisition compresses three-year USDA National Organic Program waiting periods for new supply contracts. |
Study Parameters
Independent corroboration across FDA Current Good Manufacturing Practice inspection records, Health Canada Natural and Non-prescription Health Products Directorate submissions, and USDA National Organic Program certification databases underwrites the qualitative findings. Primary interviews with functional beverage formulation scientists, natural products procurement directors, supercritical extraction equipment specialists, and direct-to-consumer brand operators combined with secondary validation from customs import records, California agricultural cooperative disclosures, and Toronto wellness retail audit data. Bottom-up cultivation capacity estimates and top-down consumption velocity patterns were reconciled through iterative triangulation.
Rate-of-change decomposition across product type, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value build-ups incorporating functional beverage manufacturer procurement surveys, indie beauty brand sourcing patterns, and subscription platform replenishment velocity data. HPLC assay standardization adoption curves and Health Canada approval pipeline flow-through informed industry-specific trajectory adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA adaptogenic claim enforcement escalation and Central American climate disruption scenarios. Forecasts reflect documented assumptions around organic certification conversion timelines and direct-to-consumer platform consolidation velocity. A small set of named triggers warrants ongoing watch: Health Canada vigilance intensity, Guatemalan drought frequency indices, and supercritical CO2 equipment lead time fluctuations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Nuts and Nutmeals Market