
 Processed Walnuts Market | 2026-2036
Processed Walnuts Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Walnuts Market Analytics
California's Central Valley nut processors is recalibrating output schedules after consecutive drought cycles constrained irrigation access. Diamond Foods, LLC leverages integrated orchards and shelling facilities to secure supply continuity across volatile growing seasons. Olam International anchors procurement networks across multiple hemispheres to buffer against regional crop shortfalls. Mariani Nut Company specializes in value-added roasting and flavoring lines that command premium shelf positioning in North American retail channels.
Processed walnuts comprise shelled and mechanically treated Juglans regia kernels, typically dried to moisture levels below 8 percent to prevent rancidity and extend shelf stability, serving as ingredient inputs across food manufacturing and direct-to-consumer packaged goods. Walnut oil extraction represents a concentrated margin pool where cold-pressed grades attract cosmetic and nutraceutical buyers alongside culinary applications. Chopped walnuts and walnut powder categories are gaining traction in baking and health food segments as formulators seek clean-label protein and omega-3 fortification without whole-nut texture constraints. Foodservice distribution channels face margin compression from labor-intensive portion control requirements, while online retail direct-to-consumer formats allow specialty roasters to bypass conventional wholesale markups.
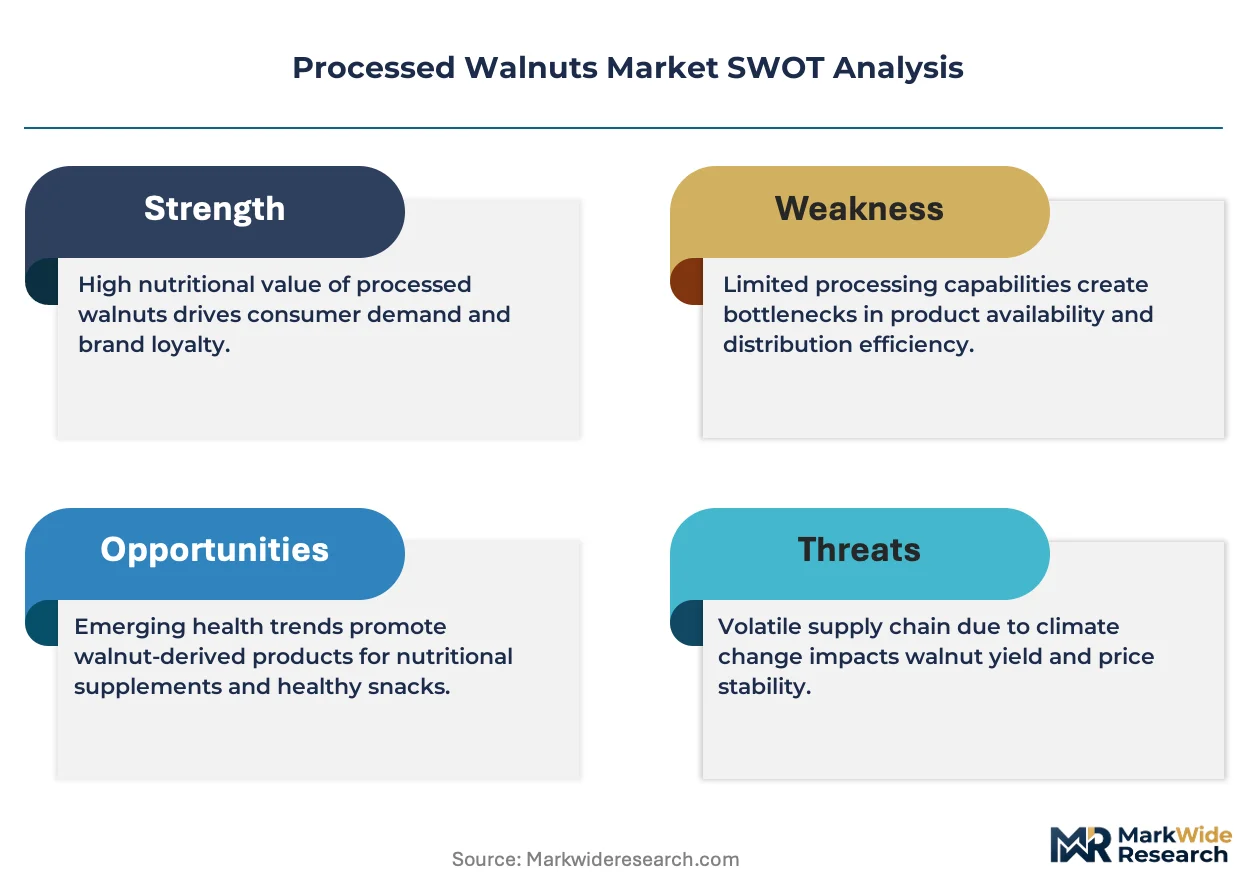
FDA food safety modernization rules and USDA organic certification standards shape processor investment in HACCP-compliant sorting and pasteurization infrastructure for walnut handling facilities. California's State Water Resources Control Board enforces groundwater pumping restrictions that directly constrain orchard expansion and shelling plant throughput capacity in the dominant production region. Stakeholders must monitor water rights adjudication outcomes and climate-adaptive cultivar development programs to assess long-term supply reliability and processing location economics.
Market Dynamics
California's Sustainable Groundwater Management Act is compressing orchard irrigation allocations, forcing processors to relocate shelling capacity or invest in water-efficient cultivar development to maintain throughput.
Growth Catalysts
- Functional food formulation:Health food manufacturers are embedding walnut derivatives into protein bars and omega-3 fortified beverages. Clean-label demand from North American and Chinese urban consumers accelerates ingredient procurement.
- USDA organic certification pathways:Streamlined organic transition programs reduce compliance timelines for California growers. Premium shelf positioning in natural grocery channels rewards certified handlers with price premiums.
- Cold-press oil extraction technology:Cosmetic and nutraceutical buyers are contracting directly with processors for unrefined walnut oil. This bypasses conventional foodservice distribution markups.
Market Restraints
- Input cost volatility:Almond and pistachio cultivation competes for limited Central Valley water, raising irrigation access costs for walnut orchards. Groundwater pumping restrictions tighten seasonally.
- Supply concentration risk:California's Central Valley produces the majority of US walnut supply. Consecutive drought cycles expose processors to single-region crop failure.
- Substitution threat:Chia seeds and flaxseed meal offer comparable omega-3 profiles at lower price points in baking applications. Formulators are testing these alternatives in cost-sensitive product lines.
Strategic Opportunities
- Underpenetrated geography:India's urban middle class shows rising appetite for premium imported nuts in tier-1 cities. Direct-to-consumer e-commerce channels bypass fragmented traditional retail.
- Regulatory tailwind:China's national nutrition labeling reforms highlight omega-3 content claims. Walnut processors can leverage this to differentiate from generic tree nut competitors.
- Technology convergence:Near-infrared sorting combined with AI-driven defect detection reduces labor costs in shelling facilities. Early adopters are achieving yield improvements that justify capital deployment.
Industry Challenges
- Skill gap in climate-adaptive agronomy:California growers lack sufficient technical expertise in deficit irrigation management and drought-resistant rootstock grafting. Extension services are struggling to scale training programs.
- Capex intensity for pasteurization compliance:FDA food safety modernization rules mandate validated kill-step equipment. Smaller shelling operations face financing constraints for HACCP-compliant infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Walnuts Market |
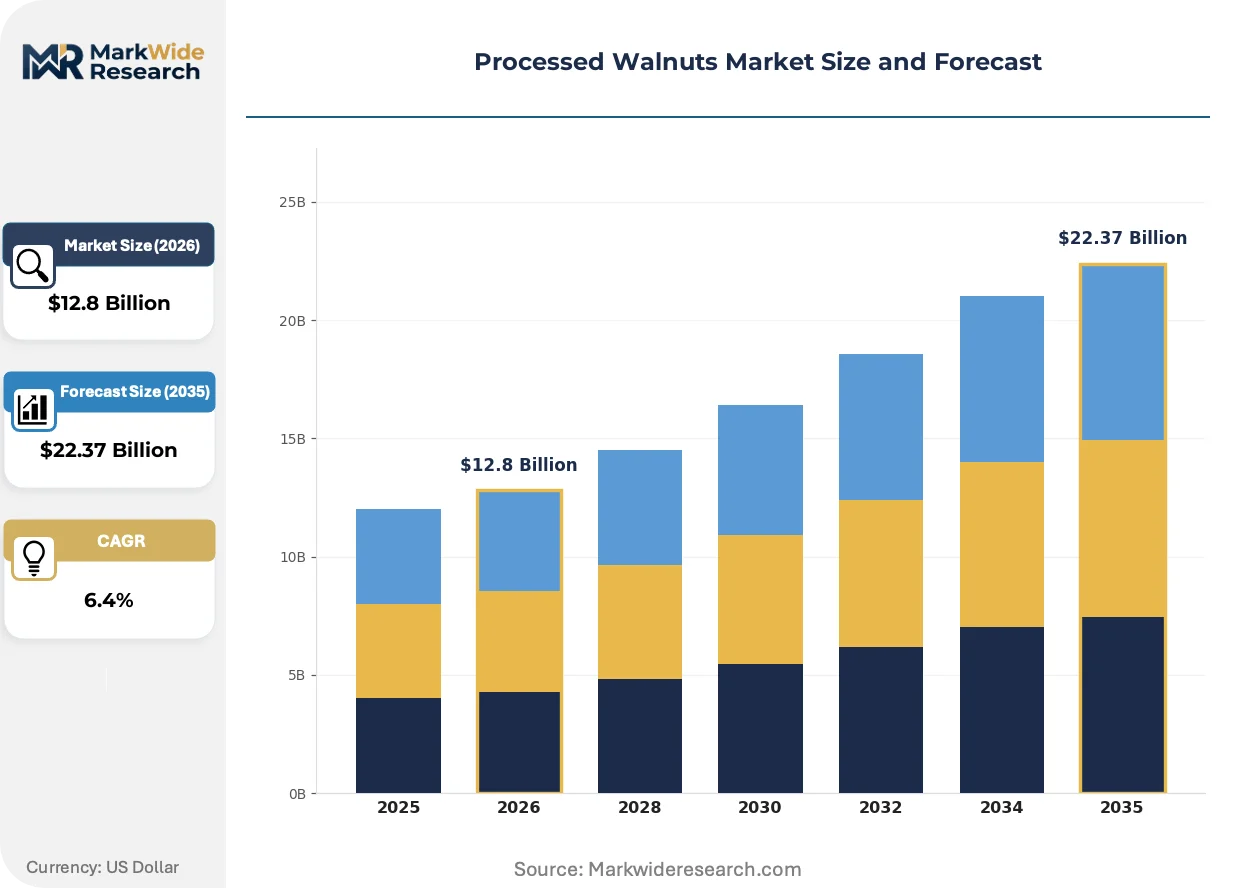
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Walnuts, Chopped Walnuts, Walnut Powder, Walnut Oil Application: Baking, Snack Foods, Confectionery, Health Foods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Diamond Foods, LLC, Future Group (Future Consumer Limited), Kashmir Walnut Group, Happilo International Pvt Ltd, Coopeniox, Grower Direct Nut Co. Inc, Natco Foods, Mariani Nut Company, Olam International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Walnuts Market Evolving Landscape
Processing technology and regulatory compliance requirements are reshaping competitive economics in walnut handling, with automation and sustainability certifications becoming primary differentiation vectors.
Hyperspectral imaging systems are electrifying quality control workflows in shelling facilities. Large-scale California processors are deploying these systems to detect shell fragments and kernel defects at line speeds exceeding manual sorting capacity. The technology is compressing labor requirements while improving food safety compliance rates for export shipments.
The EU Green Deal's Farm to Fork Strategy is tightening maximum residue limits for crop protection chemicals in imported nuts. European buyers are demanding expanded documentation of orchard management practices. California exporters are responding by accelerating integrated pest management adoption and third-party audit certifications to maintain market access.
Chinese consumers are gravitating toward portion-controlled, individually packaged walnut snacks for convenience and portion discipline. Domestic brands are displacing bulk-bin retail formats in tier-1 city supermarkets. This shift is most visible in Shanghai and Beijing, where premium positioning commands shelf space allocation from conventional whole-nut displays.
Processed Walnuts Market Segmentation
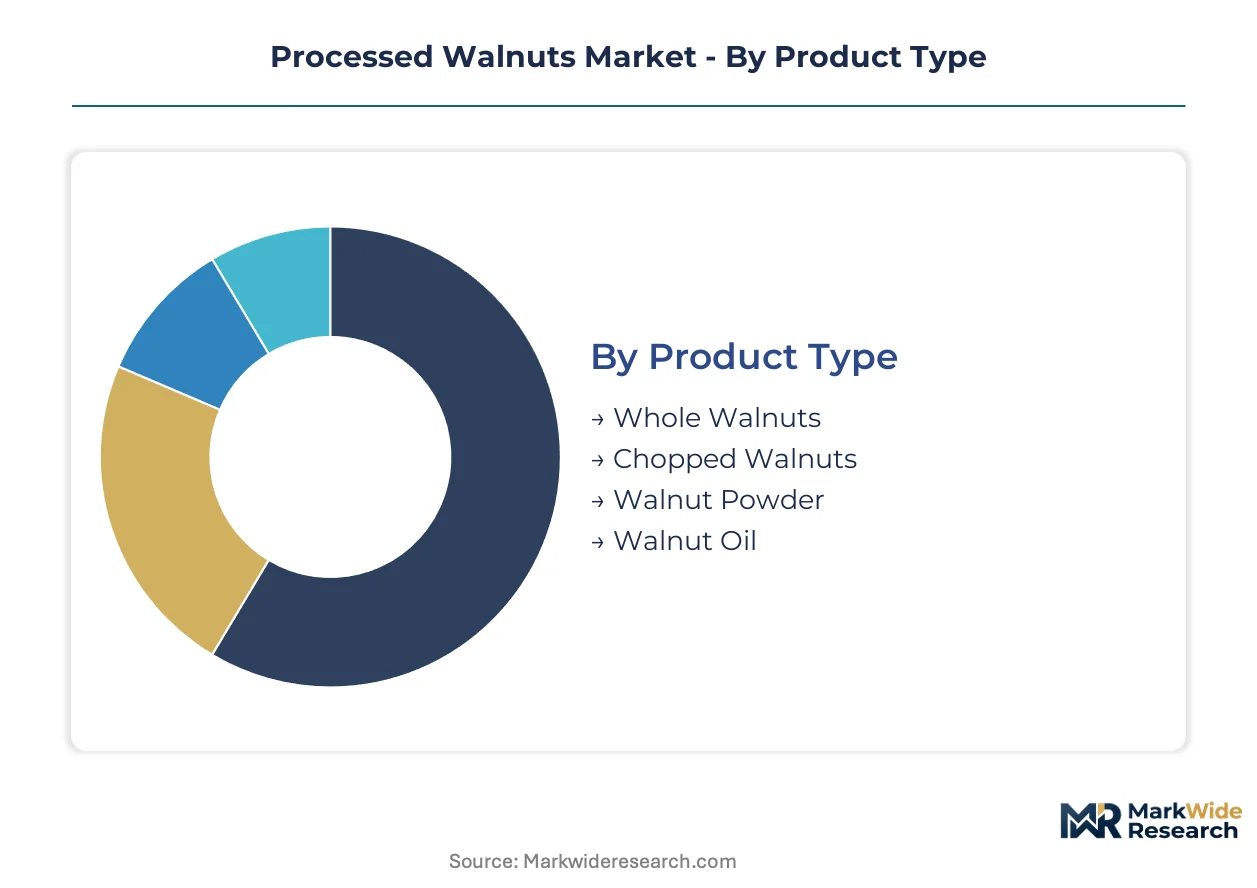
Segmentation in processed walnuts reveals divergent capital requirements and margin profiles across product formats and channel structures. Shelling and oil extraction infrastructure demands heavy upfront investment, while powder and chopped categories offer lower barriers to entry. Understanding these segment economics guides processor allocation decisions amid tightening water constraints in California's Central Valley.
Product Type:
Capital intensity varies sharply across processing stages, with oil extraction and whole-kernel handling requiring the most substantial fixed-asset deployment.
- Walnut Oil:Cold-press extraction systems demand stainless-steel pressing equipment and climate-controlled storage infrastructure. Cosmetic and nutraceutical buyers in Shanghai and Beijing contract directly for unrefined grades, bypassing conventional foodservice markups. FDA pasteurization compliance adds further capital burden for export-oriented facilities.
- Whole Walnuts:Mechanical shelling lines with near-infrared sorting systems represent the largest installed base of processing equipment. California's Diamond Foods and Mariani Nut Company anchor production capacity here, serving North American retail and Chinese import demand. Water-efficient cultivar development programs are reshaping orchard economics for kernel supply.
- Chopped Walnuts:Size-grading and fragment control equipment requires moderate capital outlay. Baking and health food manufacturers in tier-1 Indian cities drive procurement growth.
- Walnut Powder:Grinding and moisture-control systems carry lower fixed-asset requirements. Protein fortification applications in clean-label formulations attract specialty buyers.
Whole walnuts absorb the bulk of installed capacity; walnut oil is expanding most quickly.
Application:
End-use concentration determines pricing power, with health food and confectionery segments commanding premium positioning over commodity baking inputs.
- Health Foods:Omega-3 fortification claims in protein bars and functional beverages attract formulation contracts from North American clean-label brands. China's national nutrition labeling reforms highlight walnut-derived fatty acid content, differentiating processors from generic tree nut competitors. Cold-pressed oil integration into nutraceutical capsules extends value capture.
- Snack Foods:Individually packaged portion-controlled formats are displacing bulk-bin retail in Shanghai and Beijing supermarkets. Domestic Chinese brands secure shelf space through convenience positioning.
- Baking:Chopped and powder formats serve cost-sensitive commercial bakeries. Substitution pressure from chia seeds and flaxseed meal constrains margin expansion.
- Confectionery:Whole and half-kernel specifications for praline and chocolate inclusion require defect-free supply chains. EU Green Deal residue limits tighten orchard management documentation requirements for European buyers.
Health foods command the steepest price premiums; snack foods are gaining share fastest in urban Chinese distribution.
Distribution Channel:
Channel selection dictates working capital intensity and margin retention, with direct-to-consumer formats offering the most favorable economics for specialty roasters.
- Online Retail:Direct-to-consumer platforms allow specialty processors to bypass wholesale markups and capture full retail pricing. India's fragmented traditional retail structure makes e-commerce particularly attractive for premium imported nut penetration in Mumbai and Delhi.
- Supermarkets:Slotting fees and promotional allowances compress margins for packaged whole walnuts. Bulk-bin formats are losing space to portion-controlled alternatives.
- Specialty Stores:Natural grocery channels reward USDA organic certification with premium positioning. Smaller shelling operations face financing constraints for compliant infrastructure.
- Foodservice:Labor-intensive portion control requirements and distributor markups squeeze processor returns. Restaurant procurement concentrates on cost-efficient chopped grades.
Supermarkets dominate volume throughput; online retail is climbing the fastest among emerging channels.
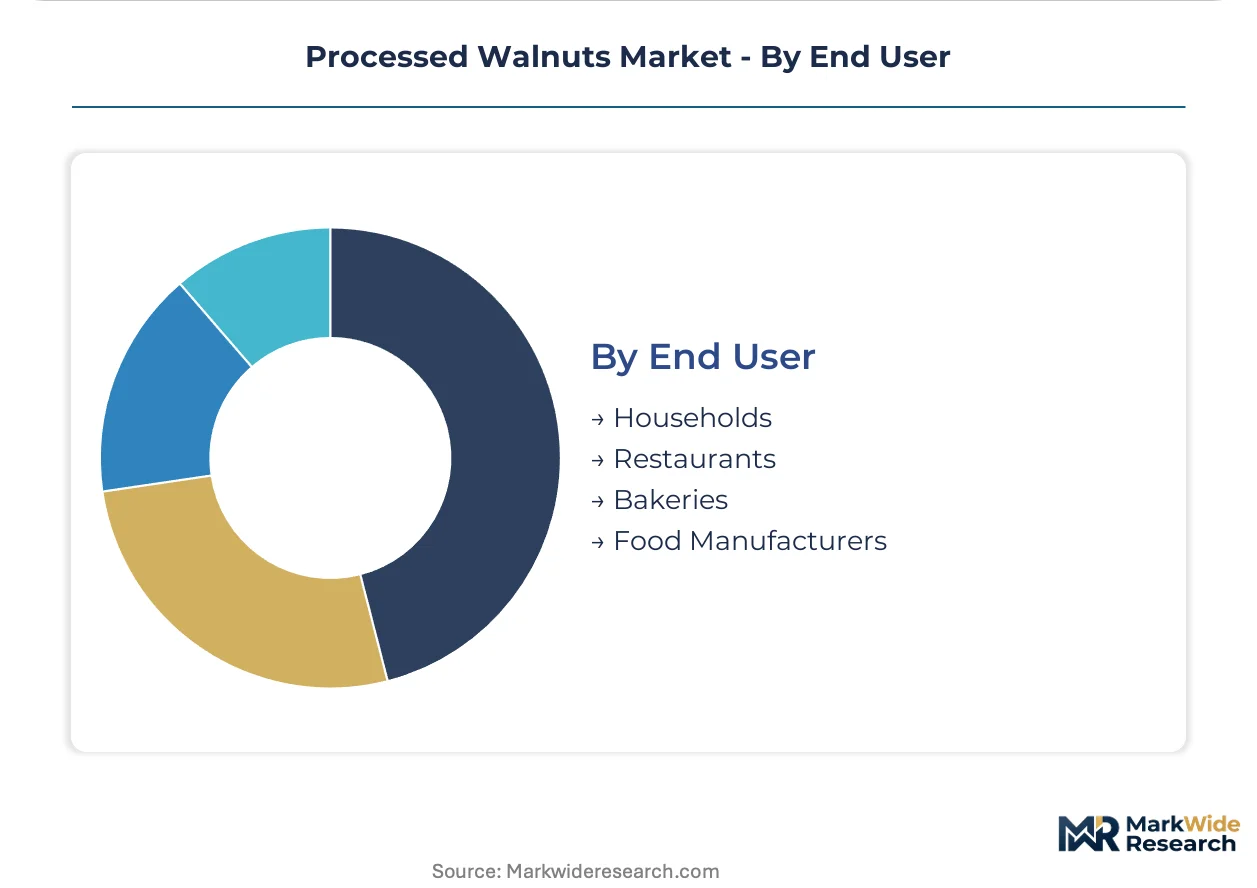
End User:
Customer scale and technical sophistication shape procurement patterns, with large food manufacturers driving standardization while artisanal bakeries seek differentiated supply.
- Food Manufacturers:Industrial buyers enforce strict HACCP compliance and lot-traceability requirements. Automated procurement systems favor processors with validated kill-step equipment and integrated pest management documentation for EU export.
- Households:Direct-to-consumer packaged formats emphasize convenience and portion discipline. Urban Chinese consumers in tier-1 cities show willingness to pay premiums for branded, individually wrapped products.
- Restaurants:Foodservice operators prioritize cost control over provenance claims. Chopped walnuts for salad and dessert applications dominate procurement.
- Bakeries:Artisanal and commercial bakers split between whole-kernel aesthetic requirements and cost-optimized fragment grades. Clean-label positioning drives interest in organic-certified supply.
Food manufacturers absorb the majority of industrial-scale output; households are expanding most quickly through e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors processed walnut supply chains through its integrated orchard-to-shelling infrastructure. Water constraints under state groundwater regulations are reshaping production economics across this dominant growing region. Demand clusters in urban centers across three continents are pulling product flows toward premium health-food channels.
United States
California's Sustainable Groundwater Management Act compresses irrigation allocations for walnut orchards in Fresno and Kern counties. FDA food safety modernization rules mandate validated kill-step equipment for export-oriented shelling facilities. Diamond Foods and Mariani Nut Company anchor processing capacity in the Central Valley, recalibrating output schedules after consecutive drought cycles.
China
Urban consumers in Shanghai and Beijing drive demand for individually packaged walnut snacks and cold-pressed oil products. National nutrition labeling reforms highlight omega-3 content claims, differentiating walnut processors from generic tree nut competitors. Domestic brands displace bulk-bin retail formats in tier-1 city supermarkets through convenience positioning.
India
Mumbai and Delhi's urban middle class shows rising appetite for premium imported nuts through direct-to-consumer e-commerce channels. FSSAI food safety standards shape import documentation requirements for processed kernel shipments. Kashmir Walnut Group sources from domestic growing regions while competing with California imports in metropolitan retail.
Germany
EU Green Deal Farm to Fork Strategy tightens maximum residue limits for crop protection chemicals in imported nuts. EFSA documentation requirements push California exporters toward integrated pest management adoption and third-party audit certifications. Hamburg and Rotterdam serve as entry points for kernel shipments destined for European confectionery manufacturers.
Australia
Health-conscious consumers in Sydney and Melbourne drive procurement of organic-certified walnut derivatives for clean-label formulations. Biosecurity regulations administered by the Department of Agriculture constrain import pathways for in-shell product. Local processors in Victoria and New South Wales focus on value-added roasting lines for domestic supermarket distribution.
Processed Walnuts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty roasting and direct-to-consumer channels. California's integrated orchard operators compete against multinational traders with multi-hemisphere procurement networks. Three archetypes dominate: vertically integrated growers with captive shelling capacity, commodity traders sourcing across origins, and value-added specialists commanding premium shelf positioning. Competitive moves concentrate on water-efficient cultivar development and HACCP-compliant infrastructure upgrades.
Among California-based integrated producers, Diamond Foods, LLC and Mariani Nut Company exemplify the orchard-to-package archetype with captive supply chains. Olam International anchors the multinational trading tier, buffering regional crop shortfalls through multi-hemisphere procurement networks. These three entities represent distinct strategic positions: captive production control, geographic diversification, and scale-driven commodity flows.
| Leading Market Players |
|---|
| Diamond Foods, LLC |
| Future Group (Future Consumer Limited) |
| Kashmir Walnut Group |
| Happilo International Pvt Ltd |
| Coopeniox |
| Grower Direct Nut Co. Inc |
| Natco Foods |
| Mariani Nut Company |
| Olam International |
| Others |
Value Network & Pricing Analysis
Chinese urban consumers' preference for individually packaged portion-controlled walnut snacks forces processors to absorb premium packaging costs and cold-chain logistics investments, compressing margins on standard grades while elevating certified organic and cold-pressed oil tiers. This demand-side specification shift rewards handlers with HACCP-compliant infrastructure and integrated orchard control, widening spreads between commodity kernel shipments and value-added formats.
Pricing Analysis
Certification bundling separates quoted price levels, with USDA organic and FDA export-grade validation commanding substantial premiums over conventional kernel shipments. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade and vertical integration depth, with Diamond Foods and Mariani Nut Company leveraging captive orchard supply to defend margin position. Price erosion runs through economy-grade chopped walnuts as chia seed and flaxseed meal substitution intensifies in cost-sensitive baking applications. Food manufacturers exhibit highest price sensitivity due to automated procurement systems, while cosmetic and nutraceutical buyers for cold-pressed oil show lowest elasticity.
Supply Chain Analysis
Container freight volatility from California's Central Valley ports to Shanghai and Hamburg directly shapes landed cost structures for export-oriented shelling facilities. Supply concentrates in the United States, China, and India, with California's Fresno and Kern counties anchoring global kernel output. Raw material flows draw from deficit-irrigated Juglans regia orchards, stainless-steel pressing equipment for oil extraction, and moisture-control systems for powder processing. Single-region vulnerability from consecutive drought cycles exposes processors to irrigation allocation cuts under the Sustainable Groundwater Management Act. Distribution runs through integrated orchard-to-package operators, commodity traders with multi-hemisphere networks, and direct-to-consumer specialty roasters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processed walnut supply chains face structural compression from California groundwater restrictions, with irrigation allocation limits propping kernel pricing across all grades by constraining orchard expansion and shelling plant throughput capacity.
For Market Incumbents: Deploy water-efficient cultivar development programs to defend throughput against Sustainable Groundwater Management Act allocation cuts. Deepen backward integration into deficit irrigation infrastructure and drought-resistant rootstock grafting capabilities to reduce exposure to single-region crop failure. Accelerate HACCP-compliant pasteurization equipment deployment ahead of FDA enforcement waves to capture export certification premiums. For New Entrants and Emerging Players: Launch via direct-to-consumer e-commerce channels targeting Mumbai and Delhi's urban middle class, bypassing India's fragmented traditional retail structure. Penetrate India's tier-1 cities with premium imported nut positioning, leveraging FSSAI import documentation requirements as a barrier against unorganized competitors. Anchor procurement through multi-hemisphere sourcing networks to buffer against California drought cycles. For Investors and Strategic Acquirers: The window for entry favors value-added specialists with USDA organic certification and cold-press oil extraction infrastructure. Long-term viability hinges on water rights security and climate-adaptive agronomy capabilities rather than commodity scale. Monitor China's national nutrition labeling reform implementation as the signal for omega-3 content claim differentiation intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Efficient Cultivar Development | Deficit irrigation expertise under California's Sustainable Groundwater Management Act secures orchard throughput. |
| HACCP-Compliant Infrastructure Upgrade | FDA pasteurization validation opens export pathways to EU and Chinese buyers demanding documentation. |
| Direct-to-Consumer Channel Launch | E-commerce penetration in Mumbai and Delhi bypasses fragmented Indian retail markups for premium positioning. |
| Cold-Press Oil Extraction Scale-Up | Cosmetic and nutraceutical contracts in Shanghai and Beijing capture margin pools above foodservice channels. |
| Multi-Hemisphere Procurement Network | Geographic diversification buffers California drought exposure for supply continuity across volatile growing seasons. |
Research Methodology
USDA production reports, FDA import refusal data, and California State Water Resources Control Board adjudication records formed the secondary backbone for supply-side validation. Primary interviews with Central Valley orchard managers, shelling facility operations directors, and Chinese tier-1 city supermarket category buyers combined with customs shipment records and organic certification databases. Bottom-up triangulation across processor capacity utilization rates and top-down reconciliation against national nutrition labeling reform timelines anchored volume estimates.
Historical trendline analysis of kernel output, oil extraction yields, and packaging format shifts informed projection modeling across the analysis window. Segmentation dimensions included product type, application, distribution channel, and end-user scale, with water rights security status as an industry-specific overlay. CAGRs derived from irrigation allocation scenario weighting and drought frequency distributions, incorporating EU Green Deal residue limit tightening and China's omega-3 labeling reform as demand-side inflection inputs.
Drought recurrence patterns, groundwater adjudication outcomes, and substitution elasticity in baking applications are the dominant revision risks to modeled forecasts. Stakeholders should weight assumptions against their own operating context and regional water portfolio exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Passionfruit Seed Oil Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Middle East and Africa Hazelnut Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Betel Nuts Market