
 Bambara Beans Market | 2026-2036
Bambara Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Bambara Beans Market Outlook
Premium-grade flour specifications is redrawing competitive boundaries in the Bambara beans sector. BamNut leverages its specialized breeding programs to secure high-protein cultivars for commercial processors. Olam International anchors West African sourcing infrastructure through controlled procurement networks spanning Ghana and Nigeria. WhatIF Foods differentiates via clean-label snack formulations that command shelf-space premiums in European retail channels.
Bambara beans are drought-tolerant legumes containing approximately 18-25% protein and 50-65% carbohydrate by dry weight, with a lipid fraction below 6.5%, making them suitable for gluten-free flour milling and plant-protein isolation. The crop thrives in sandy loam soils with minimal nitrogen fertilizer input due to symbiotic rhizobium fixation. Raw whole beans occupy the largest volume share as the foundational input for downstream processing into flour and roasted products. Flour segment growth outpaces other product categories as bakery and infant nutrition manufacturers substitute Bambara protein for imported soy isolates. Online retail distribution channels are expanding fastest among channel options, though wholesale still captures the dominant margin pool through bulk export contracts.
Ghana's Food and Drugs Authority and Nigeria's National Agency for Food and Drug Administration and Control enforce mycotoxin limits and labeling standards that determine export eligibility for processed Bambara products. The Economic Community of West African States' harmonized standards framework is reducing cross-border certification burdens for regional traders. ISO 22000 and HACCP compliance requirements from European importers are filtering supplier bases and favoring processors with documented traceability systems. Stakeholders must monitor evolving allergen declaration rules in target export markets and assess backward integration into seed multiplication to secure cultivar consistency.
Market Dynamics
Protein substitution mandates in West African food processing are compressing procurement timelines and forcing rapid backward integration into seed multiplication networks across Ghana and Nigeria.
Growth Catalysts
- ECOWAS Harmonized Standards:Cross-border certification burdens for Bambara flour traders are falling, accelerating regional trade flows between processing clusters in Kumasi and Ibadan.
- Rhizobium Symbiosis:Minimal nitrogen fertilizer requirements cut input costs for smallholder cultivators, expanding viable production zones into marginal sandy loam territories.
- Infant Nutrition Formulators:Bakery and weaning food manufacturers are substituting Bambara protein isolates for imported soy, pulling volume through West African milling infrastructure.
Market Restraints
- ISO 22000 Compliance Costs:European importer documentation requirements filter supplier bases, excluding processors lacking traceability system investments.
- Mycotoxin Contamination Risk:Ghana's Food and Drugs Authority and Nigeria's NAFDAC enforce strict aflatoxin limits that disqualify harvests from humid storage zones.
- Cowpea Substitution Pressure:Established cowpea supply chains in Sahelian markets compete for the same protein-fortification contracts in institutional feeding programs.
Strategic Opportunities
- Clean-Label Snack Channels:European retail buyers are commanding shelf-space premiums for allergen-declared Bambara formulations, opening branded export positions.
- Online Retail Expansion:Direct-to-consumer platforms are capturing margin pools previously held by wholesale bulk export intermediaries in regional trade.
- Climate-Resilient Breeding:National agricultural research institutes in Malawi are deploying drought-tolerant cultivars that stabilize yield consistency for commercial offtake agreements.
Industry Challenges
- HACCP Implementation Timeline:Processors face extended certification periods to meet European importer requirements, delaying market entry for new milling facilities.
- Seed Multiplication Expertise Gap:Commercial-scale propagation of high-protein cultivars requires agronomic skills concentrated in public research stations, constraining private sector scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bambara Beans Market |
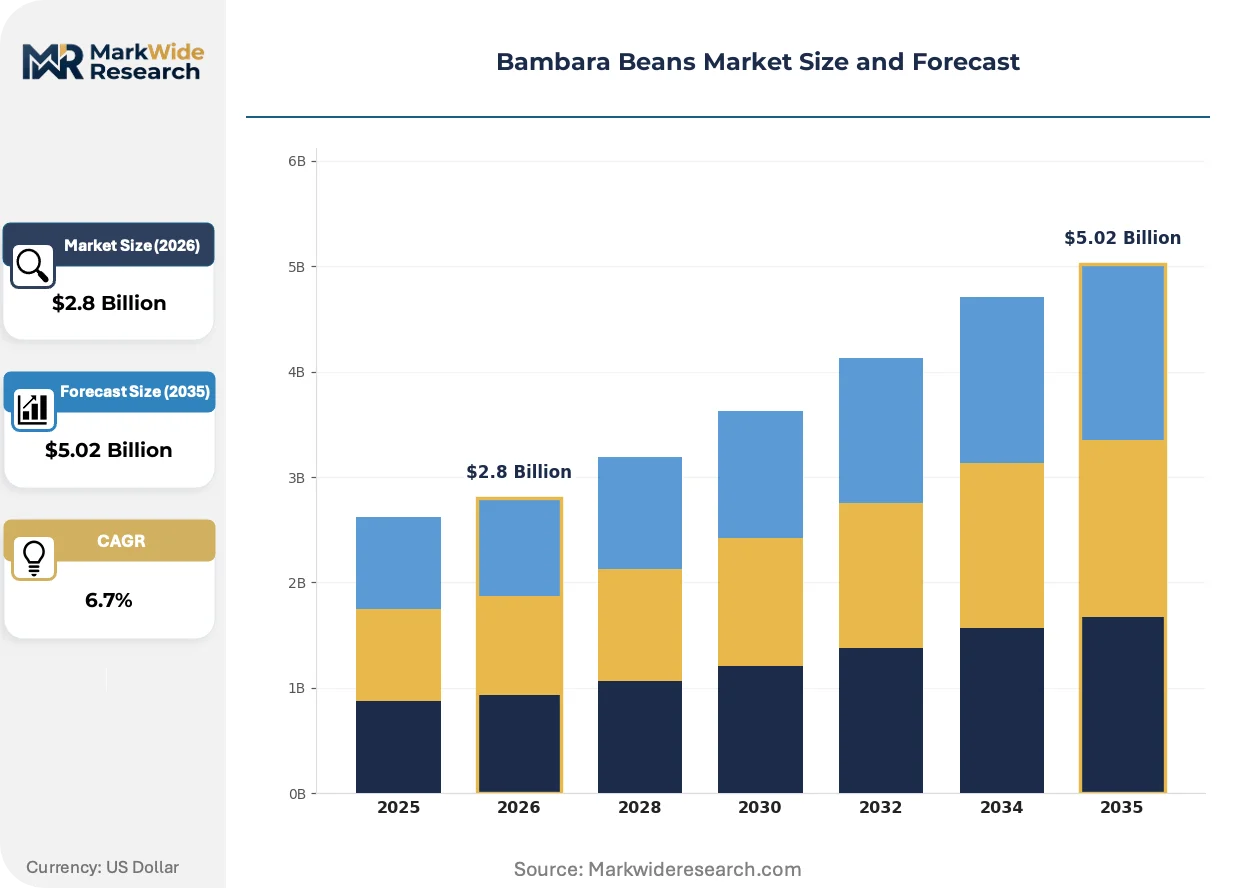
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Roasted, Flour, Snack End Use: Food Industry, Feed Production, Nutraceuticals, Organic Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Bulk, Eco-friendly Packaging |
| Companies Covered | BamNut, African Flavour’s, Earth Expo Company, Olam International, Khushbu Trades, Sacoma Global Foods Innovation CIC, NutriVate, NamZ, WhatIF Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bambara Beans Market Strategic Shifts
Processing technology diffusion and regulatory convergence are redrawing competitive boundaries across the Bambara value chain, with digital traceability and clean-label positioning emerging as primary differentiation vectors.
Mechanical dehulling and fractionation equipment is fragmenting traditional whole-bean trading patterns. Commercial processors in Ghana and Nigeria are adopting compact milling lines that separate protein-rich fractions from starch components, enabling ingredient-grade supply to infant nutrition formulators. This equipment diffusion is fragmenting the historical dominance of raw commodity exporters by allowing mid-scale processors to capture downstream margin pools previously held by importers.
EU Green Deal due diligence requirements are reshaping sourcing accountability. Mandatory deforestation-free supply chain declarations for imported agricultural commodities now extend to legume ingredients entering European food manufacturing. Bambara processors seeking export eligibility are deploying GPS-tagged farm mapping and third-party audit protocols to satisfy EFSA-aligned importer risk assessments.
Ingredient buyers are consolidating supplier relationships around documented provenance. West African bakery and weaning food manufacturers are reducing their vendor counts, favoring processors with captive seed multiplication programs and batch-level mycotoxin testing. This concentration pattern is most visible in procurement departments of Ghanaian food industry buyers expanding protein fortification programs.
Bambara Beans Market Segmentation
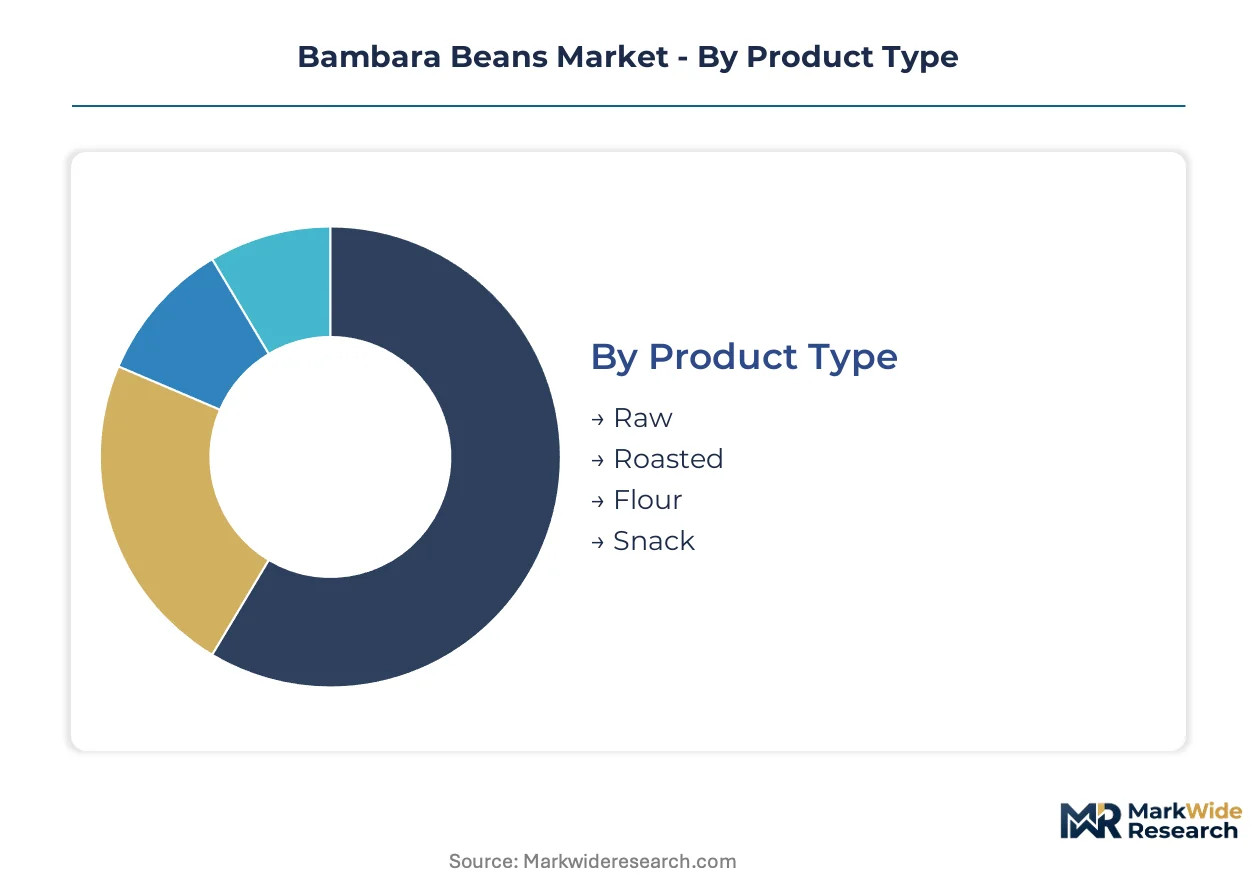
Bambara bean processors navigate distinct regulatory thresholds across each product tier, with infant nutrition formulators and European exporters facing the strictest compliance burdens. Segmentation reveals how Ghana's Food and Drugs Authority and Nigeria's NAFDAC enforcement patterns concentrate margin capture among certified operators.
Product Type:
Regulatory differentiation separates commodity-grade whole beans from value-added fractions subject to mycotoxin limits and allergen declarations.
- Raw:Whole unprocessed beans with 18-25% protein content serve as the foundational input for downstream milling operations. Procurement concentrates among Kumasi and Ibadan processing clusters where Ghana's Food and Drugs Authority enforces aflatoxin thresholds that disqualify humid-zone harvests.
- Flour:Gluten-free milling output with protein isolates suitable for bakery fortification and weaning food formulations. Demand is climbing fastest among West African infant nutrition manufacturers substituting Bambara isolates for imported soy, pulling volume through controlled procurement networks.
- Roasted:Heat-treated whole beans for direct consumption and snack ingredient supply.
- Snack:Clean-label consumer formats commanding shelf-space premiums in European retail channels.
Raw handles the majority of throughput; flour is gaining share fastest.
End Use:
Application maturity determines margin structure, with established food manufacturing offering scale against emerging nutraceutical positions.
- Food Industry:Bakery, weaning food, and protein fortification applications dominate commercial offtake. Procurement departments across Ghanaian food industry buyers are consolidating vendor relationships around processors with captive seed multiplication and batch-level mycotoxin testing.
- Organic Products:Certified cultivation meeting EU Green Deal deforestation-free supply chain declarations. GPS-tagged farm mapping and third-party audit protocols satisfy EFSA-aligned importer risk assessments for European market entry.
- Feed Production:Animal nutrition applications leveraging residual protein fractions.
- Nutraceuticals:Emerging isolate applications for functional ingredient positioning.
Food Industry commands the volume base; Organic Products shows the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect customer scale, with bulk wholesale capturing margin pools against direct-to-consumer expansion.
- Wholesale:Bulk export contracts through controlled procurement networks spanning Ghana and Nigeria. Olam International anchors this infrastructure, capturing dominant margin pools through volume aggregation.
- Online Retail:Direct-to-consumer platforms expanding fastest among channel options. WhatIF Foods leverages this route for clean-label snack distribution commanding premiums in European retail.
- Supermarkets:Conventional retail shelf placement for packaged flour and roasted products.
- Specialty Stores:Health-food and ethnic grocery positioning for premium-grade specifications.
Wholesale moves the bulk of volume; Online Retail expands most quickly on margin capture.
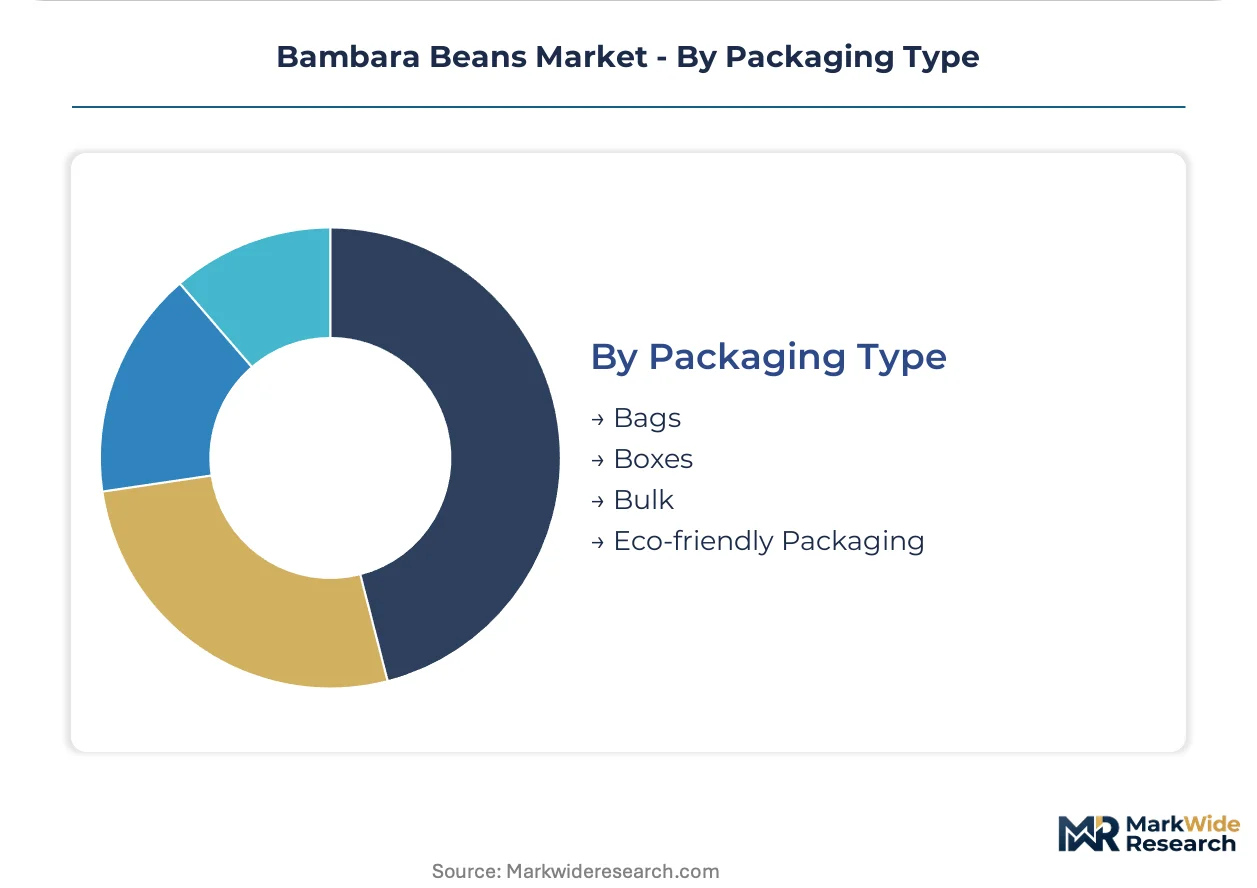
Packaging Type:
Packaging configuration tracks customer sophistication, with industrial buyers favoring unbranded bulk against retail-facing formats.
- Bulk:Unpackaged commodity shipments for industrial processors and feed manufacturers. Minimal handling preserves cost position for price-sensitive institutional buyers.
- Eco-friendly Packaging:Biodegradable and recyclable formats satisfying EU Green Deal due diligence requirements. European importers mandate sustainable packaging credentials for deforestation-free supply chain eligibility.
- Bags:Standard consumer and food-service pouches for flour and roasted products.
- Boxes:Rigid packaging for premium snack and gift positioning.
Bulk dominates tonnage movement; Eco-friendly Packaging climbs fastest on regulatory pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana exports Bambara bean flour to European infant nutrition formulators while Nigerian processors supply West African bakery chains. Malawi ships drought-tolerant cultivars to regional aggregation hubs. Trade corridors concentrate around three national production zones with distinct regulatory and infrastructure profiles.
Ghana
Infant nutrition manufacturers and clean-label snack exporters drive demand for premium-grade flour. The Food and Drugs Authority enforces mycotoxin limits that disqualify humid-zone harvests from export eligibility. Processing clusters around Kumasi host mechanical dehulling lines that separate protein fractions for bakery fortification contracts.
Nigeria
Bakery chains and institutional feeding programs pull volume through domestic milling infrastructure. The National Agency for Food and Drug Administration and Control operates batch-level testing protocols that filter supplier bases for cross-border shipments. Ibadan anchors controlled procurement networks spanning Oyo State into northern cultivation belts.
Malawi
National agricultural research institutes deploy climate-resilient breeding programs that stabilize yield consistency for commercial offtake agreements. The Ministry of Agriculture supports seed multiplication networks extending into marginal sandy loam territories. Lilongwe-based stations propagate high-protein cultivars for regional processor contracts.
United Kingdom
Specialty food retailers and allergen-conscious consumers command shelf-space premiums for declared-ingredient Bambara formulations. The Food Standards Agency enforces labeling standards that determine import eligibility for processed legume products. London distribution hubs consolidate West African shipments for European re-export.
Germany
Organic product formulators and plant-protein isolate buyers source deforestation-free supply chains under EU Green Deal due diligence requirements. The Federal Office of Consumer Protection and Food Safety aligns with EFSA risk assessment protocols for third-country imports. Hamburg port infrastructure handles bulk consolidation from Ghanaian and Nigerian export terminals.
Bambara Beans Market Competitive Environment
Listed leaders compete with private specialists across certification and traceability dimensions. Olam International anchors volume aggregation through controlled procurement networks spanning multiple West African origins. The vendor base separates into three archetypes: integrated commodity traders, breeding-program specialists, and clean-label consumer brands. Competitive moves concentrate on backward integration into seed multiplication and HACCP certification investments for European market entry.
Within the breeding-specialist tier, BamNut occupies a position exemplifying cultivar development for commercial processors. Among integrated trading houses, Olam International sits within the scale-driven archetype representing volume aggregation across Ghana and Nigeria. On the consumer-facing vector, WhatIF Foods exemplifies clean-label positioning commanding retail premiums in European channels.
| Leading Market Players |
|---|
| BamNut |
| African Flavour's |
| Earth Expo Company |
| Olam International |
| Khushbu Trades |
| Sacoma Global Foods Innovation CIC |
| NutriVate |
| NamZ |
| WhatIF Foods |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Ghanaian flour processors and European infant nutrition formulators lock in supply access while providing price visibility across multi-season procurement cycles. These arrangements concentrate margin capture among certified operators who meet Ghana's Food and Drugs Authority mycotoxin thresholds.
Pricing Analysis
Prior-generation whole-bean commodity trading faces margin compression against next-generation protein isolate premiums. Three-tier pricing structure across premium-grade flour, standard milled output, and raw commodity beans separates certified export-grade material from humid-zone harvests disqualified by aflatoxin limits. Price differentiation hinges on HACCP documentation completeness and batch-level traceability. Cost compression in commodity tiers is intensifying because cowpea substitution pressure from Sahelian supply chains erodes institutional contract margins. Smallholder cultivators show highest price sensitivity, while European organic product formulators absorb premiums for deforestation-free supply chain credentials.
Supply Chain Analysis
Strategic stockpiling preferences dominate West African processing clusters, where Kumasi and Ibadan mills maintain buffer inventories against seasonal harvest variability. Geographic supply concentration centers on Ghana, Nigeria, and Malawi, with drought-tolerant cultivar propagation expanding viable production zones. Raw material dependencies include rhizobium inoculants for nitrogen fixation, mechanical dehulling equipment for fractionation, and GPS-tagged farm mapping systems for EU Green Deal compliance. Single-source vulnerability runs through seed multiplication expertise concentrated in public research stations. Distribution runs through controlled procurement networks anchored by integrated trading houses, with online retail platforms fragmenting wholesale margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bambara beans market builds defensive moats through regulatory entrenchment, where HACCP certification and mycotoxin compliance create exclusionary barriers that filter supplier bases and consolidate procurement relationships around documented operators.
For Market Incumbents: Shield market position by deepening backward integration into captive seed multiplication programs securing high-protein cultivar consistency. Expand batch-level testing infrastructure to preempt Ghana's Food and Drugs Authority and Nigeria's NAFDAC enforcement actions. Cowpea substitution pressure in institutional feeding programs demands certification investments that emerging processors cannot replicate quickly. For New Entrants and Emerging Players: ISO 22000 fast-track certification opens European export eligibility for mid-scale mills lacking legacy infrastructure. Target online retail distribution for clean-label snack formulations where shelf-space premiums offset scale disadvantages. Infant nutrition formulators in West Africa represent the most penetrable buyer segment, pulling volume through regional milling infrastructure as soy isolate substitution accelerates. For Investors and Strategic Acquirers: Breeding-program specialists with documented cultivar development pipelines offer acquisition exposure to upstream intellectual property scarcity. Long-term viability rests on climate-resilient germplasm ownership and regulatory compliance infrastructure rather than commodity trading scale. Watch for ECOWAS harmonized standards implementation as an inflection signal accelerating cross-border trade consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | Captive supply of high-protein cultivars secures processor offtake agreements with infant nutrition formulators. |
| HACCP Certification Investment | European importer eligibility filters expand addressable market for Ghanaian and Nigerian milling operations. |
| Clean-Label Snack Launch | WhatIF Foods demonstrates shelf-space premium capture in allergen-declared European retail channels. |
| Digital Traceability Deployment | GPS-tagged farm mapping satisfies EU Green Deal due diligence requirements for deforestation-free supply chains. |
| Climate-Resilient Cultivar Licensing | Malawian research station germplasm stabilizes yield consistency for commercial contracts in marginal sandy loam zones. |
Study Parameters
A standing panel of agricultural research directors, flour mill procurement managers, infant nutrition formulators, and EU import compliance officers provided ongoing calibration across primary data collection. Secondary validation drew from Ghana's Food and Drugs Authority enforcement records, Nigeria's NAFDAC batch-testing protocols, ECOWAS harmonized standards documentation, and customs trade data tracking Bambara bean flour shipments. Bottom-up cultivar yield assessments and top-down regional production estimates underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type tiers, end-use application maturity, distribution channel economics, and packaging regulatory compliance. CAGRs were derived from fitted growth curves incorporating rhizobium symbiosis adoption rates, mechanical dehulling equipment diffusion patterns, and EU Green Deal implementation timelines as industry-specific forecast inputs.
Underlying assumptions cover climate-resilient breeding program deployment rates and ECOWAS cross-border certification harmonization, with deviation risk concentrated in mycotoxin contamination events and cowpea substitution acceleration in institutional feeding programs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Apricot Kernel Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Tiger Nuts Market