
 Almond Extract Market | 2026-2036
Almond Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Extract Market Analysis
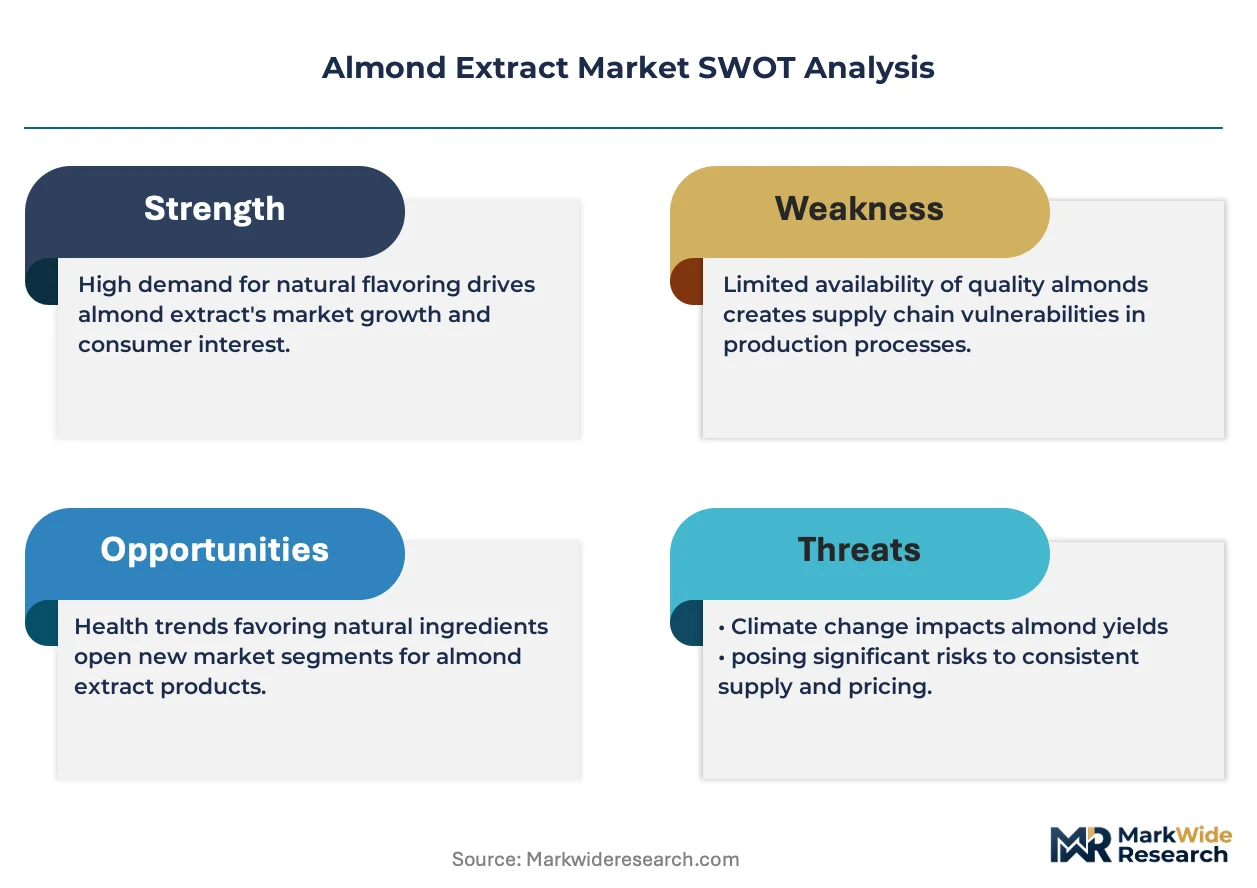
EU Green Deal farm-to-fork sustainability targets is recalibrating procurement standards across European food manufacturing, compelling extract suppliers to verify deforestation-free almond sourcing and reduce solvent residues in production. McCormick & Company, Inc. leverages its integrated spice and flavor supply chain to secure bulk natural almond extract contracts with North American retail bakeries. Nielsen-Massey Vanillas, Inc. specializes in cold-process extraction methods that preserve volatile benzaldehyde compounds for premium confectionery clients. Frontier Co-op anchors the organic and fair-trade segment through cooperative purchasing networks that connect small-scale almond growers in California to commercial buyers.
Almond extract comprises a concentrated flavoring preparation derived from bitter almond kernels or apricot kernel substitutes, typically containing benzaldehyde as the primary aromatic compound at concentrations ranging from one percent to five percent by volume, suspended in an ethanol or glycerin carrier base for food-safe dispersion. Manufacturers produce the extract through steam distillation or maceration processes designed to isolate volatile oils while managing cyanogenic glycoside content through controlled heat treatment and dilution protocols. Natural almond extract leads product type revenue pools due to clean-label premiums in baking and beverage applications, while personal care represents the fastest-growing application channel as cosmetic formulators incorporate almond oil fractions into skincare emulsions. Liquid form dominates distribution volume through supermarkets and direct sales channels, though powder formats are gaining traction in industrial-scale confectionery operations seeking extended shelf stability and reduced shipping weights.
FDA food additive regulations and USDA organic certification standards govern extract labeling, solvent limits, and allergen disclosure in the United States, while REACH chemical registration requirements and EFSA flavoring substance evaluations shape market access conditions across European Union member states. India's FSSAI import clearance protocols for food flavorings and China's GB standards for edible essences add compliance layers for suppliers targeting Asia-Pacific expansion. Stakeholders must monitor evolving benzaldehyde concentration thresholds and emerging biotechnology alternatives that could reshape raw material sourcing economics without warning.
Market Dynamics
Clean-label formulation mandates are compressing synthetic benzaldehyde demand as EU Green Deal deforestation-free sourcing rules and FDA allergen disclosure requirements force extractors to verify bitter almond kernel provenance and reduce solvent residues.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Deforestation-free sourcing mandates are compelling French artisanal confectionery producers to certify organic almond extract for protected-origin applications.
- Cold-process extraction methods:These techniques preserve volatile benzaldehyde compounds for premium patisserie supply chains seeking flavor intensity retention.
- California almond cooperative networks:Small-scale growers connect to commercial buyers through fair-trade purchasing arrangements, securing organic feedstock volumes.
Market Restraints
- Bitter almond kernel supply concentration:California and Mediterranean growing regions dominate raw material sourcing, exposing processors to climate-driven harvest volatility.
- Cyanogenic glycoside management costs:Controlled heat treatment and dilution protocols add processing overhead that synthetic benzaldehyde competitors avoid.
- REACH chemical registration friction:EFSA flavoring substance evaluations create extended approval timelines for novel extraction solvent formulations.
Strategic Opportunities
- Personal care emulsion formulators:Cosmetic manufacturers incorporate almond oil fractions into skincare products, opening non-food revenue channels.
- Powder format industrial adoption:Confectionery operations seeking shelf stability and shipping weight reduction represent an underpenetrated format conversion opportunity.
- India FSSAI import clearance pathways:Streamlined food flavoring protocols enable Asia-Pacific market access for certified organic extract suppliers.
Industry Challenges
- Organic certification timeline compression:USDA standards and EU organic equivalency agreements require multi-year field-to-bottle traceability documentation.
- Volatile oil isolation expertise scarcity:Steam distillation and maceration process optimization demands specialized flavor chemist talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Extract Market |
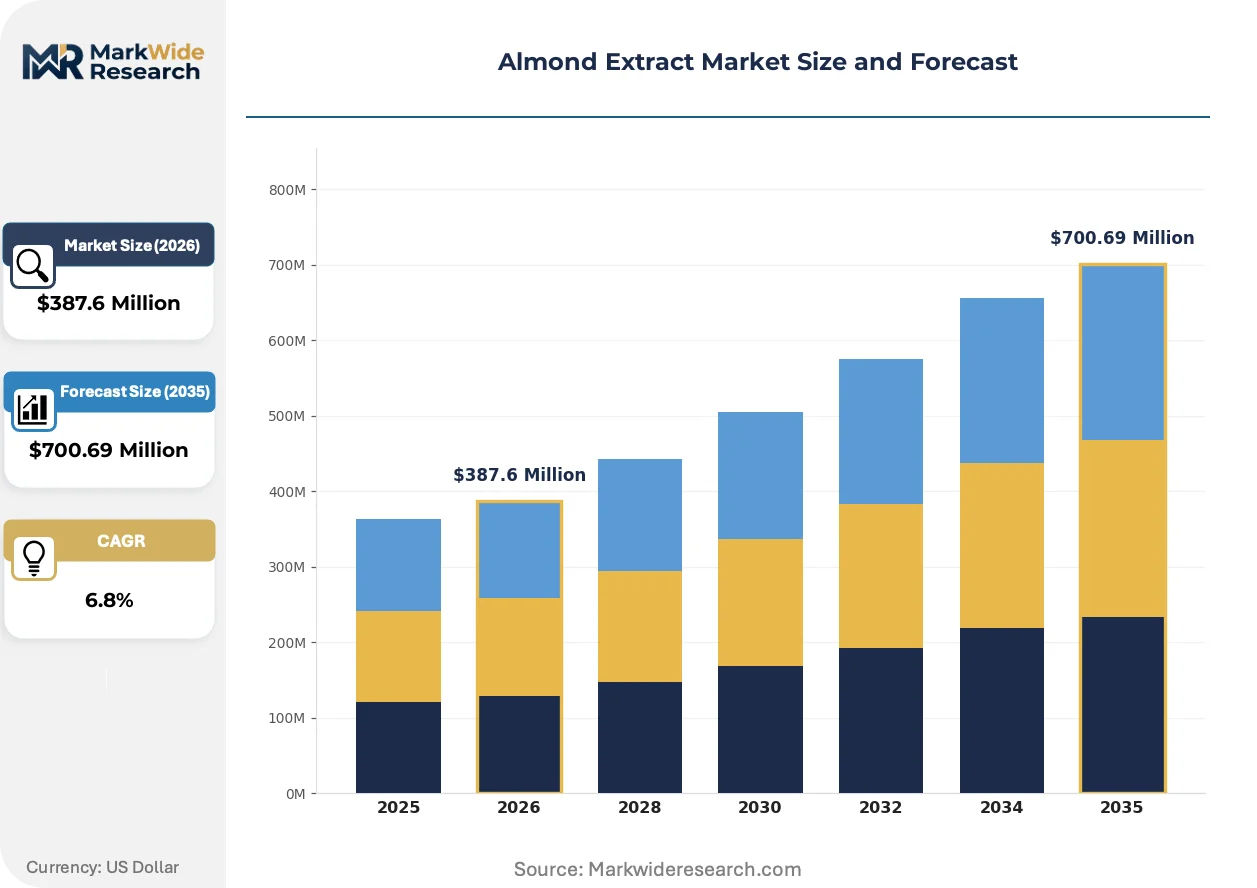
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Almond Extract, Artificial Almond Extract, Almond Oil, Almond Powder Application: Baking, Confectionery, Beverage, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Form: Liquid, Powder, Capsules, Emulsion |
| Companies Covered | McCormick & Company, Inc., Nielsen-Massey Vanillas, Inc., Frontier Co-op, Queen Fine Foods, ADM, Royal Nut Company, LorAnn Oils, The Watkins Co., Blue Diamond Growers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Extract Market Emerging Trajectories
Extraction technology convergence and regulatory transparency mandates are reconfiguring how almond extract suppliers validate purity, manage solvent residues, and communicate provenance to downstream formulators.
Supercritical CO2 extraction is rewriting benzaldehyde recovery economics by eliminating ethanol carrier dependence and reducing thermal degradation of aromatic compounds. Premium chocolate manufacturers in Belgium and Switzerland adopt this method for single-origin flavor profiles. The technology is compressing conventional solvent-based extraction margins in high-value confectionery segments.
REACH chemical registration requirements and EFSA flavoring substance evaluations are tightening benzaldehyde concentration thresholds across European Union member states. Extract suppliers must submit enhanced toxicological dossiers for existing food additive approvals. French and Italian flavor houses are accelerating natural certification programs to preempt regulatory displacement.
Direct-procurement relationships between retail bakeries and California almond cooperatives are disintermediating traditional spice and flavor distributors. North American clean-label baking chains now require batch-level provenance documentation. This pattern concentrates most visibly in artisanal sourdough and pastry segments across the Pacific Coast states.
Almond Extract Market Segmentation
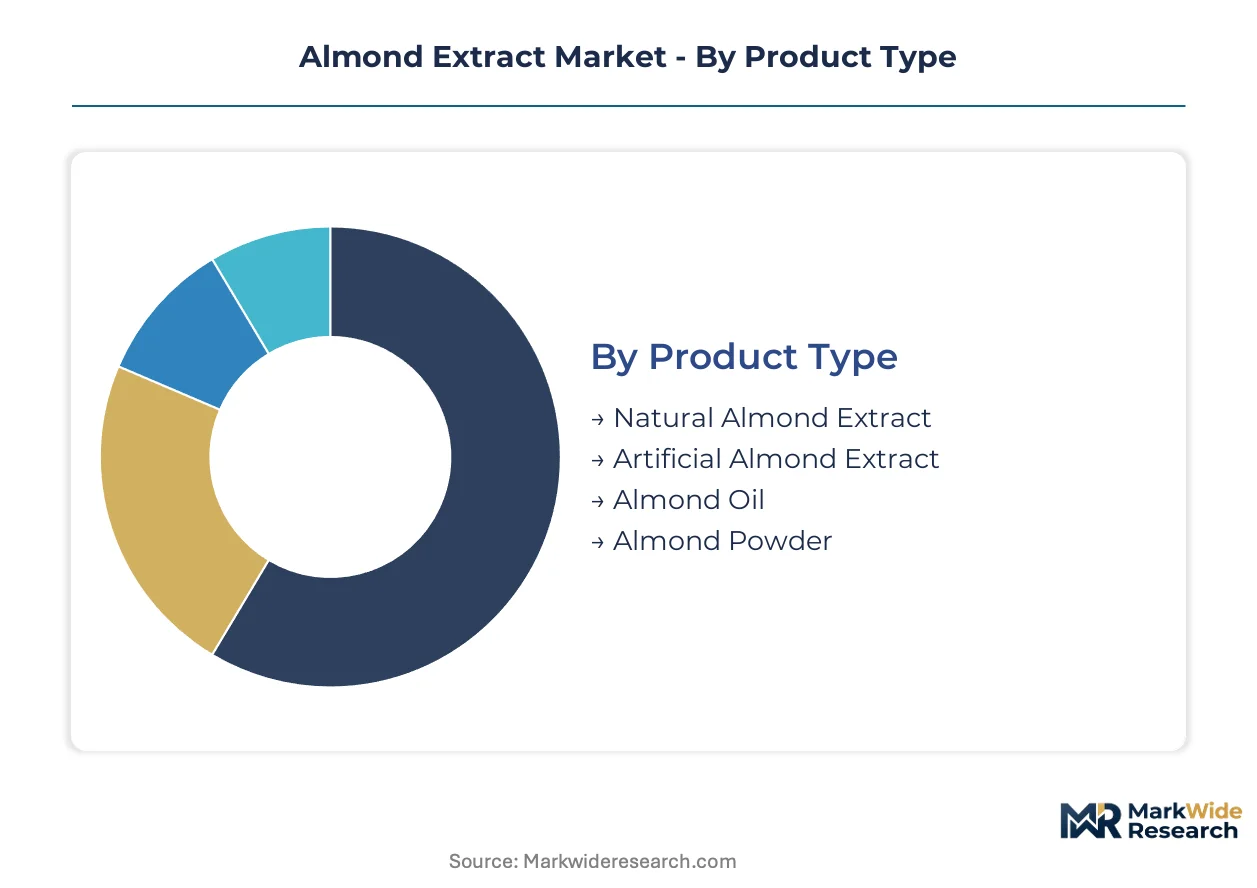
Almond extract procurement decisions hinge on formulation requirements, regulatory compliance burdens, and supply chain transparency mandates. Each segmentation dimension carries distinct cost structures and certification pathways that reshape supplier-buyer relationships across food, beverage, and cosmetic end-uses.
Product Type:
Clean-label premiums and deforestation-free sourcing mandates are compressing synthetic alternatives as buyers prioritize provenance documentation over unit cost.
- Natural Almond Extract:Derived from bitter almond kernels or apricot kernel substitutes through steam distillation or maceration, containing one to five percent benzaldehyde in ethanol or glycerin carriers. French artisanal confectionery producers and protected-origin patisserie supply chains in France absorb the highest volumes, driven by EU Green Deal farm-to-fork sustainability targets that mandate deforestation-free almond sourcing and reduced solvent residues.
- Artificial Almond Extract:Synthetic benzaldehyde formulations produced through chemical synthesis without agricultural feedstock dependencies. Industrial-scale baking operations in North America retain demand for this segment where FDA labeling transparency rules permit "natural and artificial flavor" declarations, though clean-label formulation mandates are eroding share in premium retail channels.
- Almond Oil:Cold-pressed or expeller-pressed oil fractions retaining lipid-soluble aromatic compounds and vitamin E content. Cosmetic formulators incorporate these fractions into skincare emulsions, opening non-food revenue channels with distinct REACH chemical registration requirements.
- Almond Powder:Spray-dried or freeze-dried extract formats offering extended shelf stability and reduced shipping weights. Industrial confectionery operations seeking format conversion opportunities represent emerging demand concentration.
Natural almond extract leads on scale; almond oil leads on momentum as personal care applications expand most quickly.
Application:
End-use specifications dictate benzaldehyde concentration thresholds, carrier base compatibility, and organic certification requirements that segment supplier capabilities.
- Baking:Clean-label retail bakeries across the Pacific Coast states now require batch-level provenance documentation from California almond cooperatives. Direct-procurement relationships are disintermediating traditional spice and flavor distributors.
- Confectionery:Premium chocolate manufacturers in Belgium and Switzerland adopt supercritical CO2 extraction for single-origin flavor profiles, eliminating ethanol carrier dependence. Cold-process methods preserve volatile benzaldehyde compounds for flavor intensity retention.
- Beverage:Flavored syrup and ready-to-drink formulations demand water-soluble extract formats with consistent dispersion characteristics. Beverage applications concentrate in North American and European markets with stringent solvent residue limits.
- Personal Care:Cosmetic manufacturers incorporate almond oil fractions into skincare emulsions, representing the steepest expansion trajectory as REACH chemical registration requirements tighten benzaldehyde concentration thresholds across EU member states.
Baking leads on scale; personal care leads on momentum.
Distribution Channel:
Channel selection determines traceability depth, certification handling costs, and minimum order quantities that filter supplier accessibility.
- Online Retail:E-commerce platforms enable small-batch organic extract access for artisanal producers and home bakers, with USDA organic and EU organic equivalency documentation digitized for verification.
- Supermarkets:Mass-market retail chains dominate liquid format volume through private-label and branded extract placement, concentrated in North American and European grocery consolidation.
- Specialty Stores:Gourmet food retailers and professional kitchen supply outlets serve premium patisserie and artisanal sourdough segments with certified organic and single-origin offerings.
- Direct Sales:California almond cooperatives connect small-scale growers to commercial buyers through fair-trade purchasing arrangements, compressing conventional distributor margins.
Supermarkets lead on scale; direct sales leads on momentum.
Form:
Physical format dictates extraction method compatibility, stability profiles, and downstream formulation integration requirements.
- Liquid:Ethanol or glycerin suspensions dominate distribution volume through supermarkets and direct sales channels, offering immediate dispersion in aqueous and lipid matrices.
- Powder:Spray-dried formats gain traction in industrial-scale confectionery operations seeking extended shelf stability and reduced shipping weights, with powder format industrial adoption representing an underpenetrated conversion opportunity.
- Capsules:Encapsulated extract formats target supplement and nutraceutical applications with controlled-release characteristics and dosing precision.
- Emulsion:Oil-in-water or water-in-oil dispersions serve cosmetic formulators requiring stable incorporation into skincare products without phase separation.
Liquid leads on scale; powder leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemist talent pools concentrate in California's Central Valley and France's Provence-Alpes-Côte d'Azur region, anchoring extraction expertise for volatile oil isolation protocols. These workforce clusters support the specialized steam distillation and maceration processes that define premium extract production.
United States
California almond cooperatives supply organic feedstock to Pacific Coast retail bakeries requiring batch-level provenance documentation. FDA allergen disclosure rules and USDA organic certification standards govern solvent limits and labeling transparency. Sacramento Valley processing facilities connect small-scale growers to commercial buyers through fair-trade purchasing arrangements.
France
Artisanal confectionery producers in Lyon and Grenoble absorb certified organic extract volumes for protected-origin patisserie applications. EU Green Deal farm-to-fork sustainability targets mandate deforestation-free almond sourcing verification. Grasse-based flavor houses accelerate natural certification programs to preempt EFSA flavoring substance evaluation displacements.
Germany
Industrial-scale baking operations in Bavaria retain synthetic benzaldehyde demand where clean-label premiums remain compressed. REACH chemical registration requirements create extended approval timelines for novel extraction solvent formulations. Munich metropolitan area distributors serve Central European confectionery manufacturers with blended natural-artificial portfolios.
Belgium
Premium chocolate manufacturers in Brussels and Liège adopt supercritical CO2 extraction for single-origin flavor profiles eliminating ethanol carrier dependence. EFSA benzaldehyde concentration thresholds tighten across EU member states, compelling enhanced toxicological dossier submissions. Walloon region processing facilities specialize in cold-process methods preserving volatile aromatic compounds.
India
Flavoring import volumes concentrate in Maharashtra and Gujarat food manufacturing corridors seeking Asia-Pacific market expansion pathways. FSSAI import clearance protocols for food flavorings add compliance layers for certified organic extract suppliers. Mumbai-based trading houses facilitate streamlined customs documentation for California-origin almond derivatives.
Almond Extract Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as integrated spice houses maintain captive almond sourcing against specialized extract boutiques outsourcing raw material procurement. The supplier base fragments across three strategic tiers: multinational flavor conglomerates with backward integration into California orchards, mid-scale cooperatives leveraging fair-trade certification premiums, and regional artisans emphasizing cold-process differentiation. Dominant competitive moves include direct-procurement relationship formation with retail bakery chains and supercritical CO2 technology licensing for premium confectionery segments.
Within the integrated conglomerate tier, McCormick & Company, Inc. and ADM occupy positions defined by supply chain control spanning orchard networks through retail distribution. Among specialized extract boutiques, Nielsen-Massey Vanillas, Inc. exemplifies the cold-process methodology archetype, while Frontier Co-op represents cooperative purchasing network structures connecting small-scale growers to commercial buyers. These named entities anchor competitive positioning without exhaustively mapping the supplier landscape.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Nielsen-Massey Vanillas, Inc. |
| Frontier Co-op |
| Queen Fine Foods |
| ADM |
| Royal Nut Company |
| LorAnn Oils |
| The Watkins Co. |
| Blue Diamond Growers |
| Others |
Supply Flow & Price Mechanics
California almond futures pricing cascades through extraction tiers, compressing margins for solvent-based processors while rewarding cold-process specialists with deforestation-free certification premiums that French patisserie buyers now mandate.
Pricing Analysis
Bundled certification-and-extract offerings command premiums over unbundled commodity grades. Three-tier pricing structure across organic-certified, conventional natural, and synthetic benzaldehyde levels reflects EU Green Deal traceability costs and FDA allergen disclosure compliance burdens. Cost compression in synthetic alternatives is intensifying because California drought cycles tighten bitter almond kernel availability. Industrial-scale baking operations in North America exhibit highest price sensitivity, while Belgian premium chocolate manufacturers absorb organic premiums without volume reduction.
Supply Chain Analysis
Flavor chemist shortages in California's Central Valley and France's Grasse region constrain supercritical CO2 extraction scale-up. Raw material sourcing draws from California orchards, Mediterranean growing regions, and apricot kernel substitutes from Central Asian suppliers. Single-source vulnerability concentrates in California's Sacramento Valley processing corridor, where cooperative networks dominate organic feedstock aggregation. Distribution runs through direct-procurement relationships between retail bakeries and grower cooperatives, disintermediating traditional spice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal farm-to-fork mandates and FDA labeling transparency rules accelerating clean-label extract demand across food and cosmetic applications.
For Market Incumbents: Anchor deforestation-free sourcing verification through captive California orchard partnerships or long-term cooperative supply agreements. Biotechnology-derived benzaldehyde alternatives threaten natural extract premiums within five years. Cold-process extraction capacity expansion in France's Provence-Alpes-Côte d'Azur region preserves volatile compound retention advantages against solvent-based competitors. For New Entrants and Emerging Players: Begin with powder format conversion opportunities in industrial confectionery operations seeking shelf stability and shipping weight reduction. Personal care emulsion formulators in EU member states represent the most penetrable white-space channel, with REACH registration timelines creating incumbent vulnerability. Supercritical CO2 technology licensing from Belgian processing facilities offers differentiated go-to-market positioning against conventional extraction incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale cooperatives leveraging fair-trade certification premiums and direct-procurement relationships with Pacific Coast retail bakeries. Long-term viability hinges on organic certification pipeline depth and flavor chemist talent retention. EFSA benzaldehyde concentration threshold revisions signal inflection risk for synthetic-dependent portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Sourcing Certification | EU Green Deal compliance enables protected-origin patisserie supply chain access in France. |
| Cold-Process Extraction Scale-Up | Volatile benzaldehyde retention satisfies Belgian premium chocolate manufacturer quality specifications. |
| Supercritical CO2 Technology Licensing | Eliminates ethanol carrier dependence for REACH-compliant cosmetic formulators in Germany. |
| Powder Format Manufacturing Investment | Extended shelf stability attracts industrial confectionery operations in Switzerland seeking logistics efficiency. |
| Direct-Procurement Platform Development | California almond cooperative networks bypass traditional distributor margins for North American retail bakeries. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with extraction facility managers, procurement leads at retail bakery chains, cosmetic formulators, and regulatory affairs specialists with secondary validation from FDA filings, EFSA flavoring substance evaluations, EU Green Deal documentation, and customs trade data. Bottom-up volume modeling triangulates against top-down market sizing across natural, artificial, oil, and powder product categories.
Granularity extends to product type, application, distribution channel, and form dimensions, with benzaldehyde concentration thresholds and carrier base specifications modeled at the formulation level. CAGRs derive from segment-level growth trajectories calibrated against almond kernel harvest volatility, regulatory approval timelines, and end-use substitution elasticities. California almond cooperative network expansion rates and supercritical CO2 adoption curves inform capacity-side projections.
Several conditions sit outside the modeled scope, including biotechnology-derived benzaldehyde commercialization timelines, climate-driven harvest collapse scenarios, and REACH solvent formulation reclassification events. Forecasts reflect assumptions about regulatory stability and organic certification equivalency maintenance. Material deviation in EFSA threshold revisions or FDA allergen disclosure enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Europe Cashew Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Middle East and Africa Hazelnut Market