
 Global Red Wine Market | 2026-2036
Global Red Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Red Wine Market Foresight
Argentina's Mendoza valley is narrowing the gap with traditional European output as new high-altitude plantings mature. Treasury Wine Estates leverages its Penfolds portfolio to dominate the luxury segment across Asia-Pacific markets. E. & J. Gallo Winery anchors North American volume through its mass-market brand architecture and distributor relationships. Constellation Brands, Inc. competes aggressively in the premium tier via Robert Mondavi and Prisoner Wine Company labels.
Red wine comprises fermented grape must with extended skin contact, yielding anthocyanin concentrations that produce its characteristic color spectrum and tannin structure; alcohol content typically ranges from twelve to fifteen percent by volume, serving both gastronomic pairing and standalone consumption purposes. Cabernet Sauvignon occupies the largest value share among product types due to its aging potential and established prestige pricing. Online retailers represent the fastest-expanding distribution channel as direct-to-consumer platforms bypass traditional three-tier systems. Glass bottles retain dominance in packaging type despite sustainability pressures, though bag-in-box formats capture volume in casual drinking occasions.
EU REACH and EFSA frameworks govern pesticide residue limits and oenological additive approvals across European production zones, while the USDA and TTB regulate American appellation integrity and label accuracy. China's SAMR enforces import standards that increasingly reference GB food safety protocols for foreign bottlers. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal as vineyard certification becomes a non-tariff barrier to premium market access.
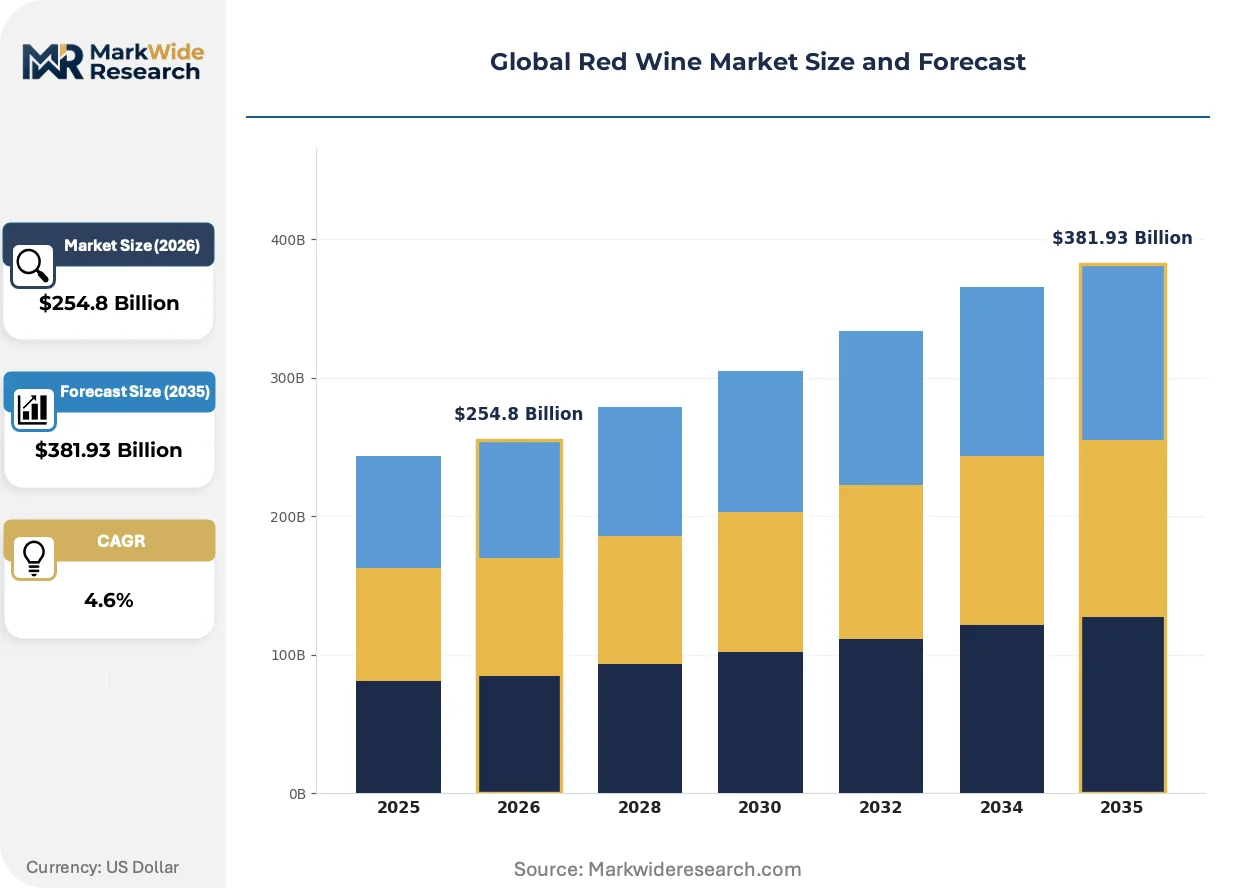
Market Dynamics
The EU Green Deal's carbon accounting mandates are forcing vineyard certification restructuring across multiple continents, compressing supply timelines and elevating compliance costs for exporters targeting European premium channels.
Growth Catalysts
- EU Green Deal certification mandates:Vineyard carbon-footprint verification creates competitive differentiation for exporters accessing European premium retail and foodservice channels, accelerating investment in regenerative viticulture.
- China tier-one city demand concentration:Shanghai and Beijing middle-class consumers demonstrate willingness to pay prestige pricing for established Old World appellations, pulling inventory allocation toward direct-import arrangements.
- High-altitude Mendoza plantings:Argentina's elevation-based viticulture delivers concentrated fruit profiles that compete with traditional European terroirs, expanding South American share in global fine-wine auctions.
Market Restraints
- Glass bottle input cost volatility:Energy-intensive container manufacturing exposes producers to natural gas price swings, compressing margins for mid-tier labels dependent on traditional packaging.
- Three-tier distribution concentration:US state-level wholesaler consolidation limits market access for smaller importers, forcing dependence on oligopolistic distributor networks.
- Climate-induced vintage variation:Erratic growing seasons in Bordeaux and Napa Valley create supply unpredictability, complicating inventory planning for large-format retail buyers.
Strategic Opportunities
- India urban premium channel underpenetration:Mumbai and Delhi luxury hotel and restaurant sectors lack dedicated wine program infrastructure, creating first-mover advantage for import specialists establishing direct relationships.
- Bag-in-box casual consumption:Alternative packaging formats bypass glass cost structures and appeal to younger demographic trial behavior in Scandinavian and Australian markets.
- Blockchain provenance verification:Distributed ledger technology converges with existing certification schemes to authenticate bottle origin, addressing counterfeiting concerns in Asian collector markets.
Industry Challenges
- Master viticulturist talent scarcity:Experienced vineyard managers capable of implementing precision agriculture and regenerative practices command premium compensation, constraining scaling for mid-size estates.
- Multi-jurisdiction label compliance:Divergent TTB, SAMR, and EFSA disclosure requirements force producers to maintain parallel packaging SKUs, elevating operational complexity.
- Oak barrel inventory financing:Extended aging protocols for premium tiers tie up working capital in cooperage assets, straining balance sheets during interest rate cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Red Wine Market |
| Market Size in 2026 | $254.8 Billion |
| Market Size in 2035 | $381.93 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabernet Sauvignon, Merlot, Pinot Noir, Syrah, Zinfandel, Malbec Distribution Channel: Specialty Stores, Online Retailers, Supermarkets, Restaurants, Wine Bars, Direct Sales Packaging Type: Glass Bottles, Tetra Packs, Bag in Box, Cans, Plastic Bottles Consumer Age Group: 21-30 Years, 31-45 Years, 46-60 Years, Above 60 Years |
| Companies Covered | Constellation Brands, Inc., Treasury Wine Estates, Accolade Wines, Pernod Ricard, Concha y Toro, The Wine Group, Castel Group, Davidve Campari-Milano S.p.A., E. & J. Gallo Winery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Red Wine Market Shifts & Advancements
Precision viticulture technologies and alternative packaging formats are compressing traditional production timelines while regulatory carbon accounting is rewriting certification hierarchies across export markets.
Sensor networks and drone-based canopy monitoring are digitizing vineyard management decisions for estates in Australia's Barossa Valley and Chile's Maipo Valley. Large-scale producers deploy these systems to optimize irrigation scheduling and disease pressure response, reducing input waste while compressing the gap between data collection and harvest intervention. This digitizing of field operations enables smaller technical teams to manage expanded hectarage without proportional labor additions.
REACH framework extensions under the EU Green Deal are mandating lifecycle carbon disclosure for agricultural imports entering European customs territory. Wine shipments now face documentation requirements covering vineyard energy use, transport refrigeration, and packaging embodied carbon, with non-compliant lots risking detention at port. Italian and Spanish cooperatives have responded by consolidating bottling at source rather than shipping bulk wine for European packaging, altering traditional Mediterranean supply configurations.
Direct-to-consumer platform adoption is fragmenting traditional wholesale dependence among boutique producers in Oregon's Willamette Valley and South Africa's Stellenbosch. These wineries bypass three-tier markups through subscription clubs and allocated release models, capturing margin previously absorbed by distributor networks. California's Napa Valley demonstrates the most advanced execution, with several hundred producers operating proprietary e-commerce fulfillment alongside traditional wholesale relationships.
Global Red Wine Market Segmentation
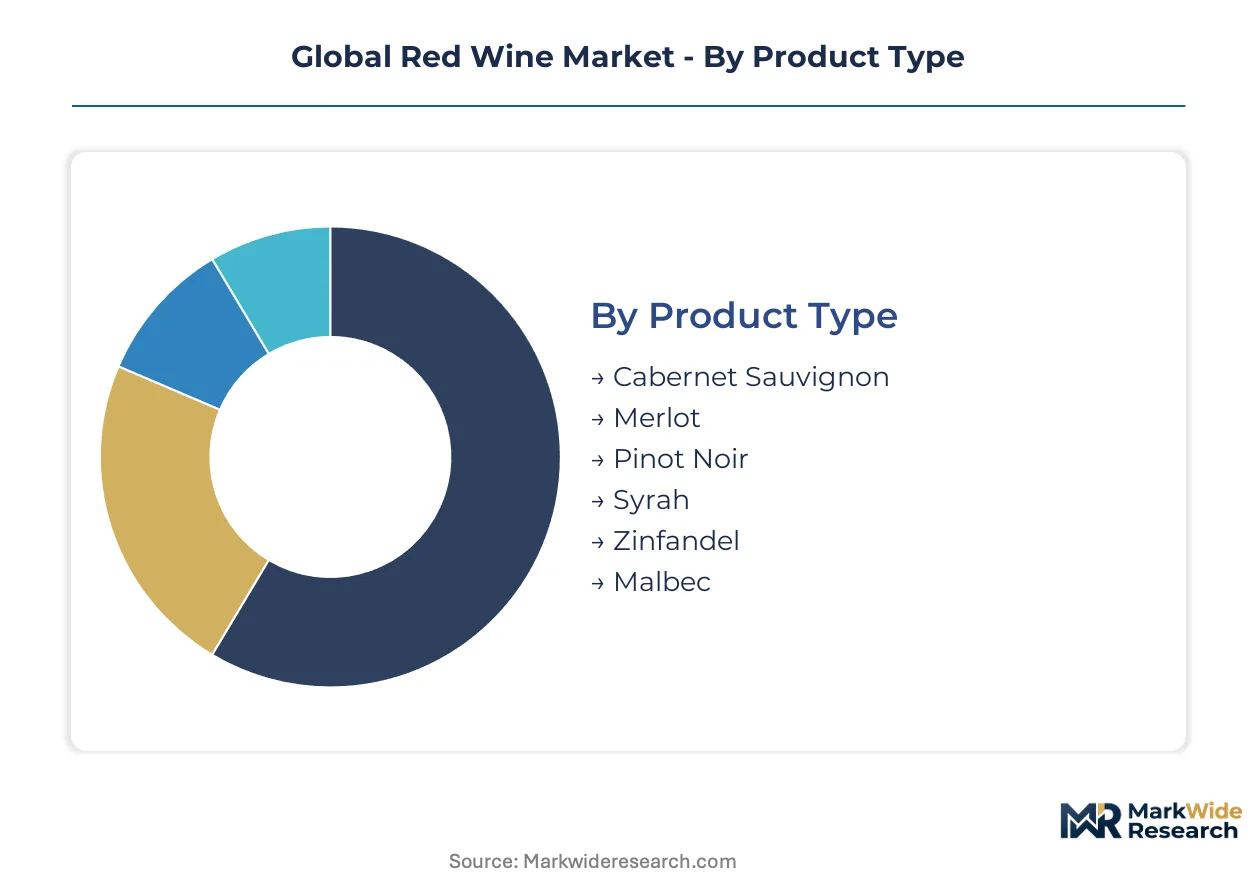
Red wine segmentation reveals distinct purchasing behaviors across varietal preferences, channel access, and generational cohorts. Producers align portfolio architecture with these divides to optimize margin capture and inventory velocity.
Product Type:
Mature varietals anchor volume while emerging alternatives reshape competitive positioning.
- Cabernet Sauvignon:Dense tannin structure and extended cellar aging potential command the highest prestige pricing in auction markets. Napa Valley and Bordeaux estates concentrate allocation toward Asian collector networks where provenance documentation drives purchase decisions.
- Pinot Noir:Thin-skinned berry morphology demands precise canopy management and cool-climate terroirs, limiting scalable supply. Willamette Valley and Burgundy producers leverage scarcity mechanics through allocated release calendars targeting enthusiast subscribers.
- Merlot:Soft tannin profile suits immediate consumption windows, dominating casual dining placements in North American casual chains.
- Syrah:Pepper-spice aromatic signature finds traction in Australian Barossa Valley export programs and Rhône cooperative bottlings.
- Zinfandel:High-sugar ripening capacity supports both dry table wine and fortified styles from California's Lodi AVA.
- Malbec:Mendoza high-altitude expressions compete on value positioning against established European benchmarks in UK and US retail.
Cabernet Sauvignon handles the majority of throughput; Pinot Noir is expanding most quickly on share.
Distribution Channel:
Channel selection dictates margin retention and brand positioning flexibility.
- Online Retailers:Direct-to-consumer platforms bypass wholesale markups and capture first-party purchase data. Treasury Wine Estates and Constellation Brands deploy proprietary e-commerce infrastructure to control pricing and release timing across Asia-Pacific markets.
- Restaurants:On-premise placements establish brand credentials through sommelier endorsement and food pairing narratives. Premium independents in Shanghai and New York drive allocation priority for limited-production labels.
- Specialty Stores:Curated assortments and staff expertise sustain discovery-oriented shopping in urban centers.
- Supermarkets:High-velocity SKUs with consistent supply profiles dominate shelf space in European and Australian grocery chains.
- Wine Bars:Flight-based sampling formats reduce consumer risk and accelerate trial of unfamiliar varietals.
- Direct Sales:Estate visitation and subscription clubs lock in recurring revenue for boutique producers in Stellenbosch and Willamette Valley.
Restaurants absorb the largest volume commitment; Online Retailers are climbing the fastest on share.
Packaging Type:
Format economics and sustainability pressures fragment container strategies.
- Glass Bottles:Embodied carbon from furnace operations and transport weight expose producers to EU Green Deal compliance costs. Italian cooperatives consolidate bottling at origin to reduce documentation burden under REACH carbon accounting extensions.
- Bag in Box:Reduced packaging mass and extended post-opening shelf life capture casual consumption occasions in Scandinavian markets. Younger demographics demonstrate trial willingness for format-agnostic quality propositions.
- Tetra Packs:Aseptic filling technology enables ambient distribution in emerging markets with limited cold chain infrastructure.
- Cans:Single-serve portability aligns with outdoor recreation and festival consumption patterns in Australia and North America.
- Plastic Bottles:Lightweight logistics economics sustain presence in price-sensitive mass retail channels despite recycling limitations.
Glass Bottles retain dominant throughput; Bag in Box is gaining share fastest.
Consumer Age Group:
Generational cohorts exhibit divergent discovery behaviors and price elasticity.
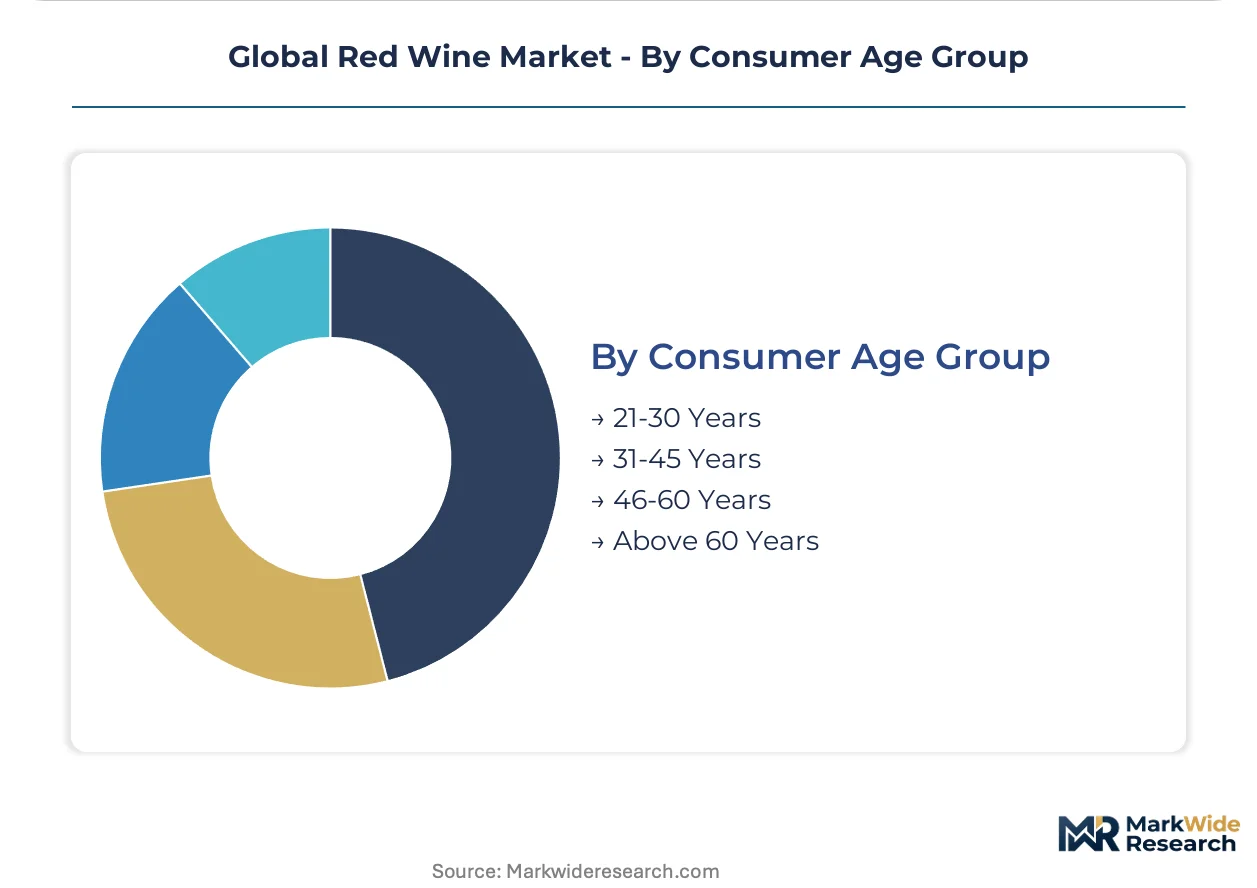
- 31-45 Years:Peak earning trajectory coincides with cellar-building ambitions and subscription club participation. This cohort drives premiumization trends through allocated purchase programs and direct-import relationships with European estates.
- 21-30 Years:Digital-native discovery patterns favor influencer recommendations and alternative packaging trial. Social commerce platforms in China's tier-one cities convert short-form content into immediate purchase behavior.
- 46-60 Years:Established palate preferences and auction market participation concentrate spending on proven provenance and vintage-dated collections.
- Above 60 Years:Brand loyalty and traditional retail habits sustain volume for established labels in mature markets.
31-45 Years commands the largest spending base; 21-30 Years shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA pesticide residue frameworks and EU Green Deal carbon accounting reshape vineyard certification across European export channels. Treasury Wine Estates and Constellation Brands redirect allocation toward Asian collector networks as China's SAMR tightens import documentation. Argentina's Mendoza high-altitude plantings mature into fine-wine auction viability.
United States
Napa Valley and Sonoma County estates drive prestige pricing through allocated release calendars targeting 31-45 year-old cellar builders. TTB label accuracy enforcement and appellation integrity rules elevate compliance costs for multi-state distributors. Willamette Valley producers deploy direct-to-consumer platforms to bypass consolidated three-tier networks.
France
Bordeaux and Burgundy châteaux concentrate supply toward Shanghai and Beijing import specialists willing to pay provenance premiums. REACH framework extensions mandate lifecycle carbon disclosure for vineyard energy use and transport refrigeration. Champagne cooperatives consolidate bottling at origin to satisfy documentation requirements under EU Green Deal customs protocols.
Italy
Tuscan and Piedmont estates leverage DOCG certification hierarchies to differentiate in UK and German retail channels. EFSA oenological additive approvals govern enological practice across Chianti Classico and Barolo production zones. Veneto cooperatives shift bulk wine bottling from Rotterdam to Italian ports to reduce REACH carbon accounting exposure.
China
Shanghai and Beijing middle-class consumers develop sophisticated palates favoring Old World appellations over domestic labels. SAMR GB food safety protocols enforce testing for foreign bottlers entering tier-one city distribution. Ningxia autonomous region vineyards experiment with high-altitude Cabernet Sauvignon plantings modeled on Mendoza techniques.
Argentina
Mendoza valley elevation-based viticulture delivers concentrated fruit profiles competing with European benchmarks in UK and US retail. National agricultural export programs support vineyard modernization and precision irrigation infrastructure. Uco Valley sub-regions attract investment as new plantings at 1,200+ meters mature into fine-wine auction viability.
Global Red Wine Market Competitive Landscape
Luxury-portfolio conglomerates and mass-market volume producers split the market into distinct competitive spheres. Treasury Wine Estates and Constellation Brands anchor the premium tier through acquired heritage labels and direct-import relationships with Asian distributors. E. & J. Gallo Winery occupies the volume-driven end through distributor network density and private-label supply contracts. Strategic moves concentrate on portfolio diversification into alternative packaging formats and geographic expansion through distributor acquisition in underpenetrated markets.
Within the luxury-portfolio tier, Treasury Wine Estates and Constellation Brands exemplify archetype execution through heritage label aggregation and Asia-Pacific allocation priority. E. & J. Gallo Winery represents the scale-driven mass-market archetype with North American distributor relationship density. Accolade Wines and Pernod Ricard occupy intermediate positions bridging premium credibility with volume accessibility. Castel Group and Concha y Toro anchor European and South American production gravity respectively, each representing regional supply-base consolidation. The Wine Group exemplifies private-label and alternative-format specialization targeting casual consumption occasions.
| Leading Market Players |
|---|
| Constellation Brands, Inc. |
| Treasury Wine Estates |
| Accolade Wines |
| Pernod Ricard |
| Concha y Toro |
| The Wine Group |
| Castel Group |
| Davidve Campari-Milano S.p.A. |
| E. & J. Gallo Winery |
| Others |
Supply & Pricing Matrix
Atlantic container freight corridors linking Bordeaux and Shanghai dictate cost structures that compress margins for mid-tier exporters while amplifying price spreads between bulk-shipped and estate-bottled allocations. These logistics dynamics concentrate pricing power with producers controlling bottling-at-source infrastructure, forcing supply chain reconfiguration toward Mediterranean port consolidation.
Pricing Analysis
Geographic price spreads between Napa Valley auction releases and Mendoza valley retail offerings now exceed three-to-one multiples at equivalent quality tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with EU Green Deal certification grades and provenance documentation serving as primary price differentiation drivers. Pricing pressure stems from glass bottle energy cost volatility, which erodes margins for traditional-format dependent labels. Casual consumption segments exhibit highest price sensitivity, while Asian collector networks demonstrate inelastic demand for documented heritage estates.
Supply Chain Analysis
Export-control regimes under EU REACH framework extensions restrict oenological additive flows and mandate carbon disclosure documentation for vineyard inputs entering European customs territory. Supply concentrates in France, Italy, and Argentina, with these origins drawing from oak cooperage in France's Limousin forest, glass furnace operations in Northern Italy, and precision irrigation hardware from Israeli manufacturers. Single-source vulnerability in master viticulturist talent constrains scaling for mid-size estates. Distribution runs through consolidated three-tier wholesaler networks in the United States and direct-import specialist channels in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across generational cohorts and packaging format preferences creates niche entry points for specialists targeting underserved demand segments with differentiated positioning.
For Market Incumbents: Harden allocation control through backward integration into estate bottling infrastructure, eliminating carbon-accounting exposure from Rotterdam bulk-wine handling. Deepen direct-to-consumer platform investment to bypass consolidated three-tier markups threatening margin retention. Priority lever rests on regenerative viticulture certification pre-empting EU Green Deal compliance deadlines. For New Entrants and Emerging Players: India's Mumbai and Delhi luxury hospitality corridors offer first-mover positioning absent dedicated wine program infrastructure. Bag-in-box format penetration in Scandinavian casual consumption presents white-space trial conversion. Blockchain provenance verification serves as differentiated go-to-market anchor for Asian collector market entry. For Investors and Strategic Acquirers: EU Green Deal regulatory inflection reshapes the acquisition landscape toward certified-regenerative estate portfolios with documented carbon accounting. Long-term viability favors vertically integrated producers controlling bottling-at-source capability. Signal to monitor: SAMR enforcement intensity against non-compliant foreign bottlers in Shanghai and Beijing distribution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Viticulture Certification | EU Green Deal compliance creates non-tariff barrier to premium European retail and foodservice channels. |
| Bottling-at-Source Consolidation | Mediterranean cooperatives reduce REACH carbon accounting exposure by shifting packaging from Rotterdam to Italian ports. |
| Direct-to-Consumer Platform Launch | Willamette Valley and Stellenbosch producers bypass three-tier markups through subscription clubs and allocated releases. |
| Alternative Packaging Format Expansion | Bag-in-box and can formats capture younger demographic trial in Scandinavian and Australian casual consumption occasions. |
| Blockchain Provenance Verification | Distributed ledger technology addresses counterfeiting concerns in Shanghai and Beijing collector markets. |
Research Methodology
Desk research of trade customs databases, vineyard registry filings, and EU regulatory gazettes preceded structured interviews with estate managers, import specialists, sommelier program directors, and cooperage procurement leads. Primary fieldwork across Mendoza, Napa Valley, and Bordeaux production zones combined with secondary validation from EFSA guidance documents and SAMR import protocol releases. Bottom-up hectarage and yield estimates triangulated against top-down value-chain modeling.
Assumptions held EU Green Deal enforcement intensity and China tier-one city income trajectories within observed patterns, while varying climate-induced vintage variation and glass input cost volatility across scenario branches. Segmentation modeling spanned varietal type, distribution channel, packaging format, and consumer age cohort dimensions throughout the forecast period. CAGRs derived from price-volume elasticity functions calibrated to auction market clearing data and retail scanner panels.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by mid-size Argentine estates would shift competitive outcomes. Material shifts in SAMR enforcement protocols or EU carbon border adjustment mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Distilled Spirits Market