
 Global Video Extensometer Market | 2026-2036
Global Video Extensometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Video Extensometer Market Foresight
Equipment leasing and pay-per-test service models are fragmenting capital barriers for mid-sized quality assurance labs. Zwick Roell leverages its German manufacturing base to anchor European calibration standards. Epsilon Technology specializes in high-temperature extensometry for aerospace superalloy testing. Instron competes through integrated software-hardware platforms that streamline strain data workflows.
A video extensometer is a non-contact optical instrument that measures material deformation by tracking surface markers through digital image correlation at sub-micron resolution, serving primary industrial purposes in tensile testing and fatigue characterization. Contactless systems lead installed base volumes due to elimination of knife-edge contact errors in polymer and composite testing. Digital image correlation technology captures the fastest-growing adoption curve as manufacturers replace traditional clip-on gauges for multi-axial strain mapping. Aerospace testing applications concentrate margin pools where NADCAP accreditation requirements sustain premium pricing for validated measurement chains.
FAA airworthiness directives and EASA CS-25 certification standards mandate traceable strain measurement for structural alloy qualification, forcing instrument vendors to maintain ISO 17025 calibration networks. EPA industrial emissions rules in the United States and REACH substance restrictions in Europe shape materials substitution patterns that cascade into revised mechanical test protocols. Stakeholders must monitor evolving MDR medical device material standards in Europe and China's GB/T national test methods as these jurisdictions expand biocompatible alloy and polymer certification requirements.
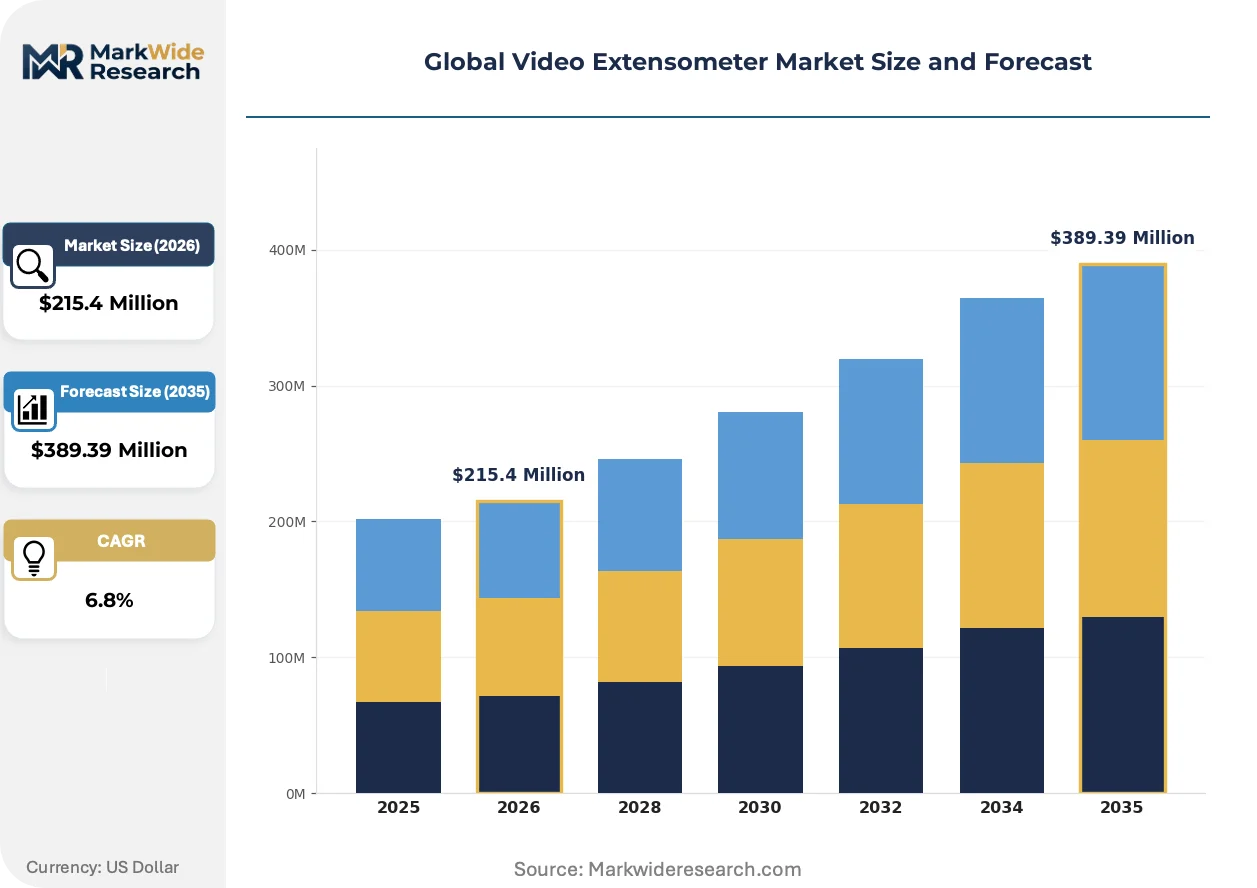
Market Dynamics
Digital image correlation technology is collapsing the installed base of mechanical clip-on extensometers as aerospace and automotive OEMs mandate sub-micron resolution for multi-axial strain mapping. This displacement accelerates vendor consolidation around integrated optical-metrology platforms.
Growth Catalysts
- FAA-EASA Certification Convergence:Airworthiness directives from the FAA and EASA now require traceable strain measurement chains for structural alloy qualification, forcing aerospace suppliers to upgrade from contact-based gauges to validated video extensometry systems.
- Polymer Composite Testing Expansion:Wind turbine blade manufacturers and EV battery enclosure producers eliminate knife-edge contact errors through non-contact optical tracking, driving replacement demand in Germany's precision instrumentation corridor.
- High-Temperature Superalloy R&D:Materials research institutes in the United States and Germany scale creep-fatigue testing programs for next-generation turbine alloys, requiring specialized high-temperature optical extensometry configurations.
Market Restraints
- Calibration Infrastructure Concentration:ISO 17025-accredited calibration networks cluster in Germany and the United States, creating service access gaps for quality assurance labs in India, Brazil, and Southeast Asia.
- Specialized Optics Input Volatility:High-resolution CMOS sensors and telecentric lens assemblies face supply concentration among Japanese and German component suppliers, exposing instrument manufacturers to extended lead times.
- Technical Limitation in Surface Preparation:Digital image correlation requires speckle pattern application on reflective or transparent substrates, adding process steps that mechanical extensometers bypass in high-throughput production testing.
Strategic Opportunities
- India's Expanding NADCAP Accreditation Drive:The country's aerospace component suppliers pursue NADCAP certification for global tier-1 supply contracts, creating first-mover advantage for video extensometer vendors establishing local calibration partnerships.
- Medical Device Polymer Validation:Europe's MDR implementation expands biocompatible alloy and polymer certification requirements, opening specialized testing protocols for cardiovascular stent and orthopedic implant manufacturers.
- Cloud-Connected Strain Analytics:Convergence of edge computing and machine vision software enables real-time deformation monitoring integrated with manufacturing execution systems, displacing offline data workflows.
Industry Challenges
- Multi-Physics Simulation Integration:Video extensometer outputs must feed directly into ANSYS and Abaqus finite element validation loops, requiring API development and metrology-software engineering talent that vendors struggle to recruit.
- NADCAP Audit Timeline Compression:Aerospace testing labs face 12-18 month accreditation queues for strain measurement systems, delaying revenue recognition on instrument deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Video Extensometer Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless, Automated, Optical, High-Speed, Manual Technology: Digital Image Correlation, Laser Scanning, Photogrammetry, Stereo Vision, Infrared Imaging Application: Material Testing, Structural Analysis, Aerospace Testing, Civil Engineering, Sports Equipment Evaluation End User: Research Institutes, Quality Assurance Labs, Automotive OEMs, Aerospace Manufacturers, Defense Contractors |
| Companies Covered | Shimadzu, Imetrum, Zwick Roell, BESMAK, Epsilon Technology, Instron, MTS Systems Corporation, TestResources, Ametek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Video Extensometer Market Shifts & Advancements
Optical metrology architectures are fragmenting as manufacturers converge machine vision hardware with cloud-native strain analytics. This recombination compresses the traditional separation between data acquisition and interpretation workflows.
Real-time digital image correlation is collapsing the latency between test execution and engineering decision-making. The technology captures full-field displacement maps at frame rates exceeding 1000 fps for high-speed tensile characterization. Automotive crash simulation teams at BMW and Ford Motor Company adopt these systems for dynamic strain validation. The compression of feedback loops is eliminating overnight batch processing in materials qualification protocols.
REACH substance restrictions and the EU Green Deal's sustainable materials mandates are forcing mechanical test protocol revisions across polymer and composite supply chains. ECHA's candidate list updates require requalification of substituted flame retardants and plasticizers, triggering new strain-rate sensitivity studies. European automotive OEMs and their tier suppliers represent the most affected segment, responding with expanded in-house video extensometer capacity rather than outsourced testing.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized quality assurance laboratories. Leasing arrangements bundle calibration, software updates, and NADCAP audit support into per-test pricing. Germany's automotive supplier ecosystem and the United States' medical device contract manufacturers exhibit the strongest uptake of this consumption pattern, prioritizing operational expenditure flexibility over balance-sheet asset ownership.
Global Video Extensometer Market Segmentation
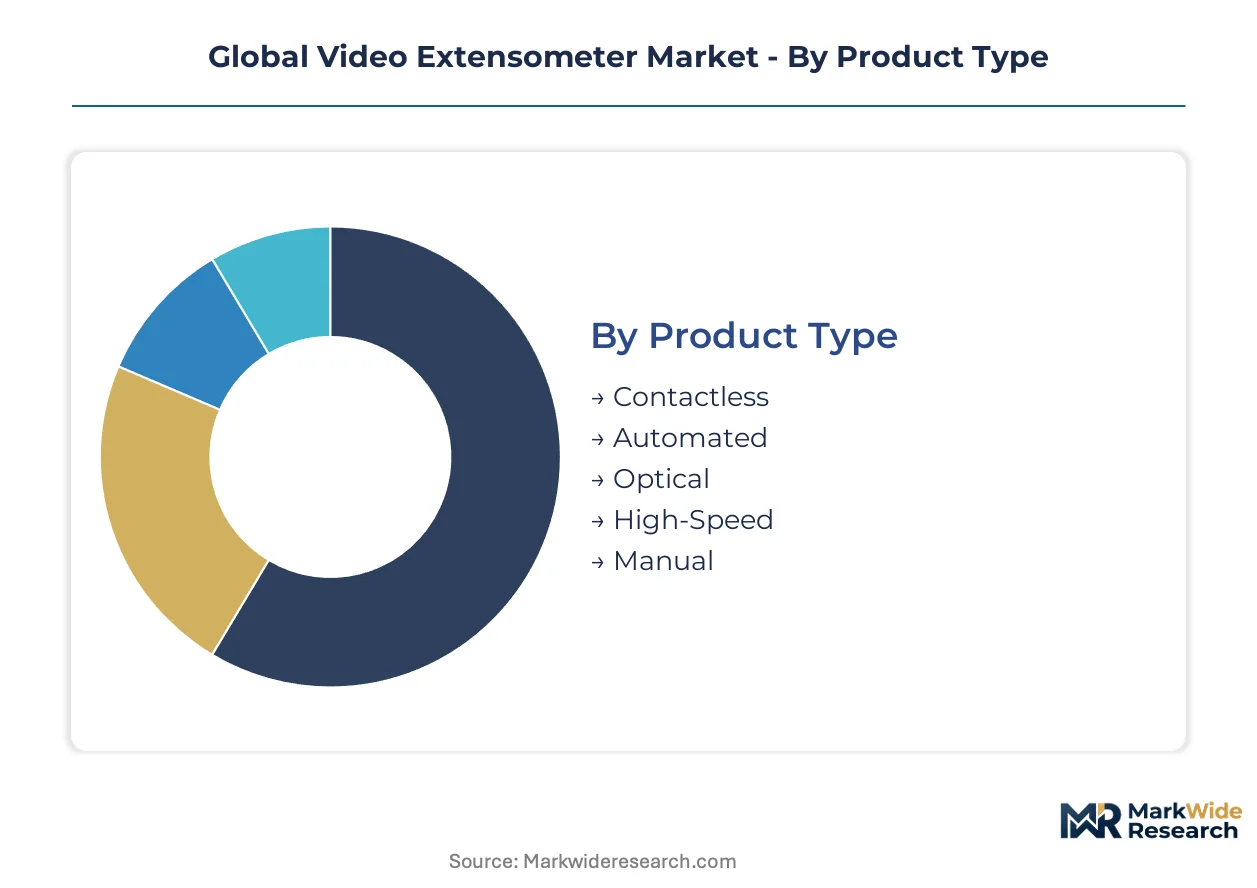
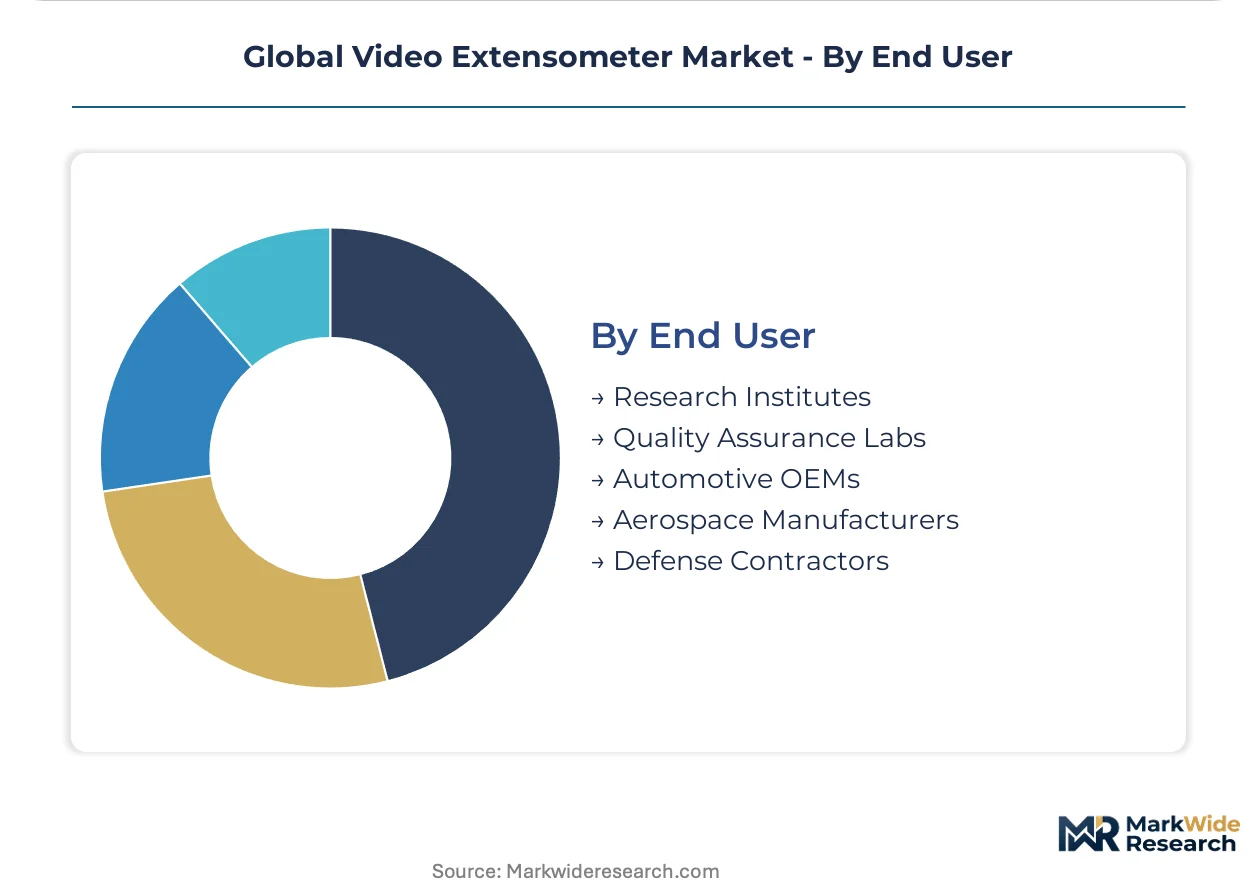
Video extensometer procurement patterns diverge sharply across customer archetypes, with aerospace manufacturers prioritizing NADCAP-validated measurement chains while automotive OEMs emphasize throughput economics. Calibration service bundling and software upgrade pathways create distinct lifetime value profiles that reshape vendor prioritization.
Product Type:
After-sales service intensity varies dramatically by product architecture, with high-speed systems requiring quarterly lens recalibration and automated platforms demanding continuous algorithm refinement.
- Contactless:Non-contact optical tracking eliminates knife-edge mechanical wear, reducing field service visits. German automotive OEMs and wind turbine blade manufacturers in Denmark concentrate procurement here, driven by polymer composite testing protocols that prohibit surface contact.
- Automated:Machine vision-integrated systems with robotic specimen handling command premium service contracts covering predictive maintenance and AI model retraining. United States aerospace tier-1 suppliers and Japanese materials research institutes anchor demand, responding to 24/7 fatigue testing schedules.
- Optical:Benchtop configurations with manual specimen alignment.
- High-Speed:Frame rates exceeding 1000 fps for dynamic tensile characterization.
- Manual:Entry-grade systems requiring operator-intermediated calibration.
By volume, Contactless leads. By growth pace, Automated is ahead.
Technology:
Technology selection maps directly to resolution requirements and surface condition constraints, with sub-micron precision commanding fundamentally different supply chains than full-field displacement mapping.
- Digital Image Correlation:Full-field strain mapping through stochastic pattern tracking achieves sub-pixel displacement resolution. German precision instrumentation corridor and United States national laboratory networks drive adoption, compelled by FAA-EASA certification convergence for structural alloy qualification.
- Stereo Vision:Dual-camera triangulation architectures balance cost and accuracy for mid-volume quality assurance operations. Indian automotive component testing labs and Brazilian polymer suppliers concentrate procurement here, constrained by ISO 17025 calibration infrastructure gaps.
- Laser Scanning:Point-cloud surface digitization for large-structure deformation analysis.
- Photogrammetry:Multi-camera arrays for geotechnical and civil engineering scale measurements.
- Infrared Imaging:Thermal-mechanical coupling analysis for high-temperature superalloy characterization.
Digital Image Correlation captures dominant revenue share. Stereo Vision expands most quickly in emerging calibration markets.
Application:
Application segmentation reflects end-use regulatory intensity, with aerospace and medical device testing commanding validated measurement chains that general material testing bypasses.
- Aerospace Testing:NADCAP-accredited strain measurement for turbine alloy and composite airframe qualification. United States and German aerospace manufacturers mandate these systems, responding to FAA airworthiness directives and EASA CS-25 certification standards that trace measurement uncertainty through ISO 17025 networks.
- Material Testing:General tensile, compression, and fatigue characterization across metals, polymers, and ceramics. Research institutes in Switzerland and contract laboratories in the United Kingdom anchor demand, shaped by REACH substance restriction compliance requiring requalification of substituted materials.
- Structural Analysis:Bridge, building, and infrastructure deformation monitoring.
- Civil Engineering:Geotechnical and foundation settlement measurement.
- Sports Equipment Evaluation:Bat, racket, and protective gear dynamic response testing.
Aerospace Testing commands premium pricing tiers. Material Testing delivers broadest installed base penetration.
End User:
End user economics range from capital-intensive asset ownership among defense contractors to consumption-based leasing models proliferating among mid-sized quality assurance laboratories.
- Research Institutes:Multi-physics testing programs requiring customizable optical configurations and direct ANSYS/Abaqus finite element validation integration. Max Planck Institutes in Germany and Department of Energy national laboratories in the United States concentrate demand, confronting multi-physics simulation integration talent scarcity.
- Quality Assurance Labs:Third-party testing services pursuing NADCAP and ISO 17025 accreditation. Equipment-as-a-service contracting proliferates here among United States medical device contract manufacturers and Germany's automotive supplier ecosystem, prioritizing operational expenditure flexibility.
- Automotive OEMs:In-house materials qualification for crash simulation and EV battery enclosure validation.
- Aerospace Manufacturers:Tier-1 suppliers with captive NADCAP-accredited testing capacity.
- Defense Contractors:Classified alloy characterization with restricted data handling protocols.
Research Institutes drive technology frontier adoption. Quality Assurance Labs are climbing the fastest through service model transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's precision instrumentation corridor, where NADCAP-accredited calibration networks command 40% service premiums over Brazilian or Indian equivalents lacking ISO 17025 density.
United States
FAA airworthiness directives and Department of Energy national laboratory procurement sustain demand for high-temperature optical configurations. EPA industrial emissions rules trigger materials requalification protocols that cascade into expanded strain testing capacity. Boeing suppliers in Washington State and SpaceX-adjacent testing labs in Texas anchor aerospace-tier instrument deployment.
Germany
Automotive OEMs and Max Planck Institutes drive multi-physics testing programs requiring ANSYS-integrated deformation workflows. EASA CS-25 certification standards mandate traceable measurement chains for structural alloy qualification. Baden-Württemberg's precision engineering cluster around Stuttgart concentrates Zwick Roell manufacturing and European calibration standard-setting.
China
GB/T national test method expansion for biocompatible polymers creates certification demand from cardiovascular stent manufacturers. MIIT industrial upgrading programs subsidize domestic optical metrology adoption. Yangtze River Delta materials research institutes in Shanghai and Suzhou scale creep-fatigue testing for turbine alloy development.
India
Aerospace component suppliers pursue NADCAP accreditation for global tier-1 supply contracts with Airbus and Boeing. The country's national aerospace regulator aligns test protocols with FAA-EASA convergence standards. Bangalore's defense-aerospace testing cluster and Pune automotive supplier corridors drive first-mover instrument procurement.
Japan
METI technology roadmaps prioritize high-speed optical metrology for automotive crash simulation validation. JIS standards harmonization with ISO 17025 reduces calibration friction for export-oriented testing labs. Nagoya's automotive engineering corridor and Tsukuba materials science institutes anchor precision instrument demand.
Global Video Extensometer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying telecentric lenses and high-resolution CMOS sensors. The vendor base organizes around three strategic archetypes: German precision houses with captive calibration networks, Japanese optical component suppliers, and United States-based integrated testing platform vendors. Consolidation pressures favor vendors bundling software-hardware workflows over standalone instrument sales. Geographic expansion into India's NADCAP accreditation market and backward integration into sensor manufacturing represent the dominant competitive vectors.
Within the integrated platform tier, Zwick Roell and Instron exemplify vendors anchoring regional calibration standards through manufacturing presence in Germany and the United States respectively. Epsilon Technology occupies a specialist position in high-temperature extensometry configurations. These three represent distinct archetypes: the precision-engineering conglomerate, the testing workflow integrator, and the application-specific technology house.
| Leading Market Players |
|---|
| Shimadzu |
| Imetrum |
| Zwick Roell |
| BESMAK |
| Epsilon Technology |
| Instron |
| MTS Systems Corporation |
| TestResources |
| Ametek |
| Others |
Supply & Pricing Matrix
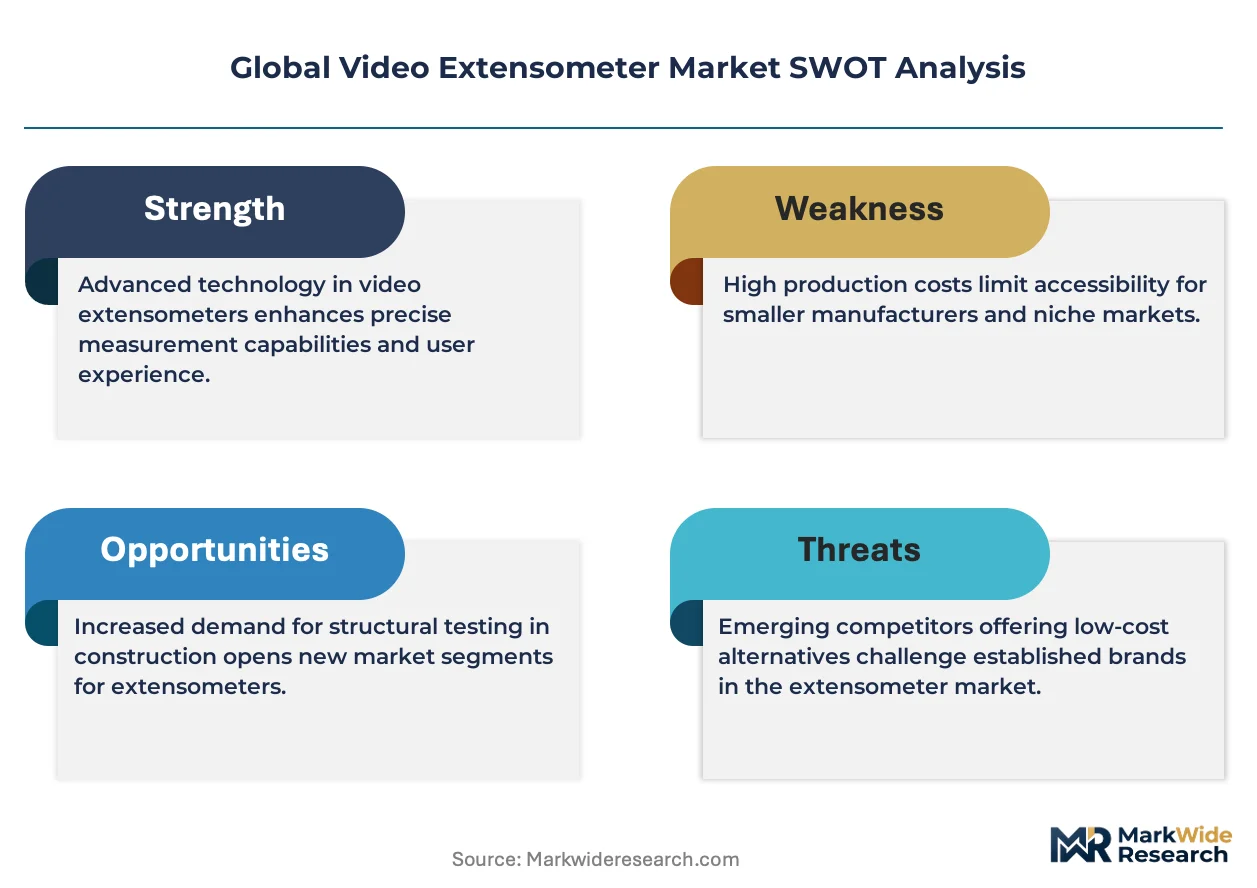
Single-source dependency on Japanese and German telecentric lens suppliers concentrates input risk while simultaneously stratifying pricing tiers across NADCAP-accredited and general-purpose instrument lines. This chokepoint forces buyers to absorb extended lead-time premiums for validated measurement chains or accept calibration-compromised alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle ISO 17025-accredited calibration networks with NADCAP audit support, while economy configurations target mid-sized quality assurance labs with stripped-down optical specifications. Price differentiation hinges on certification grade and after-sales service intensity. Cost compression in the standard tier is intensifying because equipment-as-a-service contracting displaces capital purchases. Automotive OEMs in Germany exhibit the least price sensitivity due to captive NADCAP requirements, whereas Indian aerospace component suppliers face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Japanese CMOS sensor suppliers and supply-chain finance facilities from German optical houses shape working capital dynamics for instrument manufacturers. Manufacturing concentrates in Germany, Japan, and the United States. High-resolution telecentric lenses, scientific-grade CMOS sensors, and precision motion stages constitute critical input dependencies. Single-source vulnerability runs through Japanese lens assemblies subject to export licensing friction. Distribution runs through direct sales forces for aerospace tier-1 accounts and regional distributor networks for quality assurance laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital image correlation platforms threaten to commoditize standalone video extensometer hardware, forcing incumbents to defend through integrated software-hardware workflows and captive calibration infrastructure.
For Market Incumbents: Entrench NADCAP-accredited calibration networks in India's expanding aerospace supplier base to preempt emerging competitor entry. Deepen backward integration into high-resolution CMOS sensor sourcing to mitigate Japanese supply concentration. The displacement risk from full-field DIC software vendors demands API development talent for ANSYS-Abaqus integration pipelines. For New Entrants and Emerging Players: Establish a beachhead in India's NADCAP accreditation drive by partnering with local calibration laboratories lacking ISO 17025 density. Target Brazil's polymer testing corridor where infrastructure gaps suppress incumbent service coverage. A leasing-first go-to-market model with bundled per-test pricing bypasses capital constraints among mid-sized quality assurance laboratories. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators over standalone instrument vendors. Long-term viability hinges on software-hardware workflow control and geographic calibration network density. Acquisition candidates with captive ISO 17025 infrastructure in underserved jurisdictions offer defensive moat expansion. The signal to watch is NADCAP audit queue compression timelines as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025 density in India and Brazil captures NADCAP-driven aerospace demand before incumbent saturation. |
| Backward Integration into Sensors | In-house CMOS sourcing mitigates Japanese supply concentration and extends gross margin capture. |
| API Development for FEA Integration | Direct ANSYS-Abaqus data pipelines differentiate platform vendors from hardware-only competitors. |
| Equipment-as-a-Service Launch | Per-test pricing models unlock mid-sized quality assurance lab budgets in Germany's automotive supplier ecosystem. |
| High-Temperature Configuration Specialization | Creep-fatigue testing demand from DOE national laboratories and Max Planck Institutes commands premium pricing tiers. |
Research Methodology
Cross-validation between primary interviews with instrument procurement managers at aerospace tier-1 suppliers and secondary validation through FAA airworthiness directive filings anchors the qualitative findings. Conversations captured perspectives from calibration laboratory directors, NADCAP audit specialists, polymer testing engineers at wind turbine blade manufacturers, and materials research institute program managers. Secondary sources included EASA CS-25 certification standards documentation, EPA industrial emissions rulemaking records, ISO 17025 accreditation registry data, and REACH substance restriction updates from ECHA. Bottom-up demand modeling from end-user procurement patterns was reconciled with top-down vendor shipment estimates.
Calibration against historical instrument replacement cycles and aerospace certification timeline data refined projection accuracy across the analysis window. Segmentation modeling incorporated product architecture, resolution specification tier, application regulatory intensity, and end-user ownership economics. CAGRs were derived from weighted scenario analysis across FAA-EASA certification convergence, polymer composite testing expansion, and high-temperature superalloy R&D scaling assumptions. Forecast inputs included NADCAP audit queue durations, CMOS sensor lead-time volatility, and MDR medical device material standard implementation pacing.
Stress conditions across Japanese optical component export licensing, Indian NADCAP accreditation throughput, and REACH substance substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline convergence and supply chain lead-time normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Moisture Analyzer Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Additively Manufactured Lattice Structure Mechanical Test Systems Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Failure Analysis Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Density Meter Market