
 Opportunities in South East Asia Travel and Tourism Market | 2026-2036
Opportunities in South East Asia Travel and Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Opportunities in South East Asia Travel and Tourism Market Analytics
Wellness retreat bookings from European and North American visitors is realigning where hospitality groups deploy new inventory across Indonesia and Thailand. Traveloka leverages its super-app architecture to dominate domestic Indonesian route bundling. AirAsia Group anchors low-cost carrier capacity across ASEAN secondary cities. Singapore Airlines sustains premium yield through cabin product upgrades and KrisFlyer loyalty depth.
Opportunities in South East Asia travel and tourism encompass cross-border passenger movement, hospitality services, destination experiences, and digital booking infrastructure spanning ten ASEAN member states with tropical climate assets, cultural heritage sites, and marine biodiversity corridors as core inventory. The sector functions as an employment-intensive economic engine where foreign exchange inflows from visitor spending offset trade deficits in import-dependent economies. Online Travel Agents capture disproportionate booking flow as mobile penetration exceeds desktop usage across the region. Tour Operations targeting diving, trekking, and culinary immersion command premium pricing relative to standardized packages. Budget tier accommodation through hostel networks and guesthouse aggregators absorbs volume from young solo travelers and intra-ASEAN labor mobility.
Thailand's Ministry of Tourism and Sports, Indonesia's Ministry of Tourism and Creative Economy, and Singapore's STB shape operator licensing, environmental carrying capacity limits, and tax incentive structures for hospitality investment. ASEAN Mutual Recognition Arrangements on tourism professional standards reduce labor friction for cross-border hospitality staffing. Stakeholders must monitor how carbon border adjustment mechanisms in origin markets reshape long-haul aviation economics and destination choice hierarchies.
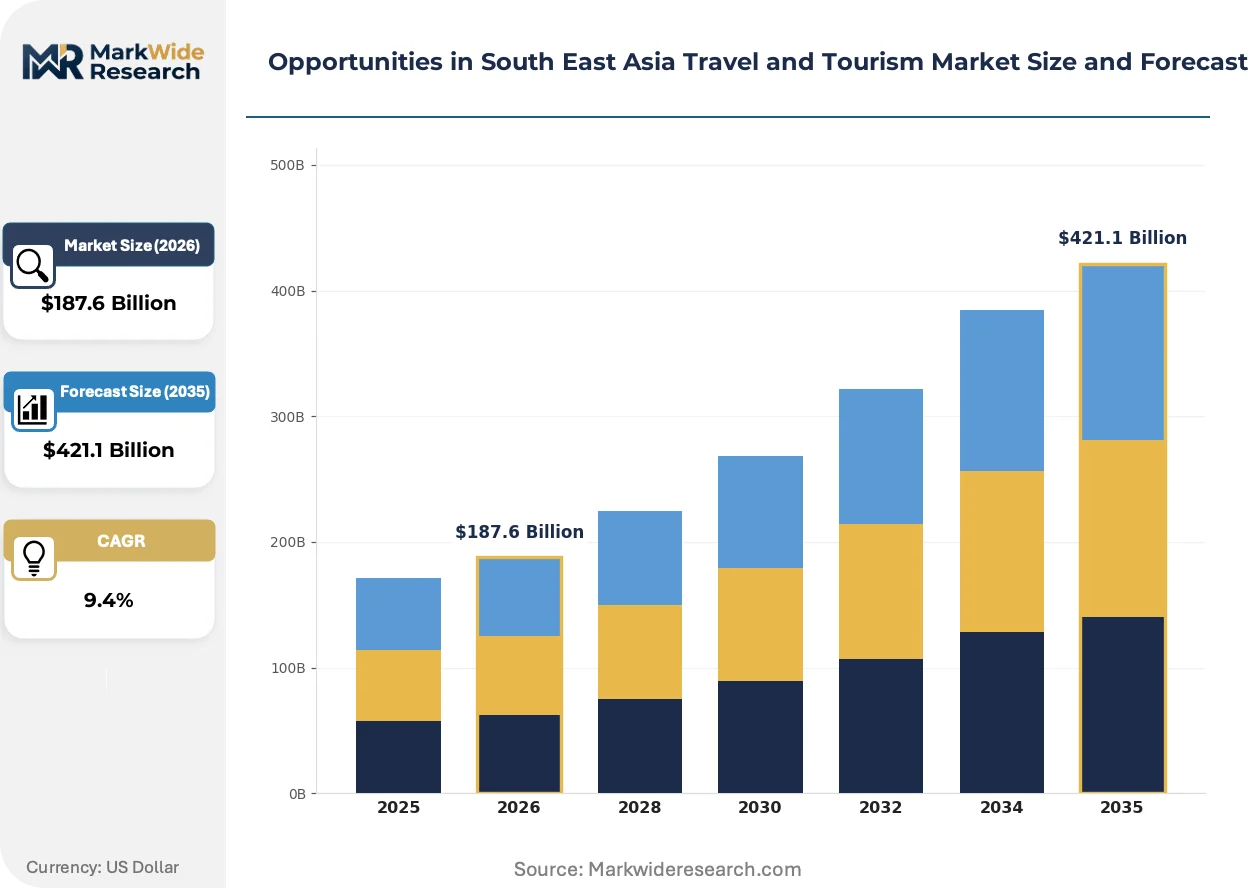
Market Dynamics
Digital booking infrastructure and mobile-first payment rails are compressing traditional travel agency intermediation across ASEAN markets, while visa liberalization programs from Thailand's Ministry of Tourism and Sports accelerate cross-border visitor throughput from G7 source markets.
Growth Catalysts
- Thailand's Digital Nomad Visa Relaxation:The Ministry of Tourism and Sports eliminated work permit requirements for remote workers from G7 nations, extending average length of stay and per-visitor spend in Bangkok and Chiang Mai hospitality clusters.
- Super-App Route Bundling:Mobile-first platforms consolidate domestic Indonesian flight, ferry, and ground transport inventory into single-transaction packages, capturing booking flow from fragmented offline agents.
- Wellness Retreat Premiumization:European and North American demand for medical tourism and holistic wellness programs is pulling hospitality investment toward Bali's Ubud corridor and Thailand's Phuket wellness clusters.
Market Restraints
- Jet Fuel Cost Volatility:ASEAN carriers face margin compression from Singapore jet fuel price swings that constitute 25-35% of operating costs for low-cost operators serving secondary city pairs.
- Environmental Carrying Capacity Limits:Indonesia's Ministry of Tourism and Creative Economy imposes visitor quotas on Komodo National Park and Raja Ampat marine corridors, capping revenue potential for dive tour operators.
- Carbon Border Adjustment Exposure:Proposed EU carbon border mechanisms on aviation threaten to erode price competitiveness of long-haul European source market routes into Bangkok and Singapore hubs.
Strategic Opportunities
- Vietnam Central Coast Concentration:Da Nang and Hoi An are absorbing displaced Chinese outbound demand with new direct flight capacity from Korea, Japan, and Australia creating white space for resort development.
- ASEAN Mutual Recognition Arrangements:Cross-border hospitality staffing agreements reduce labor friction for Thai and Indonesian hotel groups expanding into Vietnam and Philippines markets.
- Marine Biodiversity Corridor Monetization:Liveaboard diving and citizen science tourism packages around Indonesia's Coral Triangle present premium pricing power unavailable to standardized land-based itineraries.
Industry Challenges
- Multilingual Guest Experience Talent:Hospitality groups struggle to recruit Mandarin, Korean, and Arabic-speaking front-of-house staff at scale to match shifting source market demographics away from traditional European languages.
- Legacy Property Management System Integration:Independent hotels across Philippines and Vietnam face capex burdens replacing on-premise software with cloud-native platforms capable of real-time dynamic pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opportunities in South East Asia Travel and Tourism Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Transportation, Tour Operations, Activities Customer Type: Leisure Travelers, Business Travelers, Family Groups, Solo Travelers Booking Channel: Online Travel Agents, Direct Bookings, Travel Agencies, Mobile Apps Price Tier: Luxury, Mid-Range, Budget, Economy |
| Companies Covered | Traveloka, Agoda, Booking.com, AirAsia Group, Singapore Airlines, Expedia Group, Airbnb, Trip.com Group, Klook, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opportunities in South East Asia Travel and Tourism Market Evolving Landscape
Artificial intelligence and biometric identity verification are streamlining passenger processing at ASEAN airports while reshaping how hospitality groups personalize guest journeys from booking through post-stay engagement.
Facial recognition boarding gates are absorbing friction from document verification at Singapore Changi and Bangkok Suvarnabhumi terminals, compressing minimum connection times and enabling narrow-body aircraft to compete on routes previously requiring wide-body capacity. Full-service carriers and low-cost operators alike are retrofitting departure gates with this infrastructure. The technology is absorbing queue management labor costs while redirecting passenger processing staff toward concierge and retail functions.
Singapore's STB has mandated sustainability disclosure templates for licensed hotels, forcing operators to quantify energy, water, and waste metrics or risk incentive disqualification. Properties exceeding 200 rooms must submit verified data to maintain tax concession eligibility under the Tourism Development Fund. Smaller boutique operators in Kampong Glam and Tiong Bahru heritage districts are consolidating to share compliance costs and audit resources.
Direct booking via property websites and messaging apps is displacing Online Travel Agent intermediation among repeat visitors to Thai island destinations. Koh Samui and Koh Phangan resort operators now capture 40-50% of reservations through WhatsApp and LINE channels, bypassing commission structures that previously extracted 15-20% of room revenue. This channel migration is most visible among Australian and European source markets with established trust relationships from prior stays.
Opportunities in South East Asia Travel and Tourism Market Segmentation
Segmentation across the South East Asia travel and tourism market reveals how distinct traveler profiles, service configurations, and transaction channels create divergent margin structures and capital deployment priorities for operators across ASEAN states.
Service Type:
Service type differentiation tracks where foreign exchange inflows concentrate versus where employment intensity sits across ASEAN economies.
- Accommodation:Hospitality inventory spans international branded properties, domestic hotel chains, and independent guesthouses across Thailand, Indonesia, and Vietnam. Demand concentrates in Bali's Ubud wellness corridor and Vietnam's Da Nang coastal strip where resort development absorbs displaced Chinese outbound flow. Environmental carrying capacity limits in Indonesia's marine parks constrain expansion trajectories for beachfront properties.
- Transportation:Aviation, rail, ferry, and ground transport networks move visitors between ASEAN hubs and secondary destinations. Low-cost carrier capacity from AirAsia Group dominates intra-regional route economics while Singapore Airlines sustains premium yield through cabin upgrades and loyalty program depth. Jet fuel cost volatility constitutes 25-35% of operating expenses for budget operators.
- Tour Operations:Packaged itineraries bundle destination experiences, guides, and logistics for visitor segments seeking structured exploration. Dive tour operators around Indonesia's Raja Ampat and Komodo National Park face visitor quota caps that limit revenue scaling despite premium pricing power for liveaboard and citizen science packages.
- Activities:Discrete experiences including culinary immersion, trekking, and marine recreation capture spend outside accommodation and transport. European and North American demand for wellness retreats is pulling hospitality investment toward Thailand's Phuket wellness clusters and Bali's holistic programming.
Volume sits with Accommodation; growth tilts toward Activities as experiential spend displaces standardized package purchases.
Customer Type:
Customer type segmentation maps how source market recovery patterns and length-of-stay variation reshape revenue per available room calculations across Thai and Vietnamese properties.
- Leisure Travelers:Vacation-motivated visitors from Korea, Japan, and Australia drive occupancy in Vietnam's central coast and Indonesian island destinations. Thailand's Ministry of Tourism and Sports visa relaxation for G7 digital nomads extends average length of stay for this hybrid leisure-work segment.
- Business Travelers:Corporate and MICE demand from technology and finance sectors recovers faster than legacy corporate segments across Singapore and Bangkok hospitality clusters. Singapore's STB sustainability disclosure mandates for licensed hotels filter this segment toward properties with verified environmental metrics.
- Family Groups:Multi-generational travel units seek interconnected room configurations and child-friendly programming at resort properties. This segment concentrates in Phuket and Bali where all-inclusive pricing structures reduce transaction friction during extended stays.
- Solo Travelers:Individual visitors, including young backpackers and remote workers, absorb budget tier inventory through hostel networks and guesthouse aggregators. Intra-ASEAN labor mobility adds volume to this segment across land border crossings into Thailand and Vietnam.
Revenue concentration favors Business Travelers in Singapore and Bangkok; expansion opportunity centers on Leisure Travelers as Korean and Australian direct flight capacity grows.
Booking Channel:
Channel segmentation exposes how mobile penetration and trust formation velocity determine commission structures and customer acquisition costs for Thai island operators.
- Online Travel Agents:Platform intermediaries capture disproportionate booking flow as mobile penetration exceeds desktop usage across Indonesia and Philippines markets. Traveloka's super-app architecture dominates domestic Indonesian route bundling through consolidated flight, ferry, and ground transport inventory.
- Direct Bookings:Property websites and messaging apps displace intermediary commissions among repeat visitors with established trust relationships. Koh Samui and Koh Phangan operators now capture 40-50% of reservations through WhatsApp and LINE channels, bypassing 15-20% commission structures.
- Travel Agencies:Traditional offline intermediaries retain relevance for complex multi-destination itineraries and corporate account management. Fragmented offline agents lose share to mobile-first platforms in domestic Indonesian market segments.
- Mobile Apps:Native application interfaces enable single-transaction packaging of transport, accommodation, and experience inventory. Super-app ecosystems concentrate booking flow through integrated payment rails and loyalty currency programs.
Transaction volume flows through Online Travel Agents; margin expansion favors Direct Bookings as Australian and European repeat visitation deepens.
Price Tier:
Price tier stratification reflects certification standards, location premiums, and service intensity gradients across ASEAN hospitality assets.
- Luxury:Premium properties command rate premiums through branded service protocols, exclusive locations, and wellness programming. Singapore's STB mandates sustainability disclosure templates for properties exceeding 200 rooms as a condition of Tourism Development Fund tax concession eligibility.
- Mid-Range:Three and four-star properties balance service breadth with accessibility for Korean and Australian source markets. This tier absorbs volume from business travelers seeking proximity to Bangkok and Singapore central business districts without luxury rate structures.
- Budget:Limited-service hotels and branded budget chains capture price-sensitive leisure and intra-ASEAN labor mobility segments. Independent hotels across Philippines and Vietnam face capex burdens replacing legacy property management systems with cloud-native platforms capable of dynamic pricing.
- Economy:Hostel networks, guesthouses, and homestay aggregators serve young solo travelers and extended-stay digital nomads. Thailand's relaxed visa requirements for G7 remote workers extend average length of stay in Bangkok and Chiang Mai economy-tier clusters.
Room night volume concentrates in Budget and Economy tiers; revenue per available room expansion favors Luxury as European wellness retreat demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives concentrate hospitality investment near Bangkok's Suvarnabhumi Airport corridor, while Vietnam's Da Nang Hi-Tech Park and Free Trade Zone provisions accelerate resort development along the central coast.
Thailand
Bangkok and Chiang Mai absorb extended-stay digital nomads following the Ministry of Tourism and Sports visa relaxation for G7 remote workers. The Tourism Development Fund extends tax concessions to properties exceeding 200 rooms that submit verified sustainability metrics. Phuket wellness clusters pull European medical tourism demand toward holistic programming investments.
Vietnam
Da Nang and Hoi An capture displaced Chinese outbound flow through new direct flight capacity from Korea, Japan, and Australia. The Ministry of Planning and Investment's special economic zone frameworks reduce corporate income tax burdens for hospitality developments in Quang Nam province. Resort construction accelerates along the central coast to absorb intra-ASEAN leisure migration.
Indonesia
Bali's Ubud corridor attracts wellness retreat investment from European and North American source markets. The Ministry of Tourism and Creative Economy imposes visitor quotas on Komodo National Park and Raja Ampat, capping dive tour operator revenue scaling despite premium liveaboard pricing. Jakarta-based super-app platforms dominate domestic route bundling across the archipelago.
Singapore
The Singapore Tourism Board mandates sustainability disclosure templates for licensed hotels as a condition of Tourism Development Fund eligibility. Changi Airport's biometric boarding infrastructure compresses connection times and enables narrow-body competition on medium-haul routes. Premium yield sustains through cabin product upgrades and KrisFlyer loyalty program depth.
Philippines
Boracay and Palawan marine corridors attract dive tourism investment despite environmental carrying capacity scrutiny from the Department of Environment and Natural Resources. Independent hotels face capex burdens replacing legacy property management systems with cloud-native platforms. Manila-based Online Travel Agents lose domestic share to Indonesian super-app expansion.
Opportunities in South East Asia Travel and Tourism Market Competitive Landscape
Top-tier vendors anchor premium yield through loyalty depth and cabin product upgrades, while low-cost specialists compress unit economics across secondary city pairs. The market structures around three tiers: full-service carriers with hub dominance, super-app platforms with integrated payment rails, and accommodation aggregators with direct-booking displacement. Strategic moves concentrate on M&A for route network density and vertical integration into ground transport inventory.
Within the super-app tier, Traveloka exemplifies domestic Indonesian route bundling architecture. Among ASEAN carrier groups, AirAsia Group occupies the low-cost capacity position across secondary cities. Singapore Airlines anchors premium-tier yield management through cabin upgrades and loyalty program infrastructure. These three entities represent distinct competitive archetypes: platform consolidation, cost-leadership scale, and service-premium positioning.
| Leading Market Players |
|---|
| Traveloka |
| Agoda |
| Booking.com |
| AirAsia Group |
| Singapore Airlines |
| Expedia Group |
| Airbnb |
| Trip.com Group |
| Klook |
| Others |
Value Network & Pricing Analysis
Biometric boarding infrastructure deployment across ASEAN airports compresses connection times while simultaneously concentrating procurement power among full-service carriers and hub operators capable of justifying capital outlays. This technology shift reshapes cost economics for ground handling services and redirects pricing power toward carriers with scale to amortize facial recognition gate investments across high-frequency routes.
Pricing Analysis
Short lead-time bookings command rate premiums while spot inventory on direct channels carries discount exposure. Three-tier pricing structure across premium, standard, and economy levels stratifies by cabin product certification and loyalty program depth. Pricing pressure stems from Singapore jet fuel cost volatility that constitutes 25-35% of operating expenses for budget carriers. Intra-ASEAN labor mobility segments exhibit highest price sensitivity; premium yield sustains through Singapore Airlines cabin upgrades and KrisFlyer retention.
Supply Chain Analysis
Jet fuel supply rests on Singapore trading hub pricing benchmarks and regional refinery capacity across Thailand, South Korea, and Japan. Aviation-grade fuel, in-flight catering provisions, and ground handling equipment feed from concentrated ASEAN logistics corridors. Single-source vulnerability sits with Singapore jet fuel price swings that transmit directly to low-cost operator margins. Distribution runs through hub-and-spoke airport infrastructure with secondary city pair feed via narrow-body aircraft.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where mobile-first platform economics and sustainability compliance burdens force fragmented independent hotels and offline travel agencies toward exit or acquisition.
For Market Incumbents: To counter super-app platform disintermediation, full-service carriers should deepen KrisFlyer loyalty currency integration with ground transport inventory while hospitality groups accelerate cloud-native property management system replacement to enable real-time dynamic pricing against Online Travel Agent commission structures. For New Entrants and Emerging Players: Launch via WhatsApp and LINE direct-booking channels targeting Australian and European repeat visitors to Thai island destinations where established trust relationships bypass 15-20% intermediary commissions. White-space concentration sits in Vietnam's Da Nang and Hoi An resort development absorbing Korean and Australian direct flight capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation and regional hospitality group rollup. Five-to-ten year viability favors operators with verified sustainability metrics qualifying for Tourism Development Fund tax concessions. Watch ASEAN Mutual Recognition Arrangement implementation velocity as cross-border staffing scalability signal.| Strategic Initiative | Industry Significance |
|---|---|
| Super-App Route Bundling Expansion | Traveloka's domestic Indonesian flight-ferry-ground consolidation captures booking flow from fragmented offline agents. |
| Biometric Boarding Infrastructure Deployment | Singapore Changi and Bangkok Suvarnabhumi facial recognition gates compress minimum connection times for narrow-body route economics. |
| Sustainability Disclosure Compliance | Singapore STB-mandated templates for 200-plus room properties condition Tourism Development Fund eligibility on verified metrics. |
| Direct Booking Channel Migration | Koh Samui and Koh Phangan operators capture 40-50% of reservations through messaging apps, bypassing Online Travel Agent commissions. |
| Wellness Retreat Premiumization | Bali Ubud and Thailand Phuket holistic programming pulls European medical tourism investment toward certified hospitality clusters. |
Research Methodology
Document review covered ASEAN tourism ministry policy filings, airline regulatory submissions, and hospitality investment databases, complemented by interviews with hotel group revenue managers, low-cost carrier network planners, Online Travel Agent platform engineers, and sustainability compliance officers at properties exceeding 200 rooms. Secondary validation drew from STB licensing records, Indonesia's Ministry of Tourism and Creative Economy visitor quota data, and Thailand's Ministry of Tourism and Sports visa policy announcements. Bottom-up property inventory counts and top-down foreign exchange inflow estimates were triangulated against super-app transaction volume disclosures.
Segment-level projections across service type, customer type, booking channel, and price tier dimensions were generated through the analytical framework. Modeled outputs span accommodation capacity additions, aviation seat-mile deployment, and tour operator revenue concentration across the projection horizon. CAGRs were derived from regression analysis against historical visitor arrival patterns and forward capacity announcements from AirAsia Group and Singapore Airlines fleet plans.
Jet fuel price volatility, EU carbon border adjustment implementation, and environmental carrying capacity enforcement intensity are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding visa liberalization permanence and digital nomad visa uptake velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market