
 Vietnam Tourism Market | 2026-2036
Vietnam Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Tourism Market Outlook
Hospitality labor supply is rotating toward multilingual service training as international arrivals surge beyond pre-pandemic thresholds. Vietravel leverages its integrated tour package network to dominate domestic outbound coordination. Saigontourist sustains legacy hotel assets through state-backed renovation programs in Ho Chi Minh City. Agoda competes on price transparency across fragmented accommodation inventory in secondary cities.
Vietnam tourism encompasses the commercial organization of travel services, lodging, guided experiences, and destination access within the Socialist Republic of Vietnam, operating through a dual structure of state-managed heritage sites and privately operated hospitality assets. The sector functions as an export-oriented service industry, generating foreign exchange through experiential consumption of cultural, coastal, and culinary assets. International tourists command premium pricing in accommodation and tour packages while domestic travelers sustain volume during off-peak months. Adventure travel is expanding fastest in northern highland provinces where infrastructure investment lags demand growth. Business travelers concentrate margin pools in Ho Chi Minh City and Hanoi where corporate rates exceed leisure tariffs by substantial multiples.
Vietnam's Ministry of Culture, Sports and Tourism sets annual arrival targets and heritage site admission frameworks that directly shape investor confidence in resort development. The National Assembly's electronic visa legislation, administered by the Immigration Department, is reducing friction for source markets including South Korea and Japan. Stakeholders must monitor regulatory pacing between conservation mandates in UNESCO zones and commercial pressure for capacity expansion.
Market Dynamics
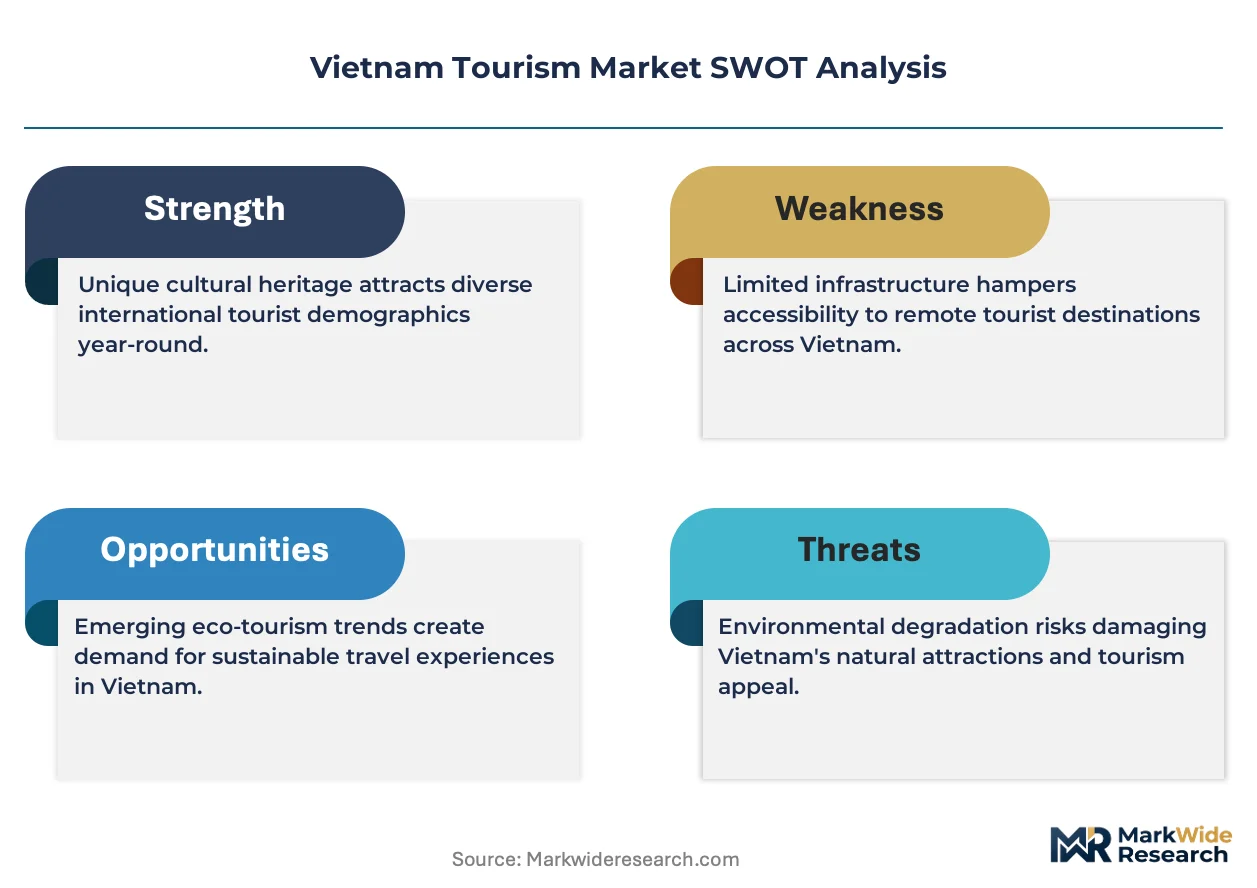
The Vietnam tourism sector is experiencing structural pressure from electronic visa policy liberalization, which is compressing booking lead times and accelerating demand volatility across coastal accommodation inventory.
Growth Catalysts
- Electronic Visa Expansion:Vietnam's Immigration Department streamlined entry protocols for South Korean and Japanese nationals, reducing friction in source market access.
- Northeast Asian Source Market Concentration:Surging arrivals from South Korea and Japan are driving lodging demand across Da Nang, Hoi An, and Nha Trang coastal corridors.
- Heritage Site Admission Frameworks:The Ministry of Culture, Sports and Tourism established tiered pricing structures at UNESCO zones, improving revenue capture per visitor.
Market Restraints
- Labor Supply Bottlenecks:Multilingual service training capacity lags behind international arrival velocity, constraining service quality in premium accommodation segments.
- Infrastructure Investment Gaps:Northern highland provinces including Lao Cai and Ha Giang lack road and utility connectivity to match adventure travel demand growth.
- Regulatory Pacing Friction:Conservation mandates in UNESCO buffer zones create approval delays for resort development permits in Quang Nam and Thua Thien Hue provinces.
Strategic Opportunities
- Central Region Capacity Expansion:Da Nang International Airport connectivity improvements create white space for integrated resort development between Hoi An and Lang Co.
- Domestic Outbound Coordination:Integrated tour package networks can capture margin pools from Vietnamese travelers seeking regional Southeast Asian destinations.
- Corporate Rate Premium Extraction:Business traveler concentration in Ho Chi Minh City and Hanoi supports sustained margin pools above leisure tariffs.
Industry Challenges
- Service Standardization Complexity:Fragmented accommodation inventory across secondary cities complicates quality assurance for online travel aggregators.
- State-Private Coordination Friction:Dual structure of state-managed heritage sites and private hospitality assets creates operational misalignment in visitor flow management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Tourism Market |
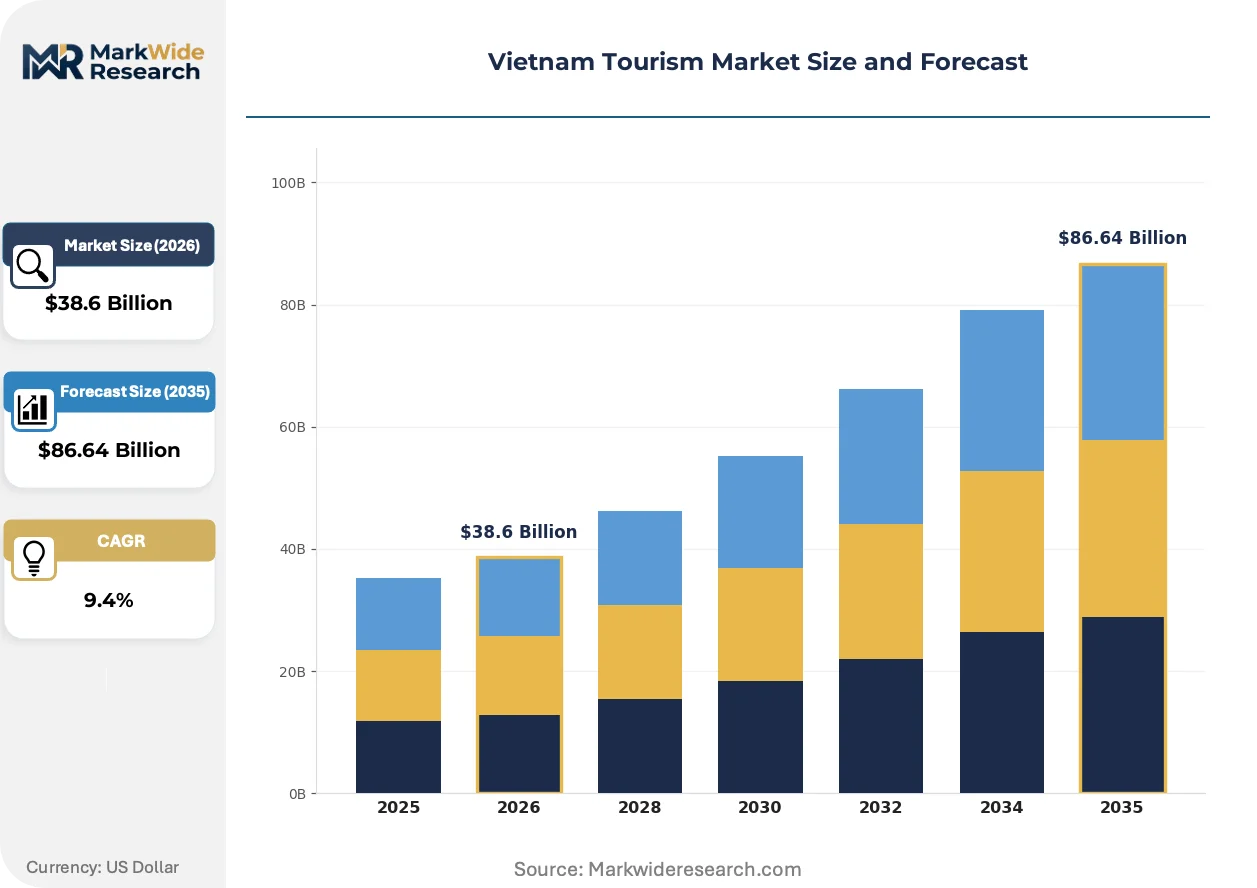
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Domestic Tourists, International Tourists, Business Travelers, Backpackers Service Type: Accommodation, Tour Packages, Transportation, Attractions Travel Purpose: Leisure, Business, Adventure, Cultural Seasonality: Peak Season, Off-Peak Season, Holiday Season, Monsoon |
| Companies Covered | Saigontourist, Vietravel, Hanoitourist, TST Tourist, Anex Vietnam, JTB-TNT, Vidotour, Booking.com, Agoda, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Tourism Market Strategic Shifts
Digital booking platforms are compressing traditional distribution hierarchies in Vietnamese tourism, while regulatory digitization and shifting traveler expectations reshape competitive positioning across accommodation tiers.
Mobile-first booking engines are supplanting traditional travel agency intermediation in domestic and international reservation flows. Independent travelers from South Korea and Japan now complete accommodation transactions directly through platform interfaces, bypassing legacy tour operator markups. This disintermediation is compressing commission structures and forcing asset owners to build direct-to-consumer capabilities.
Vietnam's National Assembly electronic visa legislation is reducing administrative friction for priority source markets. The Immigration Department's automated processing system compresses approval timelines from weeks to days. Resort developers in Binh Thuan and Khanh Hoa provinces are accelerating project timelines to capture inbound volume spikes.
Experiential consumption preferences are rotating demand toward culinary and cultural immersion programming. International visitors now prioritize cooking classes, craft workshops, and homestay arrangements over standardized resort packages. This shift is most visible in Hoi An's ancient town precinct and Hanoi's Old Quarter, where small-scale operators capture premium pricing through authenticity positioning.
Vietnam Tourism Market Segmentation
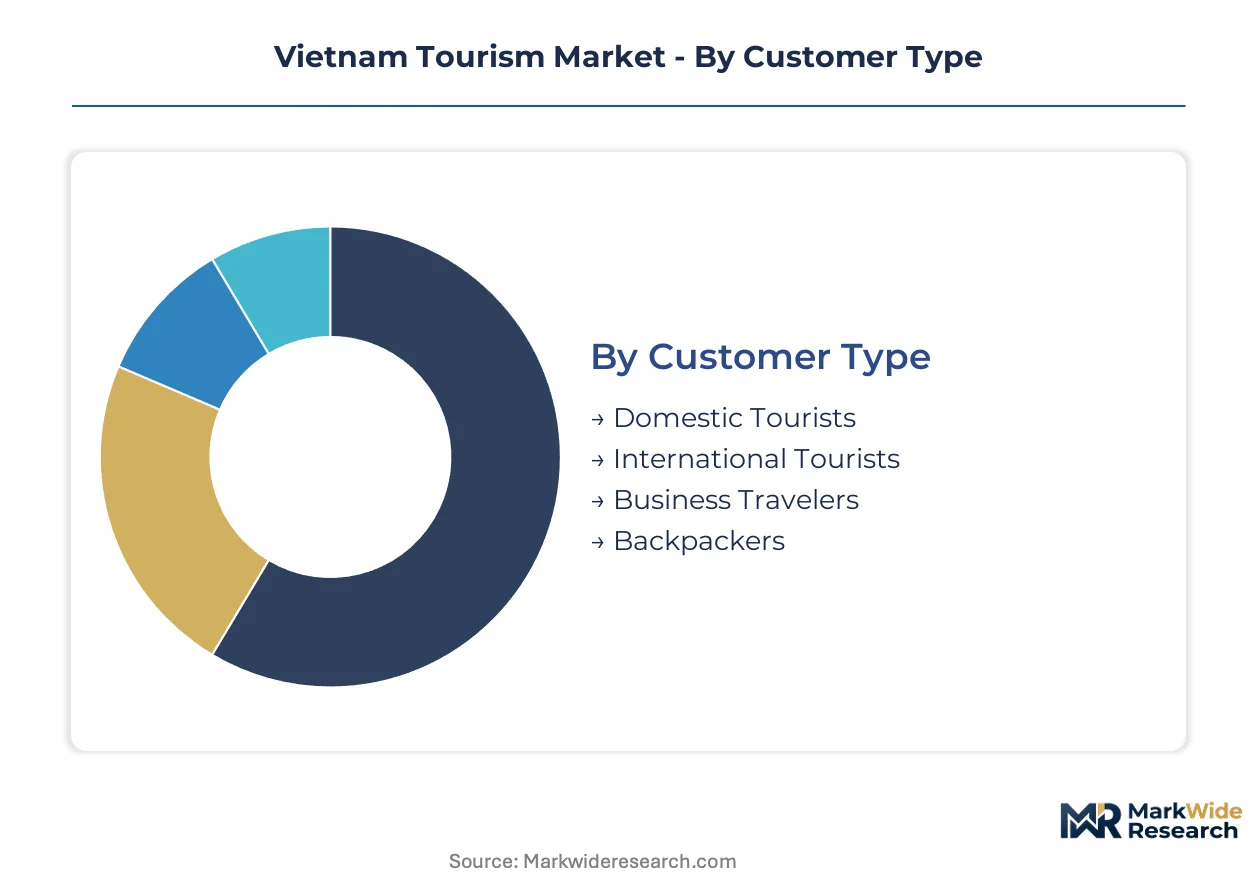
Segmentation reveals how tourism demand fragments across distinct traveler profiles and service categories in Vietnam. Each dimension exposes different margin structures, infrastructure requirements, and regulatory exposure for operators.
Customer Type:
Domestic travelers concentrate volume in coastal provinces during national holidays, while international visitors drive premium pricing in heritage zones and integrated resorts.
- Domestic Tourists:Vietnamese nationals traveling for leisure and family reunions, concentrated in beach destinations during Tet and summer holidays. Demand concentrates in Da Nang and Phu Quoc where domestic flight connectivity supports mass volume.
- International Tourists:Foreign nationals from Northeast Asia, Europe, and Australia seeking experiential consumption of cultural and coastal assets. Arrival surges from South Korea and Japan are compressing booking lead times in Hoi An and Nha Trang accommodation inventory.
- Business Travelers:Corporate visitors attending conferences, trade events, and site inspections. Ho Chi Minh City and Hanoi sustain margin pools through corporate rate premiums exceeding leisure tariffs.
- Backpackers:Budget-conscious independent travelers prioritizing extended stays and authentic local immersion. Northern highland provinces including Ha Giang and Sapa attract this segment despite infrastructure gaps.
International tourists command the established base. The steepest expansion runs through domestic tourists as rising disposable incomes rotate Vietnamese travelers toward premium experiences.
Service Type:
Margin capture varies sharply across service layers, with accommodation and tour packages exhibiting divergent capital intensity and customer acquisition economics.
- Accommodation:Lodging assets spanning luxury resorts, boutique hotels, and budget hostels. Fragmented inventory across secondary cities complicates quality assurance for online aggregators.
- Tour Packages:Bundled offerings combining transport, lodging, and guided experiences. Integrated networks dominate domestic outbound coordination to regional Southeast Asian destinations.
- Transportation:Air, rail, road, and maritime mobility services connecting origin markets to destinations. Da Nang International Airport connectivity improvements are unlocking white space for resort development between Hoi An and Lang Co.
- Attractions:Heritage sites, natural parks, and entertainment venues generating admission revenue. Tiered pricing structures at UNESCO zones established by the Ministry of Culture, Sports and Tourism improve per-visitor revenue capture.
Accommodation absorbs the largest capital deployment. Attractions deliver the steepest margin expansion trajectory through regulatory pricing authority.
Travel Purpose:
Purpose-driven segmentation determines seasonal patterns, length of stay, and cross-selling potential for ancillary services.
- Leisure:Vacation and relaxation-focused travel to coastal and resort destinations. Beach provinces in Khanh Hoa and Binh Thuan capture sustained volume through sun-sea-sand positioning.
- Business:Corporate and MICE travel concentrated in commercial centers. Ho Chi Minh City and Hanoi dominate this segment where extended stays and ancillary spending exceed leisure averages.
- Adventure:Active travel including trekking, diving, and motorbike touring. Northern highland provinces lack road and utility connectivity to match demand growth in this category.
- Cultural:Heritage-focused travel to UNESCO sites and traditional craft centers. Hoi An's ancient town precinct and Hanoi's Old Quarter capture premium pricing through authenticity positioning.
Leisure travel anchors volume throughput. Adventure travel is expanding most quickly as infrastructure investment lags demand growth in remote provinces.
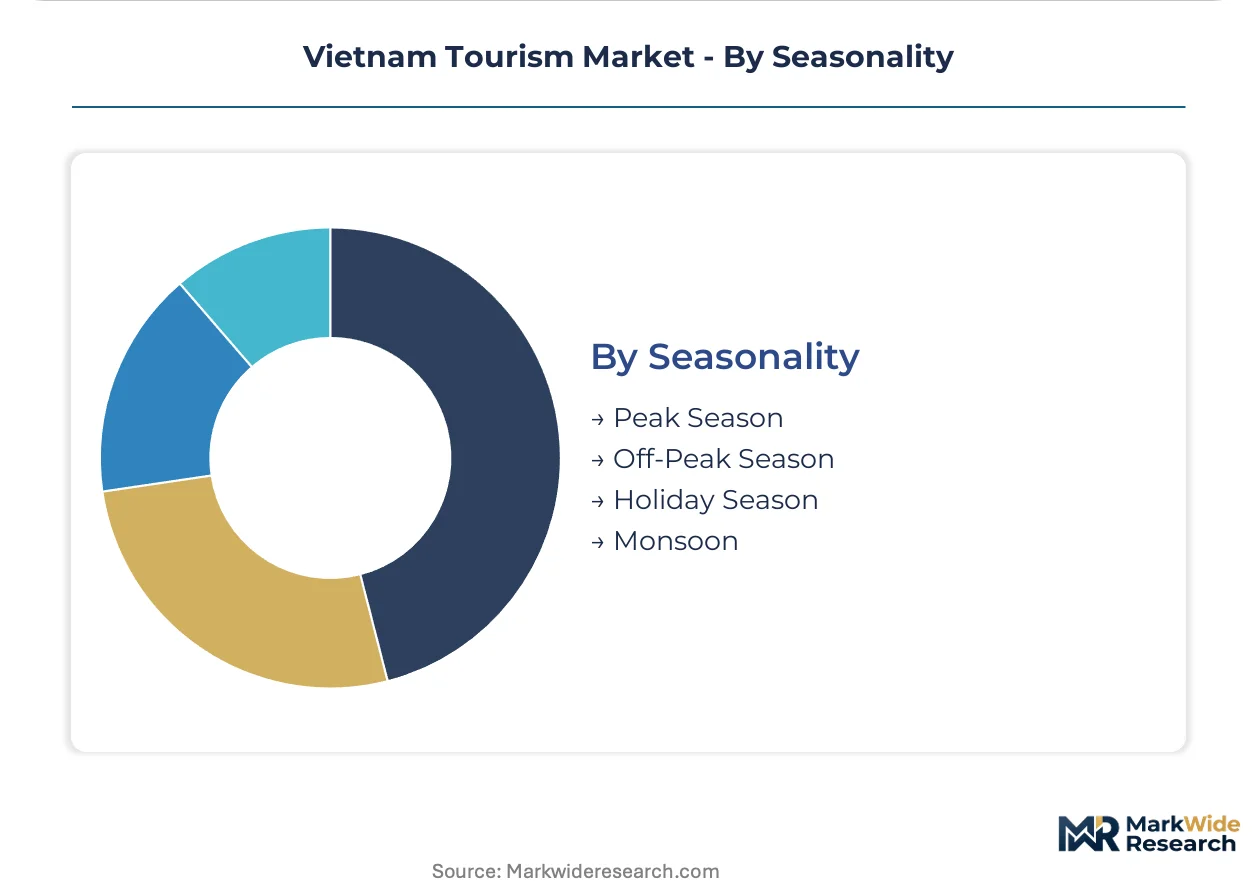
Seasonality:
Temporal segmentation exposes capacity utilization challenges and pricing volatility across Vietnam's tropical climate zones.
- Peak Season:December through February dry months attracting maximum international arrivals. Coastal accommodation rates surge during this window as European and North American visitors escape winter.
- Off-Peak Season:May through August period of reduced international demand. Domestic travelers sustain baseline volume through discounted resort packages in central region provinces.
- Holiday Season:Tet lunar new year and Reunification Day periods of concentrated domestic movement. Transport infrastructure faces strain as Vietnamese workers return to home provinces.
- Monsoon:September through November rainy period depressing coastal visitation. Adventure operators in northern provinces pivot toward dry-season trekking alternatives.
Peak season commands rate premiums and full utilization. Off-peak season presents the steepest expansion opportunity through domestic market development and MICE event scheduling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal provinces around Da Nang command rate premiums exceeding northern highland destinations by substantial multiples, while Ho Chi Minh City extracts corporate tariffs above leisure benchmarks across all accommodation tiers.
Red River Delta
Hanoi anchors inbound cultural tourism through UNESCO-listed Old Quarter precincts and imperial citadel complexes. The Ministry of Culture, Sports and Tourism administers tiered admission frameworks at heritage sites, improving per-visitor revenue capture. International flight connectivity through Noi Bai International Airport concentrates business traveler volume in Ba Dinh and Hoan Kiem districts.
Southeast Region
Ho Chi Minh City dominates corporate travel margins through MICE infrastructure and extended-stay demand from multinational site inspections. State-backed renovation programs sustain legacy hotel assets in District 1 and District 3. Tan Son Nhat International Airport capacity constraints are redirecting leisure overflow toward Vung Tau coastal corridors.
Central Coast
Da Nang International Airport connectivity improvements are unlocking white space for integrated resort development between Hoi An and Lang Co. Electronic visa expansion for South Korean and Japanese nationals is compressing booking lead times across Quang Nam and Thua Thien Hue accommodation inventory. UNESCO buffer zone conservation mandates create approval delays for new capacity in Hoi An ancient town precincts.
Central Highlands
Lam Dong province around Da Lat captures domestic leisure volume through temperate climate positioning and agricultural tourism circuits. Infrastructure investment lags behind demand growth for adventure travel in Dak Lak and Gia Lai provinces. Road connectivity gaps constrain tour package economics between coastal corridors and highland destinations.
Mekong Delta
Can Tho and An Giang provinces sustain floating market tourism and riverine hospitality circuits for international cultural travelers. The Ministry of Transport's waterway improvement programs are reducing transit friction between Ho Chi Minh City and delta provinces. Homestay networks in Ben Tre and Vinh Long capture authenticity premiums through craft workshop and culinary immersion programming.
Vietnam Tourism Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with online travel aggregators competing on price transparency while integrated tour operators capture margin through bundled service coordination. The vendor base spans state-backed legacy operators, privately held domestic networks, and foreign-owned digital platforms. Three archetypes dominate: vertically integrated domestic tour operators, asset-light international aggregators, and state-managed heritage site concessionaires. Competitive moves concentrate on direct-to-consumer platform development and strategic partnerships with accommodation inventory owners.
Within the integrated domestic tier, Vietravel and Saigontourist exemplify contrasting operational models—Vietravel leveraging outbound coordination networks while Saigontourist sustains legacy assets through state-supported renovation programs. Among digital platforms, Agoda occupies a position representing price-transparent aggregation across fragmented secondary city inventory. These three anchors illustrate how competitive positioning fragments between bundled service control and disintermediated booking efficiency.
| Leading Market Players |
|---|
| Saigontourist |
| Vietravel |
| Hanoitourist |
| TST Tourist |
| Anex Vietnam |
| JTB-TNT |
| Vidotour |
| Booking.com |
| Agoda |
| Others |
Value Chain & Pricing Dynamics
Da Nang International Airport's passenger throughput scale creates utilization efficiencies that compress per-unit operating costs for coastal accommodation operators while simultaneously establishing rate floors that smaller provincial competitors cannot match.
Pricing Analysis
The customization-premium spread between configured-to-order tour packages and standardized resort bookings determines margin capture across Vietnamese tourism. Three-tier pricing structure across premium, standard, and economy levels segments international visitors from South Korea and Japan at the top, regional Asian travelers in the middle, and domestic volume at the base. Price differentiation hinges on multilingual service certification and proximity to UNESCO heritage zones. Cost compression in the economy tier is intensifying because online travel aggregators force rate transparency across fragmented secondary city inventory. Domestic travelers exhibit highest price sensitivity, while corporate travelers in Ho Chi Minh City and Hanoi demonstrate lowest elasticity.
Supply Chain Analysis
Noi Bai International Airport's slot constraints create a chokepoint that throttles inbound capacity expansion for Hanoi's hospitality sector. Geographic supply concentration draws from Thailand, Singapore, and South Korea for aviation services, technology platforms, and luxury amenity imports. Raw material dependencies span construction materials for resort development, food and beverage inputs for culinary programming, and digital infrastructure for booking systems. Single-source vulnerability runs through centralized immigration technology vendors processing electronic visa applications. Distribution runs through hybrid channels combining direct-to-consumer platforms, legacy travel agency networks, and online aggregator marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam tourism operates in a cyclical recovery phase driven by Northeast Asian source market rebound following pandemic suppression. Electronic visa policy liberalization accelerates booking velocity but compresses lead-time visibility for inventory planning.
For Market Incumbents: Compound defensive positioning through multilingual service certification investments that lock in premium rate tiers and direct-to-consumer platform development that reduces aggregator commission exposure. State-backed renovation programs in Ho Chi Minh City legacy assets provide a lever against new supply entrants. Threat from asset-light international aggregators demands channel control reinforcement.
For New Entrants and Emerging Players: Lead with experiential programming specialization in northern highland provinces where infrastructure investment lags demand growth for adventure travel. The most penetrable segment sits in culinary and cultural immersion offerings around Hanoi's Old Quarter and Hoi An's ancient town precincts. Go-to-market angle should emphasize authenticity positioning through homestay network partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated tour operators with captive accommodation inventory and established source market relationships. Long-term viability over a five-to-ten year window rests on regulatory pacing between conservation mandates and commercial expansion approvals. Acquisition target archetype: mid-scale resort developers in Quang Nam and Thua Thien Hue provinces with approved permits in UNESCO buffer zones. Signal to watch: Immigration Department processing capacity expansion as indicator of inbound volume ceiling.
| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Visa Infrastructure Investment | Immigration Department automation reduces approval friction for South Korean and Japanese source markets. |
| Integrated Resort Development | Da Nang International Airport connectivity unlocks white space between Hoi An and Lang Co coastal corridors. |
| Multilingual Service Training | Labor supply bottlenecks in premium accommodation segments constrain quality assurance for international visitors. |
| Direct-to-Consumer Platform Launch | Asset owners bypass Agoda commission structures through proprietary booking engines for repeat visitors. |
| Heritage Site Concession Renewal | Ministry of Culture, Sports and Tourism tiered pricing frameworks improve per-visitor revenue capture at UNESCO zones. |
Study Parameters
Operator-level perspectives from hotel general managers, tour package coordinators, immigration policy administrators, and online travel platform executives anchored the qualitative base. Primary interview data combined with secondary validation from Vietnam National Administration of Tourism arrival statistics, Ministry of Culture heritage site admission records, and Da Nang International Airport passenger throughput disclosures. Bottom-up accommodation inventory assessment and top-down macroeconomic triangulation framed value estimates.
Sensitivity analysis tested forecast robustness across electronic visa processing capacity scenarios and Northeast Asian source market elasticity assumptions. Segmentation dimensions modeled span customer type, service category, travel purpose, and regional destination cluster across the analysis window. CAGRs derived from historical trajectory fitting and forward-looking demand elasticity parameters. Industry-specific inputs incorporated aviation capacity expansion timelines and UNESCO conservation mandate enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained electronic visa policy liberalization and stable regional geopolitical conditions would require recalibration. Forecasts reflect documented assumptions about infrastructure investment pacing and source market recovery velocity. Practitioners should keep alternative scenarios live as Immigration Department processing capacity and Ministry of Culture regulatory enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Thailand Sustainable Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market