
 Global Religious Tourism Market | 2026-2036
Global Religious Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Global Religious Tourism Market Outlook
Asset-light franchising and white-label platform licensing is reconfiguring capital requirements for faith-based tour operators. Globus Faith leverages its established supplier network across Mediterranean pilgrimage circuits. Nawas International Travel anchors its competitive position through exclusive parish partnerships in North American dioceses. Friendship Tours differentiates via curated Reformation heritage trails across Central European sites.
Religious tourism encompasses travel undertaken for spiritual fulfillment, doctrinal observance, or participation in faith-specific rituals at destinations holding sacred significance, typically involving structured itineraries that coordinate lodging, worship access, and ceremonial guidance. The activity generates commercial value through hospitality procurement, transportation logistics, and ancillary devotional commerce. Group tours command the largest revenue pool due to bulk contracting power and predictable occupancy rates for hotels near sacred sites. Individual travel represents the fastest-expanding arrangement category as mobile booking platforms reduce coordination friction for solo pilgrims. Sacred sites tourism maintains mature margins while spiritual retreats capture premium pricing through extended-duration programming.
Saudi Arabia's Ministry of Hajj and Umrah governs pilgrimage quotas and facility standards for Mecca and Medina access. India's Ministry of Tourism coordinates with state-level religious endowment boards to upgrade infrastructure at Kumbh Mela sites and temple towns. UNESCO World Heritage designation processes influence preservation funding and visitor management protocols at contested religious landmarks. Stakeholders must monitor visa policy reciprocity shifts and carbon-accounting requirements for long-haul pilgrimage aviation.
Market Dynamics
Digital visa infrastructure and mobile-first booking platforms are compressing pilgrimage coordination cycles while fragmenting demand across micro-segments. Saudi Arabia's Nusuk system and India's e-visa expansion for spiritual travelers demonstrate how state-level digitization restructures entry protocols and operator business models.
Growth Catalysts
- Visa digitization mandates:Saudi Arabia's Ministry of Hajj and Umrah has deployed the Nusuk platform to unify pilgrimage permits, accommodation booking, and health verification. This reduces friction for repeat Umrah travelers and expands addressable market depth.
- Sacred corridor infrastructure:India's Ministry of Tourism coordinates with Uttar Pradesh and Andhra Pradesh state boards to upgrade Kumbh Mela facilities and Tirupati temple access. Improved sanitation and crowd management extends peak-season capacity.
- Generational demand rotation:Millennial and Gen-Z travelers prioritize experiential spiritual programming over traditional group packages. Mobile-native booking behavior is compressing reservation lead times from months to weeks.
Market Restraints
- Aviation fuel cost volatility:Long-haul pilgrimage routes from Indonesia, Nigeria, and Pakistan to Saudi Arabia face margin compression when jet fuel prices spike. Tour operators lack fuel hedging scale.
- Quota concentration risk:Saudi Arabia's national pilgrimage quota system controls absolute visitor volumes for Mecca and Medina. Supply-side gatekeeping limits revenue scalability for international operators.
- Carbon accounting compliance:EU CSRD disclosure requirements and emerging aviation offset mandates in European source markets add reporting overhead. Smaller faith-based operators lack sustainability audit infrastructure.
Strategic Opportunities
- Secondary pilgrimage circuits:Ethiopia's Lalibela rock-hewn churches and Armenia's ecclesiastical heritage trails remain underpenetrated relative to Mediterranean or Gulf routes. Early positioning captures premium pricing before infrastructure maturation.
- Wellness-spirituality convergence:Extended-duration retreats combining Ayurvedic practice with Vedic study in Kerala and Rishikesh attract high-net-worth seekers. Programming extensions multiply per-capita revenue.
- White-label platform licensing:Asset-light franchising models allow regional parish networks and diocesan organizations to deploy branded booking interfaces without proprietary technology investment.
Industry Challenges
- Multi-faith guide certification:Operators serving interdenominational groups or multi-site itineraries face complex credentialing requirements across Catholic, Orthodox, Protestant, Islamic, Hindu, and Buddhist jurisdictions. Standardization remains fragmented.
- Legacy reservation system integration:Established pilgrimage organizers maintain decades-old group management databases. API connectivity with modern mobile booking engines requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Religious Tourism Market |
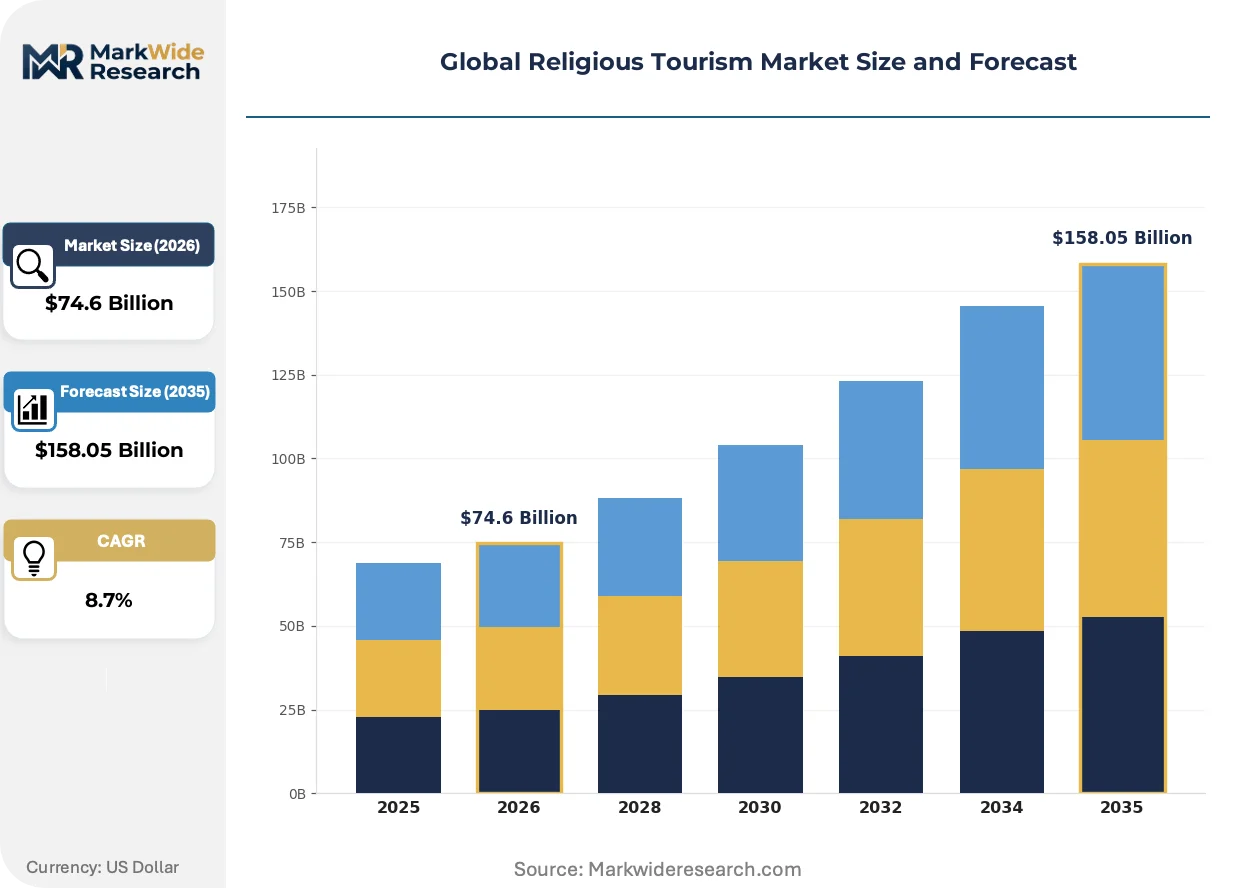
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $158.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type of Pilgrimage: Spiritual Retreats, Sacred Sites, Festivals, Cultural Events Faith-Based Identity: Christianity, Islam, Hinduism, Buddhism Travel Arrangement: Group Tours, Individual Travel, Package Deals, Self-Organized Trips Experience Type: Historic Tours, Participatory Events, Educational Trips, Scenic Journeys |
| Companies Covered | Globus Faith, Journeys Unlimited, ETS Tours, Perillo Tours, Friendship Tours, Catholic Travel Centre, Educational Opportunities, Reformation Tours, Nawas International Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Religious Tourism Market Strategic Shifts
Technology deployment in religious tourism is pivoting from passive information portals toward predictive itinerary optimization and real-time sacred site congestion management. This shift reconfigures operator value propositions and traveler expectations simultaneously.
Artificial intelligence-driven demand forecasting is hybridizing static pilgrimage calendars with dynamic pricing and capacity allocation. Faith-based tour operators in Turkey and Jordan now deploy machine learning models to predict weekly visitation patterns at Ephesus and Petra religious sites. This compression of demand uncertainty enables just-in-time contracting with local ground handlers and reduces inventory risk.
EU CSRD sustainability disclosure rules now require large European travel consolidators to report scope-three emissions from subcontracted pilgrimage aviation and ground transport. This regulatory pressure cascades through supplier tiers, forcing mid-sized operators to adopt carbon accounting software or exit corporate and institutional group contracts. Italian and Spanish diocesan travel organizers are consolidating preferred supplier lists to reduce audit complexity.
Solo spiritual travelers increasingly bypass traditional group tour intermediaries through direct-to-temple booking platforms and peer-reviewed accommodation networks. India's state-level temple boards now offer VIP darshan reservations through proprietary mobile applications, disintermediating legacy travel agents. This channel fragmentation concentrates in South Asian source markets where smartphone penetration and UPI payment infrastructure enable frictionless direct booking.
Global Religious Tourism Market Segmentation
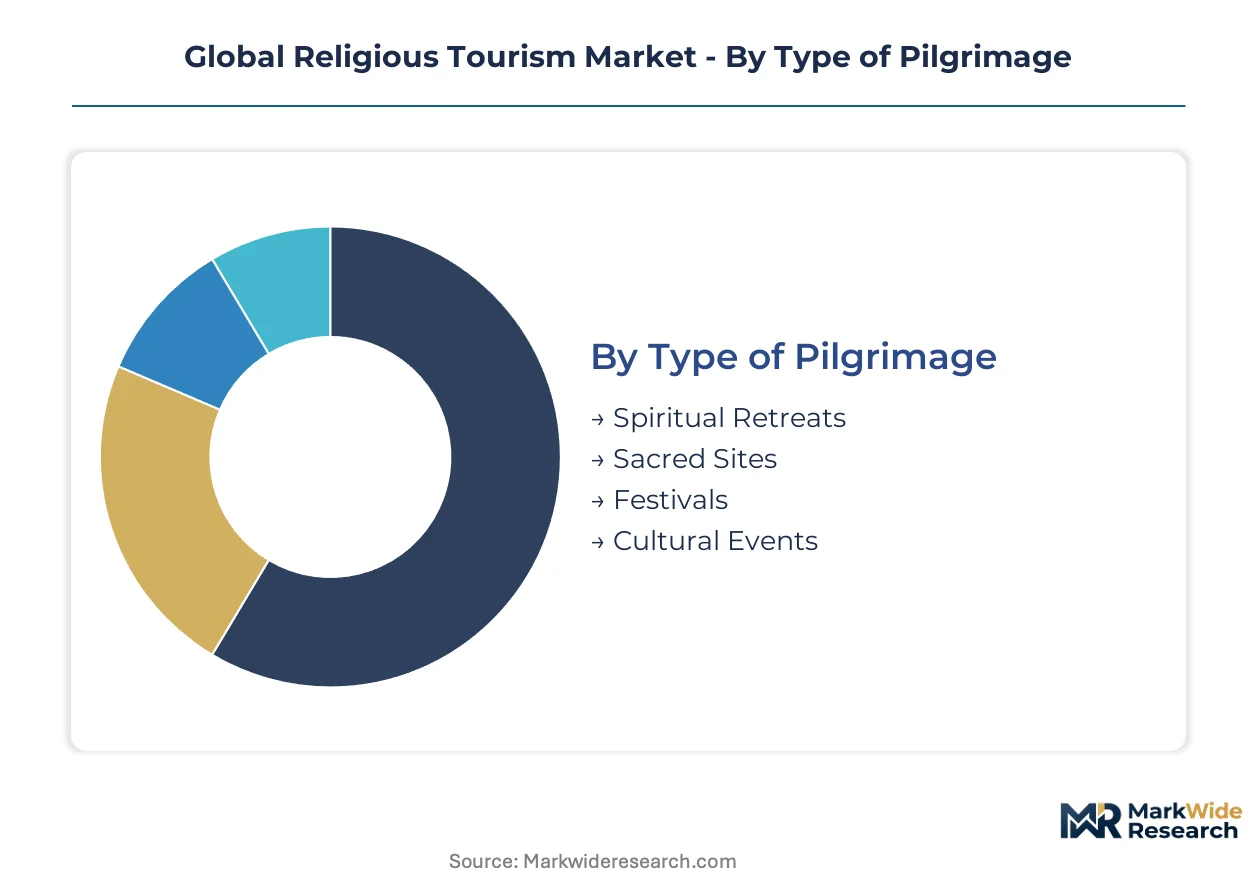
Religious tourism segmentation reveals divergent operational economics across pilgrimage formats. Tour operators calibrate inventory depth, guide certification requirements, and cancellation policies differently for each category. Understanding these structural variations determines capital allocation and partnership strategy.
Type of Pilgrimage:
Use cases span solitary contemplation to mass congregation events with radically different infrastructure demands.
- Spiritual Retreats:Extended-duration programming combines accommodation, guided practice, and ceremonial instruction in fixed-location settings. Kerala's Ayurveda-Vedic centers and Rishikesh ashrams attract high-net-worth seekers from Mumbai and Bangalore seeking wellness-spirituality convergence. Premium pricing and repeat visitation rates exceed other pilgrimage formats.
- Sacred Sites:Destination-specific travel to locations holding doctrinal significance such as Mecca, Varanasi, or Jerusalem. Saudi Arabia's Nusuk platform and India's e-visa infrastructure are compressing booking friction for repeat visitors. Mature margins and predictable demand patterns dominate this segment.
- Festivals:Time-bound mass gatherings including Kumbh Mela and Hajj requiring surge-capacity logistics. Crowd management and sanitation infrastructure determine operator viability.
- Cultural Events:Religious observances with significant secular participation such as Holy Week processions or Diwali celebrations. Broader addressable market reduces faith-specific credentialing burdens.
Established volume favors Sacred Sites; emerging adoption favors Spiritual Retreats.
Faith-Based Identity:
Credentialing requirements and destination infrastructure vary sharply across doctrinal traditions.
- Christianity:Catholic, Orthodox, and Protestant circuits each demand specialized guide certification. Mediterranean pilgrimage routes to Rome, Jerusalem, and Santiago de Compostela maintain mature operator ecosystems. Parish-based group contracting in North American dioceses anchors revenue predictability.
- Islam:Hajj and Umrah travel operates under Saudi Arabia's Ministry of Hajj and Umrah quota system with strict facility standards. Indonesian, Pakistani, and Nigerian source markets face aviation cost volatility on long-haul routes to Mecca and Medina.
- Hinduism:India's temple boards coordinate infrastructure upgrades at Varanasi, Tirupati, and Kumbh Mela sites. State-level digitization of VIP darshan bookings is disintermediating legacy travel agents.
- Buddhism:Circuits spanning Bodh Gaya, Lumbini, and Southeast Asian heritage trails attract interdenominational participation. Multi-faith guide certification complexity limits operator specialization.
Volume concentration sits with Christianity and Islam; steepest expansion trajectory appears in Hinduism as domestic Indian demand digitizes.
Travel Arrangement:
Coordination friction and margin structure differentiate booking modalities.
- Group Tours:Bulk contracting power with hotels near sacred sites generates predictable occupancy rates. Parish partnerships and institutional relationships anchor revenue.
- Individual Travel:Mobile-native booking behavior is compressing reservation lead times from months to weeks. Solo spiritual travelers increasingly bypass intermediaries through direct-to-temple platforms.
- Package Deals:Bundled transportation, lodging, and ceremonial access reduce coordination burden for first-time pilgrims. Standardized offerings sacrifice customization for operational efficiency.
- Self-Organized Trips:Peer-reviewed accommodation networks and proprietary temple board applications enable frictionless direct booking. Channel fragmentation concentrates in South Asian markets with high smartphone penetration.
Revenue scale favors Group Tours; share gain favors Individual Travel.
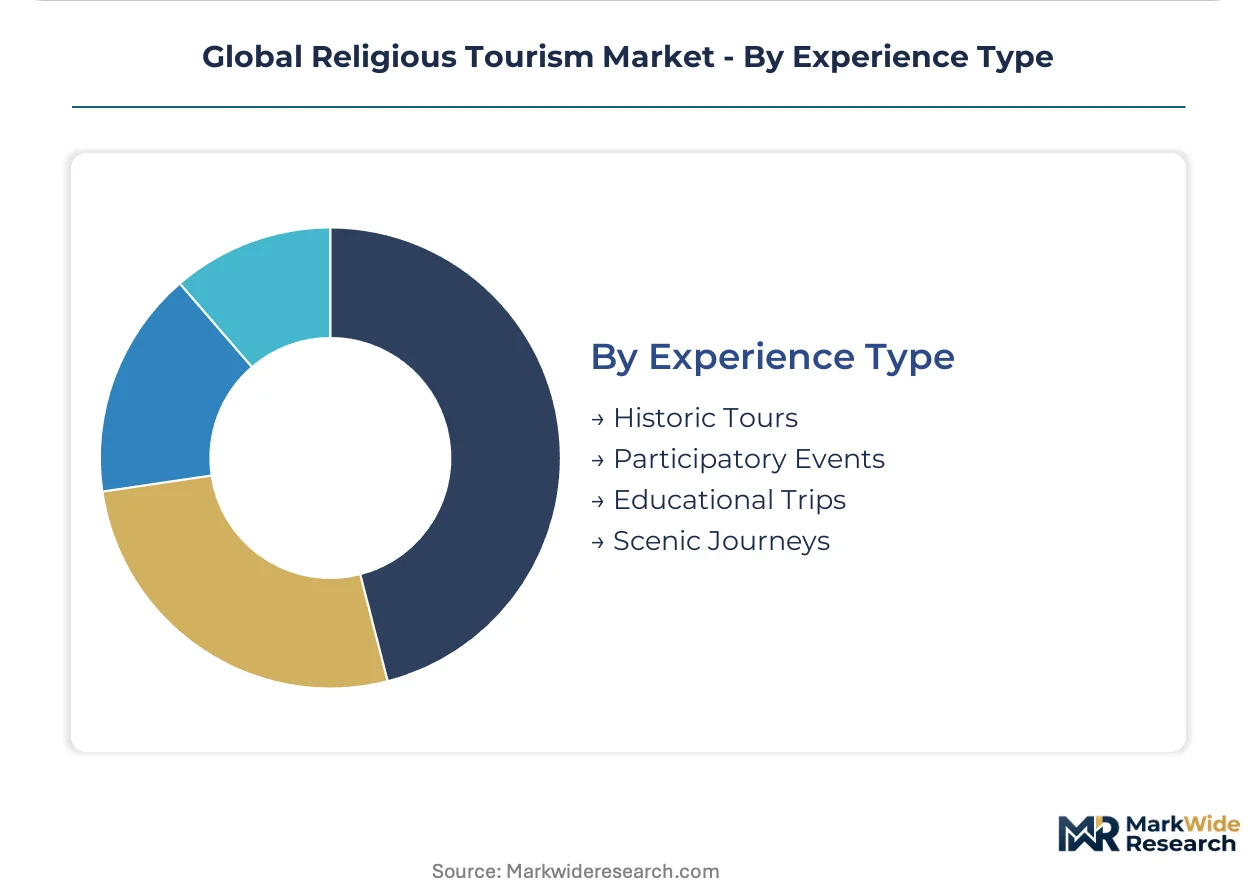
Experience Type:
Programming depth and educational content intensity determine pricing tiers.
- Historic Tours:Structured itineraries emphasizing architectural heritage and doctrinal history. UNESCO World Heritage designation influences preservation funding and visitor management protocols.
- Participatory Events:Active ritual involvement including mass, prayer ceremonies, or purification rites. Access permissions and clergy coordination requirements elevate operational complexity.
- Educational Trips:Curated study programs combining site visits with theological instruction. Reformation heritage trails across Central European sites exemplify this format.
- Scenic Journeys:Nature-integrated pilgrimage routes such as Camino de Santiago or Himalayan circuits. Extended duration multiplies ancillary revenue opportunities.
Margin stability favors Historic Tours; premium pricing expansion favors Educational Trips.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilgrimage pricing power concentrates in Saudi Arabia's quota-controlled Mecca-Medina corridor, while Indian temple towns compete on volume-driven spiritual tourism packages with thinner margins.
Saudi Arabia
Umrah and Hajj travel generates premium yields through the Ministry of Hajj and Umrah's Nusuk digital platform, which unifies permits, accommodation, and health verification. The quota system caps absolute visitor volumes but protects pricing integrity for authorized operators. Jeddah and Medina anchor the western logistics corridor where hospitality procurement concentrates around the Haramain high-speed rail termini.
India
Domestic spiritual travel dominates volume through Varanasi's Kashi Vishwanath corridor, Tirupati's Venkateswara temple circuit, and Rishikesh's ashram clusters. The Ministry of Tourism coordinates with Uttar Pradesh and Andhra Pradesh state boards to upgrade Kumbh Mela sanitation infrastructure. Kerala's Ayurveda-Vedic retreat centers in Kochi and Thiruvananthapuram capture premium pricing from Mumbai and Bangalore high-net-worth seekers.
Italy
Catholic pilgrimage circuits through Rome, Assisi, and San Giovanni Rotondo sustain mature operator ecosystems serving North American parish groups. The Vatican's Pontifical Council for the Pastoral Care of Migrants and Itinerant People influences ceremonial access protocols. Florence and Venice anchor secondary heritage trails where Reformation history programming attracts interdenominational participation.
Israel
Multi-faith visitation to Jerusalem's Old City, Bethlehem, and Nazareth generates year-round demand across Christian, Jewish, and Islamic circuits. The Ministry of Tourism coordinates security protocols with the Israel Police for peak-season religious festivals. Tel Aviv's Ben Gurion Airport serves as the primary aviation gateway where European and North American charter operators maintain seasonal capacity contracts.
Turkey
Ephesus and Cappadocia circuits combine early Christian heritage with Islamic devotional sites for interdenominational group programming. The Ministry of Culture and Tourism allocates preservation funding through UNESCO World Heritage designation processes. Istanbul anchors the logistics hub where Bosporus-crossing itineraries connect European and Asian sacred site circuits.
Global Religious Tourism Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ground handling and ceremonial access contracting. The operator base fragments across diocesan partnerships, parish networks, and direct-to-pilgrim digital channels. Three archetypes dominate: quota-licensed Hajj-Umrah specialists, parish-anchored Catholic tour organizers, and wellness-spirituality retreat curators. Competitive moves concentrate on white-label platform licensing and exclusive accommodation contracting near sacred sites.
Within the parish-partnership tier, Nawas International Travel and Catholic Travel Centre exemplify diocesan-anchored business models. Friendship Tours occupies a position in heritage-trail specialization. These operators represent how geographic concentration and credentialing relationships determine competitive position without scale-driven consolidation.
| Leading Market Players |
|---|
| Globus Faith |
| Journeys Unlimited |
| ETS Tours |
| Perillo Tours |
| Friendship Tours |
| Catholic Travel Centre |
| Educational Opportunities |
| Reformation Tours |
| Nawas International Travel |
| Others |
Value Chain & Pricing Dynamics
The Haramain high-speed rail corridor connecting Jeddah to Mecca and Medina concentrates ground transport costs for pilgrimage logistics, with freight rates directly shaping operator margin structures across premium, standard, and economy service tiers while Saudi Arabia's Nusuk visa integration compresses booking friction and intensifies price competition among authorized tour operators.
Pricing Analysis
Group tour operators anchor contract-based pricing through bulk accommodation procurement near sacred sites, with differentiation driven by VIP darshan access tiers and ground handler certification levels. Cost compression in economy pilgrimage packages is intensifying because India's state temple boards now offer direct-to-pilgrim mobile bookings that bypass traditional intermediaries. Corporate diocesan clients exhibit lowest price sensitivity due to parish-funded institutional travel, while solo millennial travelers demonstrate highest elasticity as they comparison-shop across fragmented digital platforms.
Supply Chain Analysis
Upstream aviation capacity feeds from Saudi Arabia, India, and Turkey as dominant hub countries for pilgrimage route consolidation. Jet fuel procurement, hotel block contracting, and ground handler certification rest on long-haul carrier relationships and seasonal capacity agreements. Single-source vulnerability concentrates in Saudi Arabia's Ministry of Hajj and Umrah quota licensing system, which controls absolute operator authorization volumes. Distribution runs through diocesan partnership networks, digital booking platforms, and direct temple board applications in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global religious tourism market sits at a high-growth inflection as Saudi Arabia's Nusuk platform and India's e-visa digitization simultaneously compress coordination cycles and fragment demand across micro-segments, creating asymmetric opportunity for technology-advantaged operators.
For Market Incumbents: Insulate parish partnership revenue through exclusive multi-year diocesan contracting and deepen backward integration into ground handler certification programs to offset disintermediation risk from direct-to-temple booking platforms. Priority investment in API connectivity with legacy group management databases addresses the middleware gap threatening operational efficiency. For New Entrants and Emerging Players: Build out white-label platform licensing to regional parish networks seeking branded digital interfaces without proprietary technology development, targeting North American diocesan organizations as the most penetrable incumbent-anchored segment. Go-to-market positioning should emphasize wellness-spirituality convergence programming for high-net-worth millennial seekers in Kerala and Rishikesh. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-light platform integrators with established supplier networks over capital-intensive hospitality operators, with long-term viability hinging on carbon accounting compliance infrastructure for EU CSRD disclosure cascade. Acquisition target archetype: mid-sized operators with exclusive sacred site access permits and underutilized digital booking capabilities. Signal to watch: quota liberalization announcements from Saudi Arabia's Ministry of Hajj and Umrah indicating addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Nusuk API connectivity unifies visa permits, accommodation, and health verification for authorized operators. |
| Backward Integration | Exclusive ground handler certification programs reduce dependency on fragmented local supplier markets. |
| Geographic Expansion | Early positioning in Ethiopia's Lalibela and Armenia's ecclesiastical trails captures pre-infrastructure premium pricing. |
| Strategic Partnership | Diocesan network consolidation reduces customer acquisition cost for repeat parish group contracting. |
| Sustainability Repositioning | Carbon accounting software adoption maintains EU corporate contract eligibility under CSRD disclosure rules. |
Study Parameters
The analysis maps pilgrimage type segmentation, faith-based identity categories, and travel arrangement modalities, each validated through primary interviews with tour operator executives, diocesan travel coordinators, ground handling specialists, and digital platform engineers, combined with secondary triangulation across Saudi Ministry of Hajj and Umrah policy filings, Indian Ministry of Tourism infrastructure investment disclosures, UNESCO World Heritage designation records, and aviation capacity data from IATA and airport authority sources.
Forecast assumptions held visa digitization rollout timelines and carbon accounting regulatory scope fixed while varying pilgrimage quota allocations, generational demand rotation velocity, and secondary circuit infrastructure maturation across the projection horizon. Segmentation dimensions modeled include pilgrimage format, doctrinal tradition, booking modality, and experience depth, with CAGRs derived from bottom-up operator revenue aggregation and top-down addressable market penetration analysis, incorporating jet fuel price volatility indices and smartphone penetration curves as industry-specific inputs.
Sensitivities concentrate around Saudi quota policy shifts, EU CSRD enforcement stringency, and aviation fuel cost spikes as primary revision triggers. Forecasts reflect documented assumptions regarding generational booking behavior transition and platform disintermediation velocity. Material shifts in pilgrimage permit allocation frameworks or carbon offset mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market