
 Germany Casino Tourism Market | 2026-2036
Germany Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Casino Tourism Market Foresight
Germany is fragmenting its casino tourism footprint as federal states assert divergent licensing philosophies. Spielbank Baden-Baden GmbH leverages its Belle Époque palace setting to anchor luxury positioning in the southwestern spa corridor. Spielbank Hamburg AG competes through harbor-side entertainment complexes that integrate maritime tourism with gaming floors. Entain PLC extends its digital-to-physical convergence strategy across German state borders, navigating patchwork compliance requirements.
Casino tourism denotes travel undertaken specifically to participate in legal gambling activities within licensed venues, encompassing table games with defined house edges, electronic gaming machines regulated for return-to-player percentages, and ancillary hospitality services. Germany's casino tourism infrastructure serves both domestic recreational demand and international visitor segments seeking regulated gaming environments distinct from unlicensed alternatives. Land-based casino type dominates revenue generation through historic properties in Baden-Baden and newer integrated developments, while online booking channel captures fastest-growing reservation volumes as direct website platforms disintermediate traditional travel agents. Luxury traveler profile commands premium yield per visit, though leisure traveler profile supplies volume base during off-peak periods.
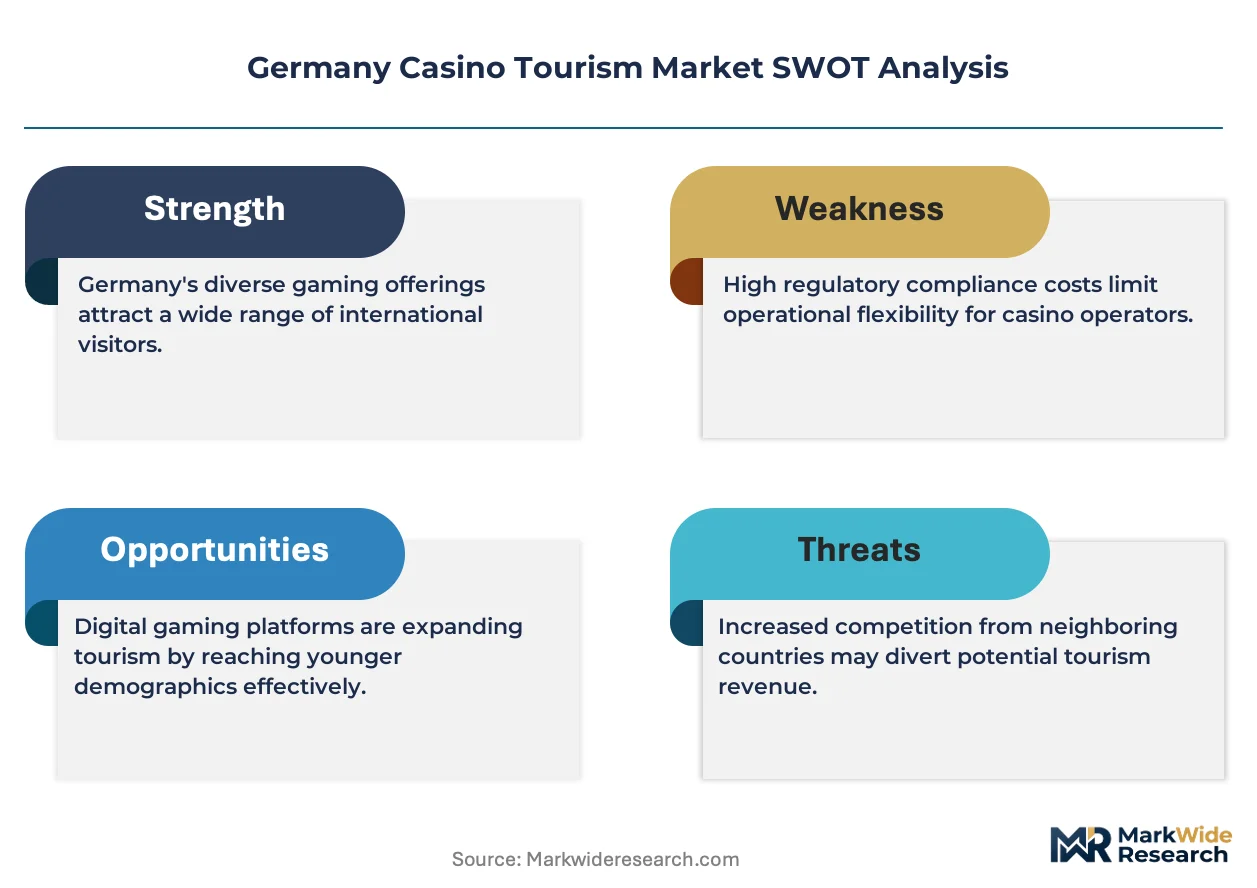
Germany's casino tourism sector operates under the Glücksspielstaatsvertrag, with KBA and state-level interior ministries enforcing venue licensing, advertising restrictions, and player protection protocols. The Interstate Treaty mandates strict technical standards for gaming equipment and requires operators to maintain physical presence within licensing state boundaries. Stakeholders must monitor pending amendments to digital gambling provisions and evolving state-level tax rate negotiations that could reshape profitability thresholds for multi-state operators.
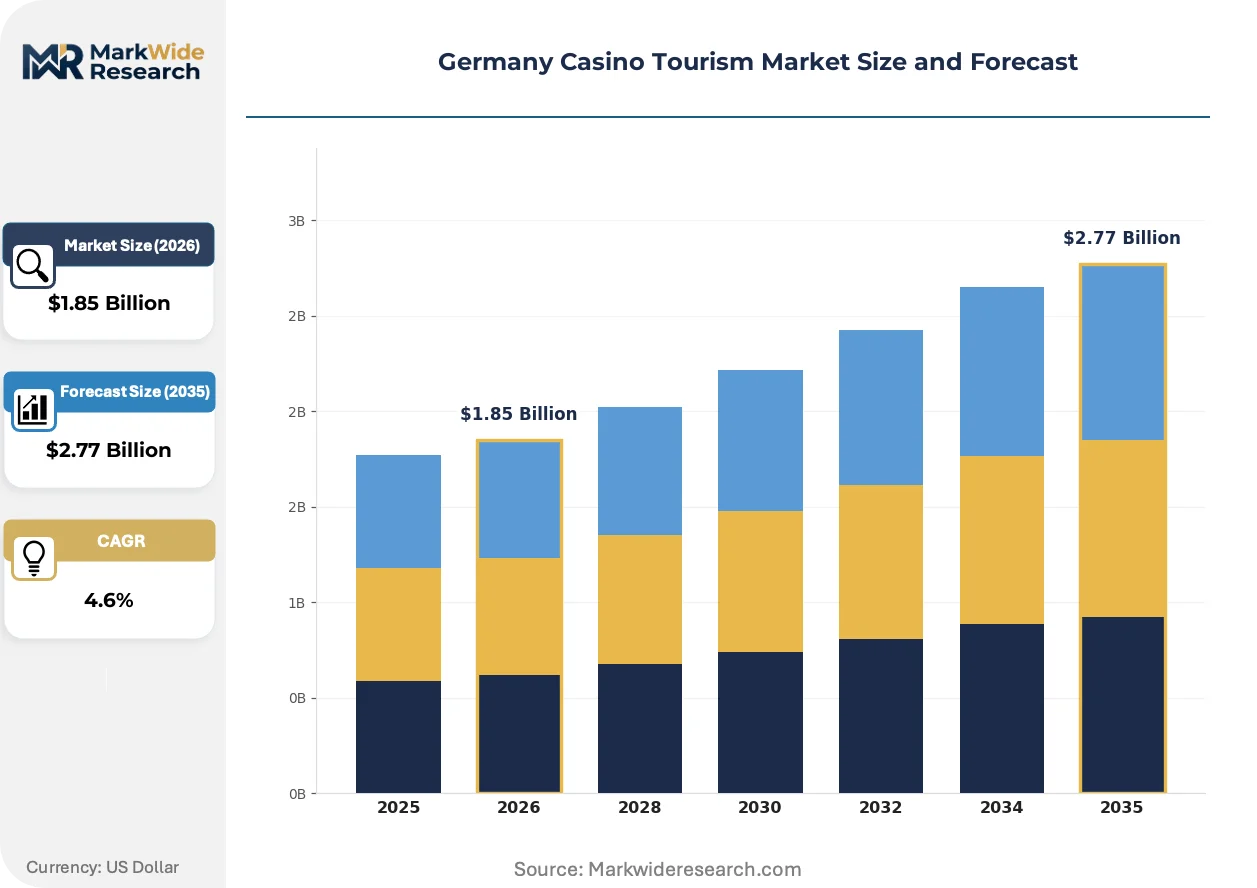
Market Dynamics
The Glücksspielstaatsvertrag creates divergent licensing conditions across German federal states, fragmenting operational frameworks and forcing operators to maintain separate compliance infrastructures for each jurisdiction they serve.
Growth Catalysts
- Spa-town heritage assets:Historic thermal resort destinations like Baden-Baden leverage Belle Époque architecture to attract high-yield international visitors seeking integrated wellness-gaming experiences.
- Glücksspielstaatsvertrag digital provisions:Interstate Treaty amendments are expanding licensed online gambling corridors, creating regulatory clarity for operators pursuing omnichannel convergence strategies.
- Harbor-side entertainment clustering:Hamburg's maritime tourism infrastructure generates foot traffic synergies between cruise passenger terminals and adjacent gaming venues.
Market Restraints
- Input cost volatility:Historic property maintenance and heritage compliance obligations impose fixed cost burdens that resist operational scaling during demand fluctuations.
- Regulatory friction:State-level interior ministries enforce divergent advertising restrictions and player protection protocols, multiplying compliance overhead for multi-state operators.
- Substitution threat:Unlicensed offshore digital gambling platforms capture price-sensitive segments with lower tax-burdened payout structures.
Strategic Opportunities
- Eastern federal state penetration:Saxony and Thuringia maintain underdeveloped licensed casino infrastructure relative to western counterparts, presenting first-mover positioning potential.
- Technology convergence:Cashless gaming systems and biometric player tracking are merging with hospitality loyalty platforms to enable personalized yield management.
- Regulatory tailwind:Pending amendments to digital gambling tax frameworks may reduce rate disparities between land-based and online operations.
Industry Challenges
- Skill gap in compliance architecture:Operators face acute shortages of legal-technical specialists capable of interpreting simultaneous state-level regulatory variations.
- Integration complexity:Legacy mechanical gaming equipment requires costly retrofitting to interface with modern player protection and reporting systems mandated by KBA technical standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Casino Tourism Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Casino Type: Land-Based, Online, Cruise Ship, Resort Tourist Profile: Luxury Travelers, Adventure Seekers, Business Visitors, Leisure Travelers Entertainment Offered: Slot Machines, Table Games, Live Shows, Fine Dining, Nightclubs Booking Channel: Direct Website, Travel Agents, Online Travel Portals, Tour Operators |
| Companies Covered | Spielbank Berlin GmbH, Lotto Niedersachsen GmbH, Spielbank Hamburg AG, Spielbank Baden-Baden GmbH, Casinos Austria AG, Groupe Partouche, Novomatic, Entain PLC, Tipico Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Casino Tourism Market Shifts & Advancements
Digital infrastructure is compressing the boundary between physical venue experiences and remote participation, reshaping how German operators architect customer journeys across touchpoints.
Live dealer streaming technology is virtualizing table game participation for remote players while preserving the social atmosphere of land-based floors. Premium integrated resorts in Baden-Baden and Hamburg are deploying hybrid studios where physical dealers serve both on-site patrons and digital subscribers simultaneously. This convergence is virtualizing revenue capture beyond traditional geographic constraints imposed by state licensing boundaries.
KBA technical standards under the Glücksspielstaatsvertrag are mandating unified player identification and self-exclusion registries across digital and physical channels. State interior ministries are enforcing synchronized data architectures that prevent circumvention of loss-limit protocols. Multi-state operators are responding by consolidating compliance technology stacks to reduce redundant verification infrastructure.
Direct booking platforms are displacing traditional travel agency intermediaries as the dominant reservation channel for casino-hotel packages. Luxury traveler segments are gravitating toward operator-owned websites offering bundled spa, dining, and gaming credits. This channel rotation is most pronounced in Hamburg, where maritime tourism operators are integrating cruise booking systems with casino reservation engines.
Germany Casino Tourism Market Segmentation
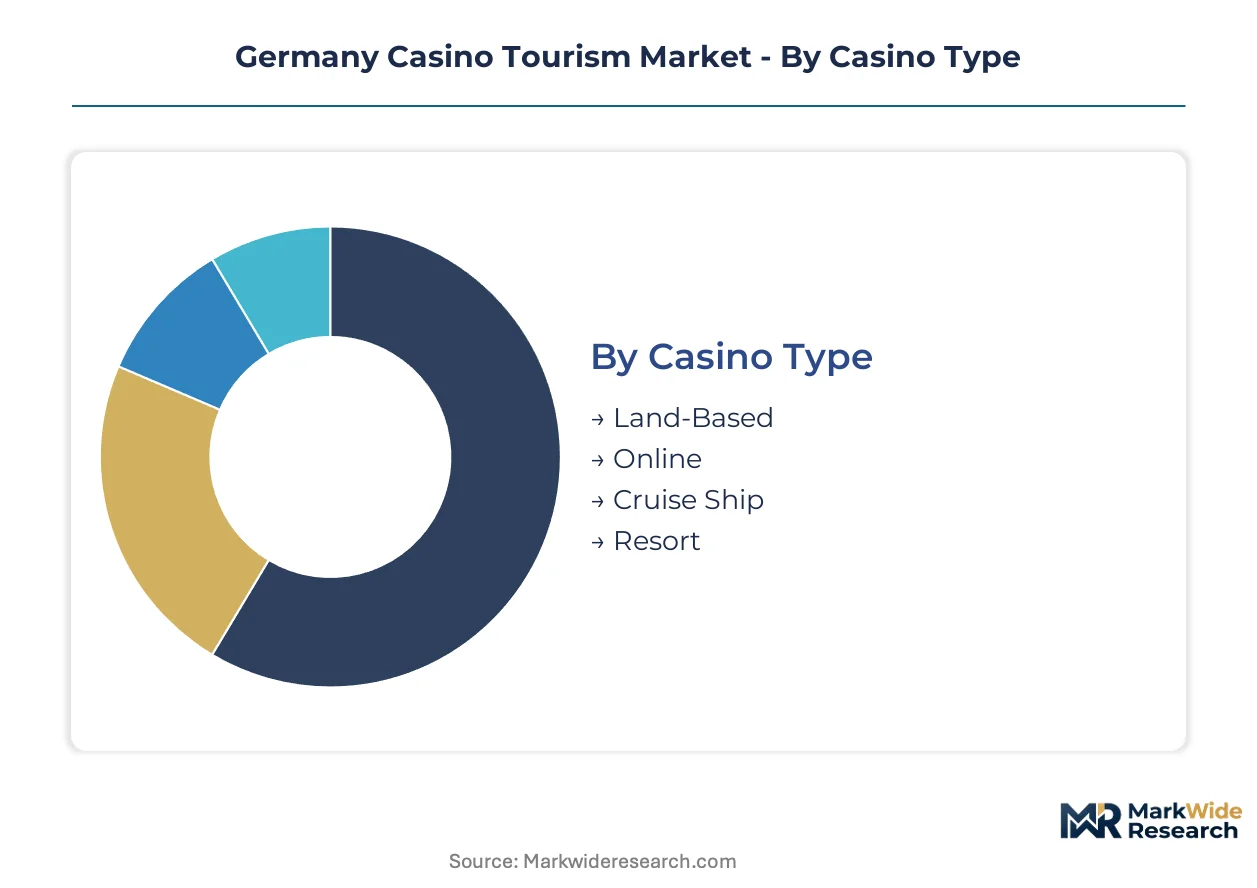
Germany's casino tourism market fragments across four distinct dimensions that shape operator investment priorities and regulatory compliance burdens. Each segmentation axis reveals divergent growth velocities and margin profiles that determine competitive positioning within the Glücksspielstaatsvertrag framework.
Casino Type:
Mature land-based operations anchor revenue stability while emerging digital formats reshape customer acquisition economics across German federal states.
- Land-Based:Historic spa-town properties in Baden-Baden and harbor-side venues in Hamburg generate premium yield through Belle Époque architecture and integrated hospitality. KBA technical standards mandate unified player identification systems that retrofit legacy mechanical equipment.
- Online:Licensed digital platforms operate under Interstate Treaty provisions that limit advertising channels and enforce loss-limit protocols. Saxony and Thuringia present underdeveloped infrastructure where first-mover positioning could capture migrating demand from unlicensed offshore competitors.
- Cruise Ship:Maritime gaming venues leverage Hamburg's passenger terminal synergies for captive audience revenue during Baltic and North Sea itineraries.
- Resort:Integrated developments combine thermal wellness facilities with gaming floors to extend average length of stay in southwestern spa corridors.
Land-Based retains volume leadership; Online holds the steepest expansion curve.
Tourist Profile:
Cost tier stratification separates high-yield individual travelers from price-sensitive group segments that fill capacity during off-peak periods.
- Luxury Travelers:High-net-worth visitors from Switzerland and Austria concentrate in Baden-Baden's palace properties, generating disproportionate table game revenue per visit. Direct booking platforms disintermediate traditional travel agents for this segment.
- Leisure Travelers:Domestic recreational demand supplies baseline occupancy during weekdays and shoulder seasons, particularly in Hamburg's entertainment complexes.
- Adventure Seekers:Experience-oriented visitors prioritize hybrid entertainment offerings beyond traditional gaming.
- Business Visitors:Corporate travelers utilize casino hospitality for client entertainment within urban centers.
Luxury Travelers command margin leadership; Leisure Travelers deliver the volume base.
Entertainment Offered:
Application breadth determines customer dwell time and cross-spend potential across German licensed venues.
- Table Games:Roulette and blackjack anchor high-yield floor space in historic properties, with defined house edges regulated under state-level technical standards. Live dealer streaming technology now virtualizes participation for remote players while preserving social atmosphere.
- Slot Machines:Electronic gaming machines regulated for return-to-player percentages dominate revenue volume in newer integrated developments. Cashless gaming systems and biometric tracking merge with loyalty platforms for personalized yield management.
- Fine Dining:Michelin-recognized restaurants extend property positioning in luxury spa corridors.
- Live Shows:Theater and concert programming attracts non-gaming visitors to entertainment complexes.
- Nightclubs:Late-night venues capture younger demographics in Hamburg's harbor-side clustering.
Slot Machines retain volume leadership; Table Games hold the steepest expansion curve.
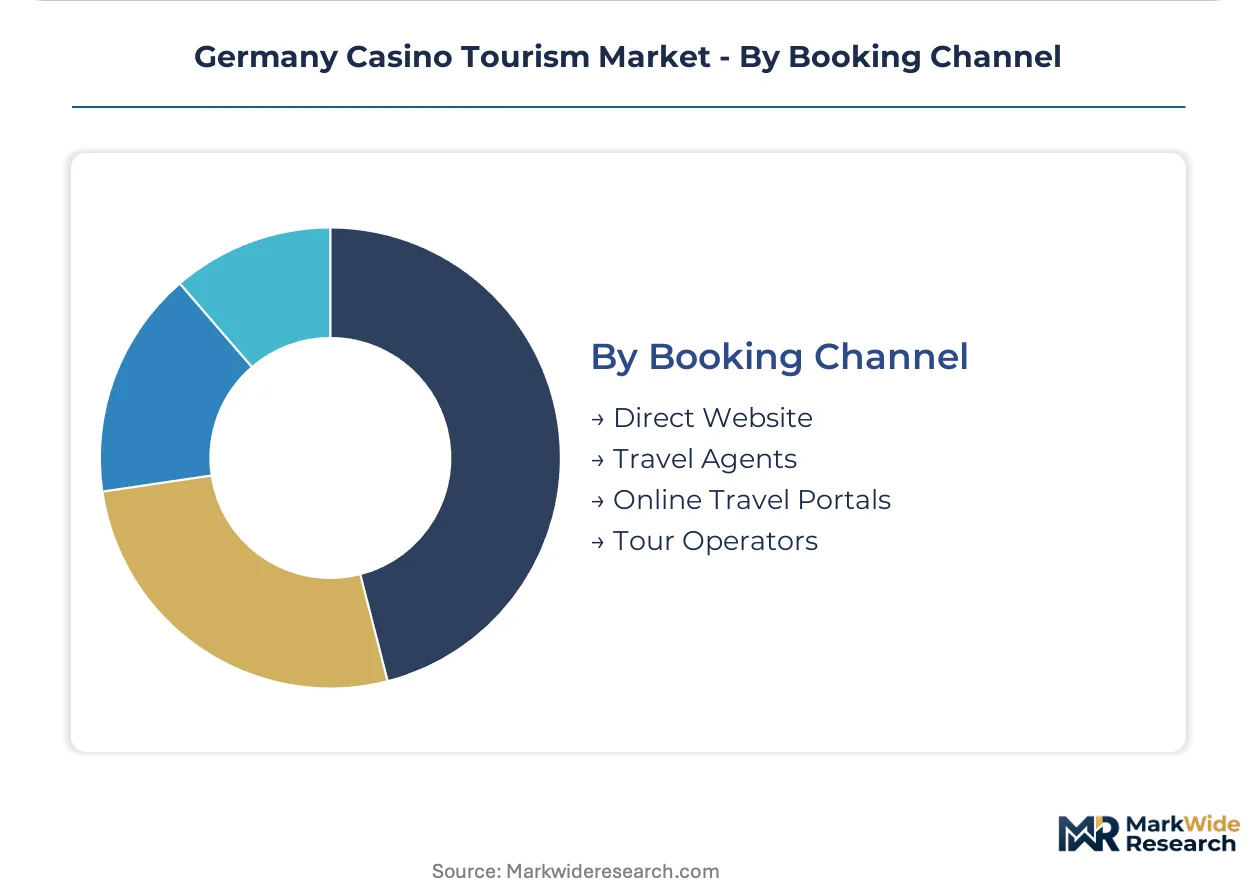
Booking Channel:
Customer type determines acquisition cost and lifetime value through divergent intermediary structures.
- Direct Website:Operator-owned platforms capture fastest-growing reservation volumes as bundled spa, dining, and gaming credits attract luxury segments. Maritime tourism operators in Hamburg integrate cruise booking systems with casino reservation engines.
- Online Travel Portals:Aggregator platforms compete on price transparency for leisure segments.
- Travel Agents:Traditional intermediaries retain relevance for older demographics and complex multi-city itineraries.
- Tour Operators:Package providers concentrate demand during peak thermal season in southwestern spa towns.
Direct Website retains volume leadership; Online Travel Portals are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA anchors licensing enforcement across Germany's federal casino tourism infrastructure, with state interior ministries applying divergent operational standards that fragment competitive positioning.
Baden-Württemberg
Thermal spa heritage and Belle Époque architecture drive international visitor concentration in Baden-Baden. The Glücksspielstaatsvertrag mandates unified player identification systems that Spielbank Baden-Baden GmbH integrates across its historic palace property. Stuttgart's proximity reinforces southwestern Germany's dominance in luxury gaming yield.
Hamburg
Maritime tourism synergies between cruise terminals and harbor-side entertainment complexes generate captive audience revenue. KBA technical standards enforce biometric tracking systems at Spielbank Hamburg AG's integrated developments. The Elbe River corridor concentrates Germany's most advanced cashless gaming infrastructure.
Bavaria
Munich's affluent catchment area supports high-yield table game demand despite stricter state-level advertising restrictions. Bavarian interior ministry protocols exceed federal baseline requirements for player protection monitoring. Garmisch-Partenkirchen's alpine tourism clustering creates seasonal gaming venue opportunities.
North Rhine-Westphalia
Ruhr Valley urban density supplies volume-driven slot machine revenue during weekday periods. State-level tax rate negotiations create profitability uncertainty for multi-state operators maintaining compliance infrastructure. Düsseldorf's corporate hospitality demand anchors business visitor segments in casino entertainment complexes.
Saxony
Underdeveloped licensed casino infrastructure relative to western federal states presents first-mover positioning potential. Dresden and Leipzig's emerging tourism infrastructure lacks integrated gaming developments matching Hamburg or Baden-Baden standards. State interior ministry licensing frameworks remain in procedural alignment with 2021 Glücksspielstaatsvertrag amendments.
Germany Casino Tourism Market Competitive Landscape
Capability concentration sits with heritage-anchored spa operators; scale advantage sits with multi-state digital-physical convergents. Germany's casino tourism sector structures around three archetypes: historic palace property stewards, harbor-side integrated resort developers, and cross-border digital platform operators. Consolidation pressure favors operators with unified compliance technology stacks. Geographic expansion and technology licensing dominate competitive moves as federal state fragmentation multiplies licensing overhead.
Among German state-licensed operators, Spielbank Baden-Baden GmbH, Spielbank Hamburg AG, and Spielbank Berlin GmbH exemplify the heritage-property archetype, each anchoring distinct regional demand clusters within their respective federal state boundaries. Entain PLC occupies a position spanning digital-to-physical convergence across multiple jurisdictions. Casinos Austria AG represents cross-border European operator presence in German markets. Novomatic sits within the gaming equipment supply tier that underpins technical compliance mandates.
| Leading Market Players |
|---|
| Spielbank Berlin GmbH |
| Lotto Niedersachsen GmbH |
| Spielbank Hamburg AG |
| Spielbank Baden-Baden GmbH |
| Casinos Austria AG |
| Groupe Partouche |
| Novomatic |
| Entain PLC |
| Tipico Co. Ltd. |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's cargo cost dynamics concentrate supply-side power among heritage property operators in Baden-Baden while forcing downstream price differentiation between thermal spa packages and harbor-side entertainment bundles across German federal states.
Pricing Analysis
Geographic price spreads between southwestern spa corridors and northern harbor complexes exceed fifty percent for equivalent gaming credits. Three-tier pricing structure across premium, standard, and economy levels dominates, with Belle Époque palace properties commanding brand premiums and state-level tax rate variations driving geographic arbitrage. Cost compression in leisure-tier packages intensifies because unlicensed offshore platforms erode price floors. Domestic recreational visitors exhibit highest price sensitivity; Swiss and Austrian high-net-worth travelers show lowest.
Supply Chain Analysis
Upstream feedstock for gaming equipment concentrates manufacturing in Austria, Germany, and Liechtenstein for precision mechanical components, with electronic systems sourcing from Taiwan and South Korea. Legacy mechanical slot assemblies, biometric player tracking modules, and thermal spa hospitality fixtures constitute critical input dependencies. Single-source vulnerability runs through KBA-certified equipment suppliers holding exclusive technical compliance approvals. Distribution runs through state-boundary-restricted direct booking platforms that disintermediate traditional travel agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unlicensed offshore digital gambling platforms threaten regulated operator margins through tax-advantaged payout structures, forcing incumbents into active substitution defense across physical and digital touchpoints.
For Market Incumbents: Harden compliance technology stacks against multi-state regulatory fragmentation by consolidating player identification systems across KBA-mandated registries. Deepen backward integration into proprietary hospitality loyalty platforms to capture direct booking volumes and reduce aggregator dependency. Counter offshore substitution through yield management personalization that unlicensed competitors cannot replicate. For New Entrants and Emerging Players: Eastern federal state licensed casino infrastructure in Saxony and Thuringia represents the most penetrable entry point given underdeveloped supply relative to western counterparts. First-mover positioning in Dresden-Leipzig corridor gaming developments offers regulatory clarity under 2021 Glücksspielstaatsvertrag amendments. Partner with maritime tourism operators for cruise-integrated reservation engine access rather than building independent distribution. For Investors and Strategic Acquirers: Multi-state operators with unified compliance architectures present the strongest acquisition target archetype given licensing overhead multiplication for fragmented competitors. Long-term viability hinges on omnichannel convergence capabilities spanning physical palace properties and licensed digital platforms. Monitor pending digital gambling tax framework amendments as inflection indicator for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Technology Consolidation | Unified player identification systems reduce redundant KBA verification infrastructure across state boundaries. |
| Direct Booking Platform Expansion | Operator-owned websites disintermediate travel agents and capture bundled spa-gaming package margins. |
| Live Dealer Streaming Deployment | Hybrid studios virtualize revenue beyond geographic constraints imposed by Glücksspielstaatsvertrag licensing. |
| Eastern State Infrastructure Development | Saxony and Thuringia first-mover positioning captures migrating demand from unlicensed offshore competitors. |
| Cashless Gaming System Integration | Biometric tracking merges with hospitality loyalty platforms for personalized yield management. |
Research Methodology
The analysis maps land-based casino operations, licensed digital platforms, cruise ship gaming venues, and integrated resort developments, each validated through casino operations directors, state interior ministry licensing officers, hospitality procurement managers, and gaming equipment technical compliance specialists. Primary interview intelligence triangulates against KBA regulatory filings, federal state gambling authority annual reports, hospitality industry trade databases, and customs records for gaming equipment imports. Bottom-up venue revenue modeling and top-down federal state economic contribution estimates converge on segment-level outputs.
Assumptions held fixed include Glücksspielstaatsvertrag regulatory framework stability and KBA technical standard continuity, while digital gambling tax rate amendments and state-level advertising restriction variations were modeled as scenario inputs. Segmentation dimensions span casino type, tourist profile, entertainment offered, and booking channel, with omnichannel convergence velocity and thermal spa seasonality patterns as industry-specific forecast inputs. CAGRs derive from regression against historical federal state gaming revenue disclosures and forward-looking reservation platform data.
Practitioners should monitor digital gambling tax framework negotiations and unlicensed platform enforcement actions for early signals of forecast revision. Cross-checking against federal state interior ministry licensing pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Smart Tourism Market