
 Rural Tourism Market | 2026-2036
Rural Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Rural Tourism Market Analytics
Aftermarket service revenue from experience curation and local guide networks is fragmenting across digital platforms and property-level operators. Airbnb Inc. leverages host education tools to sustain booking density in remote locations. Booking.com B.V. anchors its rural inventory through dedicated landing pages and filter taxonomy. Marriott International Inc. competes via its Tribute Portfolio farm-stay collection, repositioning heritage properties as experiential destinations.
Rural tourism encompasses travel to non-urban areas where visitors engage with agricultural landscapes, indigenous ecosystems, and host-community livelihoods, typically involving lodging with fewer than fifty rooms and direct revenue sharing with local populations. The activity type segment shows hiking and wine tasting commanding premium pricing due to seasonality constraints and certified guide requirements, while bird watching attracts longer-duration stays with lower per-night spend. Eco-lodges within the accommodation type category carry the highest capital intensity but also the strongest rate premiums, whereas bed and breakfast operations dominate unit count through conversion of existing rural housing stock.
The EU Green Deal and F-Gas Regulation impose energy-performance thresholds on rural hospitality infrastructure, while REACH chemical standards govern cleaning and maintenance supplies used in farm-stay properties. USDA conservation easement programs in the United States create tax-advantaged structures for landowners operating agritourism enterprises. Stakeholders must monitor evolving carbon-accounting rules for scope-three visitor travel and assess whether on-site renewable generation justifies the capex against shifting certification schemes.
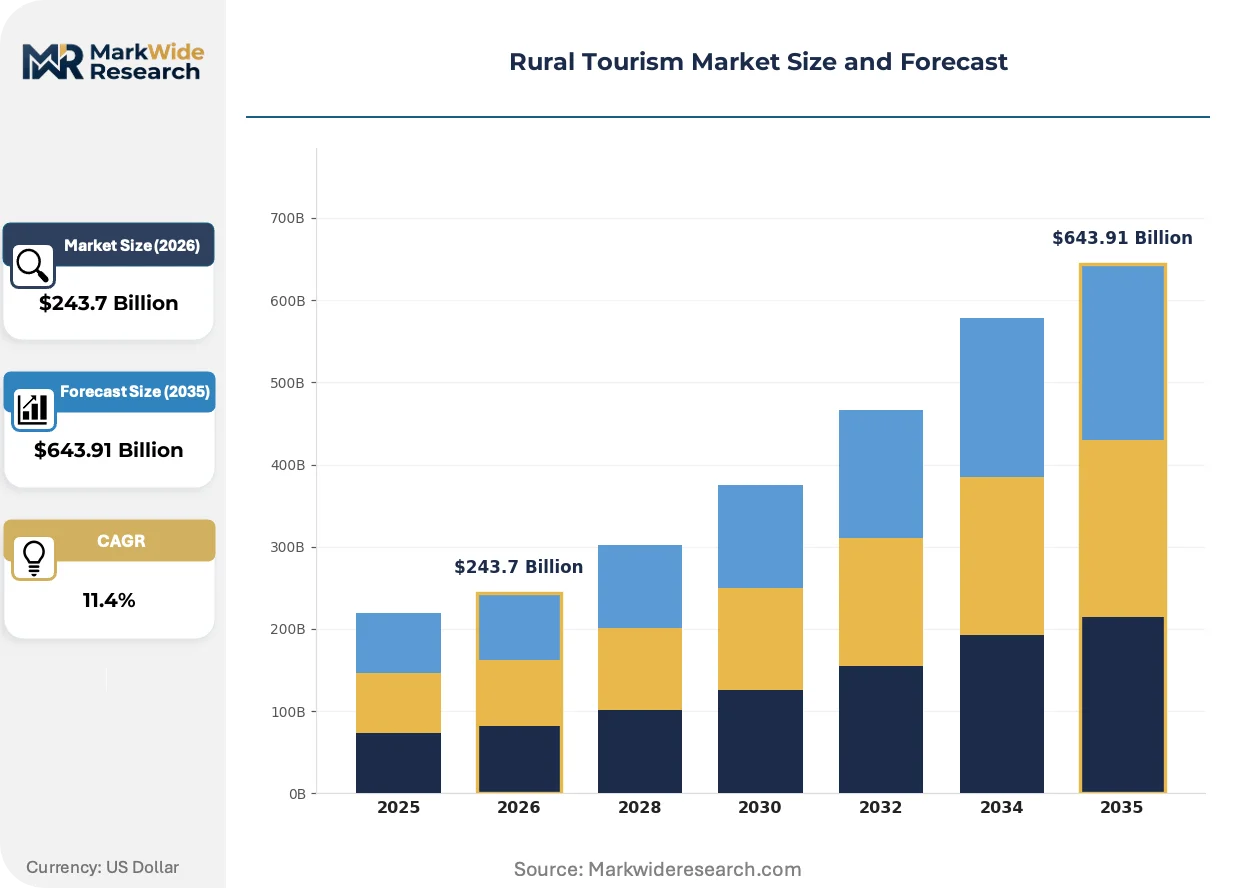
Market Dynamics
The EU Green Deal's carbon-neutral hospitality mandates are forcing property-level capital deployment into renewable generation and energy-performance retrofits, restructuring competitive advantage around certification rather than location alone.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants accelerates heat-pump adoption in rural lodging, creating retrofit demand for HVAC contractors and equipment suppliers.
- Millennial family travel patterns:Experiential travel preferences pull demand toward wine-country clusters like Portugal's Alentejo region, where agritourism density supports guide-network effects.
- USDA conservation easements:Tax-advantaged structures for agritourism operators lower land-carrying costs and extend investment horizons for heritage property conversions.
Market Restraints
- Grid interconnection delays:Rural properties face 18-36 month queues for renewable export capacity in Spain and Italy, trapping capex in permitting.
- Seasonal demand compression:Hiking and wine-tasting revenue concentrates in Q2-Q3, forcing annualized pricing that excludes budget segments.
- Specialized labor scarcity:Certified ecological guides and permaculture-trained hospitality staff command premium wages that erode rate margins.
Strategic Opportunities
- Carbon-accounting services:Scope-three visitor travel tracking creates white space for software vendors integrating booking platforms with offset marketplaces.
- Extended-stay bird-watching packages:Lower per-night spend segments support 7-14 day itineraries with higher total trip value and reduced turnover costs.
- EU CSRD alignment:Early adoption of sustainability reporting standards by farm-stay operators unlocks ESG-linked financing from institutional hospitality investors.
Industry Challenges
- REACH chemical compliance:Cleaning and maintenance supply chains require reformulation audits, extending procurement cycles for multi-property operators.
- Legacy property integration:Heritage building envelopes resist standard insulation retrofits, forcing bespoke engineering that fragments contractor capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rural Tourism Market |
| Market Size in 2026 | $243.7 Billion |
| Market Size in 2035 | $643.91 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Agritourism, Bed & Breakfast, Farm Stays, Eco-Lodges Activity Type: Hiking, Bird Watching, Wine Tasting, Cultural Tours Customer Segment: Families, Couples, Adventure Seekers, Retirees Service Offering: Guided Tours, Workshops, Local Cuisine, Transportation |
| Companies Covered | Expedia Group Inc., Airbnb Inc., Marriott International Inc., InterContinental Hotels Group, Accor S.A., Booking.com B.V., Hilton Worldwide Holdings Inc., Trip.com Group Limited, Priceline.com LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rural Tourism Market Evolving Landscape
Digital infrastructure is virtualizing the guest experience layer, compressing the traditional role of intermediaries while elevating property-level control over narrative and pricing.
Immersive pre-arrival platforms are virtualizing destination discovery through virtual-reality farm tours and seasonal harvest calendars. Millennial families now expect interactive booking journeys that preview host interactions and activity availability. This compression of information asymmetry shifts commission power from aggregators toward direct-channel investment by boutique operators.
The EU Green Deal's energy-performance thresholds are mandating building envelope upgrades and on-site generation for hospitality properties. Operators in France and Germany face 2027 deadlines for fossil-fuel heating phase-out. Eco-lodge developers are responding with passive-house construction methods that front-load capital against operational savings.
After-sales service unbundling is fragmenting experience curation between property-level hosts and specialized digital platforms. Local guide networks now operate across multiple booking channels, diluting loyalty effects. Portugal's Alentejo wine-country operators report highest friction where platform commission stacks against direct guide contracting.
Rural Tourism Market Segmentation
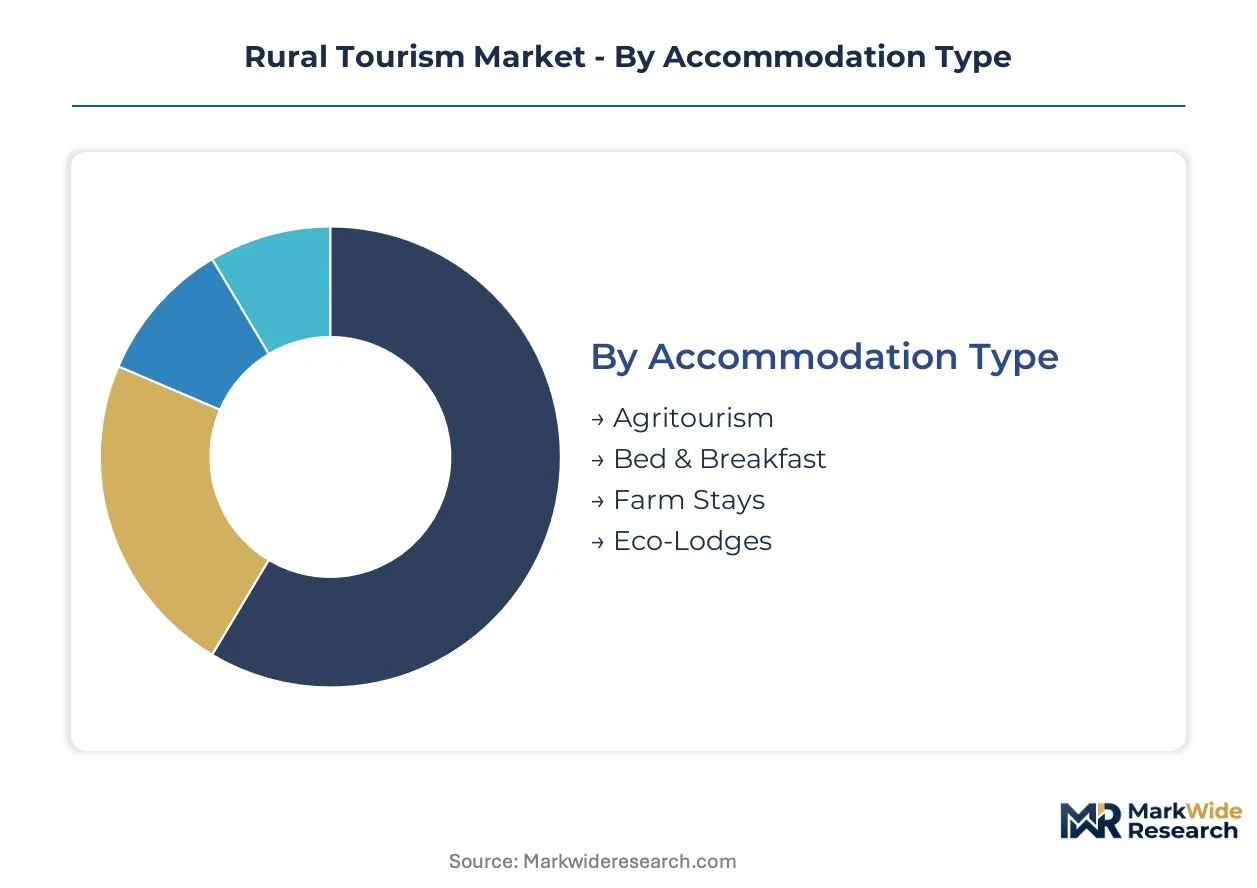
Rural tourism segmentation reveals how capital intensity and experiential depth fragment across property types and guest expectations. Accommodation and activity categories show divergent margin profiles that reshape operator investment priorities.
Accommodation Type:
Mature lodging formats coexist with emerging sustainability-certified properties across rural markets.
- Eco-Lodges:Passive-house construction and on-site renewable generation define this highest-capital tier. Portugal's Alentejo region concentrates development where EU Green Deal mandates accelerate fossil-fuel heating phase-outs.
- Bed & Breakfast:Conversion of existing rural housing stock dominates unit economics through lower entry barriers. France and Germany show dense clustering where heritage property tax incentives reduce land-carrying costs.
- Farm Stays:Direct revenue-sharing arrangements with agricultural operations characterize this experiential segment.
- Agritourism:Working-farm integration requires USDA conservation easement compliance in US markets.
Eco-lodges retain volume leadership; farm stays hold the steepest expansion curve.
Activity Type:
Seasonality constraints and certification requirements create tiered pricing power across experience categories.
- Wine Tasting:Certified guide mandates and harvest-calendar seasonality support premium rate structures. Spain's Rioja and Italy's Tuscany clusters demonstrate how regional appellation density builds guide-network effects.
- Hiking:Trail-access proximity and weather-window compression concentrate demand in Q2-Q3. Alpine regions in Austria and Switzerland extract maximum yield through limited-season scarcity pricing.
- Bird Watching:Extended-stay itineraries of 7-14 days reduce turnover costs despite lower per-night spend.
- Cultural Tours:Indigenous craft demonstrations and host-community livelihood integration differentiate this heritage-focused segment.
Hiking commands rate premiums in peak windows; bird watching delivers the most durable occupancy base.
Customer Segment:
Demographic targeting shifts operator positioning between experiential depth and accessibility requirements.
- Families:Millennial parents prioritize interactive booking journeys with pre-arrival virtual farm tours. Multi-generational travel patterns in US and UK markets drive demand for activity diversity and safety infrastructure.
- Couples:Wine-country retreats and eco-lodge privacy features attract this rate-insensitive segment. Portugal and Greece show concentration where romantic positioning justifies extended-stay packages.
- Adventure Seekers:Physical-activity intensity and remote-access requirements define this niche.
- Retirees:Accessibility-compliant properties and slower-paced itineraries align with this expanding demographic.
Families drive booking volume expansion; adventure seekers gain share fastest in emerging rural clusters.
Service Offering:
Digital platform unbundling fragments experience curation between property-level control and specialized intermediaries.
- Guided Tours:Local ecological guides now operate across multiple booking channels, diluting loyalty effects. Spain faces 18-36 month grid interconnection delays that trap renewable-powered guide-station capex in permitting.
- Local Cuisine:Farm-to-table supply chain integration and host-family dining formats command experience premiums. Italy's Emilia-Romagna and France's Provence clusters leverage appellation-protected ingredients for differentiation.
- Workshops:Permaculture training and craft instruction extend guest engagement duration.
- Transportation:Electric-vehicle charging infrastructure and scope-three carbon accounting reshape this operational layer.
Guided tours face margin compression from platform stacking; local cuisine sustains the strongest direct-channel pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operator investment concentrates where EU Green Deal mandates intersect with established wine-country infrastructure and conservation easement programs. Portugal's Alentejo region, Spain's Rioja corridor, and select US agritourism clusters absorb disproportionate capital deployment as certification requirements reshape competitive positioning.
United States
USDA conservation easement programs lower land-carrying costs for heritage property conversions across Vermont and Virginia. The 2022 Inflation Reduction Act expanded tax-advantaged structures for agritourism enterprises. Napa Valley and Sonoma County operators report strongest booking density where farm-stay inventory clusters near established wine-appellation infrastructure.
Portugal
Alentejo's wine-country rural retreats command premium rate structures through certified guide network effects. EU F-Gas Regulation phase-down deadlines accelerate heat-pump retrofits in historic farm properties. Évora and Monsaraz sub-regions concentrate development where passive-house construction methods front-load capital against operational savings.
Spain
Rioja and Priorat clusters leverage regional appellation density to build experiential tourism gravity. Grid interconnection delays of 18-36 months trap renewable-powered eco-lodge capex in permitting queues across Castile and León. Basque Country operators face compressed seasonal windows for hiking and wine-tasting revenue concentration.
France
Provence and Burgundy farm-stay operators navigate 2027 fossil-fuel heating phase-out deadlines under EU Green Deal mandates. Heritage building tax incentives reduce conversion barriers in Dordogne and Loire Valley. REACH chemical compliance audits extend procurement cycles for multi-property bed-and-breakfast networks.
Italy
Tuscany and Emilia-Romagna clusters sustain premium positioning through appellation-protected farm-to-table supply chains. CSRD alignment requirements create financing advantages for early-adopting sustainability reporters in Umbria and Piedmont. Alpine hiking operators in South Tyrol extract maximum yield through limited-season scarcity pricing.
Rural Tourism Market Competitive Landscape
Digital platform aggregators and heritage hospitality conglomerates split the market between inventory breadth and experiential depth. The competitive structure tilts toward consolidation at the luxury tier while fragmenting across boutique farm-stay operators. Two strategic archetypes dominate: technology-enabled marketplace facilitators and asset-heavy experiential curators. Dominant competitive moves include host-education tool deployment and heritage property portfolio repositioning.
Within the platform-aggregator tier, Airbnb Inc. and Booking.com B.V. exemplify technology-first positioning through host education infrastructure and dedicated rural inventory taxonomy. Marriott International Inc. anchors the asset-heavy experiential curator archetype through farm-stay collection repositioning. These three entities occupy distinct competitive vectors: marketplace facilitation, inventory aggregation, and heritage asset conversion.
| Leading Market Players |
|---|
| Expedia Group Inc. |
| Airbnb Inc. |
| Marriott International Inc. |
| InterContinental Hotels Group |
| Accor S.A. |
| Booking.com B.V. |
| Hilton Worldwide Holdings Inc. |
| Trip.com Group Limited |
| Priceline.com LLC |
| Others |
Value Network & Pricing Analysis
Overcapacity in Portugal's Alentejo wine-country lodging cluster compresses rate premiums during shoulder seasons while simultaneously pressuring property owners toward direct-channel investment and supplier consolidation to recover margin.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across rural tourism accommodation, separating passive-house certified eco-lodges from standard farm-stay conversions through energy-performance grade. Three-tier pricing structure across premium, standard, and economy levels aligns with certification depth, guide-network density, and seasonal scarcity. Cost compression in the standard tier is intensifying because grid interconnection delays trap renewable capex in permitting queues, forcing operators to absorb fossil-fuel transition penalties. Millennial families show highest price sensitivity through platform comparison behavior, while couples booking wine-country retreats demonstrate lowest sensitivity to rate premiums.
Supply Chain Analysis
Extended payment terms from HVAC equipment suppliers and supply-chain finance facilities from renewable component distributors are restructuring working capital requirements for farm-stay operators undergoing EU F-Gas Regulation retrofits. Equipment sourcing concentrates in Germany, Italy, and Denmark for heat-pump and building envelope systems. Construction inputs draw from regional timber framers in France, Portuguese cork insulation specialists, and Spanish solar thermal manufacturers. Single-source vulnerability sits with certified ecological guide networks operating across multiple properties. Distribution runs through direct contracting between farm-stay operators and local experience curators, bypassing platform commission stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rural tourism fragmentation creates white space for specialized operators as millennial family demand splinters across experiential depth preferences and certification transparency requirements.
For Market Incumbents: Pre-empt platform disintermediation by building captive guide networks through exclusive contracting in Portugal's Alentejo and Spain's Rioja corridors. Consolidate heritage property portfolios before EU CSRD alignment requirements unlock ESG-linked financing advantages for early movers. Vertical integration into on-site renewable generation secures margin against fossil-fuel heating phase-out penalties. For New Entrants and Emerging Players: Pursue bird-watching extended-stay packages in underdeveloped Alpine sub-regions where lower per-night spend segments support 7-14 day itineraries with reduced turnover costs. Target USDA conservation easement structures in Vermont and Virginia where tax-advantaged land-carrying costs extend investment horizons. Go-to-market through direct-channel immersive pre-arrival platforms that virtualize host interactions before booking commitment. For Investors and Strategic Acquirers: Capital is best deployed toward passive-house eco-lodge developers with locked-in renewable equipment supply agreements and established CSRD reporting infrastructure. Long-term viability hinges on properties achieving carbon-neutral certification before 2027 fossil-fuel heating mandates crystallize competitive sorting. Watch grid interconnection clearance velocity in Spain and Italy as the signal for scalable capex deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Host Education Infrastructure Deployment | Airbnb's host education tools sustain booking density in remote Alentejo locations against platform fragmentation. |
| Heritage Property Portfolio Repositioning | Marriott's Tribute Portfolio farm-stay collection converts agricultural assets into experiential destinations with rate premiums. |
| Carbon-Accounting Software Integration | Scope-three visitor travel tracking creates white space for vendors integrating booking platforms with offset marketplaces. |
| Passive-House Construction Method Adoption | Évora and Monsaraz operators front-load capital against EU Green Deal fossil-fuel heating phase-out deadlines. |
| Direct-Channel Immersive Platform Investment | Virtual-reality farm tours compress information asymmetry and shift commission power from aggregators toward boutique operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with farm-stay proprietors, certified ecological guides, HVAC retrofit contractors, and ESG financing officers at institutional hospitality investors. Secondary validation drew from EU Green Deal implementation trackers, ECHA REACH compliance databases, USDA conservation easement program filings, and F-Gas Regulation phase-down schedules. Bottom-up property-level capacity assessments and top-down regional tourism flow data were triangulated to anchor volume estimates.
Calibration against historical booking density patterns and seasonal occupancy curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include accommodation type, activity category, customer demographic, and service offering unbundling. CAGRs were derived from trend extrapolation adjusted for regulatory mandate acceleration and certification adoption S-curves. Grid interconnection queue lengths and conservation easement enrollment velocity served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in discretionary travel spending, exchange rate volatility affecting intra-European tourism flows, or fossil-fuel price spikes would shift the trajectory. Forecasts reflect documented assumptions regarding EU mandate implementation timelines and certification scheme stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
India Faith Based Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Smart Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Italy Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Thailand Sustainable Tourism Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Vietnam Tourism Market