
 Europe Theme Park Market | 2026-2036
Europe Theme Park Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Theme Park Market Intelligence
IP-anchored immersive storytelling is unwinding across European parks as operators compete on experiential depth rather than ride throughput alone. Europa-Park leverages its multi-theming strategy to sustain cross-border visitor loyalty from Germany, France, and Switzerland. Efteling anchors its position through original fairy-tale IP that differentiates its offering from licensed-character competitors. Disneyland Paris dominates the premium segment with its captive resort ecosystem and studio integration.
A Europe theme park constitutes a gated entertainment destination combining mechanical rides, live performance venues, themed environments, and hospitality services, typically spanning 50 to 200 hectares and processing 5,000 to 60,000 visitors daily. These facilities generate revenue through admission tickets, in-park food and beverage, merchandise, and on-site accommodation, with capital intensity driven by steel-track roller coaster engineering and audio-animatronics systems. Thrill rides and dark rides together capture the highest capital allocation per square meter, while water attractions face seasonal constraints that compress operating margins in northern climates. The family customer demographic occupies the most stable repeat-visit pool, whereas young adult segments concentrate spending on premium experiences and limited-event programming.
REACH chemical safety standards and the EU Green Deal framework constrain material sourcing for new construction while mandating energy transition timelines for existing facilities. CE marking requirements govern ride safety certification across member states, creating a unified but rigorous market access protocol. France's national environmental regulator and Germany's KBA both influence operational permitting for major expansions. Operators must monitor how CSRD disclosure rules will reshape capital allocation toward measurable sustainability outcomes.
Market Dynamics
EU Green Deal mandates are compressing capital allocation timelines for energy retrofits across European theme park portfolios, forcing operators to prioritize decarbonized infrastructure over pure capacity expansion.
Growth Catalysts
- CSRD disclosure mandates:Sustainability reporting requirements under the EU Corporate Sustainability Reporting Directive are redirecting institutional investment toward parks with verified low-carbon credentials, expanding their access to green financing instruments.
- Cross-border leisure mobility:Schengen-zone travel fluidity sustains visitor base diversification, with German and French operators capturing Swiss and Benelux repeat visitors through season-pass reciprocity programs.
- Dark ride engineering advances:Trackless ride systems and real-time media integration are enabling higher throughput per square meter in constrained urban park footprints across the Netherlands and Belgium.
Market Restraints
- Steel and rare-earth input volatility:Roller coaster fabrication depends on specialized steel alloys and permanent magnet supply chains concentrated in Chinese processing facilities, exposing capex budgets to tariff and logistics disruptions.
- REACH chemical compliance costs:The European Chemicals Agency's restricted substance lists are eliminating certain polymers and coatings from animatronic and façade applications, forcing reformulation of proven material specifications.
- Seasonal demand compression:Northern latitude parks in Scandinavia and the Baltic states face structurally limited operating calendars that prevent full fixed-cost absorption compared to Mediterranean competitors.
Strategic Opportunities
- Poland and Czech Republic greenfield development:Underpenetrated Central European markets with rising disposable incomes and limited incumbent premium park supply offer first-mover positioning for integrated resort concepts.
- F-Gas Regulation retrofit incentives:The EU's phasedown of hydrofluorocarbon refrigerants is creating subsidy pools for operators replacing climate-control systems in existing indoor attractions and hospitality assets.
- Immersive theater convergence:Projection mapping and spatial audio technologies are merging with live performance infrastructure, enabling new ticketed evening programming that extends per-visitor revenue capture.
Industry Challenges
- Audio-animatronics technician scarcity:The specialized skill set combining mechanical engineering, puppetry, and software calibration faces generational replacement gaps as veteran technicians retire without structured apprenticeship pipelines.
- CE marking timeline compression:Novel ride system certifications through notified bodies in Germany and France now extend 18-24 months, delaying revenue recognition for major attraction investments.
- Licensed IP negotiation complexity:Major entertainment franchises are demanding revenue participation structures and creative control clauses that constrain operator autonomy over attraction design and merchandise mix.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Theme Park Market |
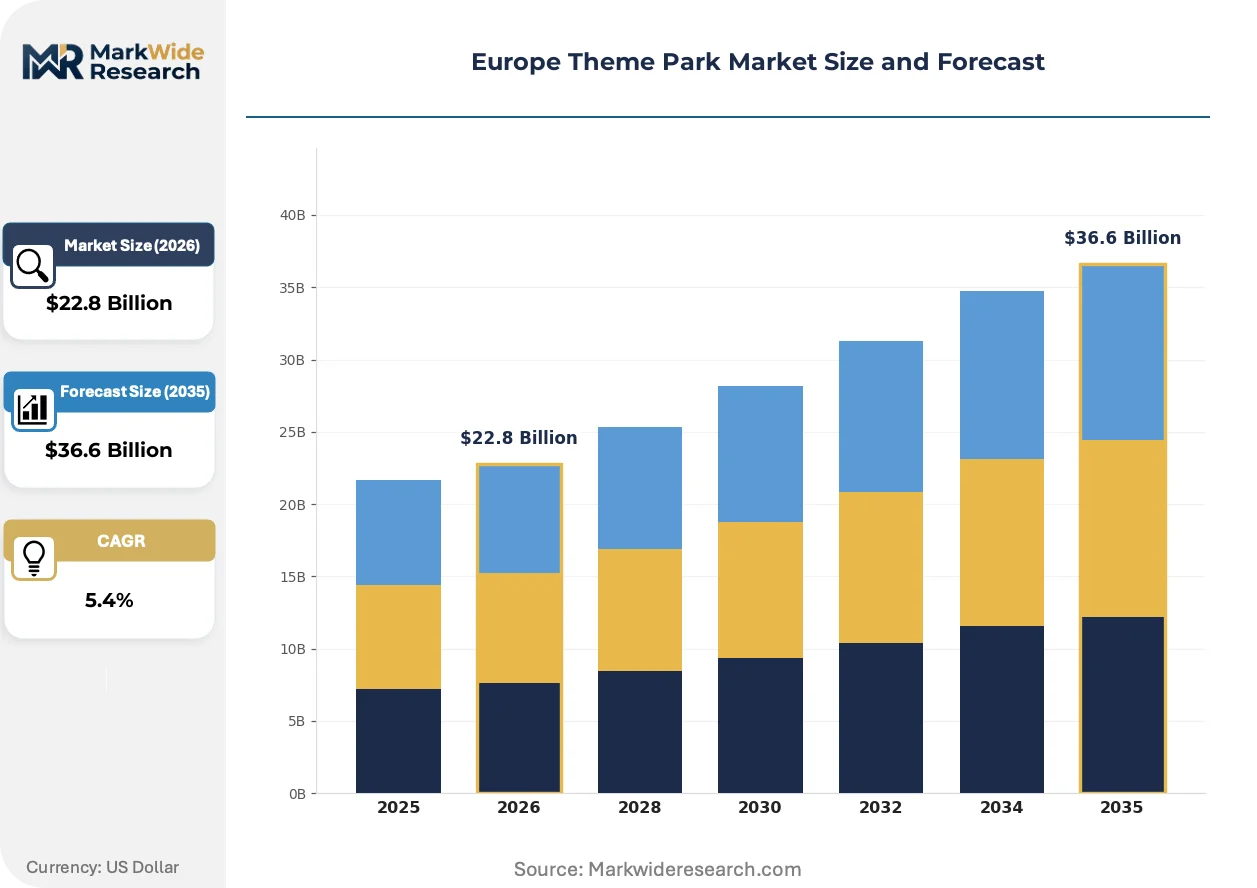
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Attraction Type: Thrill Rides, Family Rides, Water Attractions, Dark Rides Customer Demographics: Families, Teenagers, Young Adults, Tourists Ticket Pricing: Premium, Mid-tier, Budget, Group Discounts Operating Model: Seasonal, Year-round, Franchise, Independent |
| Companies Covered | Disneyland Paris, Europa-Park, Efteling, Tivoli Gardens, PortAventura, Gardaland, Liseberg, Puy du Fou, Parc Asterix, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Theme Park Market Strategic Shifts & Innovations
Experiential depth is displacing raw ride capacity as the primary competitive vector, with operators investing in narrative layering and environmental storytelling to extend dwell time and secondary spending.
Spatial audio and haptic feedback arrays are miniaturizing into wearable formats that synchronize individual visitor sensations with show action. Mid-tier parks in Spain and Italy are piloting these systems to differentiate against capital-intensive coaster investments. The technology is compressing the cost gap between premium dark rides and replicable walk-through attractions.
REACH chemical safety standards are eliminating legacy flame-retardant compounds from scenic fabrication, forcing suppliers toward bio-based alternatives with unproven durability profiles. German and French regulators are enforcing batch-testing protocols that extend pre-opening certification timelines. Operators are responding by consolidating vendor relationships with firms holding pre-approved material libraries.
Visitor purchasing patterns are fragmenting across advance-commitment and impulse segments, with mobile-enabled food pre-ordering displacing traditional queue-based concession models. Young adult demographics in the UK and Netherlands are driving adoption of experience bundling platforms that aggregate park admissions with regional hospitality. This behavioral shift is most visible in urban satellite parks where day-trip convenience outweighs resort immersion priorities.
Europe Theme Park Market Segmentation
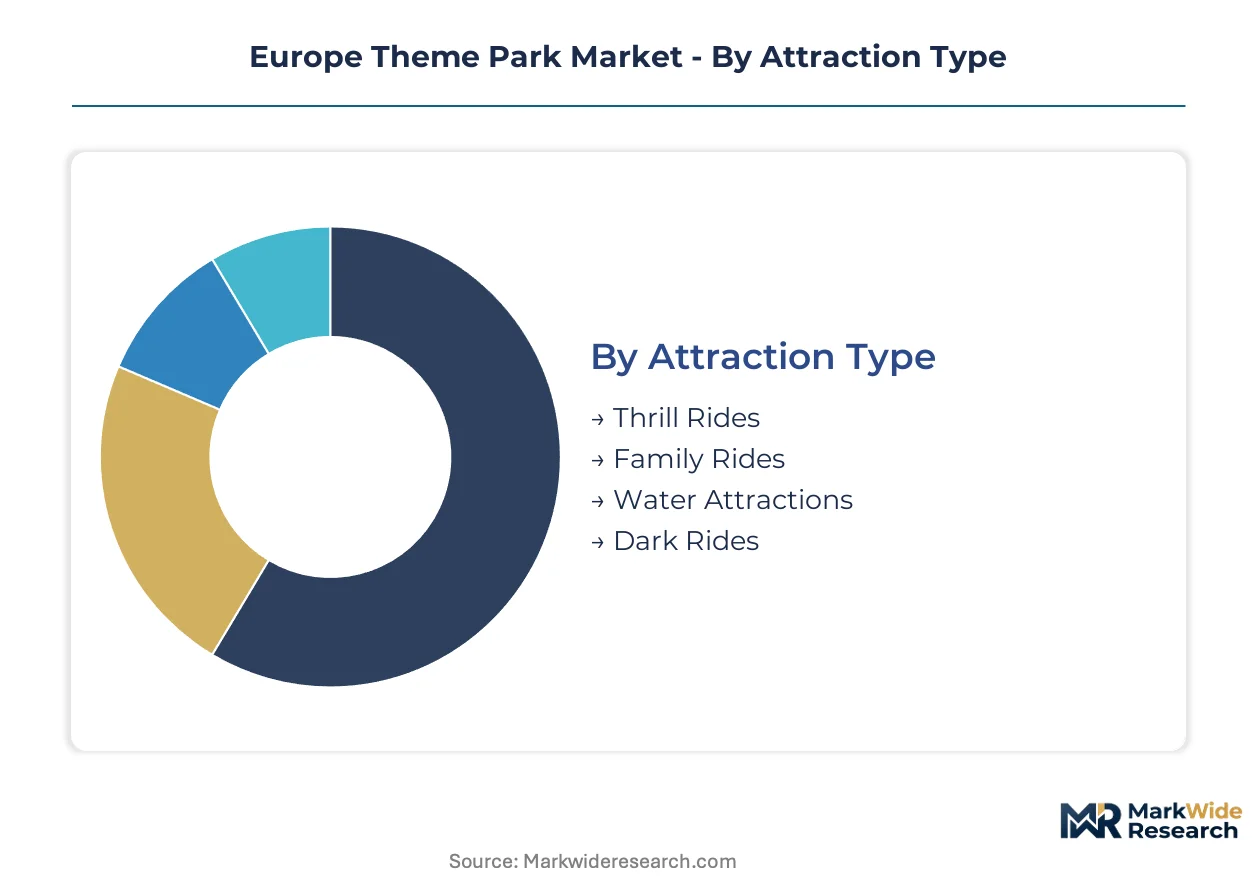
European theme park operators calibrate capital deployment and operational strategy through four distinct segmentation lenses. Attraction mix determines engineering spend and seasonal staffing models. Customer demographics shape IP licensing decisions and food and beverage programming. Pricing architecture and operating models together govern revenue recognition timing and fixed-cost absorption capacity across Mediterranean and northern latitude parks.
Attraction Type:
Thrill rides and dark rides concentrate investment in Germany and France where per-capita spending supports premium engineering. Water attractions skew toward Spanish and Italian operators with extended operating calendars.
- Thrill Rides:Steel-track roller coasters and launched ride systems demand the highest capital intensity per square meter. German parks including Europa-Park and Phantasialand anchor visitor loyalty through record-breaking coaster investments that justify premium admission pricing.
- Dark Rides:Trackless vehicle systems and real-time media integration enable narrative depth in constrained footprints. Dutch and Belgian operators leverage this technology to compete against larger capital bases without equivalent land availability.
- Family Rides:Moderate-threshold attractions with lower height restrictions capture repeat visitation from multi-generational groups.
- Water Attractions:Seasonal compression in Scandinavia and the Baltic states limits return on investment compared to Mediterranean deployments.
Thrill rides command the established base. The steepest expansion runs through dark rides as trackless engineering costs decline.
Customer Demographics:
Family segments generate the most predictable repeat-visit revenue across German and French parks. Young adult spending concentrates on limited-event programming and premium add-ons.
- Families:Multi-generational groups with children under 14 drive season-pass subscriptions and on-site hotel occupancy. Efteling in the Netherlands and Europa-Park sustain loyalty through original IP that transcends licensed-character dependency.
- Young Adults:Visitors aged 18-30 concentrate spending on Halloween events, concert series, and VIP experience upgrades. UK and Dutch parks capture this segment through mobile-first bundling platforms.
- Teenagers:Peer-group visitation patterns favor thrill-ride destinations with social media shareability.
- Tourists:International visitors, particularly from Asia and the Americas, cluster at Disneyland Paris and resort-integrated properties.
Families anchor revenue stability. Young adults are climbing the fastest as experience-bundling platforms expand penetration.
Ticket Pricing:
Premium pricing concentrates at integrated resort properties in France. Budget positioning dominates Polish and Czech satellite parks serving day-trip markets.
- Premium:Multi-day resort packages with express-line privileges and character dining command the highest per-visitor yield. Disneyland Paris and select German properties capture this tier through captive hotel ecosystems.
- Mid-tier:Single-day admission with moderate add-on availability targets repeat domestic visitors. Benelux and Spanish operators cluster here.
- Budget:Low base pricing with à-la-carte upselling serves price-sensitive families in Central Europe.
- Group Discounts:Corporate and educational volume pricing fills shoulder-season capacity at northern latitude parks.
Premium pricing captures the margin concentration. Budget tiers are gaining share fastest as Central European disposable incomes rise.
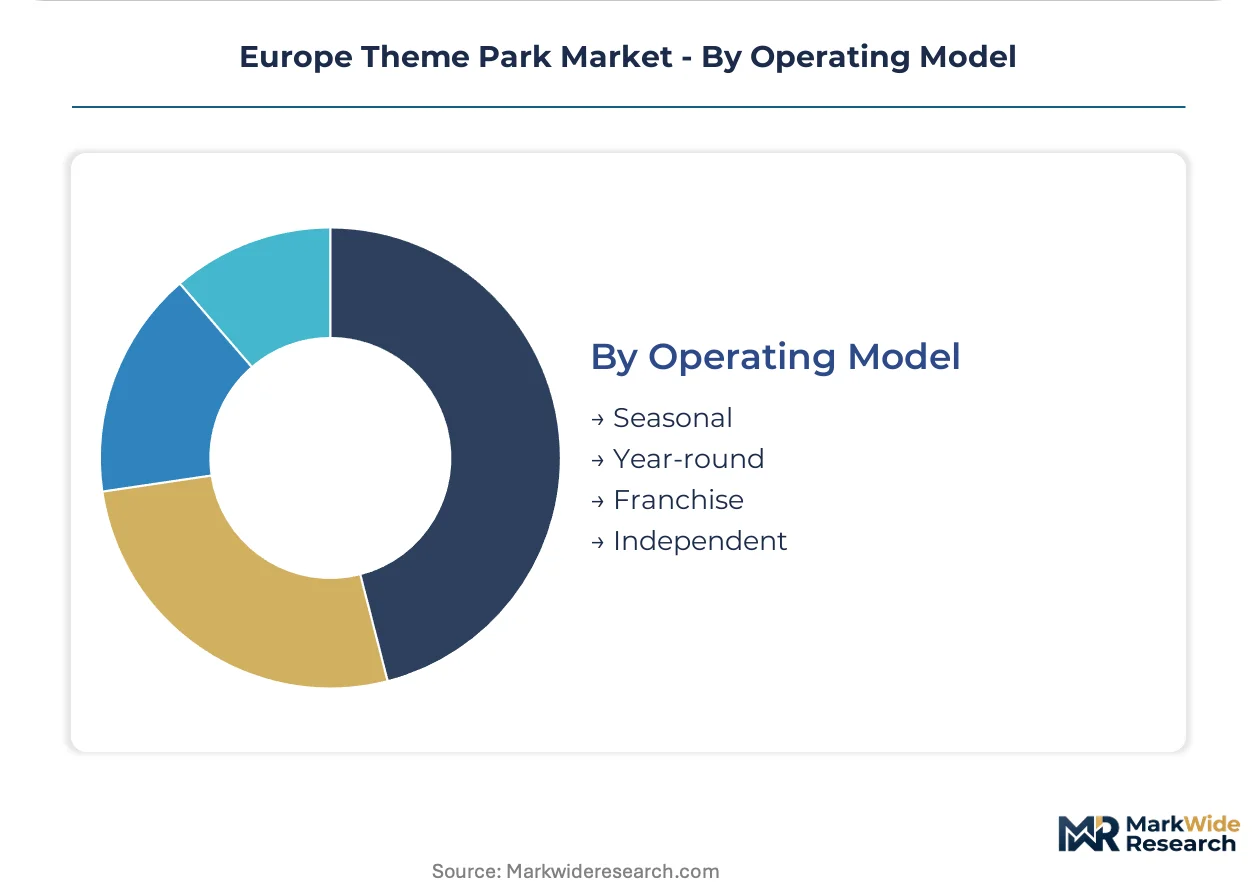
Operating Model:
Year-round operations concentrate in Mediterranean climates and indoor-dominant parks. Seasonal models prevail in Scandinavia with compressed revenue recognition windows.
- Year-round:Continuous operation enables full fixed-cost absorption and stable employment retention. Disneyland Paris and Spanish resort properties deploy this model.
- Seasonal:Weather-dependent calendars limit staffing to contract structures and compress maintenance windows. Scandinavian and Baltic operators face structural margin pressure.
- Franchise:Licensed IP agreements with revenue-sharing structures constrain operator autonomy over creative decisions.
- Independent:Original IP and family ownership enable rapid thematic pivots without corporate approval chains.
Year-round operations command the established base. The steepest expansion trajectory runs through franchise models as major entertainment licensors seek European footprint expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European theme park operators import specialized steel alloys and permanent magnet systems from Asian processing facilities while exporting experiential design expertise and IP licensing frameworks to emerging markets. This trade dynamic shapes capital deployment priorities across the region's major operational clusters.
Germany
Domestic leisure travelers and Swiss cross-border visitors sustain year-round demand at major complexes in Baden-Württemberg and North Rhine-Westphalia. The KBA enforces extended CE marking timelines for novel ride systems, compressing revenue recognition windows for new attractions. Europa-Park in Rust anchors the Upper Rhine cluster with multi-theming strategies that capture French and Swiss repeat visitation.
France
International tourists from Asia and the Americas concentrate at integrated resort properties in the Île-de-France region, driving premium per-visitor yields. The national environmental regulator mandates energy transition timelines under EU Green Deal frameworks, redirecting capital toward decarbonized infrastructure. Puy du Fou in western France exemplifies immersive theater convergence with historical narrative attractions that extend evening programming revenue.
Netherlands
Trackless dark ride engineering from Dutch specialists serves constrained urban footprints across Benelux markets, enabling competitive positioning without equivalent land availability. ECHA REACH compliance costs eliminate legacy polymers from animatronic fabrication, forcing supplier consolidation toward pre-approved material libraries. Efteling in Kaatsheuvel anchors visitor loyalty through original fairy-tale IP that differentiates against licensed-character competitors.
Spain
Mediterranean climate advantages enable extended operating calendars that absorb fixed costs more efficiently than northern latitude competitors. F-Gas Regulation retrofit incentives subsidize climate-control replacements in indoor attractions and hospitality assets. PortAventura in Tarragona and Gardaland-operated properties exemplify resort-integrated models that capture multi-day visitation from British and German source markets.
United Kingdom
Young adult demographics drive adoption of experience-bundling platforms that aggregate park admissions with regional hospitality services. CSRD disclosure mandates redirect institutional investment toward operators with verified low-carbon credentials, expanding green financing access. Urban satellite parks in the Greater London area prioritize day-trip convenience over resort immersion, with mobile-enabled food pre-ordering displacing traditional concession queues.
Europe Theme Park Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and IP licensing dimensions. The market structure concentrates around family-owned independents with original thematic IP and multinational entertainment conglomerates with captive licensed-character portfolios. Three archetypes dominate: integrated resort operators with captive hotel ecosystems, regional champions with cross-border visitor capture, and immersive theater specialists with narrative-driven attractions. Competitive moves center on M&A for IP portfolio expansion and strategic partnerships for technology licensing in trackless ride systems.
Among Germany-based operators, Europa-Park GmbH & Co Mack KG exemplifies the family-owned independent archetype with rapid thematic pivot capacity. Within the multinational conglomerate tier, Disneyland Paris represents the integrated resort model with studio-backed IP ecosystems. Dutch operator Efteling occupies a position bridging original IP authenticity with dark ride engineering integration. These three anchors illustrate how competitive positioning diverges between licensed-character dependency and proprietary narrative development.
| Leading Market Players |
|---|
| Disneyland Paris |
| Europa-Park |
| Efteling |
| Tivoli Gardens |
| PortAventura |
| Gardaland |
| Liseberg |
| Puy du Fou |
| Parc Asterix |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month CE marking timelines for novel ride systems compress revenue recognition windows and concentrate pricing power with notified bodies in Germany and France, while steel alloy and permanent magnet dependencies tether capex budgets to Asian processing volatility.
Pricing Analysis
Family leisure buyers anchor three-tier pricing structure across premium, standard, and economy levels at European parks. Premium tier differentiation rests on captive resort ecosystems and express-line privileges at integrated properties, while budget positioning serves price-sensitive day-trip markets in Central Europe. Pricing pressure stems from F-Gas Regulation retrofit mandates redirecting capital toward climate-control replacements. Young adult segments demonstrate lowest price sensitivity through experience-bundling platform adoption, whereas multi-generational families exhibit highest sensitivity to base admission thresholds.
Supply Chain Analysis
Specialized steel alloy inventories extending eighteen months ahead of major attraction openings expose operators to tariff and logistics disruptions from Chinese and South Korean processing facilities. Roller coaster fabrication draws from rare-earth permanent magnet supply chains concentrated in Chinese refining operations, while scenic fabrication hinges on REACH-compliant bio-based polymers from German and French pre-approved vendor libraries. Single-source vulnerability runs through trackless ride system engineering from Dutch specialists. Distribution runs through direct procurement contracts with notified body certification bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Central European greenfield development represents an early-cycle expansion story, with rising disposable incomes in Poland and the Czech Republic outpacing incumbent premium park supply.
For Market Incumbents: Shield core visitor loyalty through season-pass reciprocity program expansion across Schengen-zone markets, countering emerging immersive theater competitors. Accelerate backward integration into pre-approved REACH material libraries to deflect supplier consolidation risk from ECHA batch-testing protocols. Prioritize energy retrofit timelines ahead of EU Green Deal enforcement to preserve green financing access. For New Entrants and Emerging Players: Anchor in underpenetrated Central European markets with integrated resort concepts capturing first-mover positioning before disposable income maturation. Target young adult segments through mobile-first experience bundling rather than capital-intensive coaster competition. Deploy spatial audio and haptic wearable pilots as differentiation against established dark ride engineering. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because EU Green Deal mandates and CSRD disclosure requirements are redirecting institutional capital toward verified low-carbon credentials with durable competitive moats. Acquisition focus should center on family-owned independents with original IP and rapid thematic pivot capacity. Monitor CE marking timeline compression at German and French notified bodies as inflection indicator for revenue recognition risk across major attraction investments.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Ride Engineering Partnership | Trackless system licensing from Dutch specialists enables competitive positioning without equivalent land availability. |
| REACH-Compliant Material Consolidation | Pre-approved vendor library partnerships compress pre-opening certification timelines at ECHA-regulated facilities. |
| F-Gas Retrofit Program | Climate-control replacement subsidies from EU phasedown pools redirect capital toward decarbonized infrastructure. |
| Cross-Border Season Pass Reciprocity | Schengen-zone mobility programs capture Swiss and Benelux repeat visitors at German and French properties. |
| Immersive Theater Convergence | Projection mapping and spatial audio integration extends evening programming revenue at historical narrative attractions. |
Research Approach
Cross-validation between primary interviews with attraction development executives, ride system procurement directors, and ECHA compliance officers and secondary validation through EU customs trade data, CE marking notification databases, and national environmental regulator filings anchors the qualitative findings. Bottom-up modeling of per-visitor yield metrics and top-down triangulation against capital expenditure disclosures from listed entertainment conglomerates refine volume estimates.
Sensitivity analysis across the projection horizon tests segmentation dimensions including attraction type, customer demographic, pricing tier, and operating model against varying CE marking timeline assumptions and steel alloy input cost scenarios. CAGRs derive from installed base expansion rates, replacement cycle timing, and penetration curve modeling for immersive technology adoption. Industry-specific inputs include F-Gas Regulation subsidy pool allocation forecasts and REACH restricted substance list revision schedules.
Decision-makers should treat outputs as directional under sustained Schengen-zone mobility and EU Green Deal enforcement assumptions; material deviation in cross-border leisure patterns or regulatory timeline acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market