
 Italy Culinary Tourism Market | 2026-2036
Italy Culinary Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Culinary Tourism Market Foresight
Asset-light franchise and licensing models for culinary tour packaging is reconfiguring competitive dynamics across Italy's fragmented operator landscape. Abercrombie & Kent leverages its established luxury infrastructure to bundle exclusive vineyard access with private estate dining in Tuscany. Classic Journeys anchors its positioning through deep relationships with artisan producers in Piedmont and Sicily, controlling itinerary quality through direct supplier contracts. Butterfield & Robinson differentiates by integrating cycling routes with progressive meals, extending its active-travel expertise into gastronomic territory.
Italy culinary tourism encompasses structured travel experiences centered on food production, preparation, and consumption, typically spanning 2-7 days and incorporating direct engagement with chefs, farmers, and wine makers in designated regional zones. These experiences generate economic value through accommodation, transport, retail, and educational services while preserving intangible cultural heritage linked to Mediterranean diet traditions and Slow Food philosophy. Cooking classes and wine tours command premium pricing due to limited group sizes and certified instructor requirements, whereas street food tours and local market visits operate at higher frequency with lower per-capita yields. Gourmet dining experiences concentrate margin pools in metropolitan centers like Rome and Milan, though farm visits in rural provinces are expanding fastest as travelers seek provenance transparency.
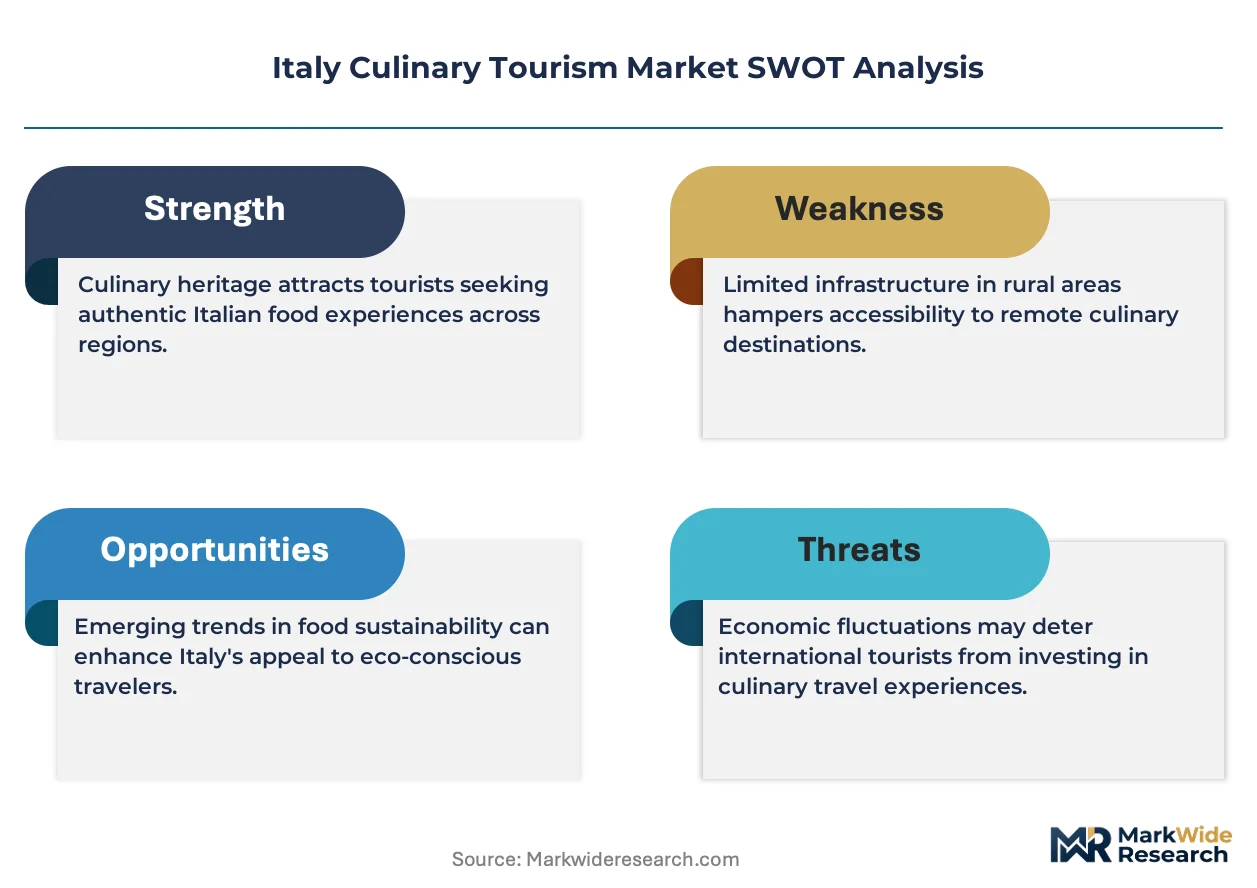
Italy's Ministry of Tourism coordinates with regional authorities to enforce quality standards through the "Viaggi Italiani" certification framework, while EU-level GDPR compliance shapes how operators collect and leverage traveler preference data for personalized itinerary design. The National Institute of Statistics (ISTAT) tracks visitor expenditure patterns, informing ENIT's promotional allocation across source markets. Stakeholders must monitor evolving EU consumer protection regulations on experience-based bookings and assess whether emerging carbon-accounting rules for tourism services will reshape long-haul visitor flows to Italian culinary destinations.
Market Dynamics
Asset-light franchise and licensing models for culinary tour packaging are reconfiguring competitive dynamics across Italy's fragmented operator landscape. ENIT co-marketing partnerships with regional DMOs are streamlining small-operator access to international distribution channels, compressing traditional gatekeeper advantages.
Growth Catalysts
- EU Green Deal alignment:Carbon-accounting frameworks for tourism services are incentivizing rail-connected itineraries through Emilia-Romagna's gastronomic corridor. Operators bundling train travel with farm visits capture preferential listing on ENIT promotional platforms.
- North American food enthusiast demand:Booking volumes for wine tours and cooking classes across Tuscany and Piedmont are accelerating as travelers seek provenance transparency. This segment commands premium pricing due to certified instructor requirements and limited group sizes.
- Slow Food philosophy institutionalization:UNESCO Mediterranean diet heritage designation is anchoring multi-day itinerary development. Regional authorities leverage this intangible cultural asset to differentiate Italian offerings from French and Spanish competitors.
Market Restraints
- GDPR compliance friction:EU-level data protection rules constrain how operators collect and leverage traveler preference data for personalized itinerary design. Customer acquisition costs rise as first-party data strategies replace behavioral targeting.
- Certified instructor scarcity:Cooking classes require qualified personnel with regional culinary credentials. Supply bottlenecks in Piedmont and Sicily limit expansion of high-yield experiences despite demand concentration.
- Seasonal demand asymmetry:Metropolitan gourmet dining in Rome and Milan absorbs year-round traffic, while rural farm visits face winter occupancy collapse. Fixed cost structures in peripheral provinces strain operator viability.
Strategic Opportunities
- Sicily artisan producer integration:Deep relationships with specialty food makers enable direct supplier contracts controlling itinerary quality. Classic Journeys-style positioning remains underdeveloped outside Tuscany and Piedmont.
- "Viaggi Italiani" certification leverage:Ministry of Tourism quality standards create tiered market segmentation. Early certification adopters gain preferred placement in ENIT international campaigns.
- Active-travel convergence:Cycling routes integrated with progressive meals extend addressable market into fitness-oriented demographics. Butterfield & Robinson's model has limited indigenous competition.
Industry Challenges
- Small-operator distribution access:Fragmented rural providers lack technical infrastructure for direct booking platforms. DMO intermediation extracts margin while delaying payment cycles.
- Carbon-accounting implementation:Emerging rules for tourism services require emissions measurement across accommodation, transport, and retail partners. Compliance tooling investment burdens mid-scale operators.
- Experience standardization:Quality variance across street food tours and local market visits erodes category pricing power. ISTAT expenditure tracking reveals yield compression in high-frequency, low-margin segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Culinary Tourism Market |
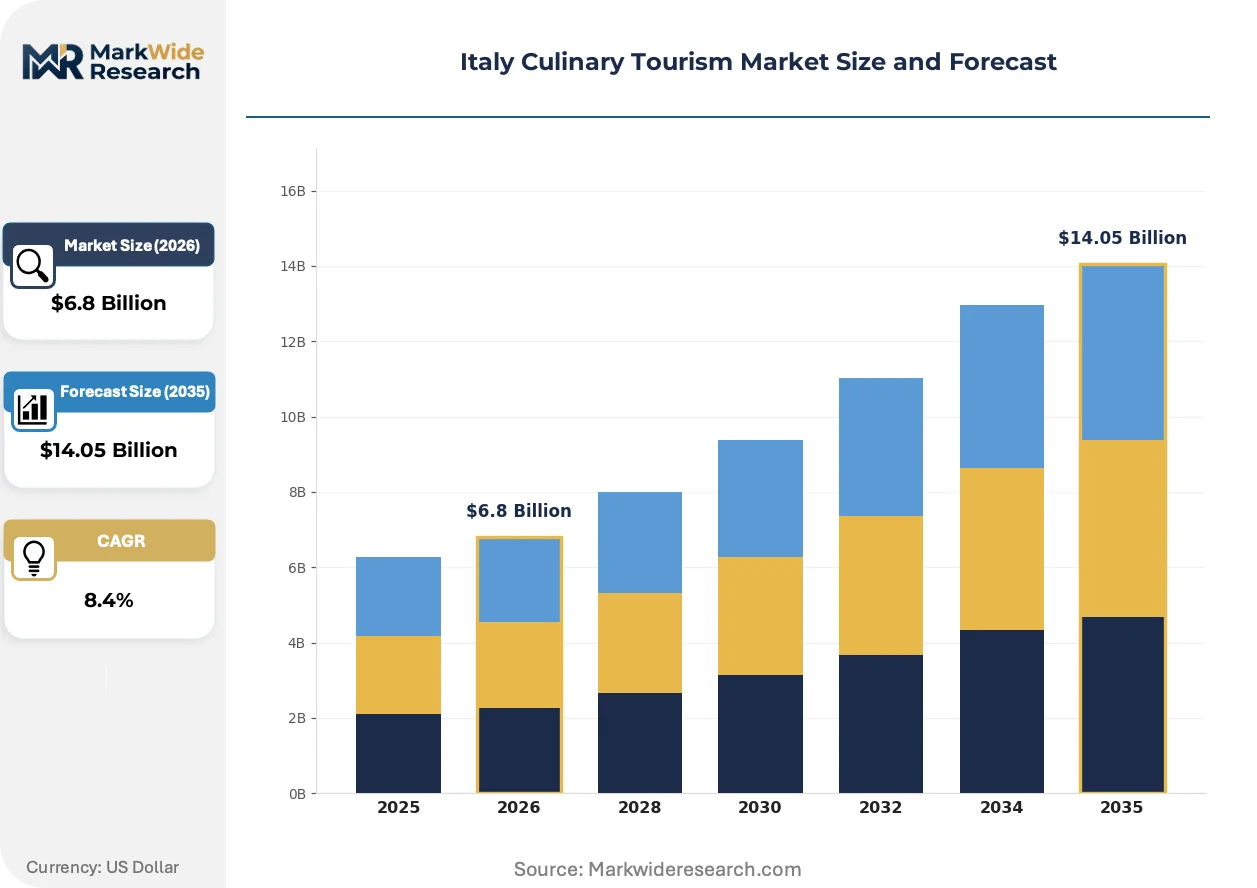
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tour Type: Cooking Classes, Wine Tours, Farm Visits, Culinary Festivals Experience Type: Gourmet Dining, Street Food Tours, Local Markets, Food Pairings Visitor Profile: Leisure Travelers, Food Enthusiasts, Culinary Students, Family Groups Duration of Stay: Weekend Trips, Week-long Vacations, Short Getaways, Custom Packages |
| Companies Covered | Zingerman's Food Tours, Abercrombie & Kent, Butterfield & Robinson, Famiglia Rana, La Rei Natura by Michelangelo Mammoliti, Classic Journeys, India Food Tour, La Terrazza, Foody Experience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Culinary Tourism Market Shifts & Advancements
Digital infrastructure deployment is reshaping how culinary experiences are discovered, booked, and delivered across Italian regions. Three developments are compressing traditional intermediation layers while elevating quality transparency.
Reservation management platforms are digitizing small-operator inventory exposure to international distribution channels. Tuscany-based vineyard estates and Emilia-Romagna farmhouse kitchens are adopting cloud-based booking engines at accelerating rates. This technology is digitizing previously opaque supply, enabling real-time availability synchronization with ENIT-endorsed travel portals.
GDPR enforcement through Italy's Data Protection Authority is tightening consent requirements for traveler preference profiling. Operators must now implement explicit opt-in architectures for itinerary personalization, increasing compliance overhead. Premium segment providers absorbing these costs are gaining competitive separation from unstandardized local competitors.
Travelers are prioritizing direct engagement with artisan producers over packaged tour intermediation. Farm visit bookings in rural provinces are expanding fastest as verification technologies replace brand trust. This pattern concentrates in Northern European source markets where Slow Food membership correlates with booking behavior.
Italy Culinary Tourism Market Segmentation
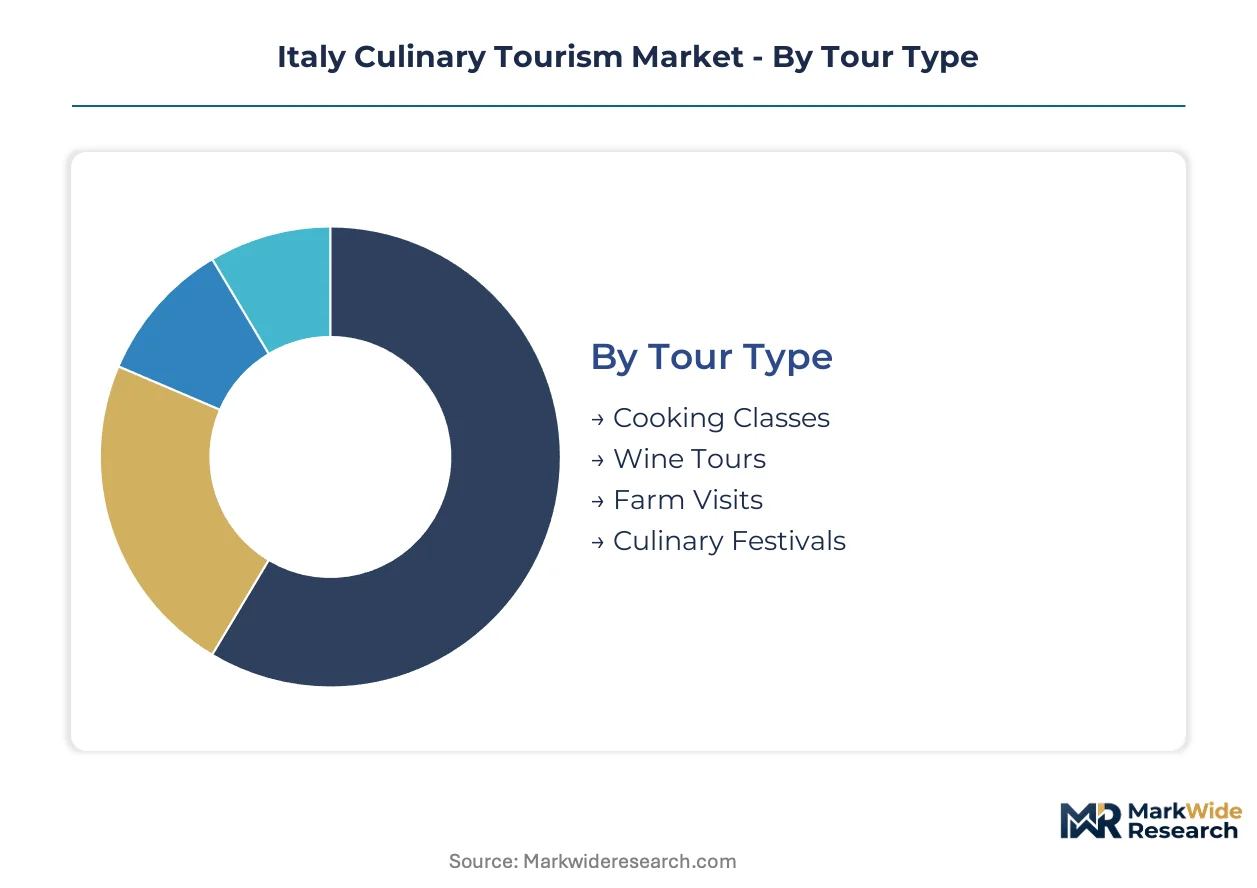
Segmentation in Italy's culinary tourism market reveals distinct margin structures and operational requirements across experience formats. Tour operators configure inventory and staffing models differently depending on which segment combination a traveler selects.
Tour Type:
Mature formats dominate revenue concentration while emerging categories reshape competitive positioning.
- Cooking Classes:Hands-on instruction in regional techniques, typically 3-6 hours with certified chefs in Tuscany and Piedmont. Demand concentrates among North American food enthusiasts seeking provenance transparency; certified instructor scarcity limits expansion despite premium pricing power.
- Wine Tours:Structured vineyard visits with tastings and estate dining, leveraging deep relationships with artisan producers. Booking volumes accelerate across Tuscany and Piedmont; ENIT co-marketing partnerships streamline small-operator access to international distribution.
- Farm Visits:Direct engagement with Parmesan and balsamic vinegar producers in Emilia-Romagna's gastronomic corridor. Travelers prioritize verification technologies over brand trust; rural provinces face winter occupancy collapse.
- Culinary Festivals:Seasonal events anchoring multi-day itineraries around UNESCO Mediterranean diet heritage. Regional authorities leverage intangible cultural assets to differentiate from French and Spanish competitors.
Cooking classes handle the majority of throughput; farm visits are expanding most quickly as travelers seek provenance transparency.
Experience Type:
Cost tier stratification separates capital-intensive formats from high-frequency, low-yield alternatives.
- Gourmet Dining:Metropolitan restaurant experiences in Rome and Milan absorbing year-round traffic with concentrated margin pools. Fixed cost structures strain operator viability in peripheral provinces.
- Street Food Tours:Urban walking routes sampling regional specialties at lower per-capita yields. Quality variance erodes category pricing power; ISTAT expenditure tracking reveals yield compression.
- Local Markets:Guided exploration of food halls and produce vendors with educational components. GDPR compliance friction constrains personalized itinerary design based on preference data collection.
- Food Pairings:Curated combinations of wine, cheese, and specialty products in controlled settings. Slow Food philosophy institutionalization anchors premium positioning.
Gourmet dining commands the highest per-capita spend; food pairings are climbing the fastest on margin contribution.
Visitor Profile:
Application-based segmentation aligns product development with distinct motivational drivers and booking behaviors.
- Leisure Travelers:General tourists incorporating culinary elements into broader Italy itineraries. Rail-connected packages through Emilia-Romagna capture preferential ENIT listing under EU Green Deal alignment.
- Food Enthusiasts:Dedicated gastronomic travelers with Slow Food membership correlating to booking behavior. This segment commands premium pricing due to limited group sizes and certified instructor requirements.
- Culinary Students:Aspiring professionals seeking credential-bearing instruction and technique mastery. Supply bottlenecks in qualified instructional personnel constrain addressable market.
- Family Groups:Multi-generational travelers requiring flexible scheduling and varied activity intensity. Custom package development absorbs higher planning overhead per booking.
Food enthusiasts generate the highest yield per departure; family groups represent the steepest expansion trajectory as multi-generational travel normalizes.
Duration of Stay:
Volume concentration patterns reflect seasonal asymmetry and fixed cost absorption challenges across operator tiers.
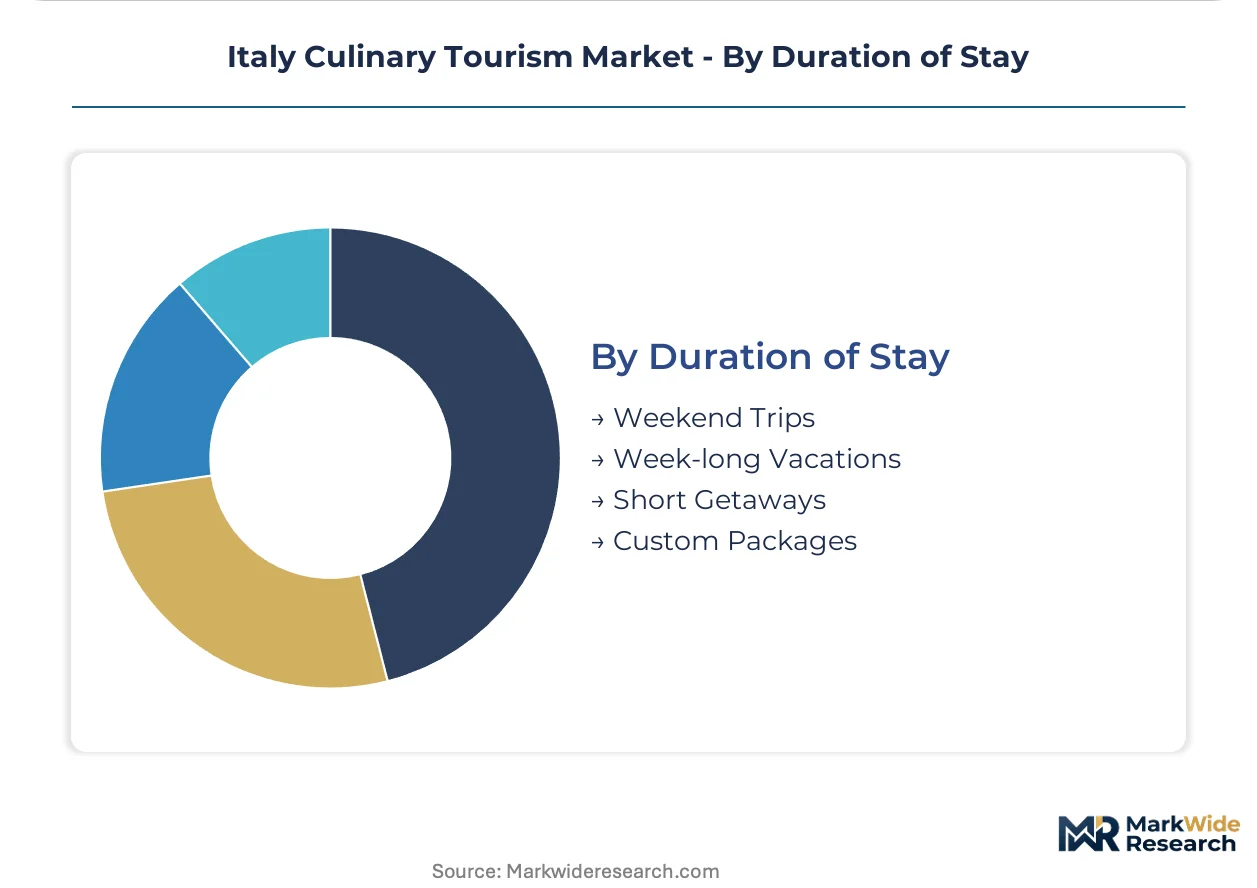
- Weekend Trips:Concentrated metropolitan dining and market visits with limited rural penetration. Rome and Milan absorb year-round traffic while farm visits face demand collapse.
- Week-long Vacations:Multi-region itineraries incorporating cooking classes, wine tours, and producer visits. Carbon-accounting implementation burdens mid-scale operators with compliance tooling investment.
- Short Getaways:2-4 day focused experiences in single regions like Tuscany or Sicily. Classic Journeys-style positioning through direct supplier contracts remains underdeveloped outside established corridors.
- Custom Packages:Bespoke itineraries requiring individualized planning and flexible supplier coordination. Asset-light franchise models reconfigure competitive dynamics for packaging complexity.
Week-long vacations absorb the majority of operator capacity; custom packages are gaining share fastest as personalization demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piedmont commands premium pricing for wine-centric itineraries while Emilia-Romagna's farm experiences operate at compressed yields. This asymmetry reflects divergent certification density and international distribution access across Italian culinary corridors.
Piedmont
Barolo and Barbaresco vineyard estates anchor multi-day wine tourism with certified sommelier requirements. The Ministry of Tourism's "Viaggi Italiani" framework mandates quality benchmarks for estate access licensing. Turin-based operators leverage rail connectivity under EU Green Deal alignment to capture preferential ENIT promotional placement.
Tuscany
Chianti Classico producers and farmhouse cooking schools absorb the majority of North American food enthusiast bookings. GDPR compliance through Italy's Data Protection Authority constrains personalized itinerary design based on traveler preference data. Florence-Siena corridor concentration strains certified instructor availability despite premium pricing power.
Emilia-Romagna
Parma's Parmesan consortium and Modena's balsamic vinegar acetaie drive provenance-transparent farm visit demand. Regional DMO co-marketing partnerships with ENIT streamline small-operator access to international distribution channels. Bologna-Parma-Modena gastronomic corridor expansion accelerates as travelers prioritize direct artisan engagement.
Sicily
Mount Etna wine producers and Palermo street food artisans attract Slow Food philosophy-aligned travelers from Northern Europe. Supply bottlenecks in qualified instructional personnel constrain cooking class expansion despite yield potential. Catania-based operators remain underdeveloped relative to Classic Journeys-style direct supplier contract models.
Lombardy
Milan's metropolitan gourmet dining absorbs year-round traffic with concentrated margin pools distinct from seasonal rural patterns. ISTAT expenditure tracking informs ENIT promotional allocation across source markets for the region. Franciacorta sparkling wine estates near Brescia represent emerging competition to traditional Tuscan and Piedmont positioning.
Italy Culinary Tourism Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with fragmented inventory access. The operator landscape concentrates around established luxury travel houses with cross-selling infrastructure, while rural single-region providers lack technical booking capabilities. Three archetypes dominate: asset-light franchise packagers, vertically integrated estate operators, and active-travel convergence specialists. Competitive moves center on DMO partnership securing for distribution access and certified instructor pipeline development for quality-controlled expansion.
Within the established luxury tier, Abercrombie & Kent and Butterfield & Robinson exemplify divergent convergence strategies, the former bundling exclusive vineyard access with private infrastructure, the latter integrating cycling routes with progressive meal formats. Classic Journeys occupies a position emphasizing deep artisan producer relationships through direct supplier contracts. These three entities anchor the competitive structure while Zingerman's Food Tours and Famiglia Rana represent alternative archetypes in specialized culinary packaging and family-owned experiential hospitality respectively.
| Leading Market Players |
|---|
| Zingerman's Food Tours |
| Abercrombie & Kent |
| Butterfield & Robinson |
| Famiglia Rana |
| La Rei Natura by Michelangelo Mammoliti |
| Classic Journeys |
| India Food Tour |
| La Terrazza |
| Foody Experience |
| Others |
Supply & Pricing Matrix
Bologna-Parma-Modena rail freight corridors anchor cost dynamics across Italy's culinary tourism supply chain, compressing logistics expenses for Emilia-Romagna operators while amplifying price differentiation between rail-connected gastronomic corridors and peripheral provinces dependent on road transport. This infrastructure asymmetry concentrates margin pools in corridor-adjacent farm visits and cooking classes while forcing rural Sicilian and Calabrian operators toward lower price tiers.
Pricing Analysis
Customization-premium spreads separate bespoke multi-day itineraries from standardized weekend packages across Tuscany and Piedmont. Three-tier pricing structure across premium, standard, and economy levels reflects certification density under the "Viaggi Italiani" framework, with certified instructor scarcity supporting premium tier pricing power. Cost compression in standard-tier street food tours is intensifying because quality variance erodes category pricing power. Food enthusiasts demonstrate lowest price sensitivity; family groups absorb highest sensitivity due to multi-generational booking complexity.
Supply Chain Analysis
Tariff exposure between EU and non-EU wine equipment suppliers dominates supply chain risk for vineyard estate operators upgrading tasting infrastructure. Geographic supply concentration centers on Italy for artisan food producers, France for enology equipment, and Germany for specialized transport refrigeration. Raw material dependencies encompass Parmigiano-Reggiano aging stock, traditional balsamic vinegar barrels, and certified organic wine grapes. Single-source vulnerability in certified instructor pipelines constrains capacity expansion. Distribution runs through ENIT-coordinated regional DMO portals connecting small operators to international travel platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's culinary tourism market represents early-cycle expansion anchored by rail-connected itinerary adoption under EU Green Deal alignment, with provenance transparency demand from North American and Northern European travelers accelerating penetration beyond traditional Tuscany-Piedmont corridors.
For Market Incumbents: Pre-empt certification bottlenecks by securing exclusive instructor pipelines through partnerships with regional culinary institutes in Piedmont and Sicily. Lock in direct supplier contracts with Parmesan consortiums and balsamic vinegar acetaie before competitor consolidation. Vertical integration into estate accommodation captures margin leakage to third-party lodging platforms. ENIT partnership tiering creates defensive moats against asset-light franchise entrants.
For New Entrants and Emerging Players: Sicily's artisan producer ecosystem represents the most penetrable entry point, with Mount Etna wine estates and Palermo street food artisans underserved by Classic Journeys-style direct contract models. Emilia-Romagna's gastronomic corridor offers white-space positioning through carbon-accounting compliant rail packages capturing preferential ENIT listing. Go-to-market execution should leverage verification technologies replacing brand trust among Northern European Slow Food members.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned agriturismo estates lacking technical booking infrastructure across Calabria and Puglia. Long-term viability hinges on certified instructor pipeline depth and DMO relationship tiering. Watch for inflection signals in ISTAT expenditure tracking showing sustained yield expansion in farm visit segments versus compression in metropolitan dining.
| Strategic Initiative | Industry Significance |
|---|---|
| "Viaggi Italiani" Certification Investment | Preferred ENIT campaign placement accelerates international distribution access for early adopters. |
| Direct Supplier Contracting | Exclusive Parmesan and balsamic vinegar estate access differentiates itinerary quality from packaged intermediaries. |
| Rail-Connected Itinerary Development | EU Green Deal alignment captures preferential listing on ENIT promotional platforms. |
| Certified Instructor Pipeline Development | Regional culinary credential partnerships resolve supply bottlenecks constraining high-yield experience expansion. |
| Verification Technology Deployment | Blockchain-enabled provenance tracking replaces brand trust for Northern European Slow Food membership segments. |
Research Methodology
Cross-validation between ISTAT expenditure tracking and ENIT promotional allocation data anchors the qualitative findings across Italy's culinary tourism landscape. Primary interviews with regional DMO directors, certified cooking instructors, vineyard estate operators, and travel platform procurement managers combined with secondary validation from EU tourism statistics, GDPR enforcement records through Italy's Data Protection Authority, and Slow Food membership databases. Bottom-up triangulation of operator-level booking data and top-down reconciliation with national tourism expenditure aggregates ensures methodological rigor.
Calibration against historical ENIT campaign performance and rail-connected itinerary adoption patterns shapes the analytical framework across the projection horizon. Segmentation dimensions encompass tour type, experience tier, visitor profile motivation, and duration of stay, with regional corridor connectivity as an industry-specific dimension. CAGRs derive from weighted averaging of operator-reported booking trajectories and infrastructure investment pipelines. Forecast inputs incorporate certified instructor supply elasticity and carbon-accounting compliance cost absorption rates.
Practitioners should monitor EU consumer protection regulation evolution and emerging tourism service carbon-accounting rules for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Industrial Tourism Market