
 Europe Destination Wedding Market | 2026-2036
Europe Destination Wedding Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Destination Wedding Market Foresight
Luxury hospitality involvement is consolidating as the fastest-rising vertical in Europe's destination wedding ecosystem. Belmond leverages its portfolio of historic European properties to anchor premium castle and vineyard ceremonies across Italy and Portugal. Wedded in Europe competes through curated local vendor networks that sustain deep destination expertise in saturated Mediterranean markets. FiestaSol differentiates by controlling seasonal charter logistics for Spanish island celebrations.
Europe destination weddings constitute cross-border ceremonial events where couples travel from their residence country to marry at a foreign venue, typically requiring coordination of legal documentation, local officiants, catering, floral design, and photography across jurisdictions. Castle weddings command premium pricing due to heritage venue scarcity and restricted capacity, while vineyard weddings attract oenophile couples seeking integrated estate experiences across Tuscany, Bordeaux, and Douro Valley. Photography and wedding planning services capture disproportionate margin pools because couples prioritize visual documentation and seamless multilingual coordination for guests arriving from multiple countries.
EU GDPR compliance shapes how European wedding planners collect and process international client data, while REACH and national environmental regulations govern floral import standards and venue chemical use across member states. The EU Green Deal's carbon reporting requirements are pressuring coastal resorts in Greece and Portugal to adopt renewable energy and waste reduction protocols. Stakeholders must monitor evolving Schengen visa processing times and bilateral marriage recognition treaties as geopolitical shifts alter cross-border couple mobility.
Market Dynamics
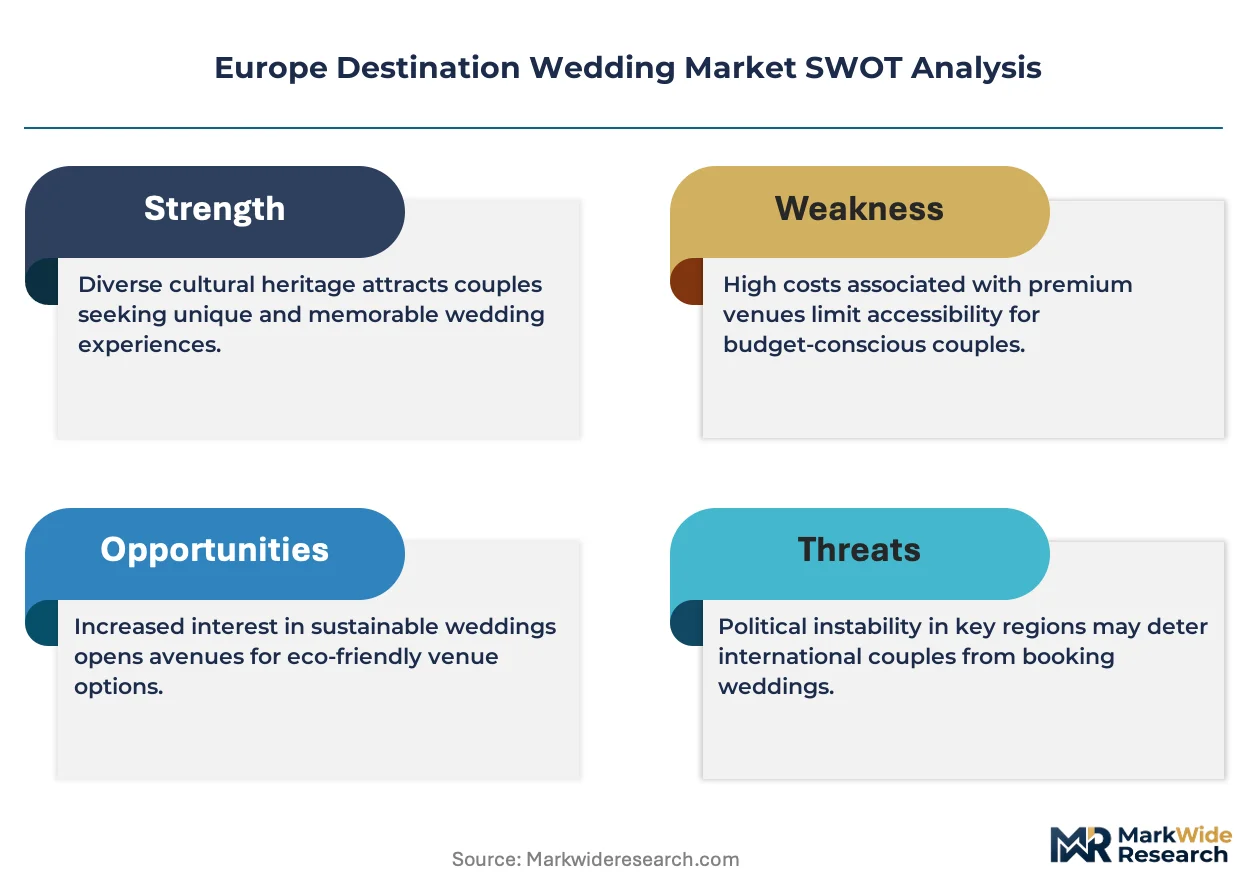
EU Green Deal carbon reporting mandates are forcing Mediterranean coastal resorts to retrofit energy systems and adopt waste reduction protocols, reshaping venue economics and supplier selection criteria across the European destination wedding ecosystem.
Growth Catalysts
- EU Green Deal compliance pressure:Carbon-neutral certification requirements from Brussels are accelerating renewable energy adoption at Greek island resorts and Portuguese vineyard estates, creating premium positioning for compliant venues.
- Schengen mobility facilitation:Streamlined cross-border guest travel within the visa zone reduces coordination friction for multi-national wedding parties, particularly benefiting Italian castle and coastal venues.
- Vineyard estate integration:Oenophile couples from Germany and the UK are driving demand for Tuscan and Douro Valley ceremonies that combine wine tourism with ceremonial events.
Market Restraints
- Heritage venue capacity scarcity:Italian castle and French château properties face strict preservation limits on guest numbers and structural modifications, constraining revenue per event.
- Floral import regulatory friction:REACH chemical standards and national phytosanitary rules create compliance costs and supply delays for non-EU flower sourcing, particularly affecting Dutch and Kenyan imports.
- Seasonal demand concentration:Mediterranean coastal resorts in Greece and Croatia operate at severe underutilization during November-March, distorting annual revenue recognition and staff retention.
Strategic Opportunities
- Portuguese Alentejo expansion:Underdeveloped vineyard and rural estate infrastructure in this southern region offers first-mover positioning before saturation reaches Tuscany levels.
- GDPR-compliant guest management platforms:Technology convergence between event planning software and encrypted international payment systems addresses data sovereignty requirements for multi-jurisdictional guest lists.
- Carbon offset bundling:The EU Green Deal's emissions disclosure framework creates white space for venues to package verified offset programs into premium ceremony pricing.
Industry Challenges
- Multilingual coordination talent scarcity:Fluent wedding planners capable of managing German, English, and Nordic-speaking guest contingents command premium wages that compress venue margins.
- Schengen visa processing volatility:Shifting bilateral recognition treaties and consular staffing gaps create unpredictable guest arrival timelines that complicate final headcount logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Destination Wedding Market |
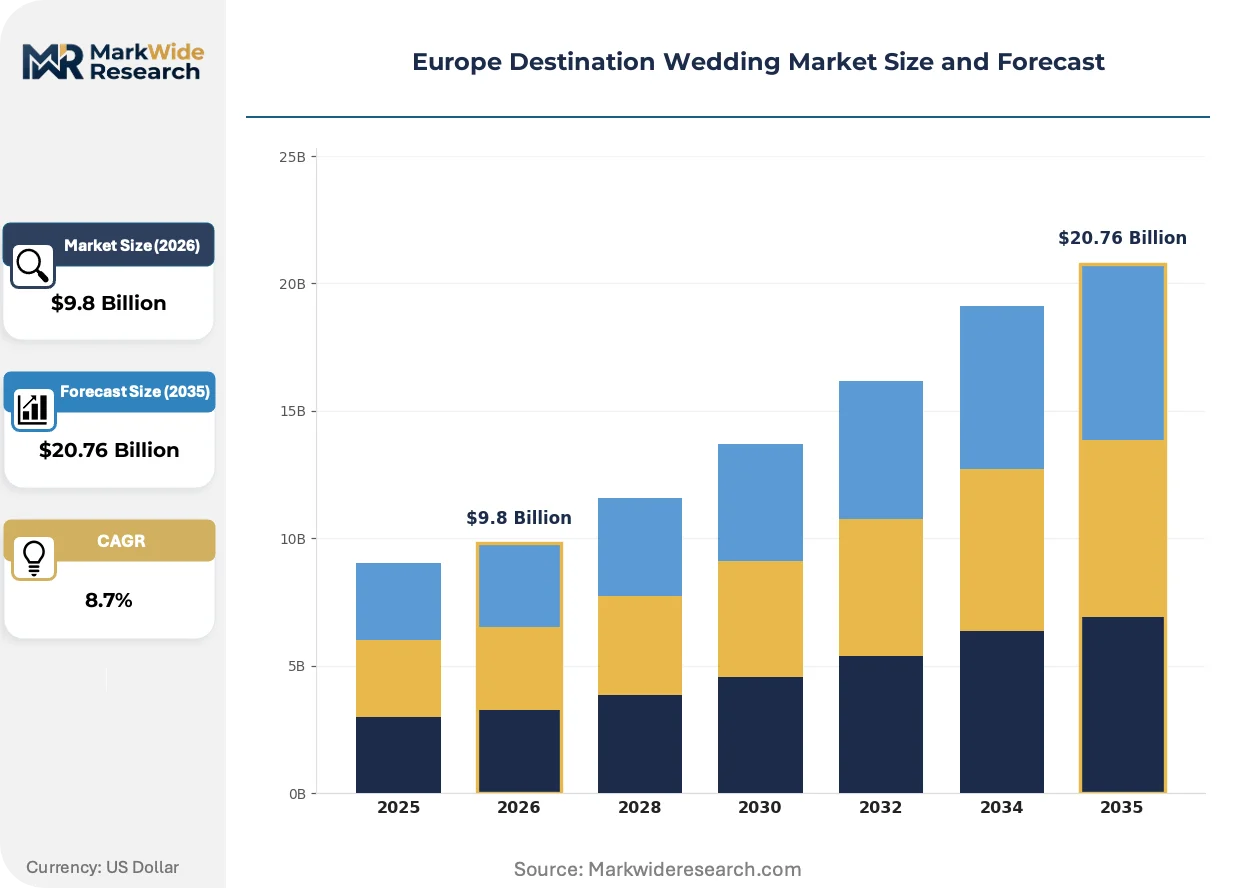
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Wedding Type: Beach Weddings, Castle Weddings, Vineyard Weddings, City Weddings Ceremony Size: Intimate Gatherings, Medium Groups, Large Celebrations, Elopements Service Type: Catering Services, Floral Arrangements, Photography, Wedding Planning Client Type: Couples, Wedding Planners, Travel Agents, Vendors |
| Companies Covered | Wedded in Europe, Culture Knot Weddings, Love Atlas Events, Belmond, Wed Voyage, White Eden Weddings, FiestaSol, The Wedding Travel Company, Wedding Planner Roma, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Destination Wedding Market Shifts & Advancements
Digital coordination tools and sustainability verification systems are compressing planning cycles and redefining premium positioning across European destination wedding markets. These shifts are altering how venues compete and how couples evaluate service providers.
AI-powered guest logistics platforms are modularizing the coordination of multi-national attendee arrivals, accommodation blocks, and local transportation across fragmented European vendor networks. High-net-worth couples from the UK and Germany are adopting these systems fastest, compressing what previously required six months of manual coordination into automated workflows that reduce planner headcount requirements.
GDPR enforcement by national data protection authorities is tightening how European wedding planners collect, store, and transfer international client information across borders. The regulation's cross-border processing rules are imposing audit and documentation burdens that disproportionately affect independent planners in Italy and Greece who lack dedicated compliance infrastructure, pushing consolidation toward hospitality-affiliated planning services.
Couples are unbundling traditional full-service packages in favor of à-la-carte vendor selection coordinated through digital marketplaces. This procurement model shift is disrupting the commission-based revenue structure of established destination planners in saturated markets like Tuscany and Santorini, while creating entry points for specialized Portuguese and Croatian vendors who compete on transparent pricing rather than relationship lock-in.
Europe Destination Wedding Market Segmentation
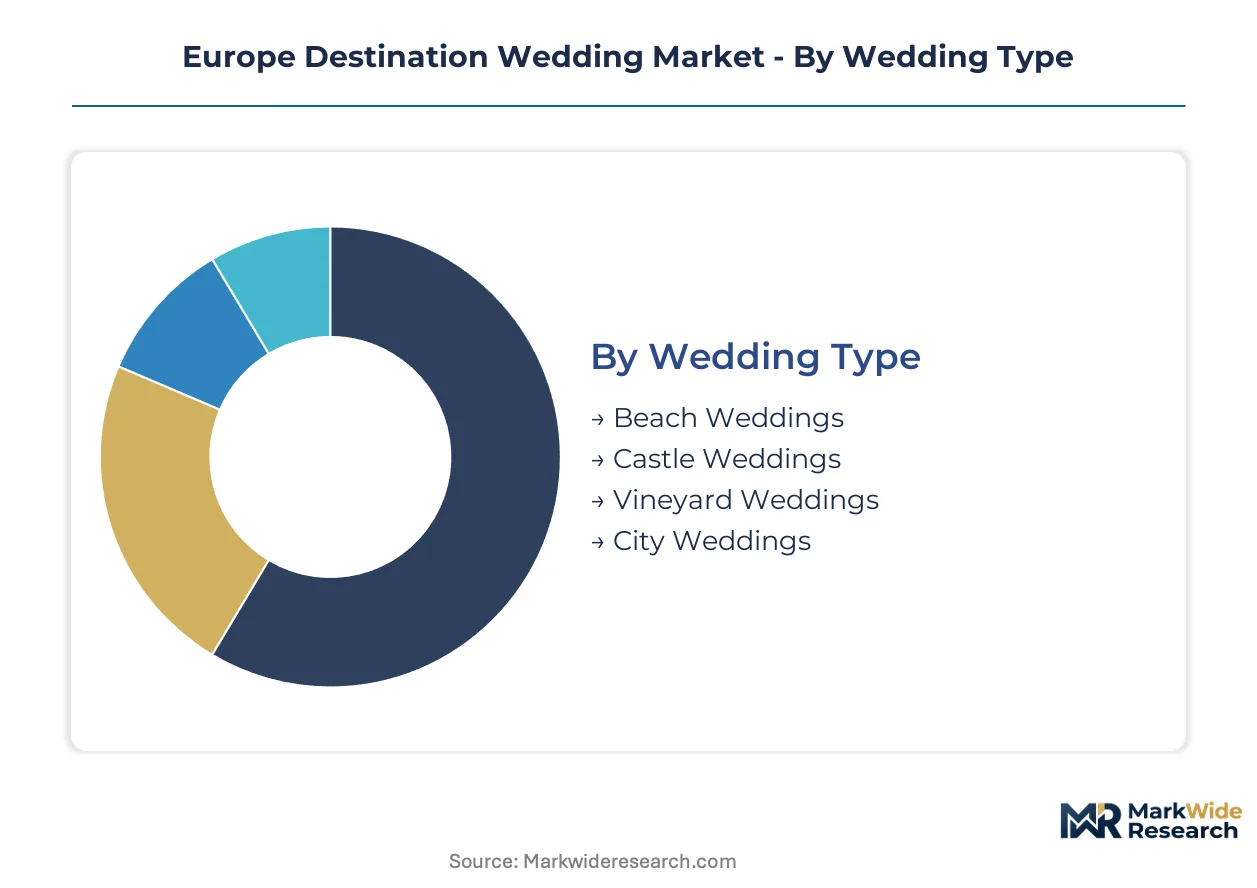
Segmentation in the European destination wedding market reveals how service providers configure offerings around venue scarcity, guest logistics complexity, and cross-border regulatory requirements. Understanding these divides exposes where margin pools concentrate and which customer types drive volume versus value.
Wedding Type:
Customization intensity spans from turnkey beach packages to fully bespoke castle ceremonies, with each format demanding distinct vendor ecosystems and legal coordination.
- Beach Weddings:Coastal ceremonies in Greece and Portugal rely on seasonal weather windows and municipal permitting for public shoreline access. Demand concentrates in Cyclades islands and Algarve cliffs where EU Green Deal compliance pressures reshape venue energy and waste protocols.
- Castle Weddings:Heritage properties across Italy and France impose strict preservation limits on guest capacity and structural modifications, constraining supply and sustaining premium pricing through scarcity.
- Vineyard Weddings:Estate-integrated ceremonies in Tuscany and Douro Valley attract oenophile couples seeking wine tourism fusion.
- City Weddings:Urban venues in Barcelona and Prague offer architectural backdrops with streamlined civil ceremony logistics.
Most installed capacity flows through Beach Weddings. Expansion is steepest in Vineyard Weddings.
Ceremony Size:
Guest count determines venue selection criteria, with heritage properties and private estates enforcing hard capacity ceilings that reshape procurement patterns.
- Intimate Gatherings:Ceremonies with under 20 guests favor boutique vineyard estates and private villas where per-head economics sustain premium service tiers. Italian planners report this format climbing fastest among German and Nordic couples prioritizing experience density over scale.
- Medium Groups:50-100 guest events dominate castle and coastal resort bookings, requiring multilingual coordination and block accommodation management.
- Large Celebrations:150+ guest counts demand dedicated logistics teams and Schengen visa coordination for multi-national attendee lists.
- Elopements:Two-person ceremonies with witness provision minimize legal complexity and vendor count.
Medium Groups capture the majority of venue nights. Intimate Gatherings are gaining share fastest among high-net-worth segments.
Service Type:
Margin distribution varies sharply between commoditized logistics and creative services protected by talent scarcity and portfolio differentiation.
- Photography:Visual documentation commands disproportionate pricing power as couples prioritize shareable content and album permanence. Mediterranean specialists with drone capability and multi-day coverage packages dominate premium positioning in Santorini and Amalfi.
- Wedding Planning:Full-service coordination captures value through risk reduction and vendor network access, with GDPR-compliant data handling becoming a competitive differentiator.
- Catering Services:Menu design and service staffing scale with guest count and dietary complexity.
- Floral Arrangements:REACH chemical standards and phytosanitary rules constrain import sourcing from Dutch and Kenyan suppliers.
Photography absorbs the largest share of incremental spend. Wedding Planning is expanding most quickly as regulatory complexity rises.
Client Type:
Decision-making authority and procurement sophistication diverge between direct couples and intermediary channels with established vendor relationships.
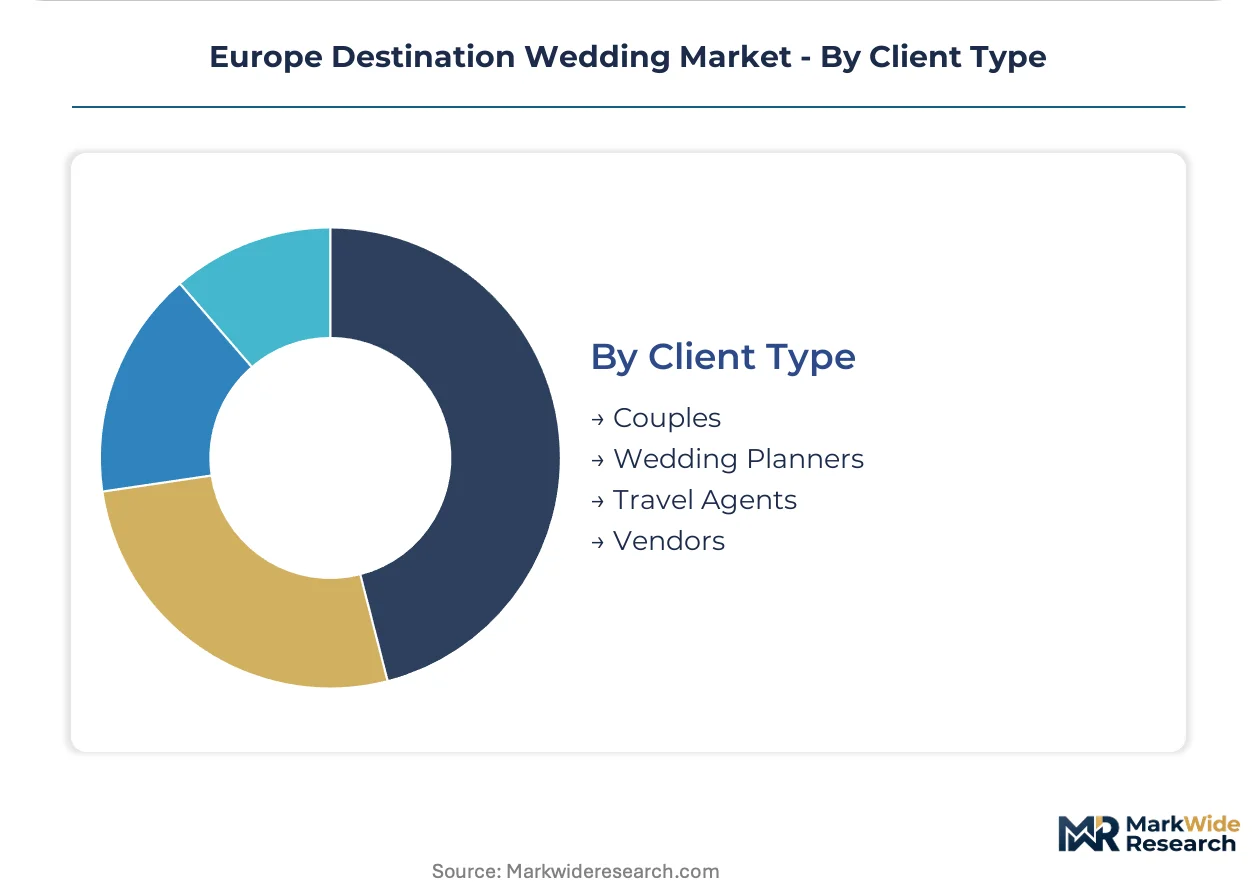
- Couples:Direct bookers increasingly unbundle packages and select à-la-carte vendors through digital marketplaces, compressing traditional planner commissions.
- Wedding Planners:Independent coordinators and hospitality-affiliated services compete on GDPR compliance infrastructure and multilingual talent access.
- Travel Agents:Package tour operators bundle ceremony logistics with guest accommodation blocks.
- Vendors:Individual service providers seek direct client relationships to bypass intermediary fees.
Couples represent the dominant booking channel. Wedding Planners are consolidating fastest as compliance burdens favor scaled operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping venue investment patterns across European destination wedding markets, as operators migrate capital toward jurisdictions with lighter heritage preservation burdens and faster municipal permitting timelines. Italy and Portugal attract disproportionate developer attention due to streamlined venue conversion pathways, while France and Greece impose stricter environmental and architectural compliance costs that slow new supply entry.
Italy
Tuscan vineyard estates and Amalfi coastal villas drive premium ceremony demand from German and UK couples seeking integrated wine tourism experiences. The country's Ministry of Cultural Heritage enforces strict preservation limits on castle modifications, constraining capacity expansion at heritage properties in Umbria and Sicily. Florence and Siena anchor the highest concentration of vineyard venues, where estate owners are retrofitting renewable energy systems to meet EU Green Deal carbon disclosure requirements.
Portugal
Douro Valley wine estates and Alentejo rural properties attract first-mover investment before saturation reaches Italian levels, with Nordic couples representing the fastest-growing origin segment. Lisbon's municipal authorities have accelerated licensing timelines for rural tourism conversions under national rural development frameworks. Porto and the northern wine region concentrate the majority of vineyard venue development, where operators bundle carbon offset programs into premium ceremony packages.
Greece
Cyclades island resorts and Crete coastal properties command peak-season premiums from North American and Australian couples prioritizing Aegean backdrops. The Hellenic Ministry of Environment enforces EU Green Deal waste reduction mandates that pressure smaller island venues to consolidate supplier networks. Santorini and Mykonos face severe capacity constraints during May-September, while underdeveloped islands in the Dodecanese attract charter logistics investment from seasonal operators.
France
Provence lavender estates and Loire Valley châteaux sustain pricing power through heritage scarcity, though bureaucratic venue conversion timelines deter rapid supply response. The country's national environmental regulator applies REACH chemical standards to floral import logistics, elevating compliance costs for non-EU flower sourcing. Bordeaux and Burgundy wine regions concentrate vineyard ceremony development, where estate owners balance preservation obligations against renewable energy retrofit investments.
Spain
Barcelona architectural venues and Balearic island resorts compete on streamlined civil ceremony logistics and extended seasonal operating windows. Madrid's regional tourism authorities have digitized multi-jurisdictional vendor licensing to reduce coordination friction for international couples. Mallorca and Ibiza dominate island ceremony volume, where seasonal charter operators control guest logistics through integrated ferry and accommodation block management.
Europe Destination Wedding Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with luxury hospitality groups consolidating premium castle and vineyard verticals while independent planners retain fragmented coastal and city markets. Market structure tilts toward tiered competition: hospitality-affiliated services leverage GDPR compliance infrastructure and multilingual talent pools, while boutique operators compete through hyperlocal vendor relationships and transparent à-la-carte pricing. Three archetypes dominate: heritage property operators, digital marketplace coordinators, and seasonal logistics controllers. M&A activity concentrates among hospitality groups acquiring regional planning firms, and portfolio diversification into adjacent wine tourism experiences.
Among independent planning specialists, Wedded in Europe, Culture Knot Weddings, and Belmond occupy distinct positioning vectors. Wedded in Europe exemplifies the curated local network archetype, sustaining deep destination expertise in saturated Mediterranean markets through vendor relationship density rather than scale infrastructure. Culture Knot Weddings represents the boutique customization tier, competing on transparent procurement and unbundled service selection. Belmond anchors the hospitality-integrated premium segment, leveraging historic European property portfolios to control scarce heritage venue access and capture margin pools from integrated accommodation and ceremony logistics.
| Leading Market Players |
|---|
| Wedded in Europe |
| Culture Knot Weddings |
| Love Atlas Events |
| Belmond |
| Wed Voyage |
| White Eden Weddings |
| FiestaSol |
| The Wedding Travel Company |
| Wedding Planner Roma |
| Others |
Supply & Pricing Matrix
AI-powered guest logistics platforms are compressing coordination timelines and collapsing traditional commission structures, simultaneously reducing planner headcount requirements and shifting margin capture toward technology-enabled venues that bundle automated workflows into premium ceremony packages.
Pricing Analysis
Planner commission markups absorb the dominant share of channel margin in Europe's destination wedding ecosystem. Three-tier pricing structure across premium, standard, and economy levels separates heritage castle ceremonies with dedicated multilingual coordination from streamlined beach packages with vendor marketplace procurement. Cost compression in mid-tier vineyard offerings is intensifying because couples increasingly unbundle services through digital marketplaces. German and Nordic direct bookers demonstrate highest price sensitivity, while UK high-net-worth couples prioritize portfolio differentiation over transparent pricing.
Supply Chain Analysis
EU Green Deal domestic-content mandates for renewable energy retrofitting are reshaping venue sourcing toward certified local contractors and regional floral networks. Supply concentrates in Italy, Portugal, and Greece, with Italian castle properties and Greek island resorts anchoring heritage venue scarcity. The ecosystem draws from Dutch floral imports, Tuscan estate wine partnerships, and Portuguese charter logistics operators. Single-source vulnerability runs through seasonal ferry operators controlling Balearic and Cyclades island access. Distribution runs through hospitality-affiliated planning services with GDPR-compliant data infrastructure and independent vendor marketplaces with transparent à-la-carte procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's destination wedding market rests on carbon offset bundling into premium ceremony pricing and automated guest logistics reducing planner wage burdens across multi-national coordination workflows.
For Market Incumbents: Hedge against commission erosion by acquiring GDPR-compliant technology platforms and securing exclusive heritage venue contracts before independent planners consolidate. Independent coordinators with hyperlocal vendor density in saturated Tuscan and Santorini markets face displacement from hospitality-affiliated services with scaled compliance infrastructure. Backward integration into vineyard estate ownership captures margin pools from integrated wine tourism experiences.
For New Entrants and Emerging Players: Boutique Portuguese vineyard estates represent the most penetrable white-space target, with Alentejo rural properties offering first-mover positioning before saturation reaches Italian levels. Nordic couples seeking Douro Valley ceremonies with carbon-neutral certification represent underserved demand. A specialized vendor marketplace with transparent pricing and REACH-compliant floral sourcing addresses regulatory friction that compresses independent planner margins.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent planning specialists in Italy and Greece who lack dedicated GDPR compliance infrastructure and face consolidation pressure. Long-term viability favors hospitality groups with captive heritage venue portfolios and technology-enabled coordination platforms. The signal to watch is Schengen visa processing volatility, which compresses booking lead times and favors operators with flexible cancellation architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Offset Bundling Program | EU Green Deal disclosure requirements create premium pricing white space for verified emission reduction packages. |
| GDPR-Compliant Platform Acquisition | Data sovereignty infrastructure separates scalable hospitality-affiliated planners from fragmented independent operators. |
| Vineyard Estate Vertical Integration | Captive supply of Tuscan and Douro Valley ceremony venues captures margin from integrated wine tourism experiences. |
| AI Guest Logistics Deployment | Automated multi-national coordination compresses six-month manual workflows and reduces planner headcount requirements. |
| Alentejo First-Mover Expansion | Underdeveloped Portuguese rural estate infrastructure offers positioning before saturation reaches Italian market levels. |
Research Methodology
Multiple input streams — primary interviews with wedding planning executives, venue procurement directors, and floral supply coordinators; secondary validation through EU regulatory filings, national tourism board statistics, and hospitality group sustainability disclosures; plus customs data on floral imports — were reconciled through bottom-up venue capacity modeling and top-down ceremony spend estimation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include wedding type, ceremony size, service tier, and client procurement channel, with regional regulatory cluster and Schengen mobility framework as cross-cutting variables. CAGRs were derived from venue night utilization curves and per-ceremony spend trajectories, incorporating EU Green Deal compliance cost pass-through and digital platform adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Schengen visa policy shifts, bilateral marriage recognition treaty revisions, and heritage preservation regulation tightening. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
Smart Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Germany Culinary Tourism Market