
 North America Museums, Historical Sites, Zoos, and Parks Market | 2026-2036
North America Museums, Historical Sites, Zoos, and Parks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Museums, Historical Sites, Zoos, and Parks Market Insights
Canada's cultural infrastructure expansion is rewriting how institutions compete for cross-border visitors. The Smithsonian Institution leverages its federal mandate and vast collections to sustain attendance across multiple museum categories. The American Museum of Natural History anchors New York City's position through immersive exhibition technology and planetary science programming. Cincinnati Zoo & Botanical Garden differentiates via conservation breeding programs that extend its brand beyond traditional zoo boundaries.
North America museums, historical sites, zoos, and parks constitute visitor-facing institutions that preserve, interpret, and exhibit cultural, natural, or historical collections through curated physical environments, digital interfaces, and educational programming; facilities range from climate-controlled galleries maintaining 50-55% relative humidity for artifact conservation to open-air historical sites requiring seasonal maintenance protocols. The primary commercial purpose centers on generating earned revenue through admissions and memberships while securing philanthropic support for capital projects and collection stewardship. Revenue stream segmentation reveals admissions and memberships as the dominant recurring income pool, with merchandise representing a higher-margin but smaller-volume category. Operational model segmentation shows hybrid public-private structures capturing the fastest growth as municipalities seek to offset operating deficits through foundation partnerships and concession outsourcing.
The National Park Service and Parks Canada set access standards, conservation mandates, and capital funding priorities that shape regional investment patterns across the United States and Canada. State-level historic preservation tax credits and Canadian federal cultural infrastructure grants further direct private capital toward rehabilitation projects and new construction. Stakeholders must monitor how shifting public funding formulas and donor expectations around climate resilience reshape capital allocation decisions across the forecast horizon.
Market Dynamics
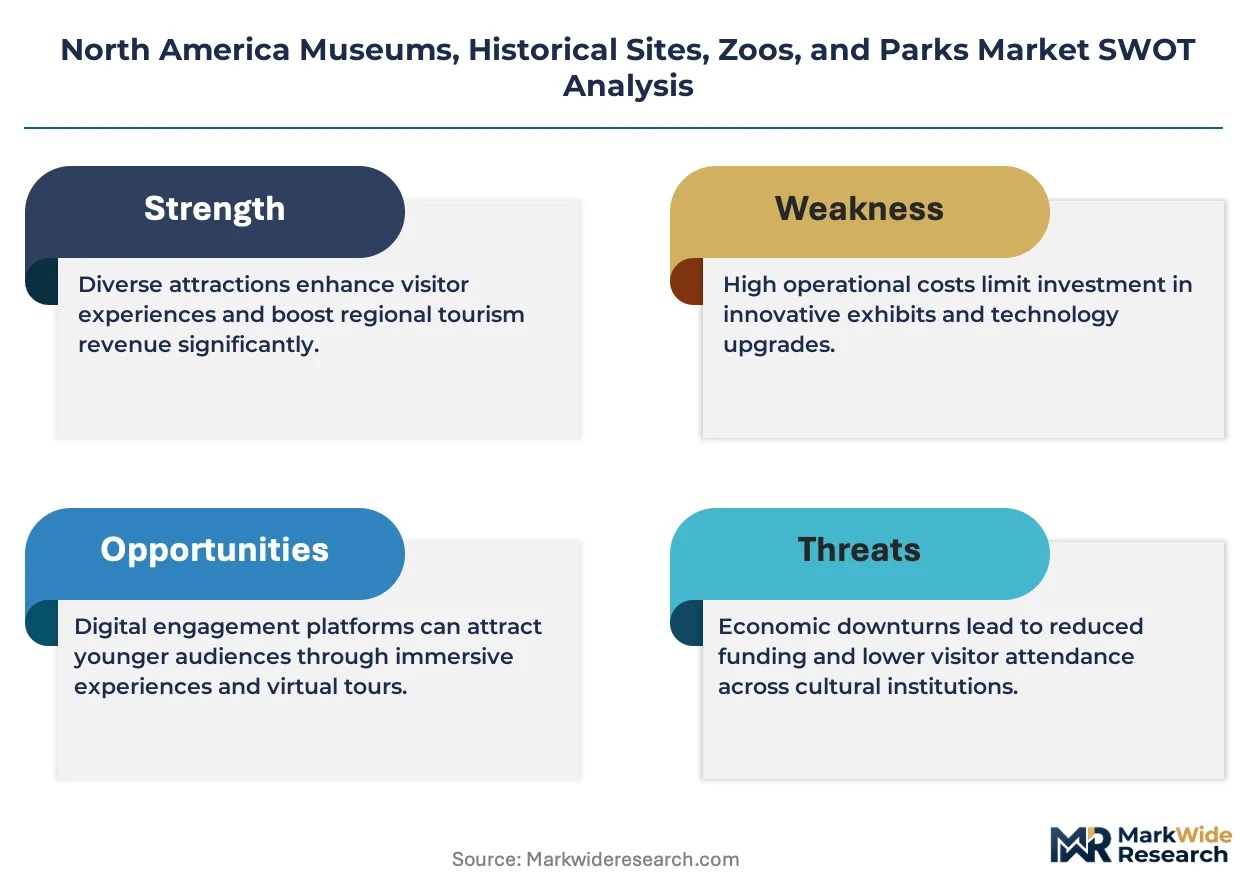
Digital engagement platforms are compressing the traditional admissions model as institutions race to convert virtual visitors into physical ticket buyers and recurring members.
Growth Catalysts
- State Historic Preservation Tax Credits:The US program redirects private capital toward rehabilitation of aging infrastructure, accelerating renovation timelines for municipal institutions.
- Conservation Breeding Programs:Zoological facilities leverage endangered species protocols to secure federal grants and differentiate membership value beyond traditional animal displays.
- California Cultural Corridor:Concentrated visitor demand between Los Angeles and San Francisco generates sponsorship pools that smaller markets cannot replicate.
Market Restraints
- Deferred Maintenance Backlog:The National Park Service redirects available capital toward public-private partnerships, constraining direct federal construction funding.
- Climate-Controlled Storage Costs:Artifact conservation requires 50-55% relative humidity maintenance, driving energy expenditures that strain operating budgets.
- Seasonal Labor Volatility:Open-air historical sites depend on temporary staffing pools that compress margin stability across winter months.
Strategic Opportunities
- Canadian Federal Cultural Infrastructure Grants:Ottawa's expansion program creates acquisition opportunities for US institutions seeking cross-border collection partnerships.
- Immersive Exhibition Technology:Planetarium and science museum convergence with virtual reality platforms opens sponsorship categories from technology vendors.
- Foundation Partnership Structures:Hybrid public-private operational models allow municipalities to outsource concession management while retaining curatorial control.
Industry Challenges
- Digital-Physical Integration:Institutions struggle to synchronize collection databases with mobile visitor interfaces without duplicating curatorial labor.
- Climate Resilience Compliance:Donor expectations now mandate carbon accounting for capital projects, extending fundraising timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Museums, Historical Sites, Zoos, and Parks Market |
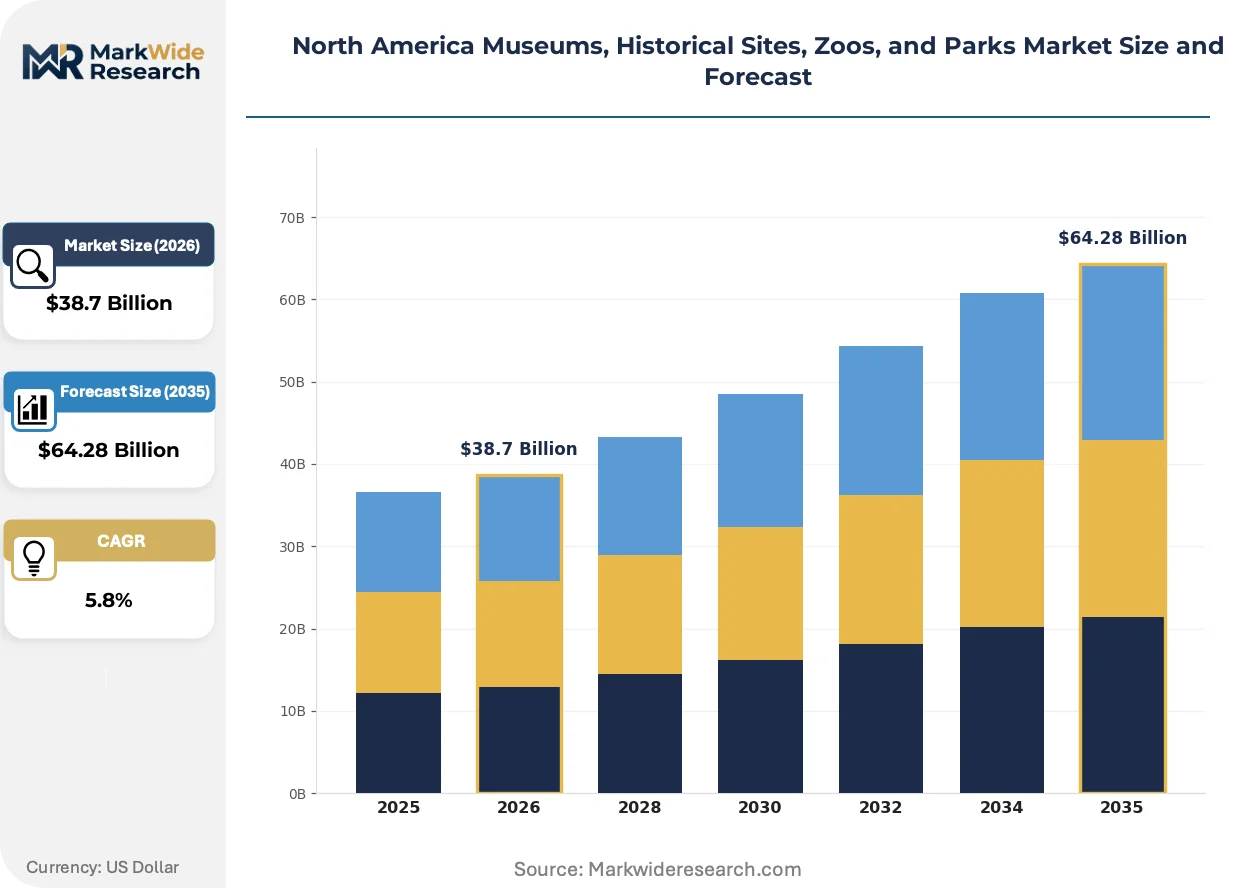
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Attraction Type: Museum, Historical Site, Zoo, Park Visitor Demographics: Families, Tourists, Students, Seniors Revenue Stream: Admissions, Memberships, Donations, Merchandise Operational Model: Public, Private, Non-Profit, Hybrid |
| Companies Covered | Smithsonian Institution, National Gallery of Art, Art Institute of Chicago, The American Museum of Natural History, Cincinnati Zoo & Botanical Garden, USS Midway Museum, Museum of Anthropology at UBC, The Montreal Museum of Fine Arts, Art Gallery of Ontario, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Museums, Historical Sites, Zoos, and Parks Market Trends and Innovations
Visitor-facing institutions are reconstructing revenue architecture around experiential depth rather than throughput volume, trading admission maximization for membership retention.
Extended reality installations are hybridizing static gallery environments with responsive digital layers. Major natural history museums deploy projection-mapped fossil exhibits that adapt narratives to visitor age demographics. The technology is hybridizing curatorial labor models, compressing docent staffing ratios while expanding personalized engagement depth.
The US National Park Service's deferred maintenance framework is forcing concession restructuring across federal landholdings. Private operators now bid for multi-decade service contracts that bundle retail, food, and lodging under unified revenue-share agreements. Wilderness-adjacent properties face the steepest compliance burdens as accessibility mandates expand trail modification requirements.
Membership programs are displacing single-ticket purchases as the dominant buyer relationship format. Cultural institutions in the US Northeast bundle reciprocal access across multiple museums, consolidating family entertainment budgets into annual commitments. This concentration is most visible in metropolitan corridors where density supports network effects between competing facilities.
North America Museums, Historical Sites, Zoos, and Parks Market Segmentation
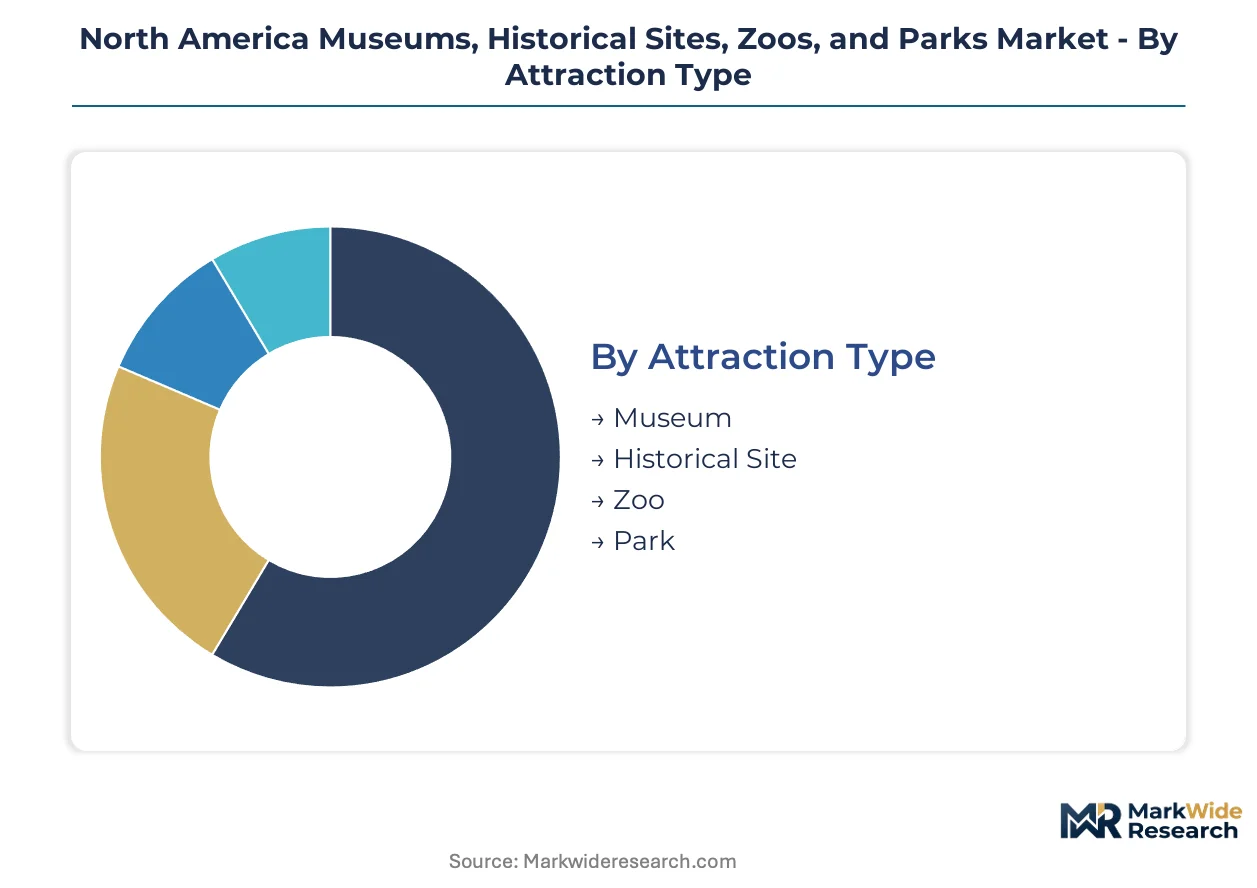
Segmentation in the North America museums, historical sites, zoos, and parks market reveals how operational models and revenue architectures determine capital access and visitor retention strategies. Institutions face divergent investment horizons depending on their funding mechanisms and audience composition.
Attraction Type:
After-sales intensity varies dramatically across attraction types, with zoos and living collections requiring continuous veterinary support and habitat maintenance versus static museum galleries.
- Museum:Climate-controlled environments maintain 50-55% relative humidity for artifact preservation. Demand concentrates in metropolitan corridors from Los Angeles to San Francisco where foundation density supports endowment growth. Smithsonian Institution properties anchor federal funding flows that smaller municipal museums cannot replicate.
- Historical Site:Open-air structures require seasonal maintenance protocols and interpretive staffing that fluctuates with weather patterns. Demand clusters in the US Northeast where state historic preservation tax credits accelerate rehabilitation timelines. The National Park Service's deferred maintenance backlog constrains direct federal construction investment at these properties.
- Zoo:Living collections mandate daily veterinary oversight and specialized nutrition supply chains. Cincinnati Zoo & Botanical Garden leverages conservation breeding programs to differentiate membership value and secure federal grants.
- Park:Wilderness-adjacent properties face expanding accessibility mandates that drive trail modification requirements. Parks Canada and the National Park Service set conservation standards that shape regional capital allocation.
By volume, Park leads. By growth pace, Museum is ahead.
Visitor Demographics:
Customer lifetime value calculations diverge sharply across demographic segments, with family memberships generating recurring revenue against single-visit tourist traffic.
- Families:Annual membership commitments consolidate entertainment budgets across multiple institutions. US Northeast cultural corridors bundle reciprocal access agreements that deepen retention metrics.
- Tourists:Single-ticket purchases concentrate in gateway cities with international airport connectivity. California's cultural corridor captures disproportionate sponsorship pools from this transient audience.
- Students:Digital engagement platforms are compressing traditional group visit models as institutions convert virtual interactions into physical field trips. Smithsonian Institution programming anchors federal educational mandates.
- Seniors:Reciprocal access networks and off-peak scheduling preferences shape programming calendars. This segment commands disproportionate volunteer labor contribution relative to admission revenue.
Families generate the highest lifetime value. Students are expanding most quickly as digital conversion tactics mature.
Revenue Stream:
Margin profiles separate recurring membership income from transactional merchandise sales, with hybrid models capturing operational stability.
- Admissions:Single-ticket revenue faces compression from digital engagement alternatives. Tiered pricing structures separate peak from off-peak visitation windows.
- Memberships:Recurring commitments now dominate buyer relationships in dense metropolitan markets. Consolidated family entertainment budgets support network effects between competing facilities.
- Donations:Philanthropic capital flows toward climate resilience compliance and collection stewardship. Donor expectations now mandate carbon accounting for capital projects.
- Merchandise:Higher-margin retail operates through concession outsourcing arrangements. Private operators bid for multi-decade service contracts bundling retail, food, and lodging.
Memberships lead by revenue stability. Merchandise claims the steepest expansion trajectory as experiential retail deepens.
Operational Model:
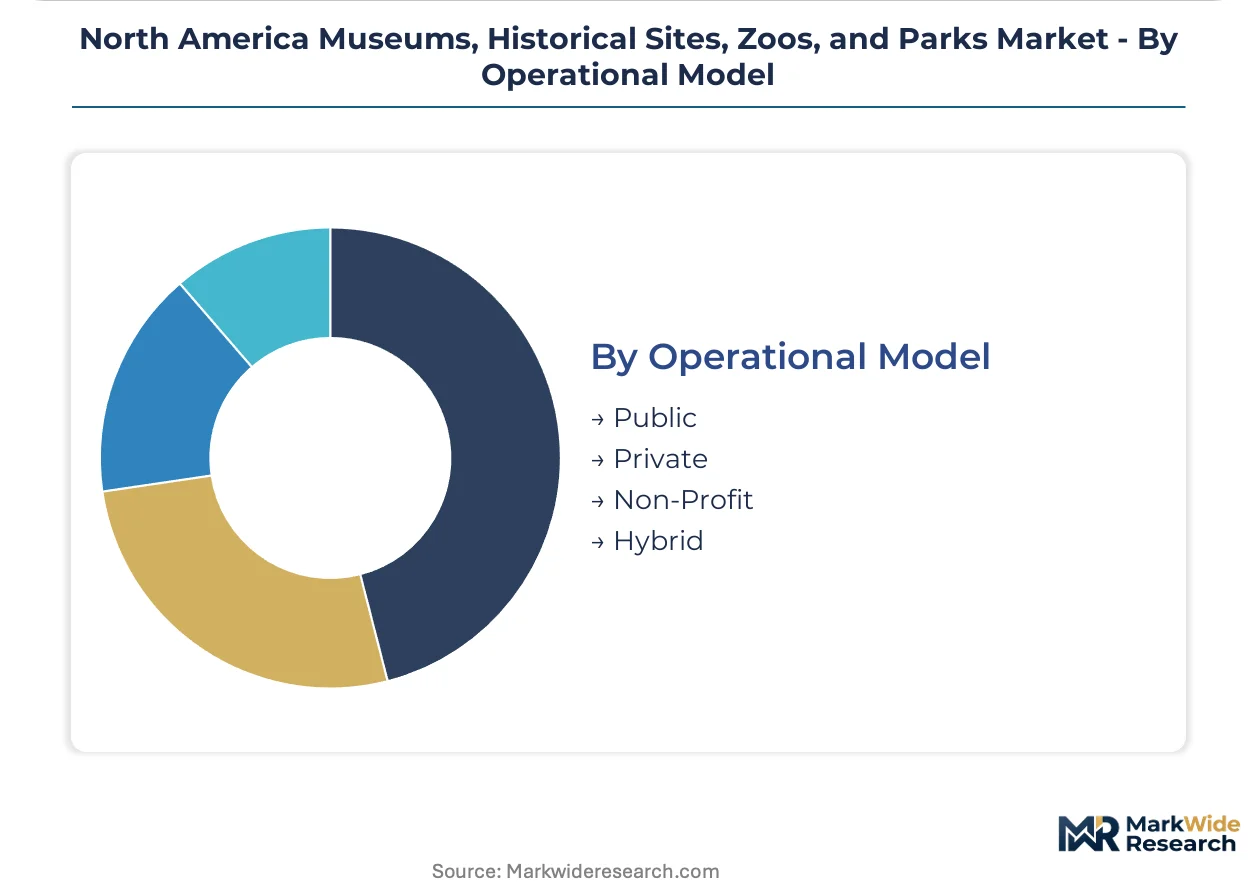
Capital access and curatorial autonomy trade off across ownership structures, with hybrid formations capturing fastest growth as municipalities offset deficits.
- Public:Direct municipal ownership faces operating deficit pressures that accelerate concession restructuring. State-level historic preservation tax credits redirect private capital toward rehabilitation.
- Private:For-profit operators concentrate in entertainment-oriented attractions with throughput maximization strategies. Federal land concession contracts now bundle unified revenue-share agreements.
- Non-Profit:Foundation-dependent institutions compete for donor attention around climate resilience narratives. Endowment management expertise separates sustainable operations from cyclical distress.
- Hybrid:Public-private structures allow municipalities to outsource concession management while retaining curatorial control. Canadian federal cultural infrastructure grants create acquisition opportunities for cross-border collection partnerships.
Hybrid models are gaining share fastest. Public institutions retain volume leadership through federal land holdings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Canada diverge sharply in institutional funding architecture, with American facilities leaning on philanthropic endowments and Canadian operations drawing heavier from federal cultural infrastructure grants. Mexico's emerging museum sector operates on municipal budgets with limited private foundation density.
United States
California's cultural corridor from Los Angeles to San Francisco concentrates sponsorship pools and foundation endowments that smaller markets cannot replicate. The National Park Service's deferred maintenance backlog redirects available capital toward public-private partnership structures rather than direct federal construction grants. The Smithsonian Institution anchors federal funding flows across Washington D.C. and New York City metropolitan clusters.
Canada
Ottawa's cultural infrastructure expansion program creates acquisition opportunities for cross-border collection partnerships with American institutions. Parks Canada sets conservation standards and access mandates that shape provincial capital allocation decisions from British Columbia to Ontario. The Museum of Anthropology at UBC and Montreal Museum of Fine Arts anchor federal grant distribution in Vancouver and Quebec cultural corridors.
Mexico
Mexico City's metropolitan zone concentrates national museum attendance and federal cultural ministry investment against limited private foundation presence. The Instituto Nacional de Antropología e Historia oversees preservation mandates and rehabilitation funding for pre-Columbian sites across the Yucatán Peninsula and central highlands. Regional historical sites in Oaxaca and Chiapas operate on constrained state budgets with seasonal tourism dependency.
North America Museums, Historical Sites, Zoos, and Parks Market Competitive Landscape
Capability concentration sits with endowed federal institutions possessing collection depth and curatorial expertise; scale advantage sits with metropolitan museums commanding sponsorship density and membership network effects. The market structures around three tiers: federally mandated anchor institutions, foundation-dependent regional museums, and hybrid public-private operators. Consolidation pressure manifests through reciprocal access networks and multi-institution membership bundling rather than ownership mergers. Competitive moves center on immersive technology deployment and concession outsourcing to private operators.
Within the federally anchored tier, the Smithsonian Institution and National Gallery of Art occupy positions defined by congressional funding mandates and collection scale that municipal competitors cannot replicate. Among conservation-focused zoological operators, Cincinnati Zoo & Botanical Garden exemplifies the breeding program differentiation archetype. The American Museum of Natural History represents the immersive exhibition technology vector, while Art Institute of Chicago anchors Midwest foundation density.
| Leading Market Players |
|---|
| Smithsonian Institution |
| National Gallery of Art |
| Art Institute of Chicago |
| The American Museum of Natural History |
| Cincinnati Zoo & Botanical Garden |
| USS Midway Museum |
| Museum of Anthropology at UBC |
| The Montreal Museum of Fine Arts |
| Art Gallery of Ontario |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in seasonal labor pools across Northeastern historical sites compresses wage negotiations while forcing institutions toward year-round contract staffing arrangements that reshape both cost structures and visitor service levels.
Pricing Analysis
Long-term concession contracts now dominate revenue-share arrangements across federal landholdings, replacing spot-based vendor relationships. Three-tier pricing structure across premium, standard, and economy levels separates Smithsonian anchor properties from regional museums and municipal historical sites. Price differentiation rests on immersive technology deployment and conservation breeding program access. Cost compression in mid-tier institutions is intensifying because energy expenditures for climate-controlled storage now consume disproportionate operating budgets. Family membership segments show lowest price sensitivity due to consolidated entertainment budget commitments, while transient tourist traffic demands dynamic peak-off-peak tiering.
Supply Chain Analysis
Extended payment terms from specialized exhibition fabricators now stretch to 90-120 days as supplier-financing facilities absorb working capital pressure from institutional clients. Geographic supply concentration centers on domestic conservation material specialists, Canadian cultural infrastructure contractors, and specialized veterinary pharmaceutical suppliers for zoological collections. Raw material dependencies include archival-grade climate control systems, projection-mapped display hardware, and endangered species nutrition formulations. Single-source vulnerability sits with specialized habitat design firms serving AZA-accredited zoos. Distribution runs through regional museum service consortia that aggregate procurement for smaller municipal institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-institution membership bundling across metropolitan corridors, consolidating individual family entertainment decisions into collective annual commitments that reshape institutional revenue predictability.
For Market Incumbents: Pre-empt competitive erosion by securing exclusive concession contracts across adjacent federal landholdings before public-private partnership windows close. Anchor defensive positioning through backward integration into immersive technology development rather than vendor dependency. The deferred maintenance backlog at the National Park Service threatens direct federal construction access, making foundation relationship depth the critical lever for capital project funding. For New Entrants and Emerging Players: Pursue white-space acquisition in Canadian federal cultural infrastructure grant pipelines, where Ottawa's expansion program creates partnership entry points unavailable in saturated US metropolitan markets. Target hybrid operational model consulting for municipalities seeking to outsource concession management while retaining curatorial control. The most penetrable segment sits with mid-sized historical sites in secondary US cities lacking in-house development expertise for digital-physical integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among zoological institutions with conservation breeding program differentiation, where federal grant streams and membership retention mutually reinforce cash flow stability. Long-term viability across the projection horizon favors endowed institutions with collection depth over throughput-dependent entertainment attractions. The signal to monitor is foundation partnership density in metropolitan corridors, as network effects between competing facilities accelerate winner-take-most membership concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Technology Deployment | Projection-mapped exhibits at American Museum of Natural History compress docent ratios while expanding personalized engagement depth. |
| Conservation Breeding Program Expansion | Cincinnati Zoo's endangered species protocols secure federal grants and differentiate membership value beyond traditional animal displays. |
| Hybrid Operational Model Adoption | Public-private structures allow municipalities to outsource concession management while retaining curatorial control over collections. |
| Cross-Border Collection Partnership | Canadian federal cultural infrastructure grants create acquisition opportunities for US institutions seeking collection depth expansion. |
| Multi-Institution Membership Bundling | Reciprocal access networks in US Northeast corridors consolidate family entertainment budgets into annual recurring commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with museum directors, zoo curators, historical site preservation officers, federal land management officials, and cultural foundation program officers. Secondary validation drew from National Park Service budget disclosures, Parks Canada capital allocation reports, Smithsonian Institution annual reports, AZA accreditation databases, and state historic preservation tax credit utilization records. Bottom-up triangulation across individual institution operating models converged with top-down sector aggregation from federal funding flow analysis.
Calibration against historical attendance volatility and capital project completion timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include attraction type, visitor demographic archetype, revenue stream composition, and operational model structure. CAGRs were derived from regression analysis of membership renewal rates, concession revenue trajectories, and federal grant appropriation patterns. Industry-specific forecast inputs incorporated climate resilience compliance cost curves and digital engagement platform adoption velocities.
Sensitivities concentrate around public funding formula shifts, donor expectation evolution regarding carbon accounting, and digital-physical integration technology cost curves. Forecasts reflect documented assumptions regarding foundation endowment growth rates and federal land management policy continuity. Macroeconomic contraction affecting discretionary family entertainment spending, regulatory restriction on federal land concession restructuring, or technological disruption in immersive exhibition formats would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Cultural Tourism Market