
 Museums, Historical Sites, Zoos, and Parks Market | 2026-2036
Museums, Historical Sites, Zoos, and Parks Market Size, Share, and Industry Trends Forecast 2026-2036
Museums, Historical Sites, Zoos, and Parks Market Insights
Visitor demand from school groups and educational institutions is consolidating around large metropolitan institutions with established curriculum partnerships. The Smithsonian Institution leverages its federal charter and nineteen museums to sustain nationwide educational programming. The Metropolitan Museum of Art competes through specialized conservation expertise and encyclopedic collection breadth. The American Museum of Natural History anchors its position with deep research integration and planetarium technology leadership.
Museums, historical sites, zoos, and parks constitute physical institutions dedicated to conservation, exhibition, and public education of cultural, natural, and scientific heritage, typically operating across indoor climate-controlled galleries and outdoor landscaped environments with specialized HVAC, lighting, and security infrastructure. The site type dimension spans museums, aquariums, botanical gardens, and nature preserves, with aquariums commanding premium capital intensity for marine life support systems. Exhibition format segments divide into interactive, static, traveling, and seasonal formats, where interactive installations attract repeat visitation and command higher per-capita ancillary spending.
Regulatory oversight from the National Park Service, state heritage commissions, and municipal zoning boards shapes site accessibility standards, conservation protocols, and expansion permits across the United States. EPA guidelines on chemical storage and OSHA visitor safety requirements further constrain operational parameters for institutions housing living collections or fragile artifacts. Stakeholders must monitor evolving funding source diversification as public grant dependence creates vulnerability to fiscal austerity cycles.
Market Dynamics
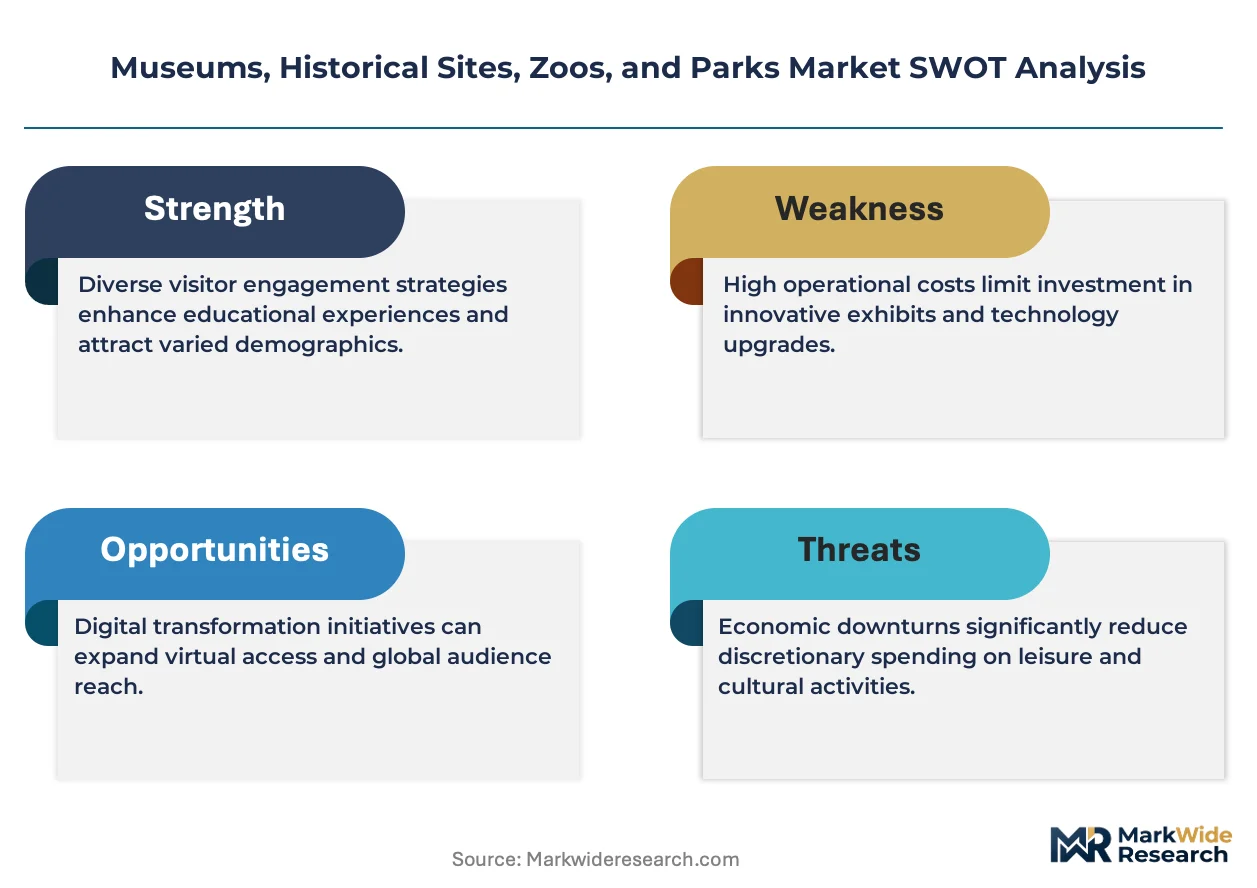
Federal digitization mandates under heritage protection frameworks are forcing capital reallocation toward digital preservation infrastructure, compressing traditional exhibition budgets while expanding virtual access capabilities.
Growth Catalysts
- Educational Tourism Expansion:School districts across the United States are formalizing curriculum partnerships with metropolitan institutions, creating recurring group visitation blocks that stabilize off-peak revenue.
- EPA Chemical Storage Guidelines:Living collection institutions must upgrade containment systems, generating retrofit demand for specialized HVAC and water quality monitoring vendors.
- Immersive Projection Mapping:Planetariums and aquariums deploy dome-based visualization systems that extend dwell time and drive ancillary concession spending per visitor.
Market Restraints
- Municipal Funding Volatility:Public grant dependence creates cyclical vulnerability when state legislatures impose austerity measures on cultural appropriations.
- Specialized Labor Scarcity:Conservation scientists and exhibit designers command premium compensation, elevating fixed cost structures above inflation-indexed admission pricing.
- Climate Control Energy Intensity:Artifact preservation requires continuous HVAC operation, exposing institutions to utility rate volatility and carbon compliance costs.
Strategic Opportunities
- Underserved Secondary Cities:Mid-sized metropolitan areas in the United States lack encyclopedic institutions, creating white space for satellite campuses of established museum networks.
- Corporate Sponsorship Models:Naming rights and curated exhibition partnerships offer revenue diversification beyond municipal grants and individual philanthropy.
- Extended Reality Convergence:Augmented reality wayfinding and virtual artifact handling are converging with mobile device penetration to enable remote collection access.
Industry Challenges
- Digital Asset Preservation Expertise:Born-digital artworks and interactive installations require specialized conservators trained in software emulation and hardware archaeology.
- ADA Accessibility Retrofit Backlog:Historical structures face complex physical modifications to meet Department of Justice standards without compromising architectural integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Museums, Historical Sites, Zoos, and Parks Market |
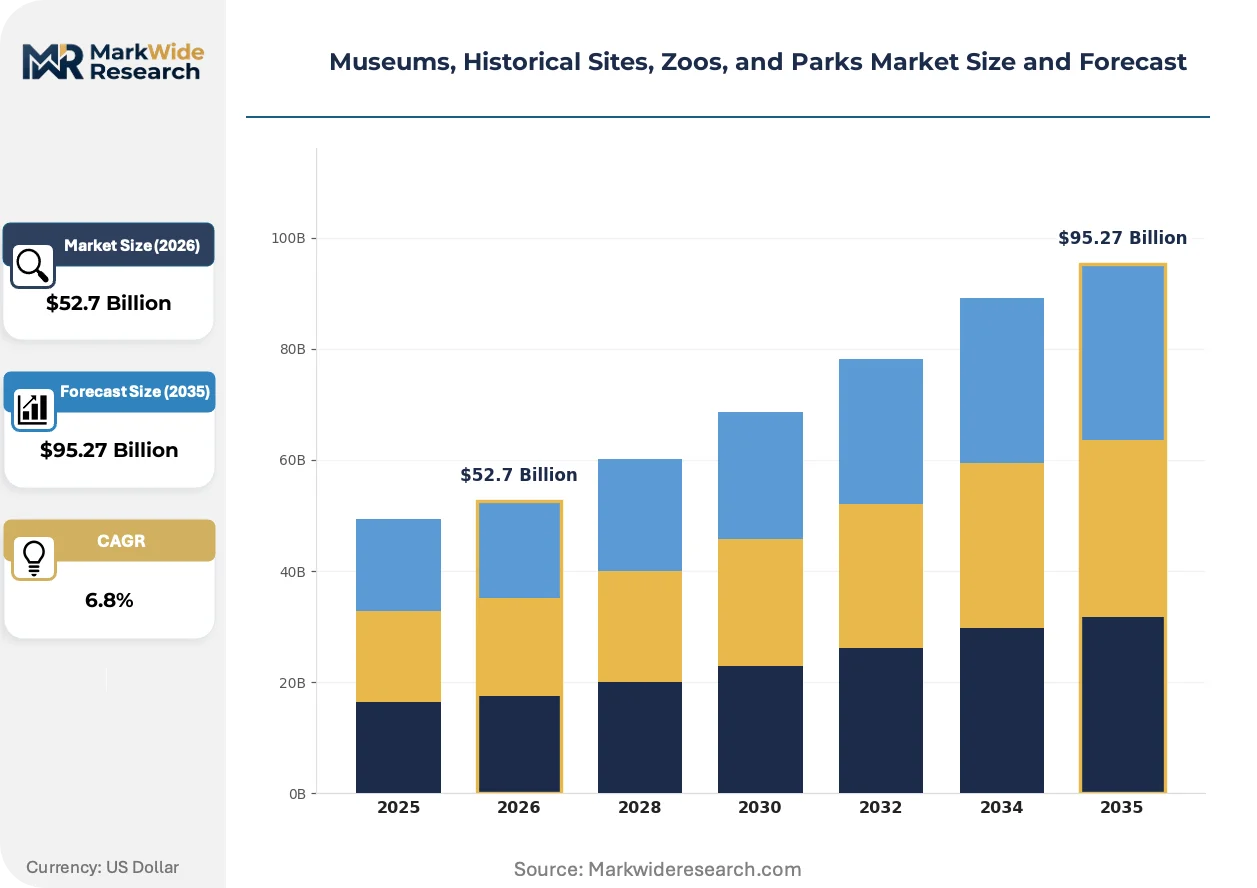
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Site Type: Museum, Aquarium, Botanical Garden, Nature Preserve Visitor Demographic: Families, Tourists, School Groups, Seniors Exhibition Format: Interactive, Static, Traveling, Seasonal Funding Source: Public Grants, Private Donations, Membership Fees, Admission Sales |
| Companies Covered | Smithsonian Institution, The Metropolitan Museum of Art, National Gallery of Art, The American Museum of Natural History, British Museum, Musée du Louvre, The State Hermitage Museum, National Museum of China, Zoological Garden of Berlin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Museums, Historical Sites, Zoos, and Parks Market Trends and Innovations
Institutional strategy is pivoting from static collection display toward programmable experiential environments that respond to visitor behavior data. This shift compresses exhibition design cycles and elevates technology integration budgets.
Spatial audio and haptic feedback systems are converging with gesture-based interfaces to create embodied learning environments. Aquariums and natural history museums deploy these installations for marine biology and paleontology education. The technology is converging with school district procurement criteria that prioritize STEM engagement metrics over traditional content delivery.
The National Park Service accessibility standards are mandating universal design compliance for all new construction and major renovation projects. Institutions must integrate tactile exhibits, audio description systems, and sensory-friendly programming. Historic sites with fragile fabric face particular constraint, as structural modifications require state heritage commission approval alongside federal compliance.
Membership models are displacing single-ticket purchases as the dominant revenue mechanism for recurring visitors. Institutions bundle exclusive access hours, curator talks, and digital content libraries to justify annual commitments. This shift is most visible in coastal metropolitan markets where competition for leisure spending intensifies across entertainment categories.
Museums, Historical Sites, Zoos, and Parks Market Segmentation
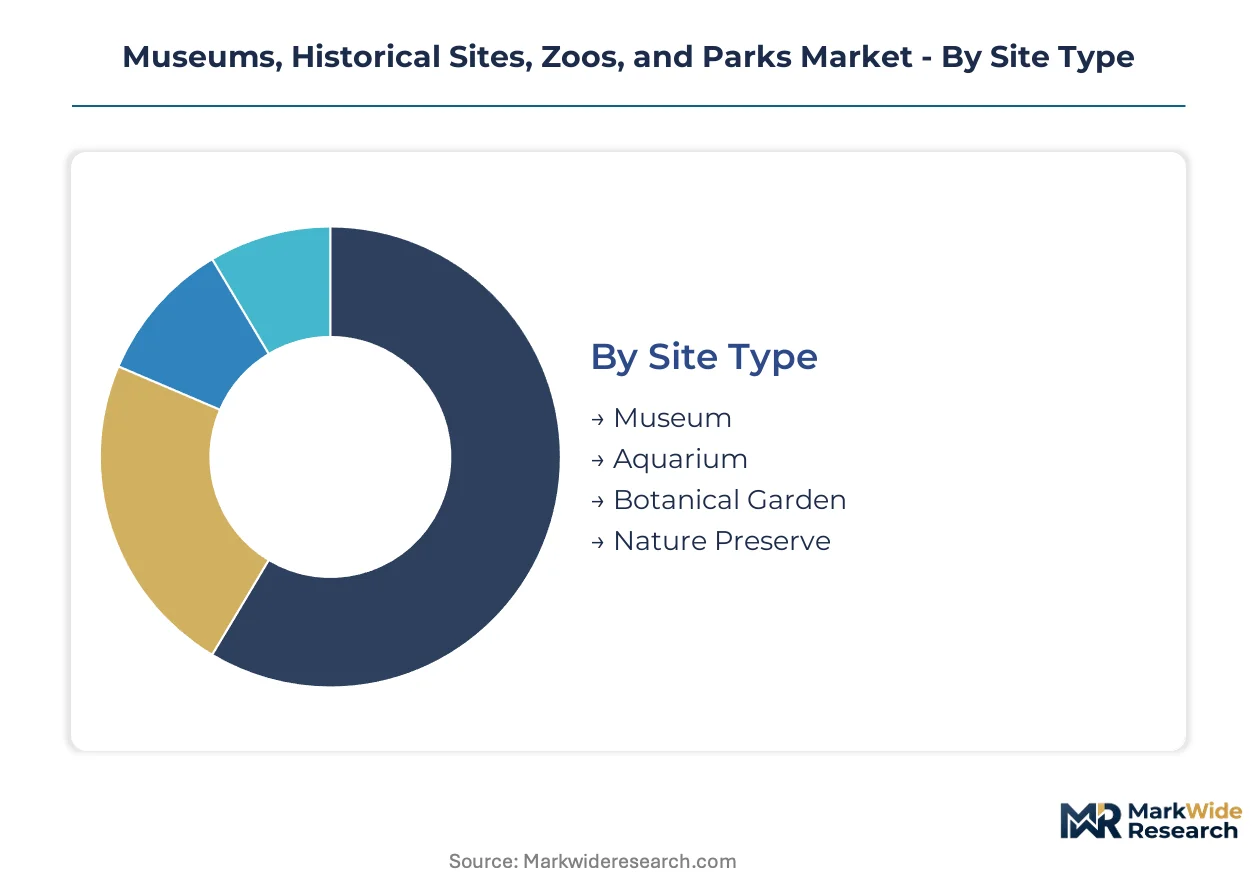
Segmentation in this market reveals how capital allocation, visitor behavior, and revenue mechanisms diverge across institutional types. Understanding these dimensions enables targeted infrastructure investment and programming decisions.
Site Type:
Replacement cycles for core infrastructure vary dramatically by site type, with living collection facilities requiring continuous system upgrades versus artifact institutions on longer preservation timelines.
- Museum:Climate-controlled galleries housing permanent and rotating collections demand precision HVAC and lighting systems. Federal digitization mandates are compressing exhibition budgets while expanding virtual infrastructure across encyclopedic institutions in the United States.
- Aquarium:Marine life support systems command the highest capital intensity per square foot, with continuous water quality monitoring and biological filtration replacement cycles. EPA chemical storage guidelines are forcing containment retrofits at coastal metropolitan facilities.
- Botanical Garden:Outdoor landscaped environments with specialized greenhouse infrastructure require seasonal irrigation and pest management system upgrades.
- Nature Preserve:Minimal built infrastructure concentrates spending on trail systems, wildlife monitoring technology, and habitat restoration equipment.
Museum sits at the top of the volume ranking, with Aquarium climbing the fastest.
Visitor Demographic:
Revenue stability correlates with demographic predictability, as recurring visitation patterns determine membership model viability and sponsorship pricing power.
- Families:Weekend and holiday visitation drives peak congestion and ancillary concession spending. Children's programming and interactive exhibits anchor repeat visits at zoos and natural history museums.
- Tourists:One-time visitors with high per-capita spending on guided tours and premium experiences. International tourism concentration in gateway cities like New York and Washington creates revenue volatility with exchange rate fluctuations.
- School Groups:Formalized curriculum partnerships with metropolitan districts generate recurring weekday blocks that stabilize off-peak revenue. STEM engagement metrics increasingly drive district procurement decisions for planetarium and aquarium field trips.
- Seniors:Weekday morning programming and lifetime membership products capture this segment's discretionary time and loyalty.
School Groups command the most predictable revenue trajectory, with Tourists showing the steepest recovery volatility.
Exhibition Format:
Technology refresh rates determine competitive positioning, as institutions race to deploy immersive systems before visitor expectations shift.
- Interactive:Gesture-based interfaces and haptic feedback systems require 3-5 year technology replacement cycles. Dwell time extensions drive ancillary spending per visitor at aquariums deploying spatial audio marine biology installations.
- Static:Traditional object display with minimal technology dependence offers lowest operating cost but declining engagement metrics among younger demographics.
- Traveling:Rotating loan exhibitions generate ticket premiums but impose complex insurance and climate-controlled transport logistics.
- Seasonal:Holiday light installations and summer outdoor programming capture temporary demand spikes with lower year-round fixed costs.
Interactive formats are gaining share fastest in capital allocation, while Static exhibitions retain volume dominance in existing square footage.
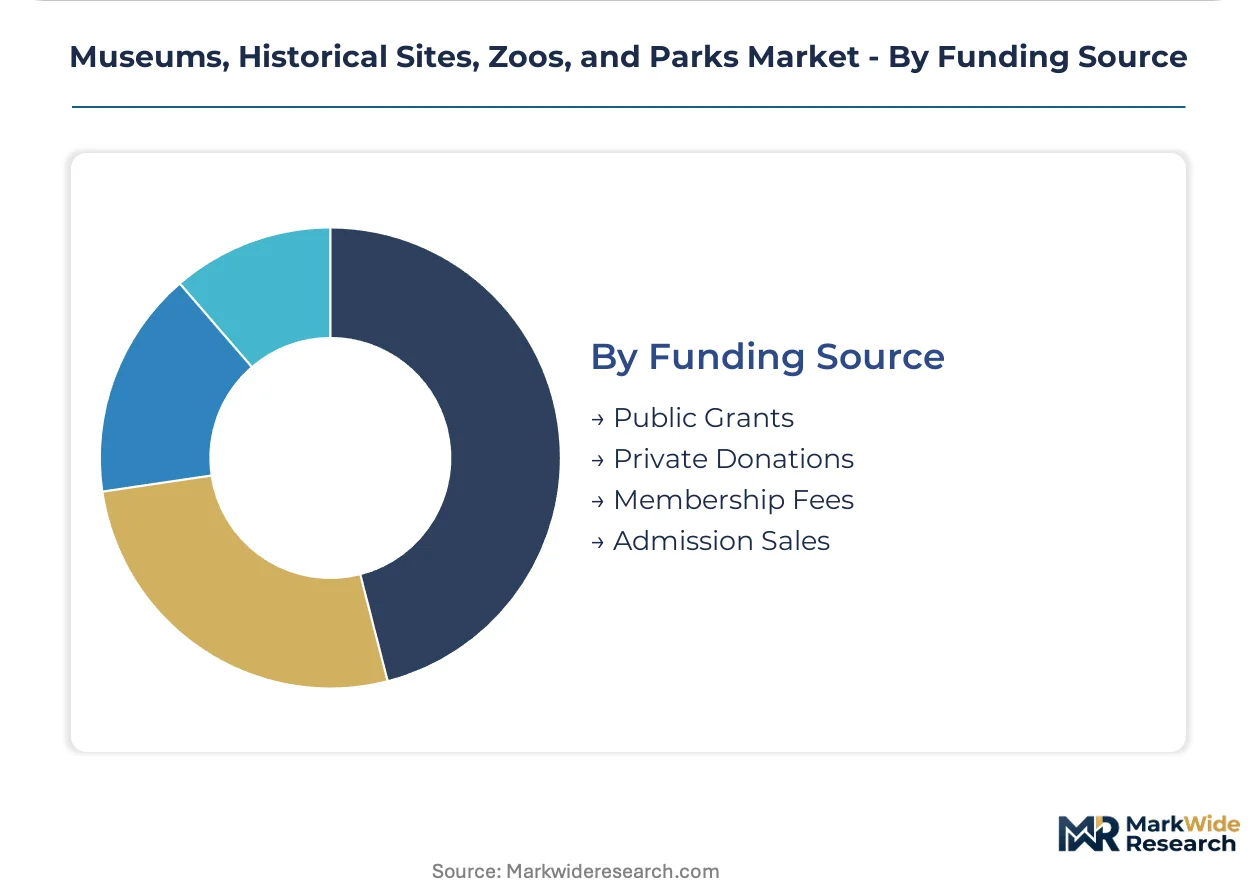
Funding Source:
Diversification breadth determines institutional resilience when any single revenue stream faces pressure.
- Public Grants:Federal and municipal appropriations sustain major networks like the Smithsonian but create cyclical vulnerability during state austerity measures.
- Private Donations:Individual philanthropy and foundation support concentrates at institutions with established development operations in wealthy metropolitan areas.
- Membership Fees:Annual commitments displace single-ticket purchases as the dominant revenue mechanism for recurring visitors, with bundled digital content libraries justifying premium pricing in coastal markets.
- Admission Sales:Walk-up ticketing remains critical for tourist-dependent institutions but faces pressure from dynamic pricing competition across entertainment categories.
Public Grants still anchor the largest revenue pool, with Membership Fees expanding most quickly as institutions pivot from transactional to relational visitor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conservation scientists and exhibit designers cluster disproportionately in metropolitan areas with established federal funding pipelines and heritage protection frameworks. These talent concentrations anchor institutional networks that shape regional market dynamics.
United States
Federal charter institutions like the Smithsonian leverage nineteen museums to sustain nationwide educational programming and digital preservation mandates. The National Park Service accessibility standards and EPA chemical storage guidelines constrain operational parameters while generating retrofit demand. Washington DC and New York City anchor the densest concentration of encyclopedic institutions with established curriculum partnerships.
United Kingdom
London's museum district concentrates heritage tourism and international loan exhibition logistics. The British Museum and National Gallery anchor visitor flows that drive membership model adoption. Historic preservation regulations from English Heritage and municipal planning authorities in Greater London shape expansion permits for institutions occupying Grade I listed structures.
France
Paris hosts the world's most visited museum, with the Louvre's conservation expertise and temporary exhibition program setting pricing benchmarks for traveling formats. The country's heritage protection framework mandates digital preservation for state-owned collections. Île-de-France institutions benefit from centralized cultural appropriations that insulate against municipal funding volatility.
Germany
Berlin's museum island and the Zoological Garden anchor institutional networks with deep research integration. German federalism distributes cultural funding across Länder, creating regional specialization in natural history and technical museums. The country's dual vocational training system supplies specialized exhibit fabricators and conservation technicians to institutions across Central Europe.
China
Beijing and Shanghai concentrate state-funded museum construction under national cultural infrastructure programs. The National Museum of China anchors patriotic education tourism with mandatory school group visitation quotas. Provincial cultural bureaus in the Yangtze and Pearl River Delta regions are expanding satellite institutions to capture domestic leisure travel growth.
Museums, Historical Sites, Zoos, and Parks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across institutional types, with federal charter networks and municipal systems occupying distinct competitive tiers. The market structure concentrates around encyclopedic institutions with established development operations and research integration capabilities. Three archetypes dominate: federally chartered networks with nationwide programming reach, metropolitan encyclopedic museums with conservation expertise premiums, and specialized living collection facilities with marine life support or planetarium technology leadership. Competitive moves center on satellite campus expansion into underserved secondary cities and corporate sponsorship models that diversify beyond grant dependence.
Among federally chartered networks in the United States, the Smithsonian Institution exemplifies the scale-driven archetype with its nineteen-museum constellation. The Metropolitan Museum of Art and the American Museum of Natural History occupy positions within the metropolitan encyclopedic tier, representing divergent strategies around conservation specialization versus research-anchored public programming. These three institutions collectively illustrate how federal funding access, curriculum partnership depth, and technology integration capabilities segment competitive positioning.
| Leading Market Players |
|---|
| Smithsonian Institution |
| The Metropolitan Museum of Art |
| National Gallery of Art |
| The American Museum of Natural History |
| British Museum |
| Musée du Louvre |
| The State Hermitage Museum |
| National Museum of China |
| Zoological Garden of Berlin |
| Others |
Pricing and Supply Chain Analysis
Steel price indices and specialty glass commodity benchmarks cascade through museum construction supply chains, compressing project budgets for new aquarium builds while elevating maintenance contract pricing for HVAC-dependent artifact institutions across the United States.
Pricing Analysis
Capacity additions in coastal metropolitan areas are reshaping price floors for immersive technology installations. Three-tier pricing structure across premium, standard, and economy levels segments visitor experiences, with planetarium dome upgrades and haptic marine biology systems commanding quality-grade premiums. Pricing pressure stems from school district procurement criteria prioritizing STEM engagement metrics over traditional content delivery. Tourist-dependent institutions in gateway cities show highest price sensitivity, while membership-model institutions demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for living collection institutions mandate multi-supplier qualification for marine life support systems and precision HVAC components. Supply concentrates in Germany, Japan, and the United States for specialized exhibit fabricators and conservation-grade climate control equipment. Raw material dependencies include low-iron glass, marine-grade stainless steel, and archival-quality lighting systems. Single-source vulnerability runs through proprietary dome projection technology vendors. Distribution runs through regional specialized contractors with heritage commission certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, with demand shifting decisively toward premium immersive specifications that extend visitor dwell time and ancillary spending.
For Market Incumbents: Acquire specialized digital preservation expertise to counter born-digital artwork conservation threats from software emulation gaps. Consolidate curriculum partnership depth with school districts to defend against municipal funding volatility. Backward integration into in-house planetarium technology development anchors pricing power. For New Entrants and Emerging Players: Gesture-based interface technology offers a technology-first wedge into underserved secondary cities lacking encyclopedic institutions. White space concentrates in mid-sized metropolitan areas without established museum networks. Satellite campus partnerships with federal charter institutions provide the most penetrable entry path. Go-to-market positioning centers on STEM engagement metrics alignment with district procurement criteria. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized living collection facilities with marine life support technology leadership. Long-term viability hinges on diversification beyond public grant dependence into corporate sponsorship and membership model economics. Acquisition targets should demonstrate established development operations in wealthy metropolitan areas. Watch federal digitization mandate acceleration as inflection indicator for digital preservation infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Preservation Infrastructure Investment | EPA chemical storage guidelines and federal mandates force capital reallocation toward compliance-grade systems. |
| Curriculum Partnership Formalization | School district STEM procurement criteria stabilize recurring weekday revenue blocks across metropolitan networks. |
| Immersive Technology Integration | Planetarium dome visualization and spatial audio systems extend dwell time and drive per-capita concession spending. |
| Membership Model Pivot | Annual commitments with bundled digital content displace single-ticket purchases in coastal competitive markets. |
| Satellite Campus Expansion | Secondary city white space creates geographic diversification for established encyclopedic institutions with development capacity. |
Research Methodology
Coverage spans the United States, United Kingdom, France, Germany, and China, with primary inputs from each market cluster. The analysis combines primary interviews with museum directors, conservation scientists, exhibit designers, school district curriculum coordinators, and heritage commission regulators with secondary validation. Secondary sources include National Park Service accessibility standards documentation, EPA regulatory filings, Smithsonian annual reports, and European heritage protection framework directives. Bottom-up institution-level data triangulates against top-down sectoral expenditure estimates.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include site type, visitor demographic, exhibition format, and funding source, with additional granularity on federal charter versus municipal system classification. CAGRs derive from trend extrapolation of historical visitation patterns, capital expenditure cycles, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate school district budget allocation data and federal cultural appropriations cycles.
The model holds under stable federal and municipal funding environments; deviation in state austerity measures or heritage protection framework revisions would shift the outlook materially. Deviation in immersive technology replacement cycle acceleration or living collection regulatory stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Italy Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Music Tourism Market
Destination Management and Attractions
Safari Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
SAVE Tourism Market