
 Culinary Tourism Market | 2026-2036
Culinary Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Culinary Tourism Market Analysis
The gap between hyper-curated gastronomic expeditions and mass-market food sightseeing is expanding across the culinary tourism landscape. Abercrombie & Kent USA, LLC leverages decades of destination expertise to anchor ultra-premium itineraries built around chef's table access and private vineyard estates. G Adventures competes on experiential density at accessible price points, while Devour Tours specializes in neighborhood-level food walks that emphasize hyperlocal storytelling over landmark aggregation.
Culinary tourism encompasses travel experiences where food and beverage consumption serves as the primary motivation, typically involving hands-on preparation, producer-site visits, or structured tasting protocols guided by regional experts. These experiences function as cultural immersion mechanisms, converting intangible heritage into bookable, repeatable commercial products with defined duration, group size, and sensory outcomes. Food tours and cooking classes together capture the dominant share of experiential type bookings, though wine tastings command higher per-participant margins due to cellar exclusivity and sommelier labor intensity. Luxury travel within the travel style dimension sustains outsized value contribution despite lower volume, as private transport and accommodation bundling multiplies transaction sizes.
EU Green Deal carbon disclosure rules and GDPR data handling requirements reshape how European operators collect dietary preferences and market origin stories across borders. The U.S. FDA's food safety modernization framework influences inbound culinary itinerary design, particularly for farm visits and artisan producer encounters. Stakeholders must monitor how sustainability certification schemes evolve from marketing differentiators into de facto market access requirements.
Market Dynamics
EU Green Deal carbon labeling mandates are restructuring how culinary tour operators source experiences, forcing disclosure of food-miles and producer emissions across multi-country itineraries.
Growth Catalysts
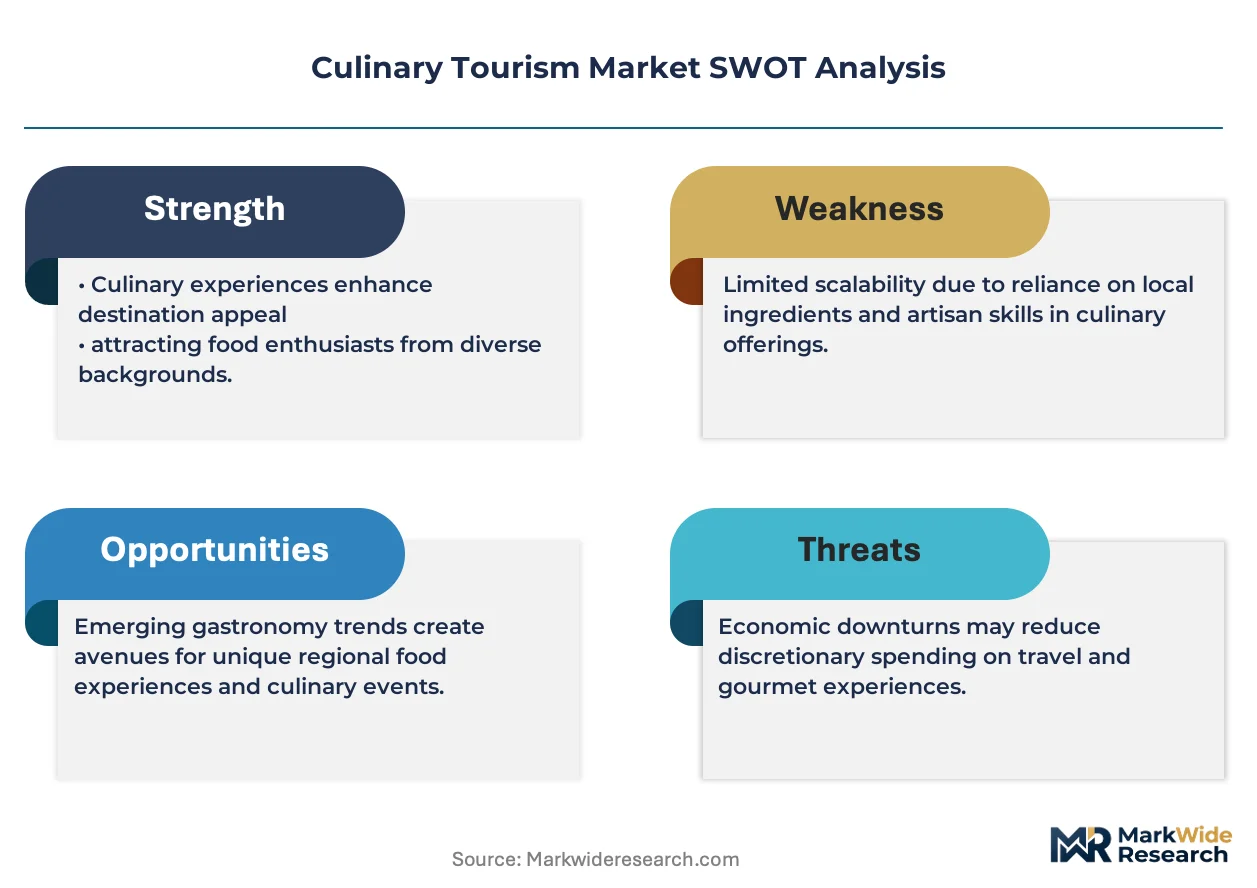
- GDPR-compliant preference engines:European operators now capture granular dietary data across borders, enabling hyper-personalized booking flows that convert at higher rates than generic packages.
- Italy's PDO clustering:Protected designation of origin density in Emilia-Romagna and Tuscany creates anchor destinations where certification scarcity commands sustained premium pricing.
- Millennial experiential booking platforms:Digital-native travelers now prioritize authenticity algorithms over packaged itineraries, pulling demand toward neighborhood-level food walks and producer-direct encounters.
Market Restraints
- Carbon disclosure compliance costs:Small operators face disproportionate burden from EU Green Deal documentation requirements, squeezing margins on sub-twelve-person tour formats.
- Sommelier labor scarcity:Wine tasting margins depend on certified cellar access and expert guidance, creating bottlenecked capacity in Burgundy and Napa Valley estates.
- Substitution by virtual cooking platforms:At-home chef streaming services capture price-sensitive experimenters who might otherwise book international culinary travel.
Strategic Opportunities
- Japan's inbound gastronomic corridor:METI's regional revitalization subsidies support sake brewery and kaiseki workshop development outside Tokyo-Osaka corridors.
- Farm-to-table IoT traceability:Convergence of blockchain provenance tracking and mobile AR storytelling enables operators to charge premium for verified supply chain transparency.
- Corporate retreat culinary modules:HR procurement teams now book cooking competitions and foraging challenges as team-building alternatives to traditional conference formats.
Industry Challenges
- Multi-jurisdiction food safety alignment:Operators must reconcile FDA farm visit protocols with EU hygiene standards and destination-country vendor certifications within single itineraries.
- Seasonal ingredient forecasting:Climate volatility disrupts harvest calendars for truffle hunting and olive pressing experiences, forcing last-minute itinerary restructuring.
- Legacy reservation system integration:Established operators struggle to connect proprietary booking engines with third-party experiential marketplaces without data fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culinary Tourism Market |
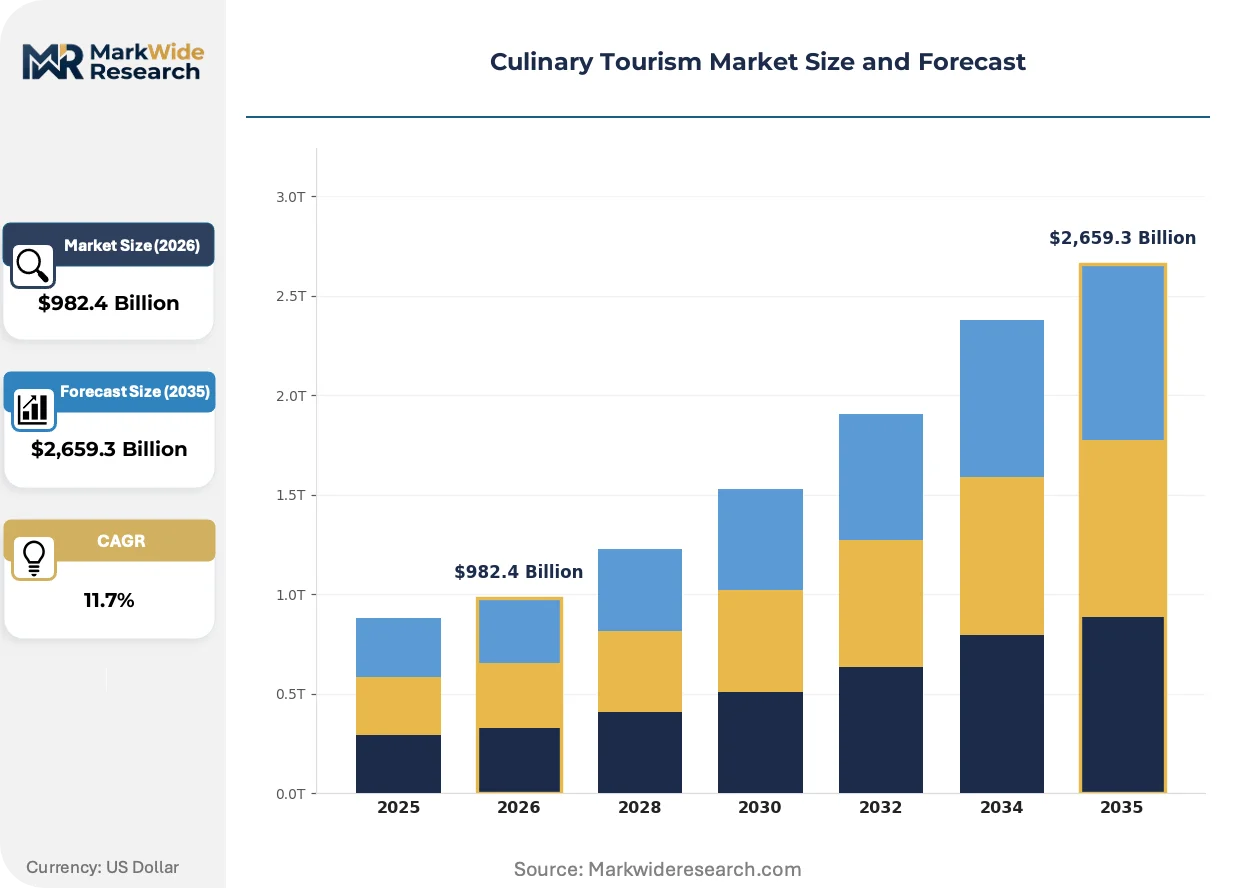
| Market Size in 2026 | $982.4 Billion |
| Market Size in 2035 | $2,659.3 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Experiential Type: Cooking Classes, Food Tours, Wine Tastings, Culinary Festivals Travel Style: Luxury Travel, Budget Travel, Group Tours, Solo Travel Food Type: Local Cuisine, Street Food, Fine Dining, Organic Food Consumer Preference: Vegetarian Options, Vegan Options, Seafood Lovers, Meat Enthusiasts |
| Companies Covered | Epicurean Ways, Gourmet On Tour, Abercrombie & Kent USA, LLC, Classic Journeys, LLC, G Adventures, Devour Tours, The International Kitchen, Food N’ Wine Vacations, Butterfield & Robinson Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culinary Tourism Market Emerging Trajectories
Digital authentication tools and regenerative sourcing protocols are displacing traditional marketing claims with verifiable experience credentials that travelers can inspect before booking.
Blockchain-enabled provenance tracking is integrating with mobile booking platforms to display real-time supply chain verification for each stop on multi-day gastronomic itineraries. Premium travelers now expect clickable farm profiles and harvest date transparency before confirming reservations. This capability is compressing the due diligence phase from weeks to hours while raising baseline expectations for operator disclosure.
EU Green Deal carbon labeling requirements are mandating gram-per-serving emissions disclosure for all food service providers hosting international tour groups. Italian operators in Emilia-Romagna have responded fastest, restructuring supplier contracts around short-haul ingredient procurement. The regulation most acutely affects wine estate experiences, where cellar refrigeration and bottle transport dominate carbon footprints.
Booking behavior among corporate retreat planners now favors unbundled culinary modules over packaged destination programs. Procurement teams assemble custom itineraries from discrete cooking class, foraging expedition, and producer visit components rather than accepting pre-structured tours. This pattern is most visible in North American technology sector travel budgets, where flexibility and cancellation terms outweigh bundled convenience.
Culinary Tourism Market Segmentation
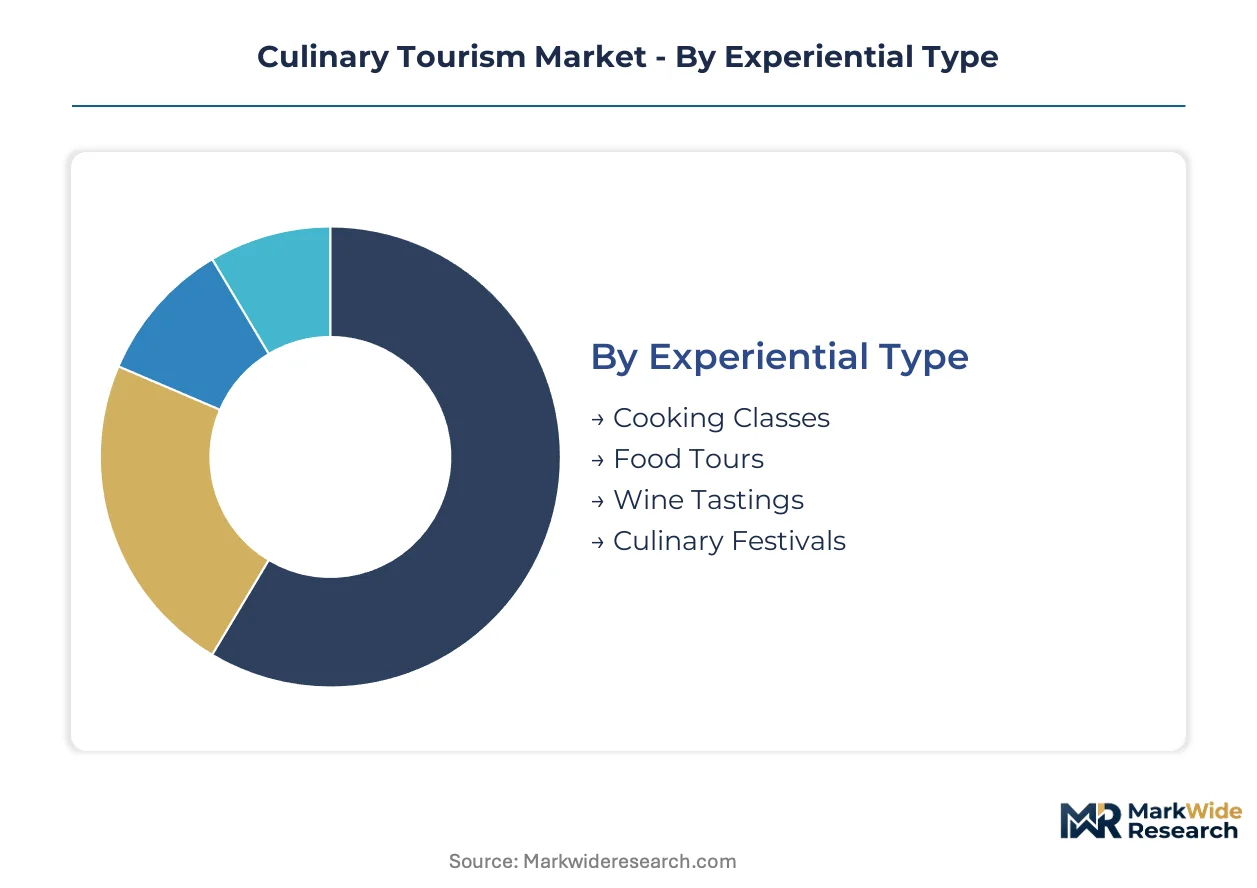
Culinary tourism operators architect revenue models around four distinct segmentation axes. Each dimension carries different margin profiles and capital requirements, forcing portfolio decisions about where to concentrate guide talent and supplier relationships.
Experiential Type:
Cooking classes demand the highest upfront capital, requiring licensed kitchen facilities, ingredient cold chains, and liability coverage for participant food handling.
- Cooking Classes:Hands-on instruction in professional or home kitchen environments where travelers prepare regional dishes under chef supervision. Demand clusters in Tuscany and Emilia-Romagna, where PDO ingredient scarcity justifies premium pricing for access to certified Parmigiano-Reggiano aging houses and traditional balsamic vinegar lofts.
- Food Tours:Guided walking or vehicle-based itineraries connecting multiple tasting stops with narrative continuity. Neighborhood-level storytelling in Barcelona's La Boqueria and Mexico City's Mercado de San Juan now outperforms landmark-aggregation formats as millennials prioritize authenticity algorithms over packaged convenience.
- Wine Tastings:Structured cellar and vineyard encounters with sommelier-led protocol. Certified cellar access in Burgundy and Napa Valley creates capacity bottlenecks that constrain margin expansion despite high per-participant yields.
- Culinary Festivals:Time-bound events aggregating producers, chefs, and tasting installations. Seasonal concentration forces operators to build annual revenue around narrow harvest windows.
Most installed capacity flows through Food Tours. Expansion is steepest in Cooking Classes.
Travel Style:
Volume distribution skews toward accessible formats, yet value capture concentrates where private transport and accommodation bundling multiplies transaction sizes.
- Luxury Travel:Private chef's table access, estate accommodation, and dedicated transport. Abercrombie & Kent anchors this tier with decades of destination expertise and vineyard estate relationships that independent operators cannot replicate.
- Budget Travel:Self-directed or small-group formats minimizing bundled services. Street food circuits in Bangkok and Hanoi dominate this tier, where low overhead permits sub-fifty-dollar daily experiential density.
- Group Tours:Scheduled departures with fixed itineraries and shared guide costs. Twelve-to-twenty-person formats optimize guide labor utilization but sacrifice personalization depth.
- Solo Travel:Unaccompanied bookings requiring enhanced safety protocols and single-supplement pricing structures. Female solo travelers in Japan's kaiseki corridor drive specialized product development.
Luxury Travel generates disproportionate value contribution. Budget Travel captures the widest participant base.
Food Type:
Certification requirements and supply chain verification costs vary dramatically across this axis, reshaping operator procurement strategies.
- Local Cuisine:Traditional preparations using region-specific ingredients and techniques. EU Green Deal carbon labeling mandates now force disclosure of food-miles for every component, advantaging short-haul procurement in Emilia-Romagna.
- Street Food:Informal vendor encounters with minimal facility overhead. Regulatory fragmentation between FDA protocols for inbound US travelers and destination-country hygiene standards creates compliance complexity for multi-country itineraries.
- Fine Dining:Michelin-tier restaurant reservations with chef interaction. Scarcity of tables at three-star establishments in San Sebastian and Lyon limits scalable product development.
- Organic Food:Certified production with blockchain-verified provenance. Farm-to-table IoT traceability enables premium pricing for supply chain transparency that travelers can inspect pre-booking.
Local Cuisine anchors destination marketing. Organic Food is climbing the fastest as sustainability certification evolves from marketing differentiator into market access requirement.
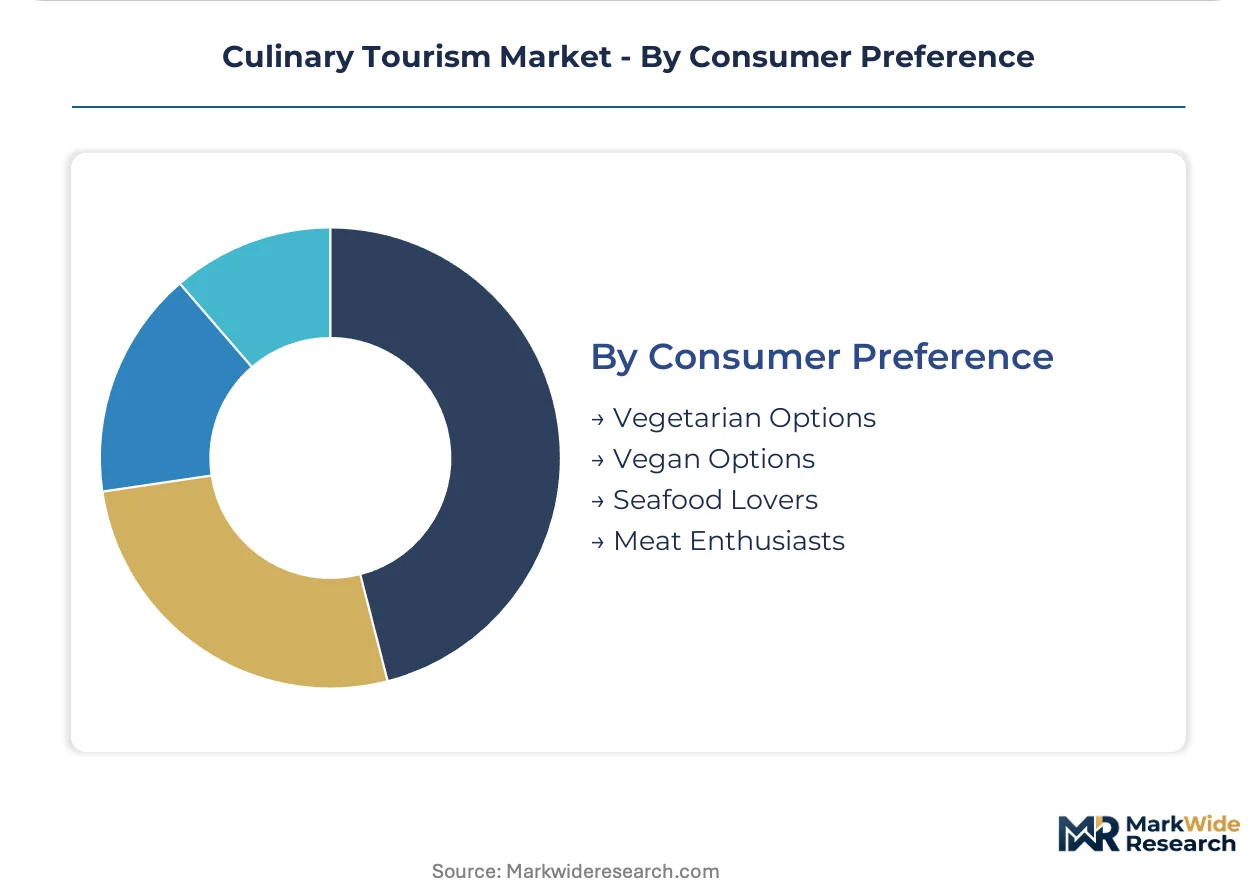
Consumer Preference:
Dietary accommodation infrastructure determines addressable market breadth, with GDPR-compliant preference engines now enabling granular personalization.
- Vegetarian Options:Plant-forward menus excluding meat but permitting dairy and eggs. India's Rajasthan and Gujarat regions offer mature infrastructure, while Mediterranean operators retrofit traditional meat-centric itineraries.
- Vegan Options:Exclusion of all animal products including honey and dairy derivatives. Japanese temple cuisine (shojin ryori) in Kyoto provides authentic experiential depth unavailable in adapted Western formats.
- Seafood Lovers:Raw and prepared fish encounters from dock to table. Tsukiji Outer Market in Tokyo and Galicia's Rías Baixas concentrate demand for certified sustainable sourcing.
- Meat Enthusiasts:Butchery demonstrations, aging facility tours, and nose-to-tail preparation. Argentina's asado traditions and Texas barbecue circuits sustain dedicated product lines.
Vegetarian Options flow through the broadest operator networks. Vegan Options are gaining share fastest as plant-based dietary patterns expand among millennial and Gen Z travelers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified sommeliers and master chefs concentrate in specific corridors, anchoring destination appeal and pricing power for premium culinary experiences.
Italy
PDO clustering in Emilia-Romagna and Tuscany sustains premium pricing for Parmigiano-Reggiano aging house access and traditional balsamic vinegar loft tours. EU Green Deal carbon labeling mandates force gram-per-serving emissions disclosure for food service providers hosting international groups. Florence and Bologna anchor the densest concentration of certified cooking class facilities in Europe.
France
Sommelier labor scarcity in Burgundy and Champagne creates capacity bottlenecks that constrain scalable wine tasting product development. EMA-aligned food safety protocols intersect with destination-country hygiene standards for multi-country itineraries. Lyon and Bordeaux concentrate three-star Michelin table access that limits bookable inventory for luxury tour operators.
Japan
METI regional revitalization subsidies support sake brewery and kaiseki workshop development outside Tokyo-Osaka corridors. PMDA food safety frameworks govern farm visit protocols for inbound culinary travelers. Kyoto's temple cuisine (shojin ryori) infrastructure provides authentic experiential depth unavailable in adapted Western formats.
United States
FDA food safety modernization frameworks influence farm visit and artisan producer encounter design for inbound itineraries. Napa Valley certified cellar access creates capacity constraints similar to Burgundy, with sommelier labor intensity driving per-participant margins. California's Central Valley and Oregon's Willamette Valley anchor domestic wine tourism density.
Spain
Barcelona's La Boqueria and San Sebastian's pintxos corridor anchor neighborhood-level food walk demand from millennial travelers prioritizing authenticity algorithms. EFSA-aligned carbon disclosure requirements reshape supplier contracting for multi-country European itineraries. Basque Country and Catalonia concentrate the highest density of Michelin-tier restaurant access outside France.
Culinary Tourism Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the culinary tourism landscape. Estate-owning operators with dedicated vineyard relationships and private chef's table infrastructure face pressure from platform-based aggregators minimizing fixed assets. Three strategic archetypes dominate: ultra-premium destination specialists, experiential-density budget operators, and hyperlocal neighborhood storytellers. Competitive moves concentrate on strategic partnerships with certified producers and geographic expansion into subsidized regional corridors.
Within the ultra-premium tier, Abercrombie & Kent USA, LLC and Butterfield & Robinson Inc. occupy positions anchored by decades of destination expertise and private estate relationships. G Adventures exemplifies the experiential-density archetype at accessible price points, while Devour Tours represents the hyperlocal neighborhood storytelling model emphasizing authenticity over landmark aggregation. These three companies illustrate how operator archetypes map to distinct margin profiles and capital requirements across the market.
| Leading Market Players |
|---|
| Epicurean Ways |
| Gourmet On Tour |
| Abercrombie & Kent USA, LLC |
| Classic Journeys, LLC |
| G Adventures |
| Devour Tours |
| The International Kitchen |
| Food N' Wine Vacations |
| Butterfield & Robinson Inc. |
| Others |
Supply Flow & Price Mechanics
Luxury-to-budget tier divergence in culinary tourism manifests through bundled private transport and estate accommodation multiplying transaction sizes at the top, while stripped-down neighborhood food walks compete on experiential density at thin margins below. EU Green Deal carbon labeling mandates force gram-per-serving emissions disclosure that reshapes supplier contracting across both tiers, with short-haul procurement in Emilia-Romagna commanding premium positioning against long-haul dependent operators.
Pricing Analysis
Bundled versus unbundled service splits dominate culinary tourism pricing, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and sommelier labor intensity. Wine tastings in Burgundy and Napa Valley extract highest yields through certified cellar exclusivity, while street food circuits in Bangkok and Hanoi compete on sub-fifty-dollar daily experiential density. Cost compression in small-group formats intensifies because EU Green Deal documentation burdens squeeze margins on sub-twelve-person tours. Corporate retreat planners show least price sensitivity, prioritizing flexibility and cancellation terms over bundled convenience.
Supply Chain Analysis
Certification and qualification gating through protected designation of origin density in Italy, sommelier certification scarcity in France, and METI-subsidized regional revitalization in Japan concentrates premium supplier relationships in these three corridors. Culinary tourism supply chains draw from PDO-certified aging houses, certified organic farms with blockchain verification, and master chef kitchen facilities. Single-source vulnerability runs through Burgundy and Napa Valley cellar access, where certified sommelier labor creates capacity bottlenecks. Distribution runs through platform-based experiential marketplaces and direct operator booking engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Culinary tourism functions as a regulatory compounder where EU Green Deal carbon disclosure mandates are accelerating market access requirements faster than operator adaptation capacity, forcing consolidation around compliant infrastructure investments.
For Market Incumbents: Deepen vertical integration into certified PDO supplier networks and proprietary estate relationships to defend margin position against platform-based aggregators minimizing fixed assets. Lock in exclusive chef's table access and private vineyard contracts before regional revitalization subsidies in Japan and Italy attract new capacity. Carbon disclosure compliance infrastructure represents the priority defensive lever. For New Entrants and Emerging Players: Blockchain-enabled provenance tracking technology offers a technology-first wedge into corporate retreat procurement, where unbundled culinary modules are displacing packaged destination programs. Target North American technology sector travel budgets with IoT traceability and mobile AR storytelling capabilities. White-space opportunity concentrates in METI-subsidized sake brewery corridors outside Tokyo-Osaka and kaiseki workshop development in secondary Japanese cities. For Investors and Strategic Acquirers: Asymmetric upside sits with hyperlocal neighborhood storytelling operators possessing GDPR-compliant preference engines and authentic producer-direct relationships that platform aggregators cannot replicate. Five-to-ten year viability favors asset-light designers over estate-heavy producers facing stranded capacity risk from climate volatility disrupting harvest calendars. Watch for EU Green Deal sustainability certification evolution from marketing differentiator into de facto market access requirement as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Enables real-time supply chain verification that compresses corporate due diligence from weeks to hours. |
| GDPR-Compliant Preference Engine Deployment | Captures granular dietary data across borders, converting at higher rates than generic booking flows. |
| PDO Supplier Network Exclusivity | Locks in Parmigiano-Reggiano aging house and traditional balsamic vinegar loft access against competitor replication. |
| Farm-to-Table IoT Traceability Buildout | Supports premium pricing for verified organic supply chain transparency inspectable pre-booking. |
| Corporate Retreat Module Unbundling | Captures HR procurement shift toward flexible cooking competitions and foraging challenges. |
Methodological Framework
Coverage spans Italy, France, Japan, the United States, and Spain, with primary inputs from each combining executive interviews with culinary tour operators, certified sommeliers, and destination management company procurement leads with secondary validation. Bottom-up and top-down triangulation incorporates EU Green Deal regulatory filings, FDA food safety modernization frameworks, METI regional revitalization subsidy disclosures, and proprietary booking platform transaction data.
Granularity-level modeling disaggregates experiential type, travel style, food type, and consumer preference dimensions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro tourism flows and regulatory compliance cost trajectories. Forecast inputs incorporate PDO certification expansion timelines, sommelier labor supply elasticity, and corporate retreat procurement pattern shifts.
The model holds under stable EU Green Deal implementation trajectories and continued METI subsidy programs; deviation in carbon labeling enforcement intensity or regional revitalization funding suspension would shift supplier contracting economics. A model refresh is warranted upon material change in sustainability certification scheme evolution from marketing differentiator into market access requirement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Agro-Rural Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Safari Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Global Religious Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Literary Tourism Market