
 USA Casino Tourism Market | 2026-2036
USA Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
USA Casino Tourism Market Analytics
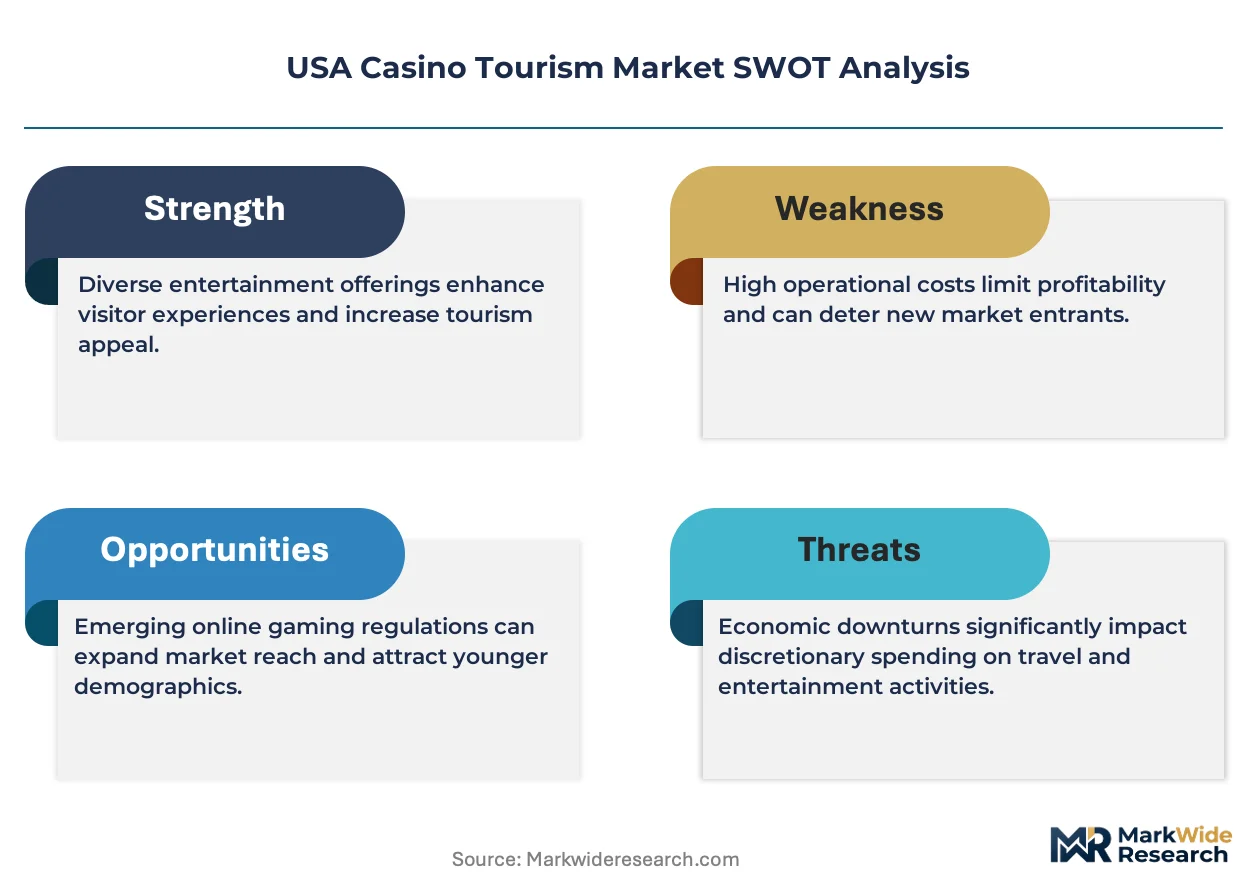
Asset-light management contracts and REIT spinoffs is narrowing the capital barrier for new entrants in casino tourism. MGM Resorts leverages its regional portfolio diversification to sustain cash flow stability beyond Las Vegas. Caesars Entertainment anchors its position through loyalty program density and omnichannel integration. Wynn Resorts differentiates via ultra-premium hospitality design and international VIP feeder networks.
USA casino tourism encompasses destination travel centered on legalized gambling venues, typically combining table games, electronic gaming devices, lodging, and ancillary entertainment across properties exceeding 50,000 square feet of gaming space. The segment serves both leisure consumers and corporate event planners seeking bundled hospitality experiences. Tribal casinos dominate geographic reach through sovereign immunity advantages and compact-negotiated exclusivity zones. Luxury resorts capture disproportionate margin pools through high-yield VIP gambling and integrated non-gaming amenities. Gaming tournaments within entertainment offerings represent the fastest-growing engagement format, attracting younger demographics and extending property dwell time.
The National Indian Gaming Commission oversees tribal casino operations, while state gaming commissions including the Nevada Gaming Control Board and New Jersey Division of Gaming Enforcement set operational standards for commercial properties. Federal tribal compacts and state constitutional amendments collectively determine where casino tourism can legally expand. Stakeholders must monitor pending interstate compact renegotiations and emerging state legislative sessions for expansion signals.
Market Dynamics
State-level sports betting legalization is fragmenting competitive access across the United States, forcing operators to pursue jurisdiction-by-jurisdiction licensing rather than national market entry. This regulatory patchwork is concentrating capital deployment in states with favorable tax structures and compact-negotiated exclusivity zones.
Growth Catalysts
- Mobile wagering frameworks:State constitutional amendments enabling smartphone-based sports betting are expanding addressable player bases beyond physical property footprints. New Jersey Division of Gaming Enforcement standards serve as a template for emerging jurisdictions.
- Tribal compact renegotiations:Sovereign immunity advantages allow tribal operators to deploy gaming devices in exclusivity zones where commercial casinos face statutory prohibitions. Oklahoma and Florida compacts are expanding Class III gaming authorization.
- Integrated resort development:Mixed-use entertainment complexes combining convention centers, retail, and non-gaming hospitality are extending average visitor dwell time and per-trip spend.
Market Restraints
- Input cost volatility:Construction labor shortages and steel pricing fluctuations are inflating development timelines for greenfield casino properties in regional markets.
- Regulatory friction:The Nevada Gaming Control Board's stringent suitability investigations for key employees create multi-month delays in executive staffing and property openings.
- Substitution threat:Social casino gaming applications and sweepstakes-based platforms are capturing younger demographic engagement without requiring physical travel.
Strategic Opportunities
- Underpenetrated state markets:Texas and Georgia remain without commercial casino frameworks, creating first-mover advantages for tribal or legislative advocates who secure compact or amendment passage.
- Technology convergence:Cashless wagering systems integrating biometric authentication with player tracking databases are enabling real-time loyalty personalization and responsible gaming intervention.
- Distribution innovation:Airport slot lounges and interstate highway travel centers are creating micro-casino touchpoints that capture transient traffic without full resort investment.
Industry Challenges
- Skill gap in compliance analytics:The intersection of anti-money laundering protocols and cryptocurrency transaction monitoring requires specialized talent scarce in traditional gaming operations.
- Capex intensity of legacy modernization:Slot floor replacement cycles and property refurbishment demands are competing with new market entry capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Casino Tourism Market |
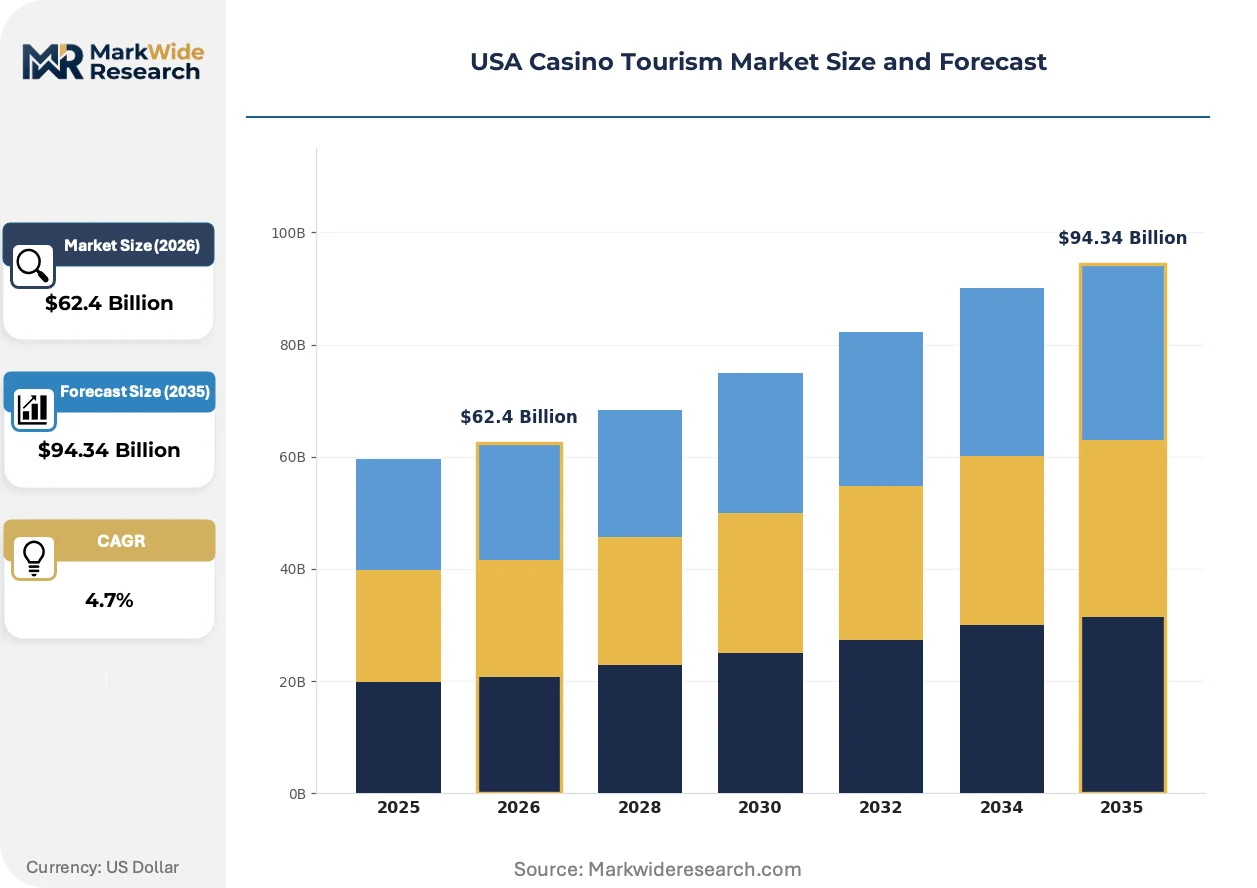
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $94.34 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Domestic Tourists, International Tourists, Gaming Enthusiasts, VIP Gamblers Casino Type: Luxury Resorts, Riverboat Casinos, Tribal Casinos, Standalone Casinos Entertainment Offering: Live Shows, Nightclubs, Dining Experiences, Gaming Tournaments Visit Purpose: Leisure, Business Meetings, Special Events, Group Travel |
| Companies Covered | Wynn Resorts, Bally’s Corporation, MGM Resorts, Resorts World Las Vegas, Fontainebleau Las Vegas, Caesars Entertainment, Penn Entertainment, WinStar World Casino and Resort, Las Vegas Sands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Casino Tourism Market Evolving Landscape
Digitization of the player experience is compressing the boundary between physical casino floors and remote engagement platforms. Operators are deploying technology stacks that unify loyalty recognition across on-property and digital touchpoints.
Server-based gaming systems are migrating from proprietary hardware architectures to cloud-native infrastructure. Regional casino operators in Oklahoma and Florida are adopting these platforms to reduce floor reconfiguration downtime from days to hours. This migration from fixed-asset gaming machines to software-defined slot content is enabling dynamic game libraries that respond to player preference data in near-real time.
The National Indian Gaming Commission has issued updated technical standards for Class II electronic gaming systems that mandate enhanced audit trail capabilities. Tribal operators must now deploy systems capable of real-time transaction logging to sovereign regulatory databases. Properties in compact-negotiated exclusivity zones are prioritizing compliance infrastructure investments to maintain operational authorization.
Younger demographic segments are demonstrating preference for skill-influenced gaming formats over pure chance-based slot mechanics. Esports tournament integration and gamified loyalty progression systems are displacing traditional comp point accumulation in properties targeting millennials and Generation Z. Atlantic City operators have been most aggressive in deploying these experiential amenities to differentiate against Las Vegas benchmark properties.
USA Casino Tourism Market Segmentation
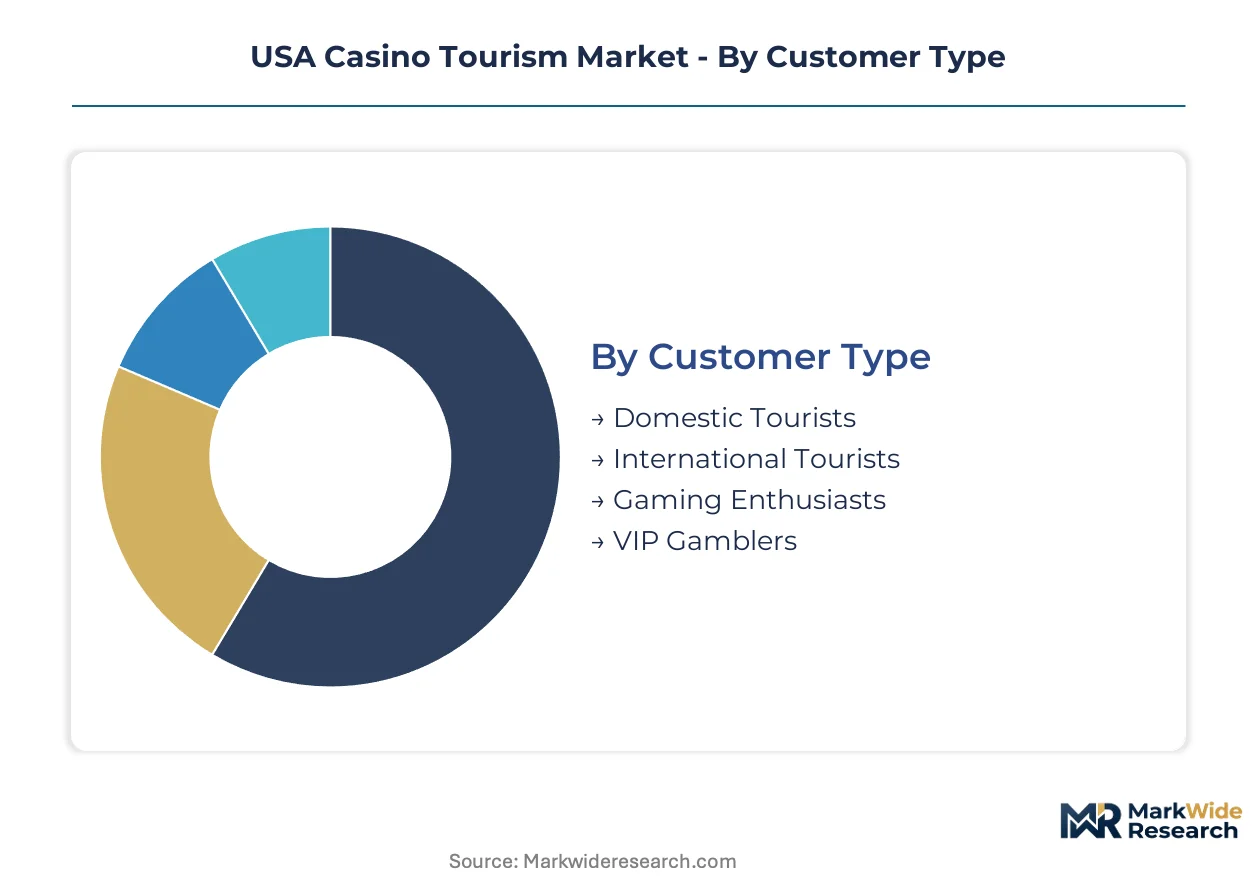
Segmentation in USA casino tourism reveals how distinct traveler profiles and property formats command different pricing power and operational complexity. Operators calibrate loyalty programs and amenity bundles based on these divisions to maximize per-visitor yield across Nevada, Atlantic City, and emerging regional markets.
Customer Type:
Mature domestic segments anchor revenue stability while emerging international and VIP channels reshape margin structures.
- Domestic Tourists:Drive-in and fly-in visitors from neighboring states seeking weekend entertainment packages. Concentrated in Nevada and Atlantic City corridors where regional airline connectivity and interstate highway access reduce friction.
- International Tourists:Cross-border arrivals from Canada, Mexico, and Asia-Pacific feeder markets. Demand clusters at Las Vegas Strip properties with multilingual staff and currency exchange infrastructure; visa processing delays constrain recovery velocity.
- Gaming Enthusiasts:Repeat visitors prioritizing table game variety and tournament schedules over non-gaming amenities. Oklahoma tribal casinos capture this segment through compact-negotiated exclusivity and high-slot-density floors.
- VIP Gamblers:Ultra-high-net-worth individuals requiring private gaming salons and dedicated hosts. Wynn Resorts and MGM Resorts deploy international sales offices in Macau and Singapore to sustain this pipeline; credit issuance and collection capabilities differentiate operators.
Domestic Tourists handle the majority of throughput; Gaming Enthusiasts is the fastest mover on share.
Casino Type:
Cost tier differentiation separates capital-intensive integrated resorts from leaner operational models.
- Luxury Resorts:Mixed-use developments exceeding $1 billion in replacement value combining gaming floors with convention centers, retail, and fine dining. MGM Grand and Bellagio in Las Vegas set the benchmark; Florida's Seminole Hard Rock Hollywood replicates this template in a compact-negotiated exclusivity zone.
- Tribal Casinos:Sovereign immunity operations governed by state-tribal compacts with Class II and Class III gaming authorization. Geographic reach dominates through exclusivity zones in Oklahoma, California, and Florida where commercial casinos face statutory prohibitions.
- Riverboat Casinos:Dockside or cruising vessels operating under historical licensing frameworks in Mississippi and Missouri. Limited by physical constraints on gaming square footage and amenity expansion; aging hull maintenance escalates operating costs.
- Standalone Casinos:Gaming-focused properties without integrated hotel or entertainment components. Atlantic City boardwalk venues and regional slot parlors in Pennsylvania compete on convenience and parking accessibility rather than destination dwell time.
Luxury Resorts command the premium pricing tier; Tribal Casinos is expanding most quickly through compact renegotiations.
Entertainment Offering:
Application-based segmentation tracks how non-gaming amenities extend property utilization rates.
- Live Shows:Residency productions and touring acts in purpose-built theaters. Caesars Entertainment's Colosseum and MGM's Park Theater in Las Vegas anchor this segment; talent guarantees and production insurance inflate fixed costs.
- Gaming Tournaments:Poker championships and slot competitions with structured prize pools. Younger demographic engagement climbs fastest here; World Series of Poker and regional tribal events in Oklahoma extend dwell time without incremental capital deployment.
- Nightclubs:Electronic dance music venues and bottle-service lounges targeting 21-34 age cohorts. Hakkasan and Omnia in Las Vegas generate disproportionate beverage revenue per square foot; noise abatement regulations constrain suburban expansion.
- Dining Experiences:Celebrity chef restaurants and buffet operations spanning price points. Food and beverage margins subsidize promotional gaming offers; Atlantic City operators leverage boardwalk location for seafood differentiation.
Live Shows retains the highest per-visitor attach rate; Gaming Tournaments is gaining share fastest among under-40 segments.
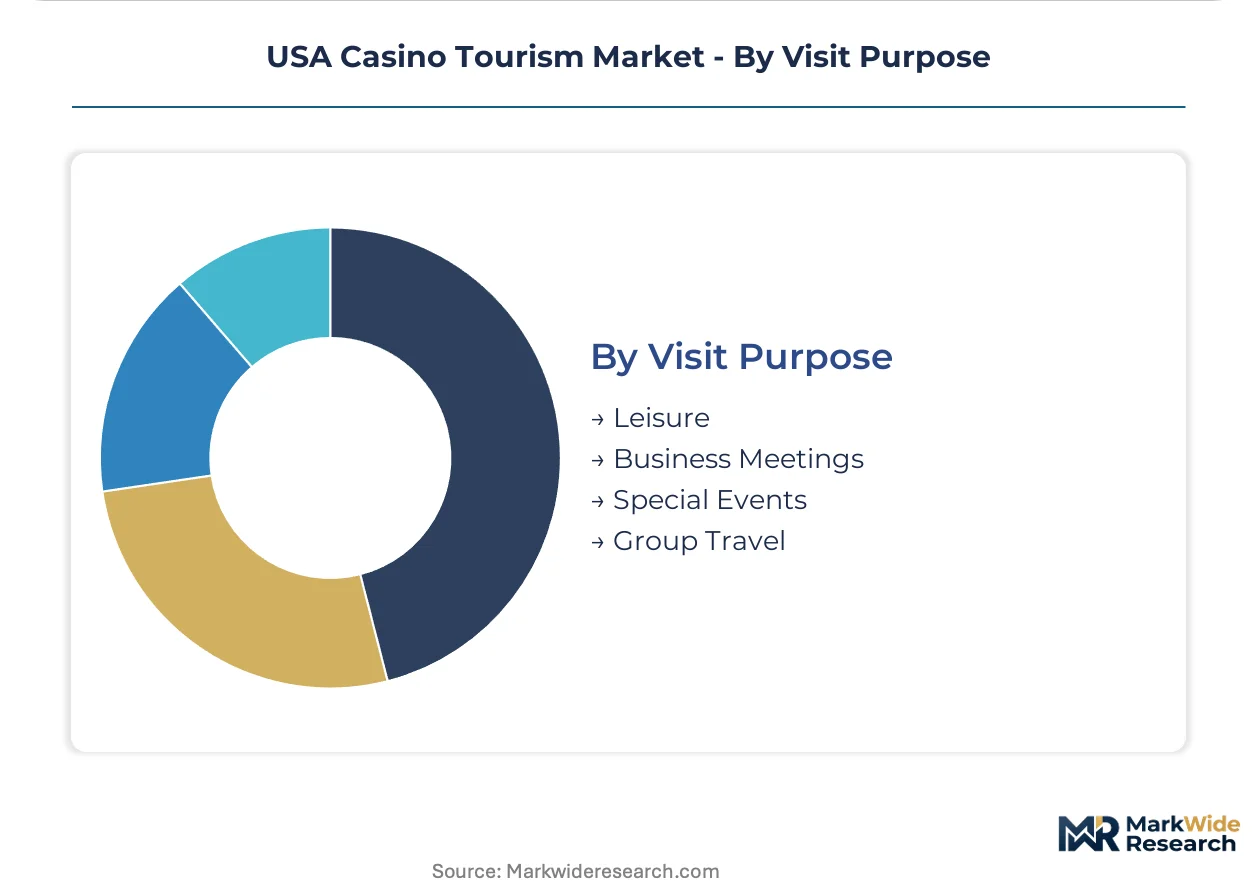
Visit Purpose:
Customer type and margin profile diverge sharply between leisure discretionary and contracted corporate segments.
- Leisure:Discretionary travel with flexible booking windows and price sensitivity. Concentrated in Nevada weekend corridors; substitution threat from social casino applications pressures this base.
- Business Meetings:Corporate events and incentive travel with contracted room blocks. MGM Resorts and Caesars Entertainment compete on convention center square footage; hybrid meeting technology reduces peak-night compression.
- Special Events:Weddings, concerts, and sporting event packages with premium pricing tolerance. Super Bowl and Formula 1 weekends in Las Vegas demonstrate revenue maximization through dynamic yield management.
- Group Travel:Bus tours and senior excursion packages with high volume, low per-capita spend. Regional operators in Florida and Oklahoma optimize for motorcoach parking and quick-serve dining throughput.
Leisure absorbs the largest room-night volume; Business Meetings is climbing the fastest as corporate travel normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level sports betting legalization and tribal compact renegotiations are redistributing casino tourism investment across American jurisdictions. Nevada retains destination dominance while Oklahoma, Florida, and Atlantic City corridors capture shifting regional demand.
Nevada
Clark County's Las Vegas Strip anchors luxury integrated resort development with Formula 1 and Super Bowl events compressing peak pricing. The Nevada Gaming Control Board enforces suitability standards that delay executive staffing but preserve operational integrity. Downtown Las Vegas and Reno sub-markets are diversifying into experiential entertainment to capture drive-in visitors from California and Arizona.
Oklahoma
Tribal compacts with the Choctaw Nation and Chickasaw Nation authorize Class III gaming expansion across 50,000+ electronic devices. The National Indian Gaming Commission mandates enhanced audit trail capabilities for sovereign regulatory compliance. Thackerville's WinStar and Durant's Choctaw properties leverage Texas border proximity to capture Dallas-Fort Worth metro leakage without commercial casino competition.
Florida
The Seminole Tribe's compact-negotiated exclusivity enables Hollywood and Tampa mega-resort investments with banked card games and sports wagering. State constitutional amendment requirements block commercial casino expansion outside tribal zones. Orlando corridor proximity and Miami international connectivity position properties for Latin American VIP feeder networks.
Atlantic City
New Jersey Division of Gaming Enforcement standards serve as regulatory templates for mobile wagering frameworks nationwide. Boardwalk properties compete on convenience gaming and quick-serve dining rather than destination dwell time. Marina district resorts leverage convention center adjacency for corporate event compression during shoulder seasons.
USA Casino Tourism Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resort operators with multi-state licensing capabilities and tribal sovereign immunity advantages. Three strategic archetypes dominate: luxury hospitality designers, regional scale platforms, and tribal exclusivity holders. Competitive intensity manifests through loyalty program density wars and jurisdiction-by-jurisdiction licensing races rather than direct property overlap.
Within the luxury integrated resort tier, Wynn Resorts and MGM Resorts exemplify design-forward positioning with international VIP feeder infrastructure. Caesars Entertainment anchors the regional scale archetype through omnichannel loyalty integration across dozens of properties. These operators represent contrasting capital deployment philosophies—asset-heavy development versus asset-light management contracts—while competing for the same destination event compression weekends.
| Leading Market Players |
|---|
| Wynn Resorts |
| Bally's Corporation |
| MGM Resorts |
| Resorts World Las Vegas |
| Fontainebleau Las Vegas |
| Caesars Entertainment |
| Penn Entertainment |
| WinStar World Casino and Resort |
| Las Vegas Sands |
| Others |
Value Network & Pricing Analysis
Overcapacity in Atlantic City's standalone casino segment compresses rate premiums while tightening margins for operators lacking integrated resort scale, forcing supply-side consolidation and selective reinvestment toward higher-yield formats.
Pricing Analysis
Property format tier—luxury integrated resort versus regional tribal facility versus convenience-focused standalone—creates the primary spread in per-visitor yield across the USA casino tourism market. MGM Resorts and Wynn Resorts command premium-mid-economy pricing differentiation through convention center adjacency and VIP salon density, while Oklahoma tribal properties compete on volume throughput with lower per-trip spend. Pricing pressure stems from social casino gaming applications capturing younger demographic engagement without physical travel requirements. Domestic leisure travelers show highest price sensitivity, whereas corporate meeting planners and international VIP gamblers demonstrate inelastic demand for peak-event weekends.
Supply Chain Analysis
Gaming device manufacturing concentrates in Nevada, Illinois, and select Asian production hubs serving the North American casino floor replacement cycle. Electronic gaming machines draw from semiconductor components, specialized display panels, and secure currency handling systems. Single-source vulnerability in server-based gaming software licensing creates operational risk for regional operators migrating to cloud-native infrastructure. Distribution runs through manufacturer-direct sales for major Strip properties and third-party distributor networks for tribal and regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USA casino tourism incumbents face substitution defense against social casino platforms and sweepstakes-based digital competitors that capture engagement without requiring destination travel investment.
For Market Incumbents: Build loyalty program density as the primary moat against digital substitutes. MGM Resorts and Caesars Entertainment demonstrate this through omnichannel point accumulation spanning physical properties and mobile sports wagering. Integrate biometric authentication with player tracking databases to deepen personalized engagement. Prioritize convention center square footage expansion in Las Vegas and Atlantic City to secure contracted corporate room blocks that insulate against leisure demand volatility. For New Entrants and Emerging Players: Pursue underpenetrated state markets lacking commercial casino frameworks, specifically Texas and Georgia corridors where tribal compact advocacy or legislative amendment passage creates first-mover positioning. Target airport slot lounges and interstate highway travel centers as micro-casino formats requiring reduced capital deployment versus full integrated resort development. Emphasize cashless wagering technology convergence as differentiation against legacy property infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light management contract operators with multi-state licensing capabilities rather than capital-intensive greenfield development. Tribal casino management agreements offer sovereign immunity-protected revenue streams with reduced regulatory friction. Monitor state legislative sessions for sports betting expansion signals as inflection indicators for jurisdiction-by-jurisdiction market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Wagering Platform Integration | Unifies loyalty recognition across Caesars Entertainment's omnichannel touchpoints, extending player lifetime value beyond physical visits. |
| Tribal Compact Renegotiation | Expands Class III gaming authorization for Oklahoma's Choctaw Nation, securing exclusivity zones against commercial competition. |
| Convention Center Capacity Expansion | Positions MGM Resorts to capture corporate meeting compression during Las Vegas Formula 1 and Super Bowl peak weekends. |
| Biometric Cashless Wagering Deployment | Enables real-time responsible gaming intervention for Nevada Gaming Control Board compliance while reducing floor labor costs. |
| Esports Tournament Infrastructure | Attracts millennial and Generation Z demographics to Atlantic City properties seeking differentiation against Las Vegas benchmarks. |
Research Methodology
Cross-validation between regulatory commission filings and operator financial disclosures anchors the qualitative findings in this USA casino tourism analysis. Primary interviews with casino operations executives, tribal gaming commission administrators, state gaming enforcement directors, and hospitality asset managers combined with secondary validation from National Indian Gaming Commission technical standards, Nevada Gaming Control Board suitability determinations, New Jersey Division of Gaming Enforcement licensing records, and SEC 10-K filings. Bottom-up property-level revenue modeling and top-down state gaming tax receipt aggregation provided triangulation across data sources.
Calibration against historical CAGRs from comparable hospitality and entertainment sectors informed the projection framework across the analysis window. Segmentation dimensions modeled include customer type, casino format tier, entertainment offering category, and visit purpose, with additional weighting for state regulatory framework variations. CAGRs derived from trend extrapolation adjusted for jurisdictional expansion velocity and substitution threat intensity. Forecast inputs incorporated tribal compact renegotiation timelines and state constitutional amendment passage probabilities.
Macroeconomic conditions sit as an overlay; deviation in discretionary travel spending indices and corporate event budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory expansion pace and technology adoption curves. Cross-checking against National Indian Gaming Commission revenue reports and state gaming commission tax collections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
India Faith Based Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Global Desert Tourism Market