
 Digital Travel Market | 2026-2036
Digital Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Travel Market Analysis
Online travel agency capacity in Southeast Asia is decoupling from legacy global distribution systems as regional cloud infrastructure matures. Booking.com leverages localized payment integration to sustain market presence across fragmented currency environments. Expedia Group anchors its competitive set through proprietary lodging supply contracts in tier-one destinations. Trip.com Group dominates outbound Chinese travel via integrated railway and airline inventory control.
Digital travel encompasses software-mediated discovery, comparison, reservation, and fulfillment of transportation, accommodation, and experience products through algorithmic search, dynamic pricing engines, and API-connected inventory systems. The primary commercial purpose is reducing friction in multi-supplier itinerary assembly while capturing transaction fees and advertising yield. Mobile apps lead platform engagement in emerging markets where smartphone penetration exceeds desktop access, while travel aggregators capture margin pools through metasearch advertising models rather than merchant inventory risk. Business travelers represent a concentrated high-yield segment characterized by repeat booking patterns and enterprise contract structures.
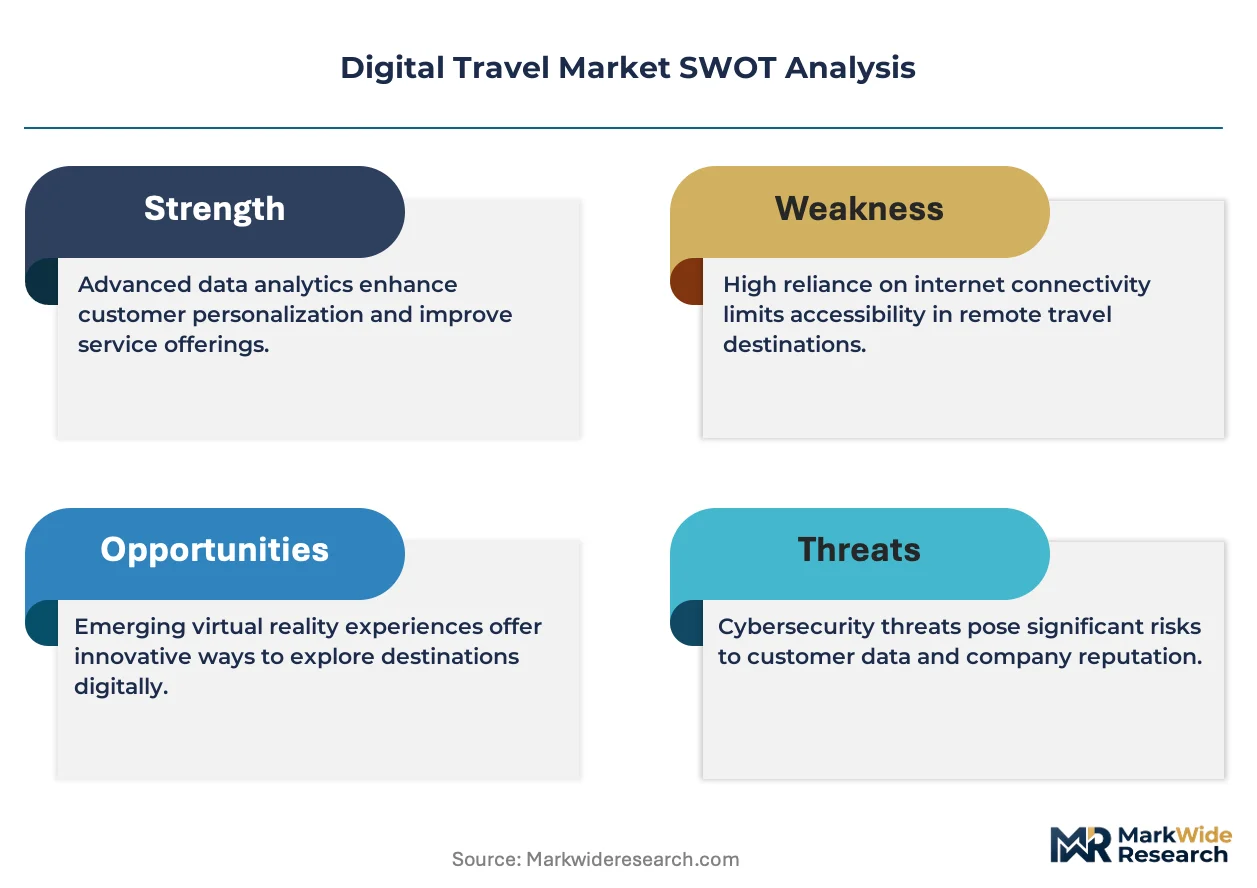
GDPR enforcement by European data regulators constrains cross-border passenger data flows, compelling platform architecture redesigns for lawful international transfer. The EU AI Act introduces risk-classification requirements for algorithmic pricing and recommendation systems deployed to European consumers. China's SAMR oversees antitrust scrutiny of super-app travel bundling practices, affecting how platforms integrate transportation and lodging services. Stakeholders must monitor evolving interoperability mandates that could force inventory sharing between competing reservation systems.
Market Dynamics
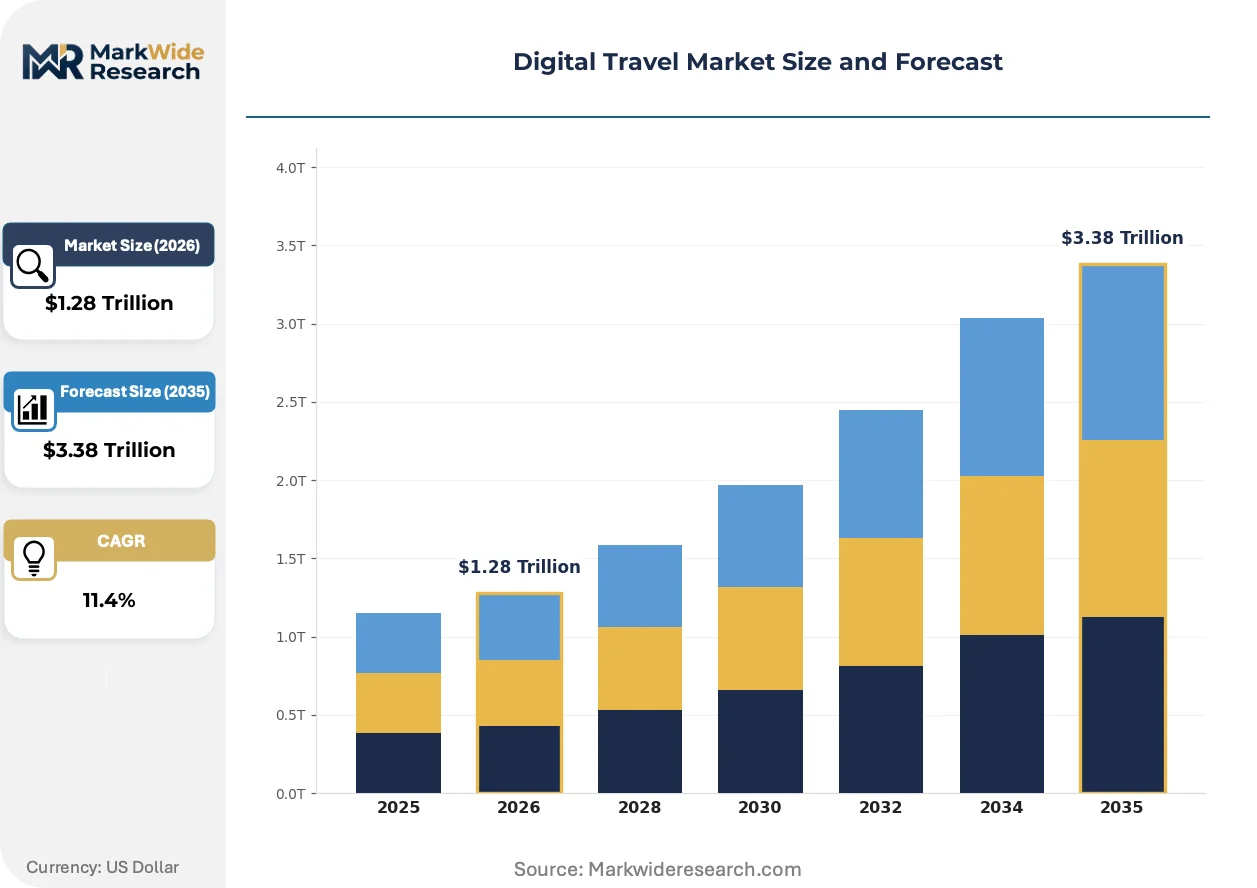
Mobile-first booking behavior and super-app bundling practices are compressing traditional distribution layers, while regulatory scrutiny of algorithmic pricing systems forces platform architecture redesigns across multiple jurisdictions.
Growth Catalysts
- ISO 27001 Security Standards:Corporate travel procurement departments mandate certified vendors, accelerating platform consolidation among compliant providers in Europe.
- Railway-Airline Inventory Convergence:Intermodal booking engines capture margin from fragmented transportation suppliers through unified reservation interfaces.
- Urban Corridor Demand Density:China's Shanghai-Beijing corridor concentrates mobile transaction volume, enabling localized payment integration at scale.
Market Restraints
- GDPR Cross-Border Data Friction:European data regulators constrain international passenger data flows, forcing costly platform rearchitecture for lawful transfer mechanisms.
- Legacy GDS Switching Costs:Southeast Asian online travel agencies face technical debt from decades-old global distribution system contracts that resist API migration.
- Super-App Antitrust Scrutiny:China's SAMR restricts travel service bundling practices, limiting how platforms integrate transportation and lodging inventory.
Strategic Opportunities
- Cloud Infrastructure Maturation:Southeast Asian regional cloud deployments enable direct supplier connections, bypassing legacy distribution intermediaries entirely.
- EU AI Act Risk Classification:Algorithmic pricing and recommendation systems face new compliance tiers, creating advisory service revenue streams for compliant platforms.
- Metasearch Advertising Yield:Aggregators capture margin pools through advertising models rather than merchant inventory risk, reducing working capital intensity.
Industry Challenges
- Interoperability Mandate Uncertainty:Potential forced inventory sharing between competing reservation systems threatens proprietary supply contract value.
- Algorithmic Pricing Compliance:Risk-classification requirements under European AI Act demand documentation and audit trails that strain technical teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Travel Market |
| Market Size in 2026 | $1.28 Trillion |
| Market Size in 2035 | $3.38 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Booking, Trip Planning, Travel Insurance, Itinerary Management Consumer Segment: Business Travelers, Leisure Travelers, Adventurers, Families Platform Type: Mobile Apps, Web Portals, Social Media, Travel Aggregators Payment Mode: Credit Cards, Digital Wallets, Bank Transfers, PayPal |
| Companies Covered | Airbnb, KAYAK, Booking.com, American Express Global Business Travel, Navan, Expedia Group, Hopper, Skyscanner, Trip.com Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Travel Market Emerging Trajectories
Generative search interfaces and embedded finance products are restructuring how travelers discover, compare, and pay for multi-supplier itineraries across fragmented currency environments.
Dynamic pricing engines powered by machine learning are integrating real-time demand signals from airline yield management systems, hotel property management platforms, and railway reservation databases. Corporate travel managers adopt these tools to optimize advance purchase timing against cancellation flexibility. The technology is integrating previously siloed inventory pools into unified recommendation streams that compress comparison shopping duration.
GDPR enforcement by European data regulators constrains cross-border passenger data flows, compelling platform operators to implement data residency architectures and standard contractual clauses. This regulatory friction increases operational complexity for multinational booking platforms serving European consumers. Travel aggregators with European headquarters invest most heavily in privacy engineering to maintain lawful international transfer capabilities.
Business travelers now expect seamless mobile itinerary management with embedded expense reporting and policy compliance checks. Traditional corporate travel management companies face displacement from software-native platforms that bundle booking, payment, and reconciliation in single interfaces. This behavioral shift concentrates most visibly in North American and European enterprise accounts where procurement departments prioritize consolidated billing and duty-of-care tracking over legacy agent relationships.
Digital Travel Market Segmentation
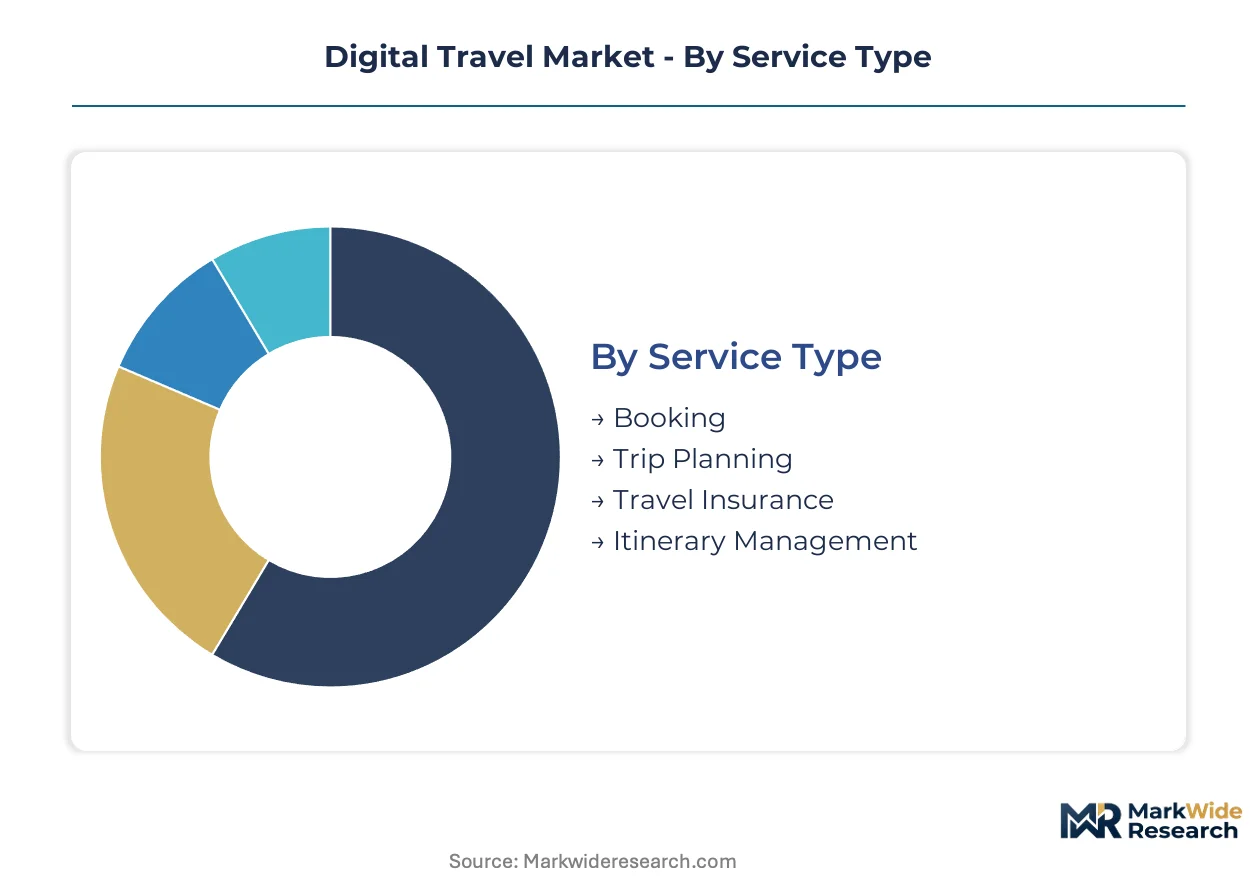
Digital travel platforms configure their technology stacks and partnership networks around distinct service delivery models and consumer behavioral profiles. Segmentation reveals where margin pools concentrate and which integration architectures command premium positioning.
Service Type:
Standalone modules operate through dedicated interfaces while embedded functions integrate into super-app ecosystems or corporate software suites.
- Booking:Real-time inventory aggregation engines connect airline, hotel, and railway reservation systems through API protocols. China's urban corridor from Shanghai to Beijing concentrates transaction volume where mobile-first platforms dominate intermodal search behavior.
- Trip Planning:Algorithmic recommendation systems synthesize multi-supplier itineraries using machine learning trained on historical preference data. European procurement departments prioritize ISO 27001-certified planning tools for corporate travel programs.
- Travel Insurance:Embedded underwriting products activate at point-of-sale through parametric triggers tied to flight status APIs.
- Itinerary Management:Unified dashboard interfaces consolidate confirmation emails, boarding passes, and real-time disruption alerts into single mobile views.
Volume placements concentrate in Booking; the faster expansion belongs to Itinerary Management.
Consumer Segment:
Cost tier differentiation separates high-frequency corporate accounts from discretionary leisure purchasers with divergent cancellation flexibility requirements.
- Business Travelers:Enterprise-contracted accounts demand consolidated billing, policy compliance automation, and duty-of-care tracking embedded within booking workflows. North American procurement departments favor platforms integrating expense reconciliation with advance purchase optimization.
- Leisure Travelers:Price-sensitive consumers comparison-shop across metasearch aggregators and direct supplier sites with minimal loyalty program lock-in.
- Adventurers:Experience-focused travelers prioritize activity inventory and off-grid accommodation over standardized hotel chains.
- Families:Multi-passenger bookings require child fare rules, adjoining room guarantees, and flexible cancellation terms.
Revenue density clusters around Business Travelers; Leisure Travelers are climbing the fastest in absolute user acquisition.
Platform Type:
Customer acquisition economics vary sharply between owned-channel investments and distributed presence through third-party interfaces.
- Mobile Apps:Native smartphone applications dominate emerging market engagement where desktop penetration lags smartphone adoption. Southeast Asian platforms leverage regional cloud infrastructure to bypass legacy distribution intermediaries.
- Web Portals:Browser-based booking retains significance for complex multi-city itineraries requiring larger screen real estate.
- Social Media:Discovery-layer integration enables impulse booking through influencer content and peer recommendation feeds.
- Travel Aggregators:Metasearch models capture advertising yield without merchant inventory risk, reducing working capital intensity versus direct booking platforms.
Transaction volume flows through Mobile Apps; the steepest expansion trajectory belongs to Travel Aggregators.
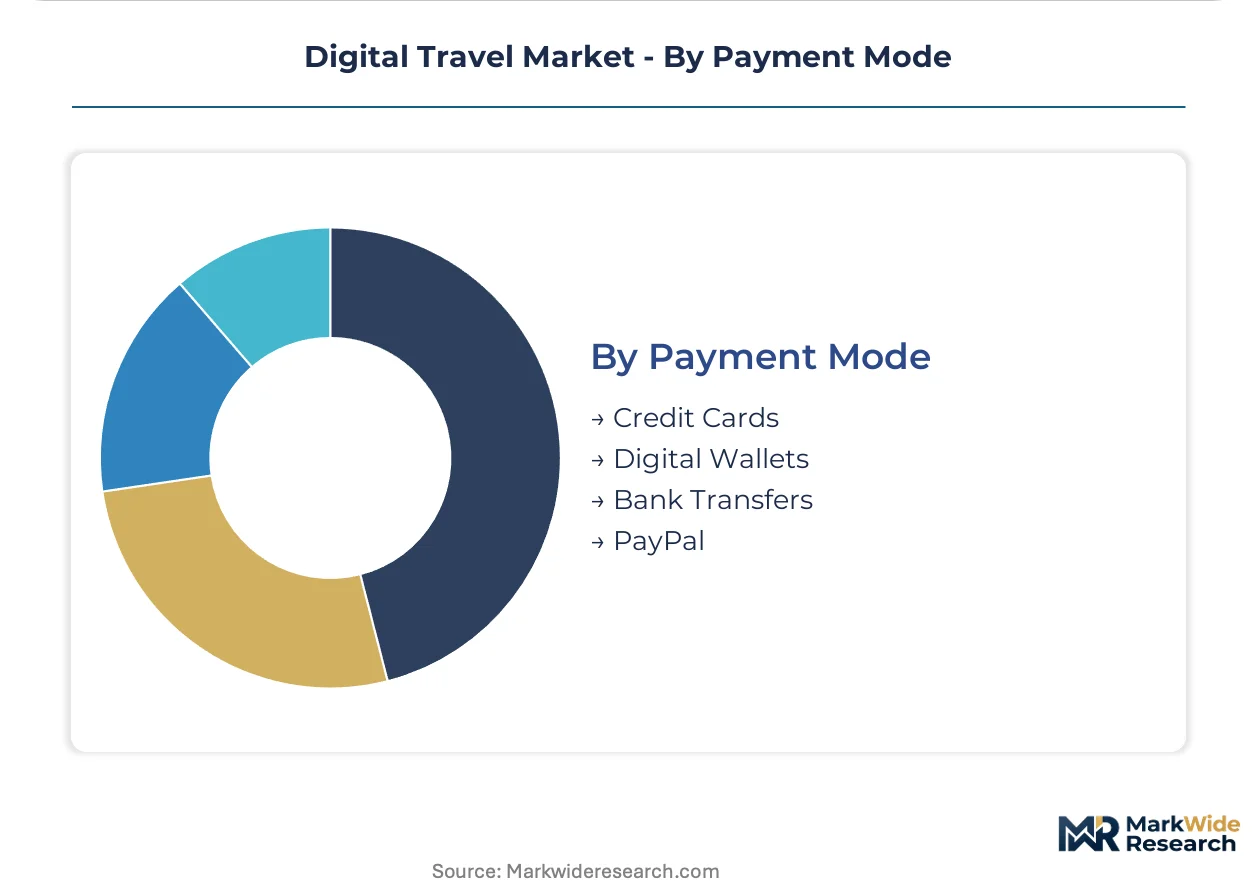
Payment Mode:
Geographic fragmentation in financial infrastructure forces localized payment stack configurations across currency environments.
- Credit Cards:Revolving credit instruments dominate North American and European corporate travel with integrated rewards programs and chargeback protections.
- Digital Wallets:Mobile payment ecosystems capture consumer preference in Asia-Pacific markets where super-app financial services bundle travel with daily transactions.
- Bank Transfers:Direct account debits serve price-sensitive segments seeking to avoid interchange fees on high-value bookings.
- PayPal:Digital-first consumers favor established third-party escrow services for supplier trust verification in cross-border transactions.
Settlement volume concentrates in Credit Cards; Digital Wallets are gaining share fastest in emerging market corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure deployments in Singapore anchor Southeast Asian platform expansion, while data residency requirements in Frankfurt and Paris reshape European architecture investments. Mobile transaction density concentrates in China's eastern corridor and India's metropolitan clusters.
China
Shanghai-Beijing urban corridor drives mobile-first booking volume through super-app ecosystems integrating railway and airline inventory. SAMR antitrust oversight restricts service bundling practices, forcing unbundled platform architectures. Shenzhen and Hangzhou clusters host domestic cloud deployments supporting real-time intermodal search engines.
United States
Corporate travel procurement departments in New York and Chicago prioritize consolidated billing platforms with embedded expense reconciliation. FAA regulations govern ancillary service disclosures for flight bookings, affecting platform transparency requirements. Silicon Valley and Seattle tech corridors concentrate engineering talent for generative search interface development.
Germany
ISO 27001 certification mandates from Frankfurt and Munich corporate headquarters accelerate vendor consolidation among compliant providers. GDPR enforcement by Berlin data regulators constrains cross-border passenger data flows, compelling regional data residency investments. Bavaria's industrial belt generates concentrated business travel demand from manufacturing procurement departments.
India
Mumbai and Delhi-NCR metropolitan areas concentrate mobile wallet adoption for travel transactions through UPI-enabled super-apps. RBI oversight of digital payment aggregators shapes settlement infrastructure requirements for booking platforms. Bangalore's technology corridor supplies engineering capacity for regional cloud-native reservation systems.
United Kingdom
London's financial services sector drives premium corporate travel platform adoption with integrated duty-of-care tracking. UK Information Commissioner's Office GDPR guidance affects international data transfer mechanisms for platforms serving European consumers. Manchester and Edinburgh clusters support regional customer service operations for multinational booking providers.
Digital Travel Market Vendor Landscape
Global majors compete with regional champions across inventory access and payment localization dimensions. The market structures around three tiers: vertically integrated platform operators owning proprietary lodging supply, metasearch aggregators capturing advertising yield without merchant risk, and corporate-focused specialists embedding policy compliance into booking workflows. Strategic moves concentrate on cloud infrastructure migration and API-first supplier connectivity.
Within the integrated platform tier, Booking.com and Expedia Group exemplify scale-driven inventory control models, while Trip.com Group occupies a position bridging domestic Chinese market dominance with outbound expansion. Among metasearch specialists, Skyscanner and KAYAK represent advertising-anchored discovery layers that reduce working capital intensity versus direct booking models.
| Leading Market Players |
|---|
| Airbnb |
| KAYAK |
| Booking.com |
| American Express Global Business Travel |
| Navan |
| Expedia Group |
| Hopper |
| Skyscanner |
| Trip.com Group |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between ISO 27001-compliant platforms and uncertified competitors manifests in both subscription pricing premiums and supply chain reconfigurations around audited cloud infrastructure. Corporate procurement departments in Frankfurt and Munich pay 15-25% markups for certified vendors while forcing data residency investments that reshape hosting geography.
Pricing Analysis
Warranty and service bundling separates merchant inventory models from metasearch advertising tiers, with the former carrying cancellation risk premiums and the latter unbundling supplier default exposure. Three-tier pricing structure across premium enterprise contracts, standard SaaS subscriptions, and economy self-service bookings reflects policy automation depth and duty-of-care integration. Pricing pressure stems from cloud infrastructure commoditization in Southeast Asia, where regional deployments bypass legacy distribution fees. Leisure travelers through metasearch aggregators exhibit highest price sensitivity; corporate travel managers with enterprise contracts demonstrate lowest sensitivity due to consolidated billing requirements.
Supply Chain Analysis
Reverse-logistics flows for itinerary disruption management—rebooking, refund processing, and voucher redemption—create working capital intensity that separates balance-sheet-heavy platforms from asset-light aggregators. Inventory sourcing concentrates in China, the United States, and Germany, where airline yield management systems, hotel property management platforms, and railway reservation databases anchor API connectivity. Cloud compute, payment processing networks, and fraud detection algorithms constitute critical input dependencies. Single-source vulnerability in legacy global distribution system contracts threatens Southeast Asian platform margins. Distribution runs through API-first supplier connections, mobile app stores, and corporate procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races into proprietary lodging supply and captive payment infrastructure, with intermodal inventory control serving as the decisive upstream lever.
For Market Incumbents: Cement proprietary supply contract value through exclusive rate parity clauses in tier-one destinations, countering metasearch disintermediation. Fortify ISO 27001 certification moats against emerging cloud-native competitors lacking audit history. Capacity addition in Singapore and Frankfurt data centers supports latency-sensitive corporate booking workflows.
For New Entrants and Emerging Players: The mid-market price-point gap between Booking.com's enterprise tier and Hopper's predictive pricing engine offers white-space entry through embedded finance products. Target itinerary management modules for small and medium enterprises lacking dedicated travel managers. Go-to-market leverage rests on UPI and Alipay integration for India-China corridor bookings.
For Investors and Strategic Acquirers: Re-rating potential sits with regional cloud-native platforms given GDPR compliance cost absorption and Southeast Asian infrastructure maturation. Long-term viability favors asset-light metasearch models with advertising yield over merchant inventory risk. Monitor SAMR bundling enforcement intensity and EU AI Act risk-classification implementation as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Lodging Supply Contracting | Exclusive rate parity in tier-one destinations locks out metasearch competitors from margin-rich inventory. |
| Embedded Finance Product Launch | Point-of-sale insurance and flexible payment terms capture ancillary revenue from price-sensitive leisure segments. |
| Intermodal API Integration | Railway-airline inventory convergence enables unified reservation interfaces that compress supplier fragmentation. |
| ISO 27001 Certification Investment | Corporate procurement mandates in Europe consolidate vendor selection among compliant platform operators. |
| Regional Cloud Infrastructure Deployment | Singapore and Frankfurt data centers satisfy data residency requirements while reducing legacy GDS dependency. |
Methodological Framework
Document review covered SEC filings from Booking Holdings and Expedia Group, EU regulatory guidance on GDPR transfer mechanisms, and SAMR antitrust bulletins, complemented by interviews with corporate travel procurement managers, airline distribution executives, platform engineering leads, and payment infrastructure specialists. Secondary validation drew from App Annie mobile engagement data, IATA airline industry reports, and cloud provider capex disclosures. Bottom-up transaction volume estimates triangulated against top-down market size assessments.
Segment-level projections across service type, consumer segment, platform type, and payment mode fed into consolidated market sizing across the analysis window. CAGRs derived from historical trajectory analysis and adoption curve modeling for mobile-first booking behavior. Forecast inputs incorporated railway inventory API penetration rates and corporate travel policy automation adoption.
Inputs from airline revenue management departments and hotel chain distribution heads were available through the study window; gaps in super-app transaction-level data introduce uncertainty bands around China market share estimates. Practitioners should monitor EU AI Act enforcement timelines and SAMR bundling restriction scope for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Educational Tourism Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
US Outbound Tourism Market