
 Italy Casino Tourism Market | 2026-2036
Italy Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Casino Tourism Market Foresight
Integrated resort hospitality revenue is fragmenting across standalone gaming halls, boutique casino hotels, and cruise-anchored venues. Ludica Italia leverages its Milan-centric property portfolio to anchor premium table-game traffic. CasinOpera competes through theatrical entertainment bundling at its Rome flagship. Travel Leaders sustains package-tour distribution control across North American feeder markets into Venice and Florence.
Italy casino tourism denotes travel itineraries where licensed gambling establishments constitute the primary or substantial purpose of visitation, typically involving ADM-regulated gaming floors with minimum bet thresholds, slot-to-table ratios, and mandatory player identification protocols designed to generate taxable leisure revenue for host municipalities. Land-based venues dominate current margin pools through high-roller table minimums and hospitality bundling, while hybrid formats that merge physical loyalty programs with remote account access represent the fastest-expanding segment category. E-wallet penetration within payment method splits is displacing cash handling costs and accelerating KYC compliance velocity at entry points.
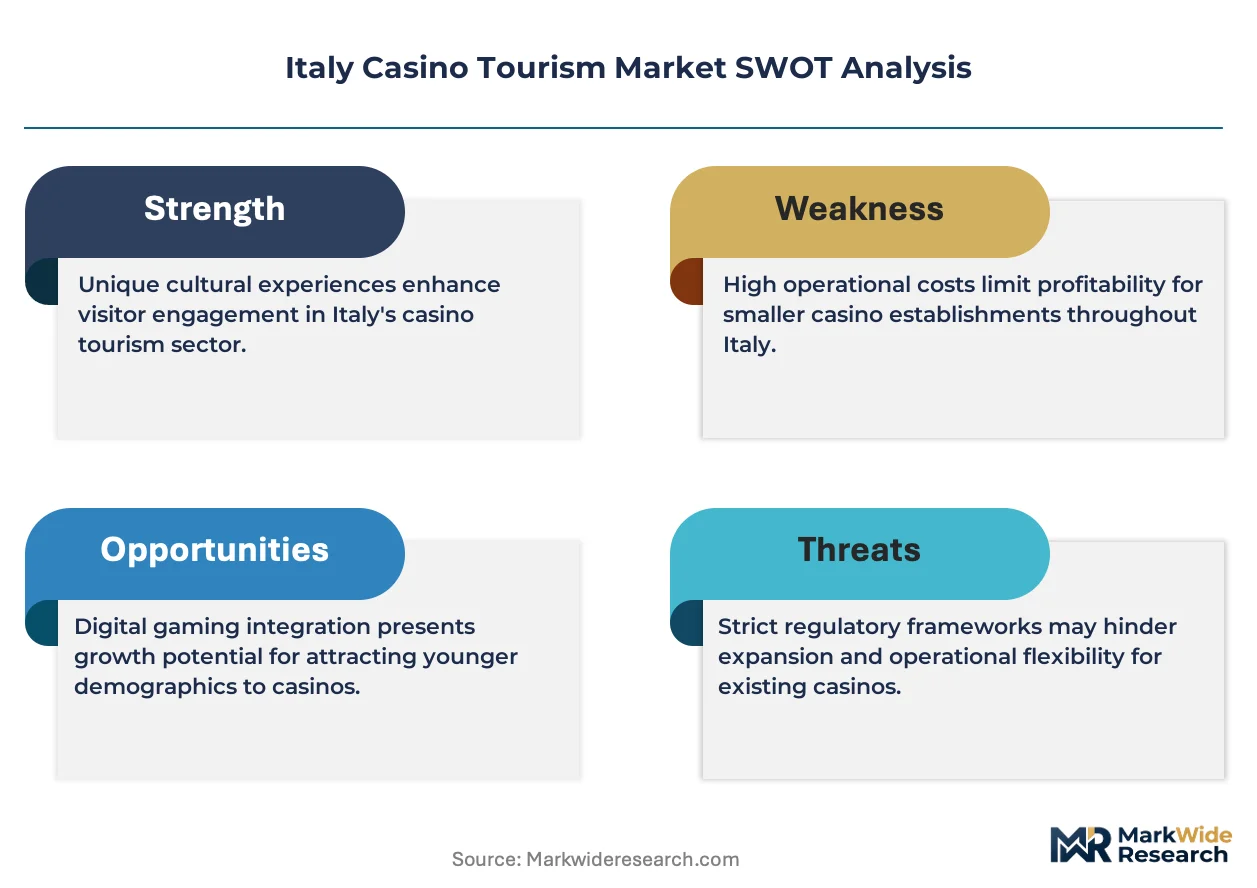
ADM licensing requirements, Italy's Gambling Advertising Decree restrictions, and EU Anti-Money Laundering Directives collectively shape operator marketing scope, player onboarding friction, and cross-border payment routing. The EU Green Deal's hospitality energy benchmarks are pressuring historic casino properties in Venice and Sanremo toward retrofit capital commitments. Stakeholders must weigh regulatory compliance investment against the revenue trajectory of hybrid customer journeys before committing to property expansion or digital platform buildouts.
Market Dynamics
ADM licensing reforms for remote gaming are compressing the competitive window for new entrants while forcing incumbent operators to recalibrate their hybrid physical-digital customer acquisition costs. The regulatory velocity is outstripping legacy compliance infrastructure across northern Italy's established gaming corridors.
Growth Catalysts
- E-wallet payment penetration:Digital wallet adoption at entry points is slashing cash handling overhead and compressing KYC verification timelines for player onboarding.
- EU Green Deal hospitality benchmarks:Retrofit mandates for historic Venetian and Sanremo properties are unlocking municipal co-financing for energy-efficient casino floor renovations.
- Lombardy-Veneto industrial corridor demand:High-net-worth manufacturing executives from Milan through Verona are extending business travel into integrated resort weekends.
Market Restraints
- Italy's Gambling Advertising Decree:Broadcast and digital promotional restrictions throttle operator brand awareness among first-time visitors.
- Historic property retrofit costs:Venice's UNESCO-protected casino buildings face 40-60% premium construction costs versus greenfield developments.
- EU Anti-Money Laundering Directive compliance:Enhanced player due diligence protocols extend account activation timelines and increase abandonment rates at digital entry points.
Strategic Opportunities
- Hybrid loyalty program convergence:Operators bridging physical player cards with remote account access capture cross-channel spend that pure land-based or pure digital competitors forfeit.
- Cruise-anchored venue expansion:Port cities including Genoa and Naples present underdeveloped embarkation-day gaming revenue pools.
- Southern Italy market whitespace:Calabria and Sicily lack integrated resort density despite rising domestic tourism infrastructure investment.
Industry Challenges
- Table-game dealer certification pipelines:ADM-mandated croupier licensing timelines lag operator expansion schedules across emerging properties.
- Legacy slot system integration:Mechanical reel-to-digital platform migrations demand specialized technical talent scarce in Italian gaming technology labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Casino Tourism Market |
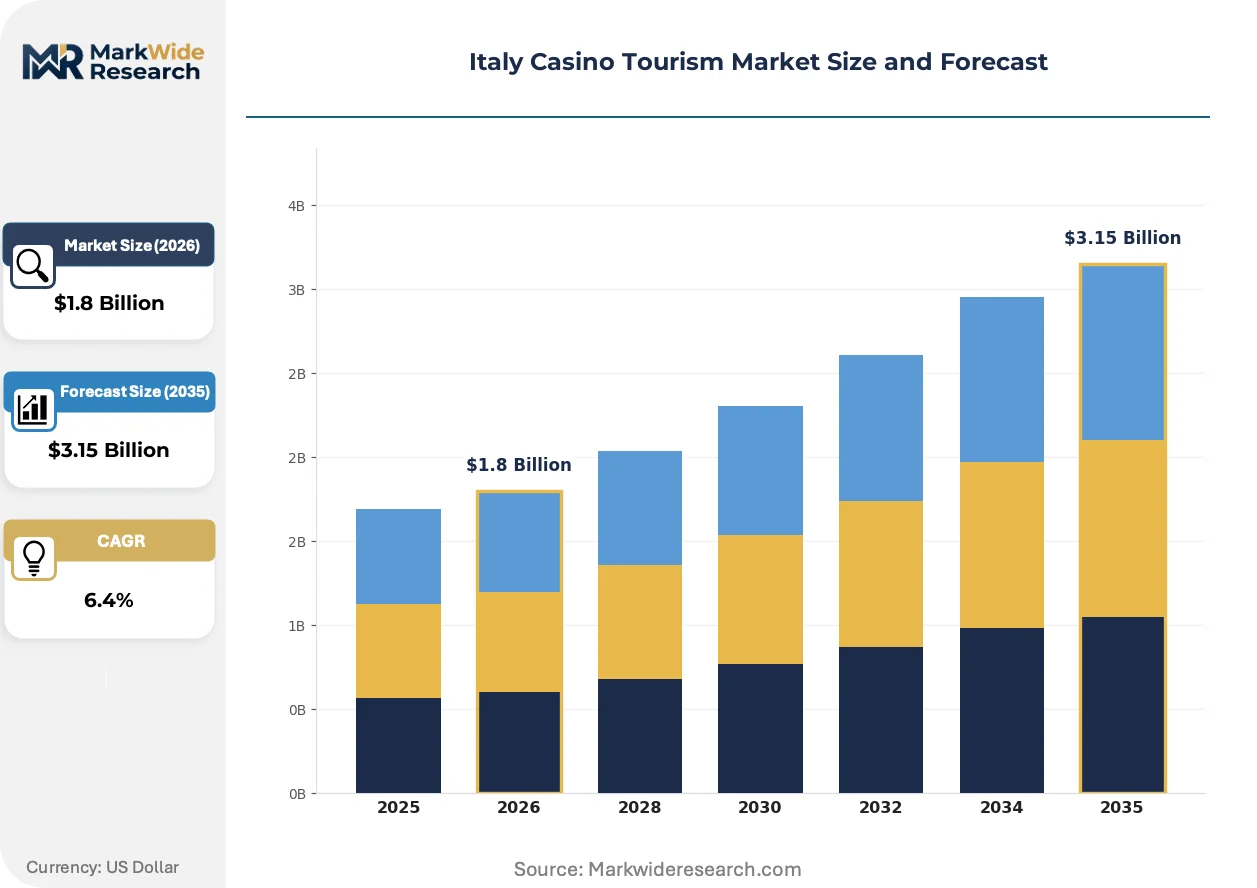
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Casino Type: Land-Based, Online, Hybrid, Cruise Ship Customer Demographics: Millennials, Families, Tourists, High Rollers Tourism Segment: Leisure, Business, Sports Betting, Entertainment Payment Method: Cash, Credit Card, E-Wallet, Cryptocurrency |
| Companies Covered | Travel Leaders, Rome and Italy Tourist Services, Globus Journeys, Ludica Italia, CasinOpera, MindBridge Italia, Gioco Nostro, Senso Ludo, TourRadar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Casino Tourism Market Shifts & Advancements
Operator technology stacks are converging around unified player data layers that erase friction between on-premise and remote gaming sessions. This integration imperative is reshaping capital allocation toward software-defined casino floors.
RFID-enabled table-game chips are hybridizing physical wagering with real-time player behavior analytics. Premium Venetian and Milan properties are deploying these systems to automate comp accrual and detect advantage play patterns. The technology is hybridizing hospitality revenue management with gaming floor surveillance functions.
Italy's ADM remote gaming licensing framework is tightening technical standards for platform security and player fund segregation. Operators must now demonstrate server redundancy and disaster recovery capabilities exceeding prior thresholds. The regulation is compressing vendor selection cycles and favoring established European platform providers over emerging entrants.
Package-tour distribution through North American travel intermediaries is fragmenting as direct operator booking engines capture repeat visitor relationships. Venice and Florence properties are unbundling airfare-hotel-gaming bundles to retain margin on ancillary spend. The shift is most pronounced among high-frequency visitors from the northeastern United States feeder markets.
Italy Casino Tourism Market Segmentation
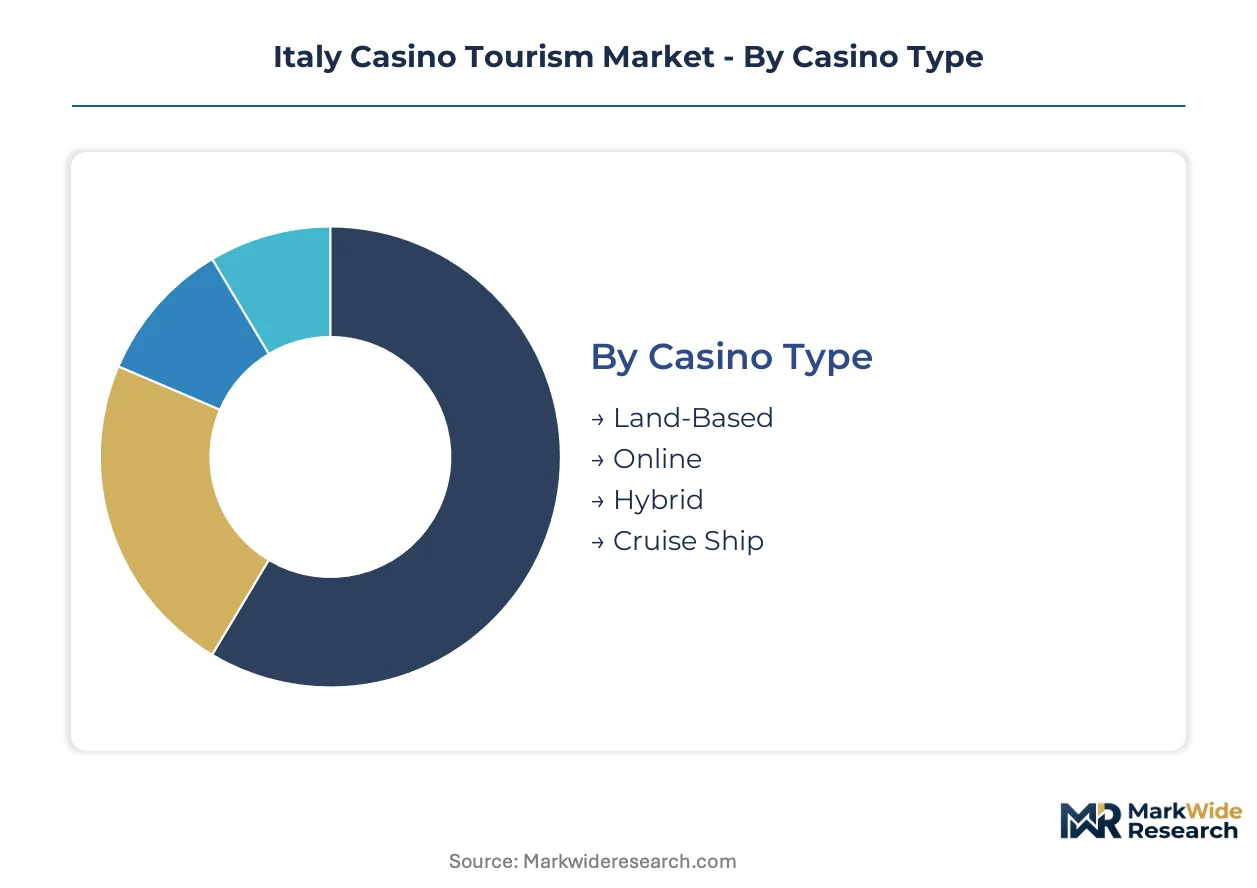
Casino tourism segmentation in Italy reveals divergent margin profiles across physical and digital touchpoints. Operator strategy must calibrate infrastructure investment against the distinct compliance burdens and customer acquisition economics governing each category.
Casino Type:
The use-case spectrum spans immersive hospitality experiences through frictionless remote access, with hybrid formats capturing cross-channel lifetime value.
- Land-Based:Historic properties in Venice, Milan, and Sanremo anchor premium table-game revenue through ADM-mandated floor layouts with defined slot-to-table ratios. Northern Italy's industrial corridor concentrates high-roller visitation from Lombardy manufacturing executives extending business travel into integrated resort weekends.
- Online:ADM-licensed remote platforms operate under tightened technical standards for server redundancy and player fund segregation, compressing vendor selection cycles toward established European providers. Digital entry points face extended KYC timelines under EU Anti-Money Laundering Directive protocols, elevating abandonment rates during account activation.
- Hybrid:Unified player data layers bridge physical loyalty cards with remote account access, capturing spend that single-channel competitors forfeit.
- Cruise Ship:Embarkation-day gaming at Genoa and Naples ports accesses underdeveloped revenue pools with lower regulatory density than land-based venues.
Established volume favors land-based; emerging adoption favors hybrid.
Customer Demographics:
Cost tier stratification separates premium hospitality bundling from mass-market digital acquisition.
- Millennials:E-wallet-native cohort drives digital platform engagement, with payment method preferences slashing operator cash-handling overhead at entry points.
- Families:Multi-generational itineraries concentrate in Florence and Rome properties where theatrical entertainment bundling broadens appeal beyond gaming floors.
- Tourists:North American package-tour distribution through Venice intermediaries is fragmenting as direct operator booking engines capture repeat visitor relationships.
- High Rollers:Milan-centric properties anchor premium table-game traffic through elevated minimums and personalized hospitality protocols.
Margin concentration sits with high rollers; volume expansion targets millennials.
Tourism Segment:
Application context determines ancillary revenue capture and length-of-stay economics.
- Leisure:Discretionary itineraries dominate Venice and Sanremo visitation, with UNESCO-protected historic properties commanding premium positioning despite 40-60% retrofit cost premiums under EU Green Deal mandates.
- Business:Corporate travel extension into integrated resort weekends concentrates along the Lombardy-Veneto corridor, where manufacturing executive density supports midweek gaming floor utilization.
- Sports Betting:ADM-regulated wagering intersects with tourism through event-anchored visitation patterns, particularly around football calendar peaks.
- Entertainment:Theatrical bundling at Rome flagship properties competes for cultural-tourism spend against traditional performing arts venues.
Leisure commands peak rates; business stabilizes occupancy troughs.
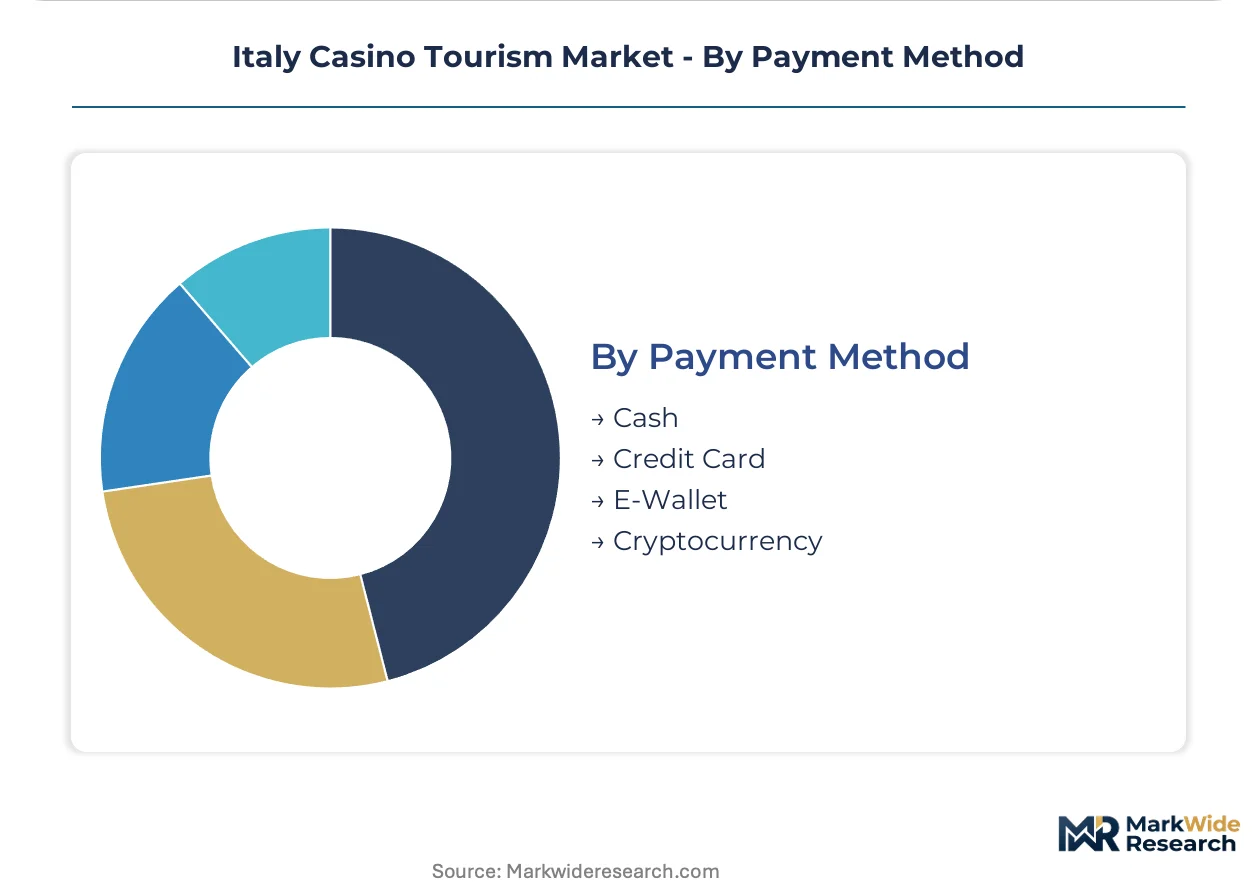
Payment Method:
Maturity gradients separate legacy cash infrastructure from accelerating digital displacement.
- Cash:Declining share reflects ADM-mandated player identification protocols and rising handling costs at historic property entry points.
- Credit Card:Persistent utility for high-roller hospitality bundling, though interchange fees pressure margin on premium transactions.
- E-Wallet:Penetration is displacing cash handling costs and accelerating KYC compliance velocity across northern Italy's gaming corridors.
- Cryptocurrency:Regulatory ambiguity under EU Anti-Money Laundering frameworks constrains adoption despite operator interest in cross-border payment routing efficiency.
Legacy infrastructure favors credit; compliance velocity favors e-wallet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Italian sub-regions. Lombardy and Veneto exhibit price-inelastic high-roller visitation, while southern markets show greater sensitivity to package-tour pricing.
Lombardy
Milan-centric integrated resorts anchor premium table-game revenue through manufacturing executive density. ADM licensing reforms compress competitive windows for new entrants. The Lombardy-Veneto industrial corridor concentrates midweek gaming floor utilization from business travel extensions.
Veneto
Venice properties command peak rates despite UNESCO-protected retrofit premiums under EU Green Deal mandates. Historic casino buildings face 40-60% construction cost premiums versus greenfield developments. The Venetian lagoon cluster sustains discretionary leisure itineraries with theatrical entertainment bundling.
Lazio
Rome flagship properties compete for cultural-tourism spend through theatrical entertainment integration. Italy's Gambling Advertising Decree restricts broadcast and digital promotional scope. The capital metro anchors multi-generational family itineraries with broadened non-gaming appeal.
Piedmont
Sanremo's historic casino properties face energy retrofit mandates with municipal co-financing unlocks. EU Anti-Money Laundering Directive compliance extends player onboarding timelines. The Ligurian Riviera cluster maintains premium positioning through heritage hospitality assets.
Sicily
Calabria and Sicily present underdeveloped integrated resort density despite rising domestic tourism infrastructure. Southern markets lack hybrid loyalty program penetration seen in northern corridors. The Mediterranean island cluster offers whitespace for cruise-anchored venue expansion at Palermo and Catania ports.
Italy Casino Tourism Market Competitive Landscape
Integrated resort operators and tour packaging intermediaries split the market into distinct margin pools. The competitive structure concentrates around hospitality-bundled gaming floors in the north and distribution-controlled package circuits. Three archetypes dominate: property-centric luxury operators, theatrical entertainment bundlers, and travel intermediary networks. Consolidation pressure favors hybrid loyalty program convergence and direct booking engine buildouts over third-party distribution reliance.
Among property-centric operators, Ludica Italia and CasinOpera occupy differentiated positions within the premium tier. Ludica Italia exemplifies the Milan-anchored integrated resort archetype with concentrated table-game traffic. CasinOpera represents theatrical entertainment bundling through its Rome flagship positioning. Travel Leaders sits within the intermediary network archetype, sustaining distribution relationships across North American feeder markets.
| Leading Market Players |
|---|
| Travel Leaders |
| Rome and Italy Tourist Services |
| Globus Journeys |
| Ludica Italia |
| CasinOpera |
| MindBridge Italia |
| Gioco Nostro |
| Senso Ludo |
| TourRadar |
| Others |
Supply & Pricing Matrix
The Brenner Corridor freight artery linking northern Italian industrial hubs to Austrian and German markets transmits fuel cost volatility directly into hospitality procurement budgets, concentrating pricing power among integrated resort operators with captive supply relationships while forcing smaller venues toward third-party service contracts that erode margin capture.
Pricing Analysis
Ancillary hospitality revenue from spa services, fine dining, and extended-stay packages drives lifetime value per visitor beyond gaming floor metrics. Three-tier pricing structure across premium, standard, and economy levels segments visitors by minimum bet thresholds and loyalty tier status. Pricing pressure stems from EU Green Deal retrofit mandates elevating fixed costs at UNESCO-protected Venetian properties. Mass-market package-tour segments exhibit highest price sensitivity, while high-roller cohorts demonstrate inelastic demand for personalized hospitality protocols.
Supply Chain Analysis
Supplier-financing arrangements through extended payment terms and supply-chain finance facilities have become critical liquidity tools for historic property renovations. Gaming equipment manufacturing concentrates in Germany, Austria, and the United States, while hospitality textiles and fixtures draw from Italian domestic suppliers and Portuguese specialty manufacturers. Single-source vulnerability runs through proprietary RFID table-game chip providers. Distribution runs through ADM-licensed equipment distributors with exclusive territorial rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across payment method preferences and customer journey formats creates niche entry points for specialists unburdened by legacy infrastructure. The shift from package-tour intermediation toward direct operator booking engines particularly rewards agile entrants.
For Market Incumbents: Build hybrid loyalty program moats bridging physical player cards with remote account access to capture cross-channel spend. Incumbents should consolidate dealer certification pipelines through ADM-accredited training partnerships to outpace expansion timelines of emerging properties. Channel control over North American feeder market relationships remains a critical defensive lever against direct-booking fragmentation. For New Entrants and Emerging Players: Southern Italy integrated resort whitespace in Calabria and Sicily represents the most penetrable entry point given underdeveloped competitive density and rising domestic tourism infrastructure. Cruise-anchored venue expansion at Palermo and Catania ports offers lower regulatory density than land-based alternatives. A go-to-market angle targeting embarkation-day gaming revenue pools with streamlined digital onboarding bypasses legacy property retrofit burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from hospitality conglomerates with non-core casino assets in secondary Italian markets. Long-term viability centers on operators demonstrating unified player data layer capabilities across physical and digital touchpoints. The signal to watch is ADM remote gaming license application velocity as an inflection indicator for platform-provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Loyalty Platform Integration | Unifies physical player cards with remote account access to capture cross-channel lifetime value. |
| ADM Remote Gaming License Acquisition | Secures regulatory authorization for digital platform operations under tightened technical standards. |
| Cruise-Anchored Venue Expansion | Accesses underdeveloped embarkation-day revenue pools at Genoa and Naples port facilities. |
| EU Green Deal Retrofit Compliance | Unlocks municipal co-financing for energy-efficient renovations at historic Venetian properties. |
| Direct Booking Engine Development | Captures repeat visitor relationships fragmenting from North American travel intermediary control. |
Research Methodology
A standing panel of casino operations directors, ADM compliance officers, hospitality procurement managers, and travel intermediary account executives provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against ADM licensing registers, EU regulatory filings, and hospitality industry trade data. Bottom-up property-level revenue modeling triangulated against top-down regional tourism expenditure estimates.
Scenario-bracketing framed analytical approaches across the projection horizon, with sensitivity testing applied to regulatory reform timelines and macroeconomic tourism demand variables. Segmentation dimensions modeled encompass casino type, customer demographic cohort, tourism application context, and payment method preference. CAGRs derived from historical trajectory analysis adjusted for structural shifts in hybrid channel adoption and e-wallet penetration velocity.
Practitioners should monitor ADM licensing reform implementation pace and EU Anti-Money Laundering Directive enforcement intensity for early signals requiring forecast reassessment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Museums Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
USA Faith Based Tourism Market