
 RFP Software Market | 2026-2036
RFP Software Market Size, Share, and Industry Trends Forecast 2026-2036
RFP Software Market Insights
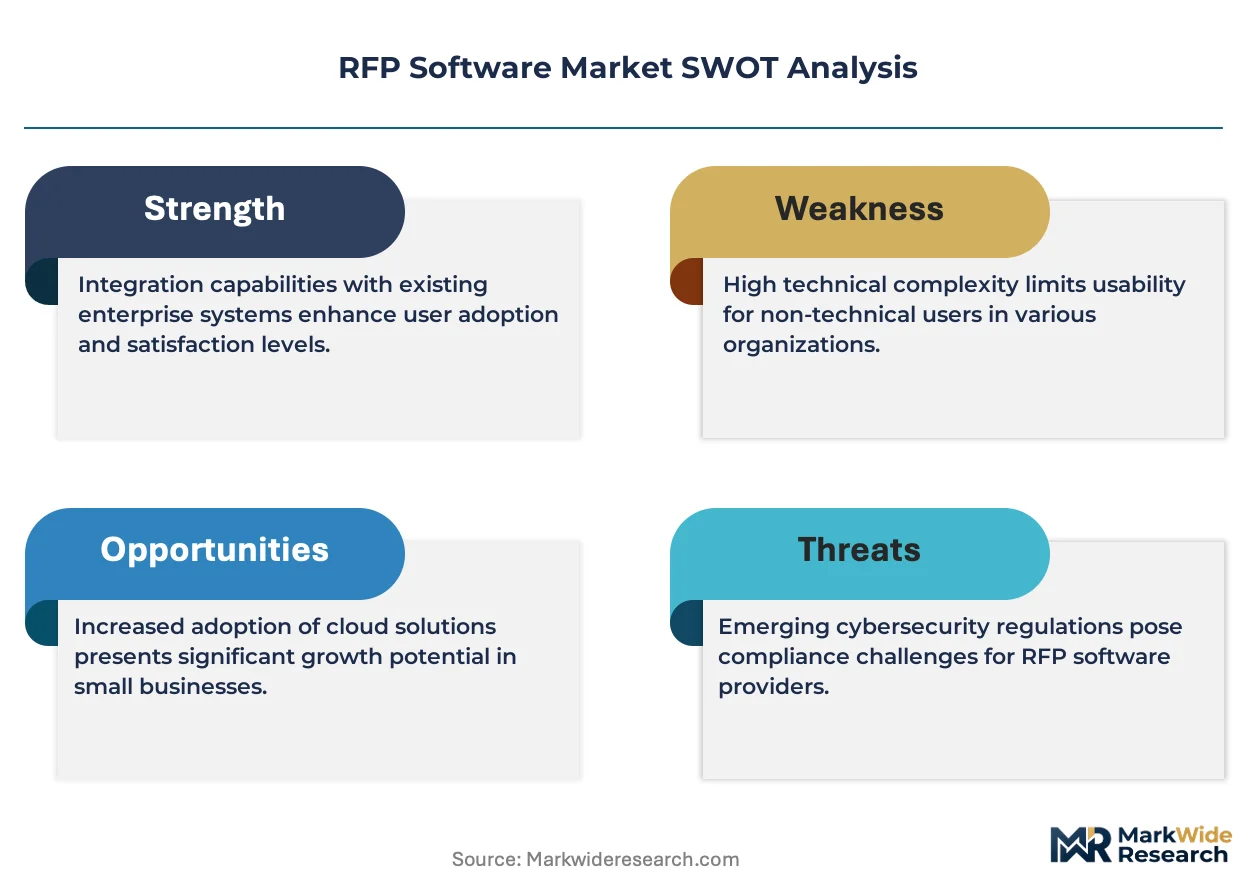
Enterprise procurement teams is bifurcating from mid-market buyers as the dominant revenue source for RFP software vendors. Responsive leverages deep workflow automation to anchor enterprise accounts with complex compliance requirements. Loopio competes through specialized content management capabilities that reduce response cycle times for high-volume proposal shops. Upland Software sustains geographic dominance across North American government contracting corridors through longstanding channel relationships.
RFP software comprises cloud-native and on-premise platforms that automate request-for-proposal creation, vendor evaluation, and contract award workflows through structured data capture, template libraries, and collaborative editing environments. These systems integrate with CRM and ERP databases to enforce procurement governance and accelerate sourcing decisions. Proposal Management applications lead segment value as organizations centralize bid response operations, while Cloud-Based deployment captures the fastest growth trajectory as IT departments retire legacy on-premise procurement infrastructure. Document Automation features command premium pricing where compliance documentation demands multi-stakeholder approval chains.
FedRAMP authorization requirements shape vendor eligibility for US federal contracts, while GDPR and EU AI Act provisions constrain cross-border data processing for European procurement platforms. The Securities and Exchange Commission's disclosure rules indirectly elevate RFP audit trail standards for publicly traded buyers. Procurement leaders must weigh vendor lock-in risks against the interoperability demands of multi-enterprise supply networks.
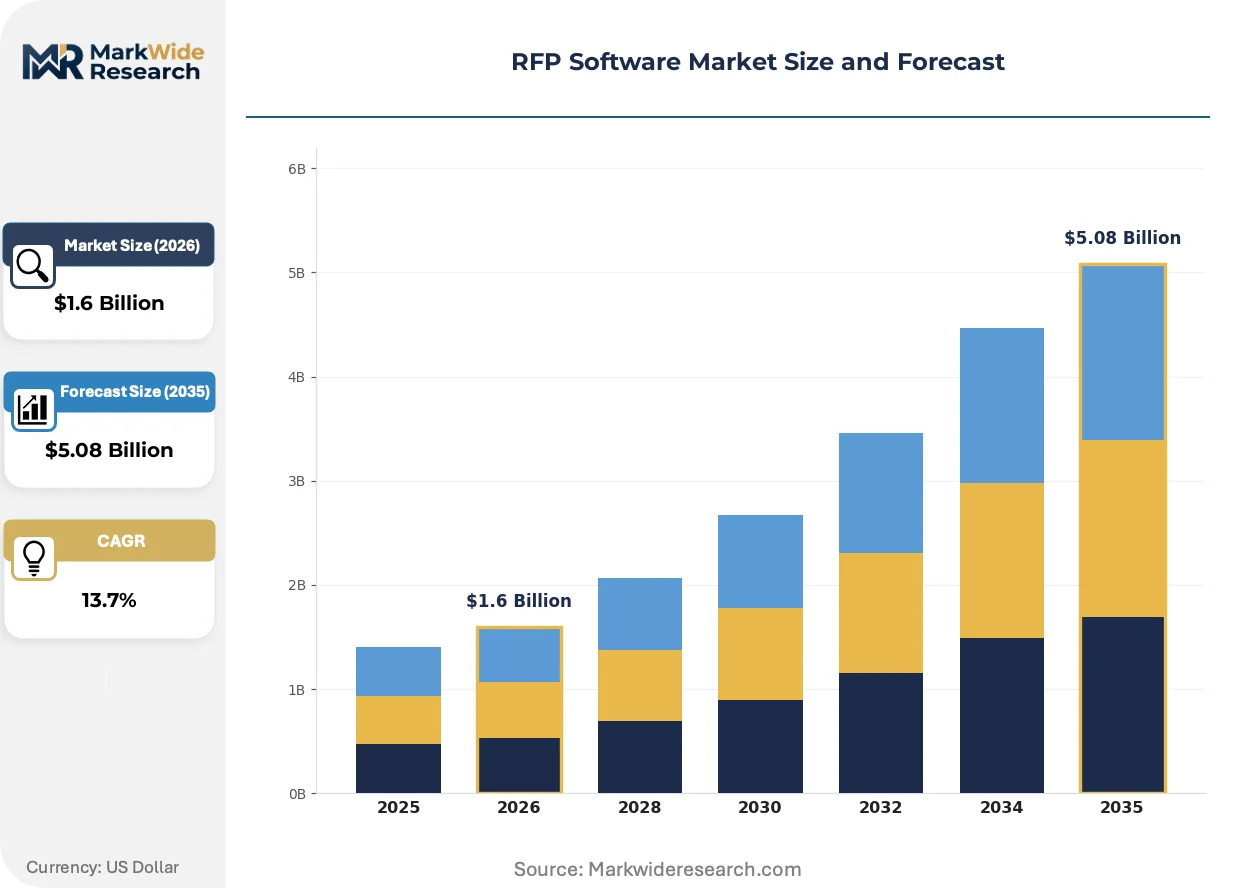
Market Dynamics
Cloud migration mandates under FedRAMP authorization requirements are compressing vendor qualification timelines while forcing procurement offices to retire legacy on-premise infrastructure, fundamentally restructuring how RFP software vendors compete for enterprise and government accounts.
Growth Catalysts
- FedRAMP Authorization:Federal agencies now require cloud service providers to demonstrate standardized security controls, creating a compliance moat that filters vendor pools and accelerates procurement digitization across civilian and defense contracting offices.
- Proposal Management Consolidation:High-volume bid response operations in professional services and IT consulting are centralizing content libraries to compress cycle times and reduce redundant drafting labor across distributed teams.
- ERP-CRM Integration:Procurement governance automation is pulling RFP platforms deeper into enterprise technology stacks, embedding sourcing workflows within existing financial and customer data environments.
Market Restraints
- Implementation Cost Burden:Multi-stakeholder approval chains for compliance documentation require substantial professional services investment, stretching payback periods for mid-market buyers with constrained IT budgets.
- Vendor Lock-in Risk:Deep workflow integration with proprietary template libraries and historical bid data creates switching friction that procurement leaders must weigh against interoperability demands of multi-enterprise supply networks.
- Cross-border Data Processing Constraints:GDPR and EU AI Act provisions limit how European procurement platforms handle vendor evaluation data, fragmenting product architectures and compliance engineering resources.
Strategic Opportunities
- AI-Assisted Response Generation:Natural language processing convergence with structured content management is opening white space for vendors to automate first-draft proposal creation while maintaining human oversight for compliance-critical sections.
- State and Local Government Digitization:Municipal procurement offices lag federal cloud adoption curves, presenting untapped demand for FedRAMP-authorized platforms with simplified deployment pathways.
- API-First Ecosystem Positioning:Modular integration architectures are enabling new channel strategies through procurement technology marketplaces and system integrator partnerships.
Industry Challenges
- Legacy System Integration Complexity:Government contracting offices maintain decades-old procurement databases that resist standard data exchange protocols, forcing custom middleware development and extended implementation timelines.
- Compliance Certification Backlogs:FedRAMP authorization queues stretch vendor qualification timelines, delaying revenue recognition and consuming technical resources that could otherwise advance product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFP Software Market |
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Proposal Management, Document Automation, Bid Management, Vendor Selection End User: Corporations, Government Agencies, Nonprofits, Educational Institutions Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Features: Collaboration Tools, Analytics, Customizable Templates, Workflow Automation |
| Companies Covered | Responsive, Loopio, Steerlab, Qvidian, PandaDoc, RFP365, Upland Software, AutoRFP.ai, Iris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFP Software Market Trends and Innovations
Generative AI capabilities are decomposing traditional proposal drafting workflows, while regulatory pressure on audit trail integrity and buyer demands for seamless interoperability are simultaneously reshaping vendor roadmaps and competitive positioning.
Natural language generation is decomposing the linear response drafting process that has dominated proposal management for two decades. Enterprise procurement teams with complex compliance requirements are adopting AI-assisted content suggestions at accelerating rates, compressing the time between RFP receipt and first submission draft from weeks to days. This decomposition is enabling high-volume proposal shops to reallocate skilled writers toward strategic messaging and win-theme development rather than repetitive boilerplate production.
The Securities and Exchange Commission's disclosure rules are indirectly elevating RFP audit trail standards for publicly traded buyers, mandating documented vendor evaluation criteria and decision rationale. Industrial consequence flows through to software requirements: procurement platforms must now embed immutable logging and multi-signature approval workflows as core features rather than optional modules. Public-sector procurement offices and regulated industries including healthcare and financial services are responding fastest, baking these capabilities into minimum viable product definitions.
Centralized procurement governance is displacing distributed purchasing authority across multi-divisional enterprises, concentrating software purchasing decisions within dedicated sourcing centers of excellence. Regional procurement hubs are replacing site-level purchasing autonomy, with North American headquarters operations dictating standardized platform selections for global affiliates. This concentration is most visible in professional services and technology sectors, where parent companies mandate unified RFP systems to enforce spend visibility and supplier performance benchmarking across operating units.
RFP Software Market Segmentation
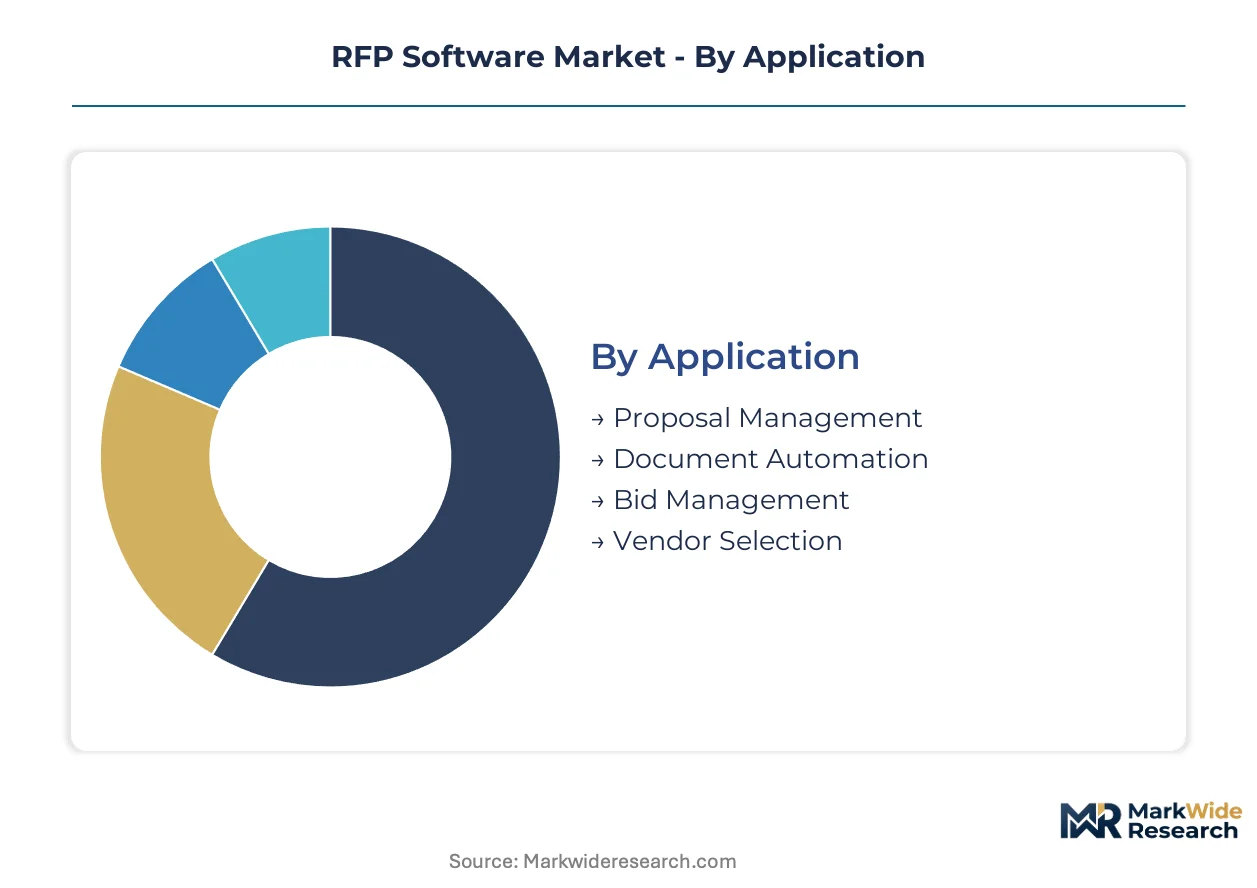
RFP software vendors configure product roadmaps and pricing architectures around distinct operational workflows. Segment boundaries reflect how procurement teams prioritize compliance automation, collaboration intensity, and integration depth within their technology stacks.
Application:
Proposal Management solutions flow through enterprise direct sales channels with substantial professional services attachment, while Document Automation and Bid Management segments reach mid-market buyers through self-serve and partner-led pathways.
- Proposal Management:Platforms centralize content libraries, response workflows, and compliance verification for high-volume bid operations. Demand concentrates in North American IT consulting and professional services firms where compressed response cycles directly correlate with revenue capture. FedRAMP authorization requirements filter vendor eligibility for federal contractors.
- Document Automation:Systems generate standardized procurement documents through template-driven assembly and clause libraries. Adoption accelerates among healthcare and financial services organizations facing SEC disclosure mandates and multi-stakeholder approval chains. Premium pricing reflects compliance-critical documentation requirements.
- Bid Management:Modules track opportunity pipelines, deadline calendars, and resource allocation across distributed response teams.
- Vendor Selection:Tools structure evaluation criteria, scoring rubrics, and finalist comparison workflows for procurement decision-makers.
By volume, Proposal Management leads. By growth pace, Document Automation is ahead.
End User:
Corporations and Government Agencies absorb the majority of vendor R&D investment, while Nonprofits and Educational Institutions access scaled-down configurations through grant-funded procurement programs and consortia purchasing agreements.
- Corporations:Multi-divisional enterprises mandate centralized procurement governance with ERP-CRM integration and spend visibility dashboards. North American headquarters operations dictate standardized platform selections for global affiliates.
- Government Agencies:Federal, state, and municipal offices require FedRAMP-authorized cloud deployments with immutable audit trails and multi-signature approval workflows. Cloud migration mandates compress vendor qualification timelines.
- Nonprofits:Organizations leverage donor-restricted funding cycles to acquire proposal management capabilities through nonprofit technology consortia.
- Educational Institutions:Universities and research institutes deploy RFP platforms for grant application management and vendor selection for capital projects.
Government Agencies command the highest per-seat pricing. Corporations deliver the largest aggregate contract values.
Deployment:
Cloud-Based deployments dominate new bookings, while On-Premise and Hybrid configurations persist in regulated environments with data residency requirements and legacy system dependencies.
- Cloud-Based:SaaS architectures enable rapid provisioning, automatic updates, and elastic scaling for variable proposal volumes. Federal agencies under FedRAMP authorization requirements drive civilian and defense contracting office adoption.
- On-Premise:Self-managed installations satisfy data sovereignty constraints and air-gapped security requirements in defense and intelligence contexts. Implementation timelines extend due to custom middleware development for legacy database integration.
- Hybrid:Configurations split sensitive data processing on-premise with collaborative workflows in cloud environments.
- Mobile:Native applications extend approval workflows and notification systems to field-based procurement officers.
Cloud-Based deployments capture the steepest expansion trajectory. On-Premise retains defensive value in classified contracting corridors.
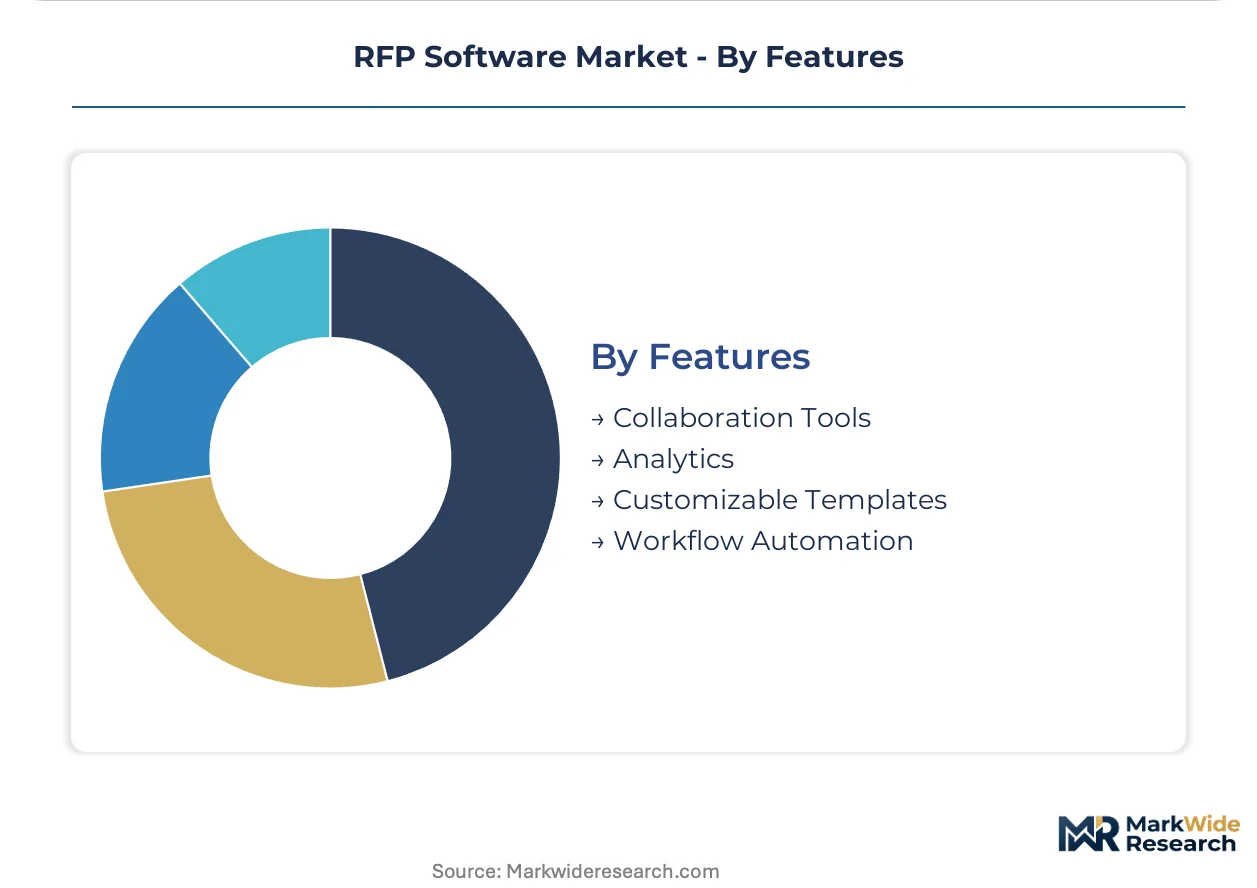
Features:
Workflow Automation and Collaboration Tools anchor premium pricing tiers, while Analytics and Customizable Templates differentiate mid-market offerings through configurable self-service capabilities.
- Workflow Automation:Engines route documents through multi-stage approval chains with conditional logic and escalation rules. Enterprise procurement teams with complex compliance requirements prioritize these capabilities for audit trail integrity.
- Collaboration Tools:Real-time editing, commenting, and version control enable distributed response teams to coordinate across time zones. High-volume proposal shops in professional services reduce redundant drafting labor.
- Analytics:Dashboards visualize win rates, response cycle times, and content reuse metrics for continuous improvement.
- Customizable Templates:Libraries accelerate document creation with pre-approved clauses and organization-specific formatting.
Workflow Automation commands the highest implementation services attach rate. Analytics features are penetrating fastest among data-mature procurement organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFP software vendors ship cloud-native platforms from United States development centers to procurement offices across Germany, United Kingdom, and Australia. Trade corridors concentrate in English-speaking enterprise markets with aligned data governance frameworks.
United States
Federal cloud migration mandates and defense contracting volume drive platform adoption. FedRAMP authorization requirements filter vendor eligibility for civilian and defense procurement offices. Washington D.C. metro corridor concentrates government technology integrators implementing compliance-heavy sourcing workflows.
Germany
Industrial manufacturing procurement centralization and automotive supplier compliance demands expand addressable market. GDPR and EU AI Act provisions constrain cross-border data processing architectures. Munich and Stuttgart industrial clusters deploy RFP automation for multi-tier supplier qualification.
United Kingdom
Professional services consolidation and post-Brexit regulatory divergence reshape procurement technology requirements. Financial Conduct Authority disclosure standards elevate audit trail expectations. London financial services and consulting corridors standardize on centralized proposal management platforms.
Australia
Public-sector procurement digitization and infrastructure investment cycles sustain demand growth. Federal government cloud-first policies accelerate SaaS adoption across state contracting offices. Sydney and Melbourne enterprise hubs centralize procurement governance for Asia-Pacific affiliate operations.
Canada
Provincial government modernization programs and federal contractor compliance requirements expand vendor opportunity. Shared Services Canada cloud procurement frameworks standardize security assessment protocols. Toronto and Ottawa technology corridors concentrate implementation demand for cross-border enterprise affiliates.
RFP Software Market Competitive Landscape
Player mix skews toward specialized SaaS vendors with workflow automation depth rather than horizontal enterprise suites. Market structure remains fragmented across application-specific niches despite consolidation pressure from adjacent procurement technology platforms. Three archetypes dominate: compliance-heavy government specialists, content-centric proposal accelerators, and integration-first platform extenders. Competitive moves concentrate on FedRAMP authorization races and API ecosystem partnerships that embed RFP capabilities into broader procurement stacks.
Within the workflow automation tier, Responsive exemplifies deep compliance integration for federal contracting requirements. Loopio occupies a position representing content management specialization that compresses response cycles for high-volume professional services operations. Upland Software anchors the geographic concentration archetype with sustained presence across North American government contracting corridors. These three vendors collectively represent the strategic positioning spectrum—compliance depth, content velocity, and channel density—that shapes competitive differentiation in procurement officer evaluations.
| Leading Market Players |
|---|
| Responsive |
| Loopio |
| Steerlab |
| Qvidian |
| PandaDoc |
| RFP365 |
| Upland Software |
| AutoRFP.ai |
| Iris |
| Others |
Pricing and Supply Chain Analysis
Ninety-day FedRAMP authorization queues compress vendor revenue recognition timelines while amplifying pricing power for compliance-ready incumbents serving federal contracting offices. This lead-time compression concentrates procurement decisions among pre-authorized vendors, reshaping how RFP software suppliers structure subscription tiers and professional services bundles.
Pricing Analysis
Cloud-native SaaS platforms command substantial premiums over legacy on-premise installations and emerging AI-assisted modules. Pricing stratifies across FedRAMP-authorized enterprise tiers, standard mid-market subscriptions, and self-serve economy offerings, with authorization status and integration depth as primary differentiation drivers. Cost compression in the mid-market intensifies as constrained IT budgets stretch payback periods for multi-stakeholder implementation projects. Government agencies exhibit the lowest price sensitivity due to mandated compliance requirements, while nonprofit and educational buyers demonstrate acute sensitivity to per-seat costs.
Supply Chain Analysis
Container availability constraints across transpacific trade lanes elevate inbound logistics costs for hardware-dependent on-premise deployments, though cloud-native SaaS delivery minimizes physical supply chain exposure. Development talent concentrates in the United States, India, and Ireland, with engineering resources feeding from technical universities and enterprise software alumni networks. Single-source vulnerability sits with hyperscaler infrastructure providers hosting authorized federal workloads. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and procurement technology marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multi-divisional enterprises mandate centralized procurement governance, reducing vendor count per account while expanding contract values for approved suppliers. This consolidation elevates the stakes of platform selection decisions and extends sales cycles.
For Market Incumbents: Shield enterprise accounts through accelerated FedRAMP Moderate and High authorization investments that filter competitor eligibility for federal revenue pools. Deepen API ecosystem partnerships with ERP and CRM incumbents to embed RFP workflows within existing procurement technology stacks, raising switching costs against emerging AI-native entrants.
For New Entrants and Emerging Players: FedRAMP authorization fast-tracks through agency sponsorship programs open wedge opportunities in state and local government corridors lagging federal cloud adoption curves. Target municipal procurement offices with simplified deployment pathways and pre-configured compliance templates. Lead with AI-assisted response generation capabilities that compress first-draft timelines for professional services buyers underserved by legacy content management architectures.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-moat play because regulatory authorization requirements compound competitive advantage for early movers while fragmenting addressable market access for late entrants. Acquisition targets should display FedRAMP authorization progress, sticky enterprise renewal rates above industry benchmarks, and API-first architectures enabling platform extension. The signal to watch is state government cloud procurement framework adoption velocity as a leading indicator of municipal market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Filters vendor eligibility for federal contracting revenue pools under civilian and defense procurement mandates. |
| API-First Platform Integration | Embeds RFP workflows within Salesforce and SAP environments to enforce procurement governance automation. |
| AI-Assisted Response Generation | Compresses proposal drafting cycles from weeks to days for high-volume professional services bid shops. |
| State Government Channel Expansion | Captures municipal digitization demand through simplified deployment pathways and consortia purchasing agreements. |
| Content Library Consolidation | Centralizes compliance-verified clauses to reduce redundant drafting labor across distributed response teams. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with procurement technology officers, federal contracting specialists, and enterprise IT directors, alongside secondary validation through FedRAMP authorization databases, SEC disclosure filings, and government procurement spending records. Primary fieldwork captured workflow automation requirements, compliance verification pain points, and platform switching cost perceptions. Secondary sources encompassed hyperscaler partnership announcements, ERP integration documentation, and public-sector digitization policy directives. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the analysis window, the forecasting framework modeled deployment mode transitions, organization size tier migration patterns, and vertical adoption intensity variations. Segmentation dimensions encompassed application type, end-user industry, cloud migration stage, and integration complexity tier. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against historical SaaS expansion benchmarks and public-sector technology refresh cycles.
Underlying assumptions cover sustained federal cloud migration mandates and stable hyperscaler infrastructure pricing, with deviation risk concentrated in compliance certification backlog extensions and cross-border data processing regulatory shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time Tracking Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Big Data Software Market
Software & Services
Data Integration Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Construction Suites Software Market
Software & Services
Dental Practice Management Software Market
Software & Services
Global Forestry Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Commissioning Software Market
Software & Services
Global SEO Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Indonesia IT Services Market
Software & Services
GCC Human Capital Management Software Market