
 Global Open Source Services Market | 2026-2036
Global Open Source Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Open Source Services Market Foresight
Healthcare and financial services is rebalancing toward cloud-native open source platforms as compliance costs for proprietary software escalate. Red Hat, Inc. anchors enterprise Linux subscriptions across North American hospital networks. IBM Corporation leverages its hybrid cloud portfolio to capture multi-year managed service contracts. Oracle Corporation competes through MySQL and Java support revenue tied to legacy modernization budgets.
Open source services encompass professional consulting, implementation, training, and ongoing support for software distributed under licenses permitting source code access, modification, and redistribution, typically governed by foundations such as Apache or Linux Foundation with contribution agreements and trademark policies. These services reduce vendor lock-in while enabling customization of kernel-level code for workload-specific performance tuning. Consulting and implementation services command premium pricing due to scarcity of certified architects in Kubernetes and OpenShift ecosystems. Cloud-based deployment models are outpacing on-premise installations as hyperscaler marketplaces integrate open source billing. Large enterprises represent the deepest margin pool, though SME demand is accelerating through managed platform-as-a-service offerings.
The EU AI Act mandates algorithmic transparency for high-risk applications, directly benefiting auditable open source machine learning frameworks. HIPAA in the United States imposes audit trail requirements that open source databases with community-verified encryption modules satisfy more readily than black-box alternatives. ISO/IEC 5230 on open source compliance is becoming a procurement gate for Fortune 500 vendor qualification. Stakeholders must evaluate whether their support contracts cover security patch velocity adequate for regulatory disclosure timelines.
Market Dynamics
Compliance mandates from the EU AI Act and HIPAA are forcing enterprises to abandon proprietary black-box systems in favor of auditable open source infrastructure with transparent supply chains and community-verified security modules.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:High-risk AI applications in German automotive and French healthcare sectors now require inspectable code bases, accelerating migration from closed-source machine learning platforms.
- Financial services core banking modernization:North American and European banks are replacing legacy mainframe architectures with open source distributed systems to reduce vendor lock-in and enable workload-specific kernel tuning.
- ISO/IEC 5230 procurement gate:Fortune 500 vendor qualification processes now require documented open source compliance, creating pull-through demand for certified professional services and managed support contracts.
Market Restraints
- Certified architect scarcity:Kubernetes and OpenShift ecosystems face acute talent shortages, inflating consulting rates and extending implementation timelines for enterprise deployments.
- Security patch velocity gaps:Community-driven disclosure timelines often lag regulatory requirements from HIPAA and GDPR, exposing enterprises to audit trail deficiencies during incident response.
- Legacy integration friction:Cobol and mainframe-dependent institutions in Japan and the United States face prohibitive refactoring costs when connecting open source middleware to decades-old transactional systems.
Strategic Opportunities
- Indian SME platform-as-a-service penetration:Managed open source offerings from domestic cloud providers are capturing mid-market demand previously excluded from enterprise-grade support contracts.
- Edge computing convergence with 5G:Telecommunications operators in South Korea and Germany are deploying containerized open source stacks at cell tower sites, creating new service revenue streams for systems integrators.
- US IRA clean energy incentives:Grid modernization grants are funding open source energy management system deployments, requiring specialized implementation services for utility-scale battery and solar installations.
Industry Challenges
- Contributor agreement complexity:Apache Foundation and Linux Foundation trademark policies create legal review bottlenecks, delaying product launches and complicating multi-license compliance for commercial distributions.
- Cloud marketplace billing fragmentation:Hyperscaler integration of open source consumption metrics remains inconsistent across AWS, Azure, and Google Cloud, forcing service providers to maintain parallel invoicing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Open Source Services Market |
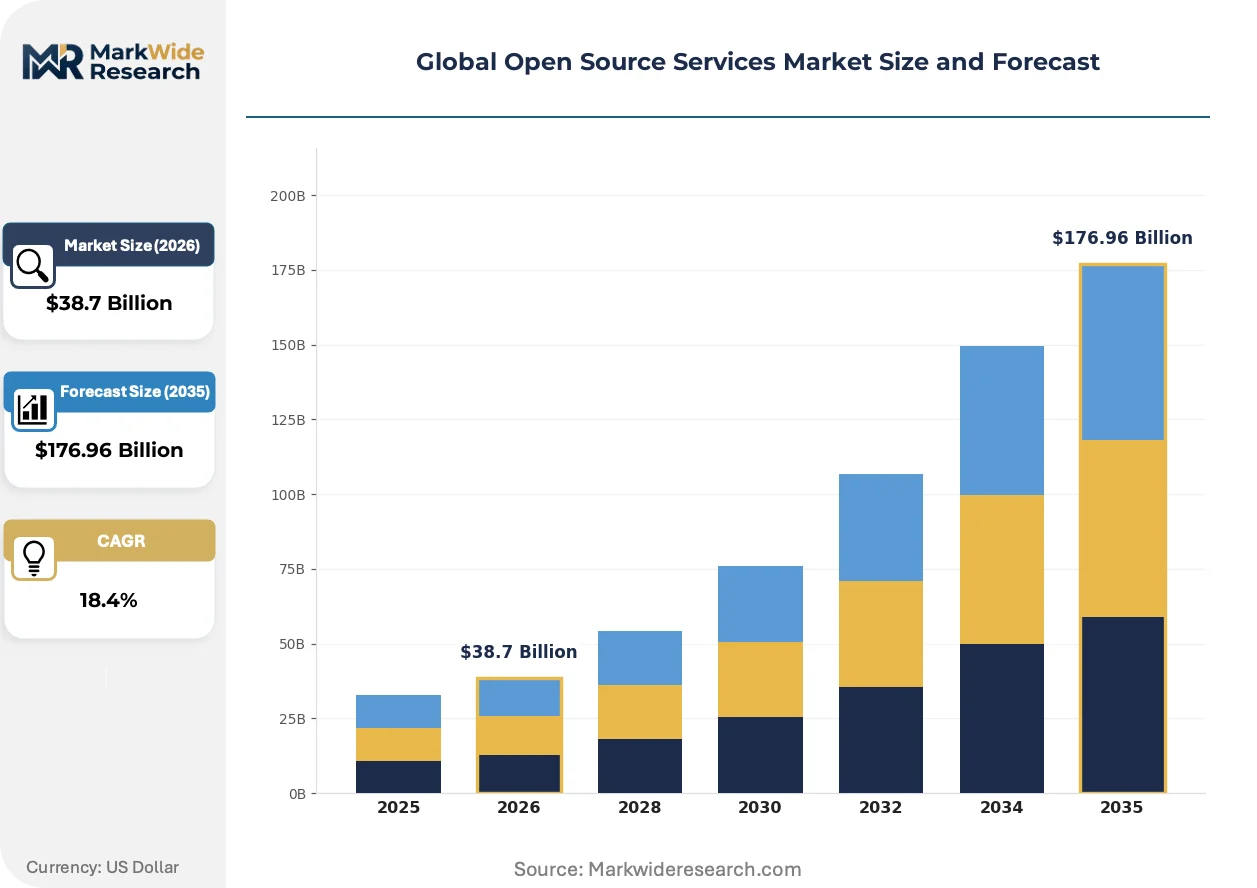
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Training, Support Deployment Model: On-Premise, Cloud-Based, Hybrid, Others End User: SMEs, Large Enterprises, Government, Non-Profits Industry Vertical: IT, Education, Healthcare, Financial Services |
| Companies Covered | IBM Corporation, Red Hat, Inc., Oracle Corporation, Accenture Plc., Cisco Systems, Inc., SUSE, Wipro Limited, Infosys Limited, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Open Source Services Market Shifts & Advancements
Software supply chain transparency is rewriting competitive positioning across enterprise procurement, with automated vulnerability scanning and SBOM generation becoming baseline requirements rather than differentiators.
WebAssembly is rewriting how edge workloads execute across heterogeneous hardware. Industrial automation OEMs in Germany and Japan are adopting Wasm runtimes for portable, sandboxed code deployment on factory floor controllers. This compression of deployment friction is eroding the advantage of vertically integrated proprietary runtime stacks.
The EU AI Act's risk classification framework is triggering mandatory algorithmic impact assessments for high-risk applications. Healthcare providers in France and the Netherlands are prioritizing open source machine learning frameworks with documented training data lineage. Medical device manufacturers are restructuring product roadmaps to accommodate CE marking requirements for transparent decision logic.
Enterprise buyers are unbundling support contracts from software licenses, purchasing professional services directly from specialized consultancies rather than through primary vendors. This disintermediation is most pronounced in US financial services, where procurement teams are negotiating multi-year managed service agreements with boutique Kubernetes specialists independent of distribution partnerships.
Global Open Source Services Market Segmentation
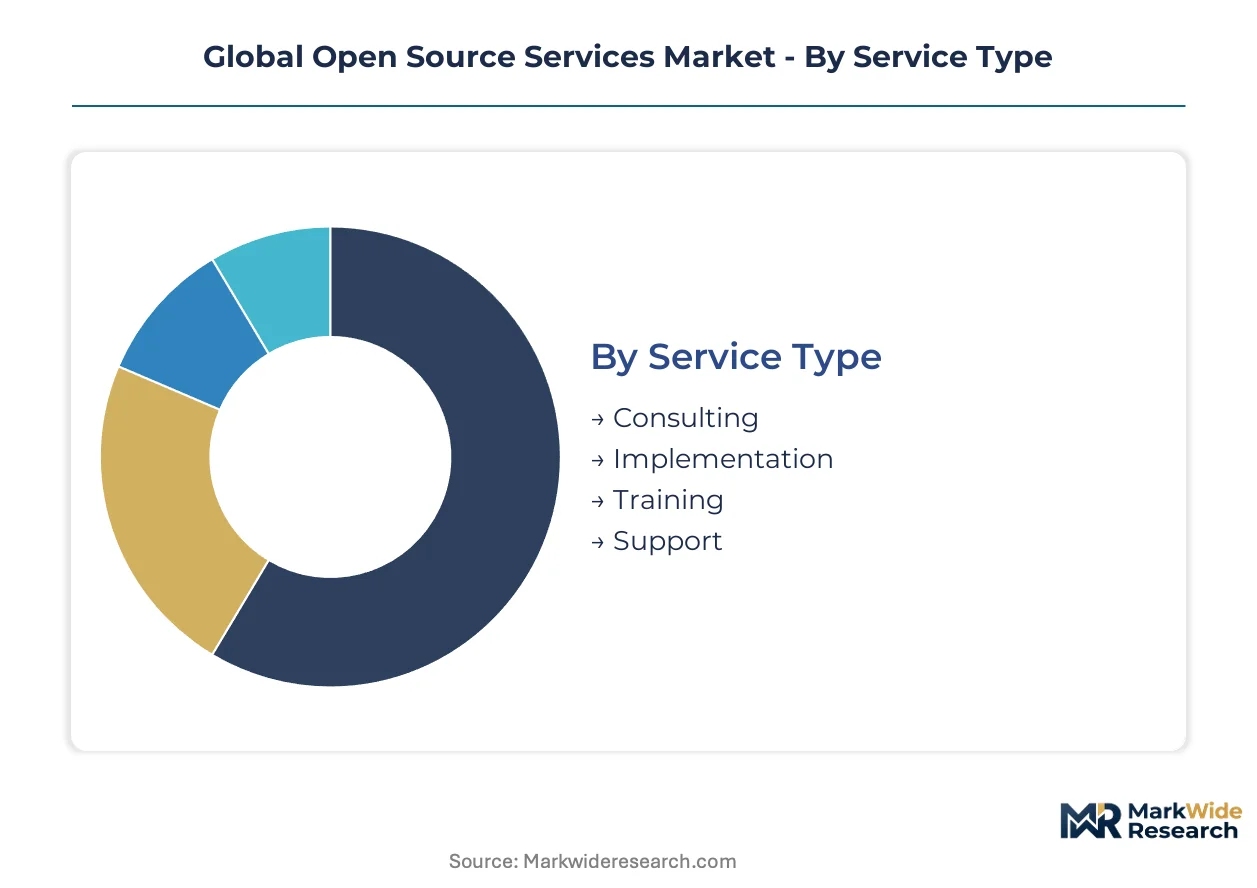
Segmentation in open source services reveals distinct procurement patterns across buyer sophistication levels. Enterprises prioritize certified support contracts for compliance-heavy workloads, while mid-market adopters favor consumption-based managed platforms. Understanding these fault lines enables service providers to align talent deployment and pricing architecture with actual buyer willingness-to-pay.
Service Type:
Buyers differentiate primarily by internal capability depth—organizations with mature DevOps teams purchase discrete consulting blocks, while capability-constrained firms demand full-lifecycle managed services.
- Consulting:Architecture design and migration planning for Kubernetes and OpenShift ecosystems. German automotive OEMs and French healthcare networks drive premium demand as EU AI Act compliance deadlines compress procurement timelines.
- Implementation:Hands-on deployment, configuration, and integration with legacy transactional systems. North American financial institutions dominate contract value, replacing mainframe middleware with distributed open source stacks to satisfy HIPAA audit trail requirements.
- Training:Certification programs and workforce upskilling for scarce technologies. Indian IT services firms and Brazilian system integrators represent expanding demand as nearshore delivery models mature.
- Support:Ongoing maintenance, security patching, and SLA-backed incident response. Enterprise subscriptions anchor vendor revenue, though SME penetration accelerates through platform-as-a-service bundling.
Volume sits with Support; growth tilts toward Consulting.
Deployment Model:
Deployment choice tracks data sovereignty requirements and latency sensitivity—regulated industries retain on-premise control for patient and transaction records, while digital-native workloads migrate to consumption-metered cloud instances.
- On-Premise:Air-gapped installations in defense, classified government, and critical infrastructure facilities. Japanese manufacturing conglomerates and Saudi petrochemical operators maintain captive data centers for intellectual property protection.
- Cloud-Based:Hyperscaler-managed open source distributions with integrated billing and auto-scaling. South Korean telecommunications operators and Australian healthcare providers lead migration as ISO/IEC 5230 procurement gates harden.
- Hybrid:Orchestrated workloads spanning private data centers and public cloud burst capacity. Swiss banking networks and Canadian energy utilities adopt this architecture to satisfy GDPR and domestic privacy law fragmentation.
- Others:Edge-deployed container runtimes and WebAssembly-based factory floor controllers. German industrial automation OEMs pilot these configurations for 5G-connected manufacturing cells.
Hybrid deployments command the highest service attach rates; cloud-based configurations are climbing fastest as marketplace billing standardizes.
End User:
End user segmentation reflects contract scale and procurement sophistication—large enterprises negotiate multi-year managed service agreements, while SMEs access capabilities through consumption-priced platforms previously gated by minimum commitments.
- SMEs:Mid-market firms purchasing through domestic cloud provider marketplaces in India and Southeast Asia. Managed platform-as-a-service offerings eliminate certified architect hiring requirements.
- Large Enterprises:Fortune 500 institutions with dedicated open source program offices and compliance teams. US financial services and German automotive sectors represent the deepest contract value pools.
- Government:National and sub-national agencies mandating auditable supply chains. EU member state healthcare authorities and US federal civilian agencies prioritize SBOM generation and vulnerability disclosure velocity.
- Non-Profits:Research institutions and humanitarian organizations with grant-funded infrastructure. Academic medical centers in the Netherlands and public health NGOs in East Africa leverage foundation-subsidized support tiers.
Large Enterprises generate the majority of current revenue; SME expansion offers the steepest trajectory as managed platforms democratize access.
Industry Vertical:
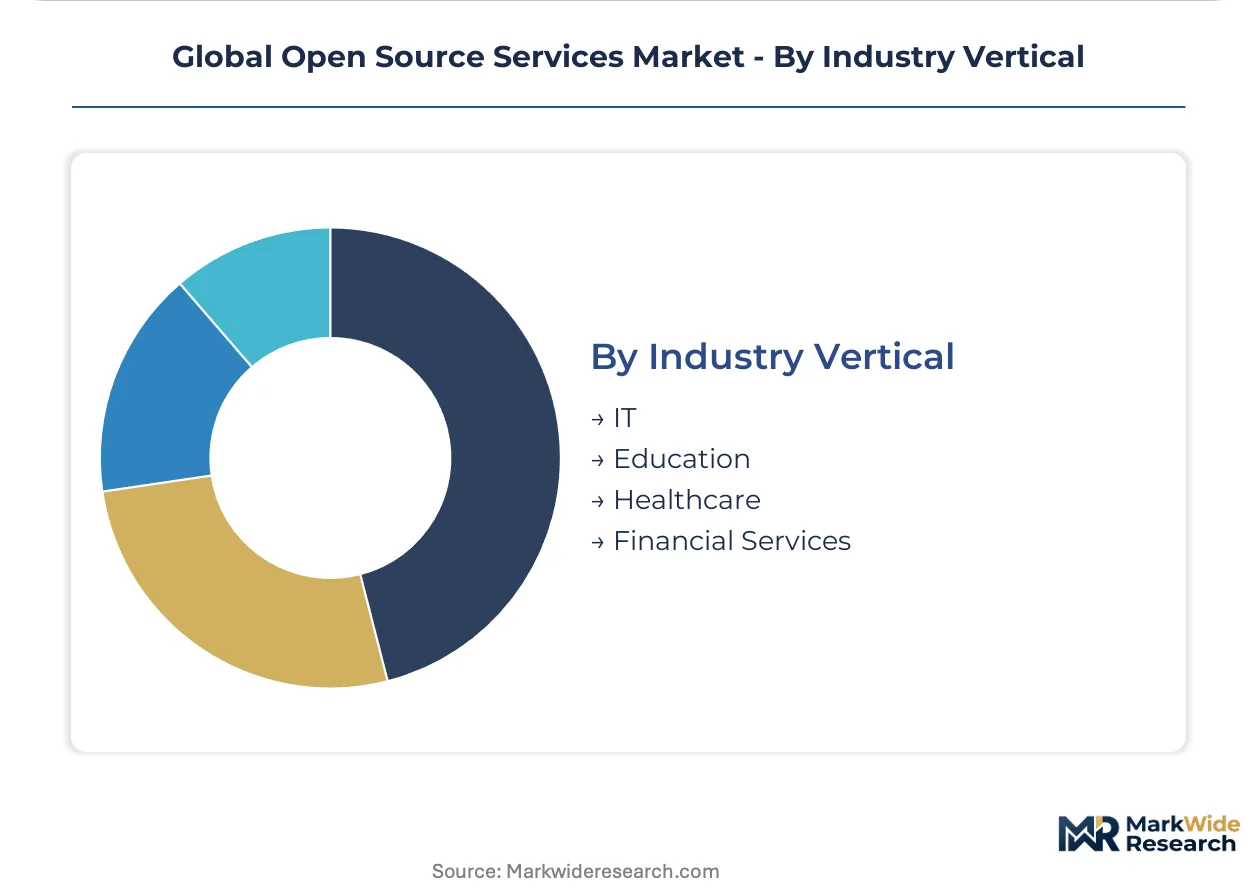
Vertical specialization determines regulatory exposure and therefore support contract pricing—healthcare and financial services pay premiums for HIPAA and GDPR-aligned security patching velocity, while education and general IT accept standard SLAs.
- IT:Technology vendors and digital service providers consuming open source as foundational infrastructure. This segment exhibits the highest internal expertise and therefore the lowest services attach rate.
- Education:Universities and research consortia with permissive licensing cultures and limited procurement budgets. European higher education networks and US land-grant institutions drive demand for foundation-subsidized training and community support tiers.
- Healthcare:Hospital networks, medical device manufacturers, and pharmaceutical firms facing HIPAA and EU MDR compliance burdens. French and Dutch providers prioritize machine learning frameworks with documented training data lineage for high-risk diagnostic applications.
- Financial Services:Banks, insurers, and payment processors modernizing core banking platforms. North American institutions lead legacy mainframe replacement, while EU firms accelerate under ECB supervisory pressure for operational resilience.
Financial Services concentrates the highest contract values; Healthcare is expanding most quickly as CE marking and FDA premarket requirements harden algorithmic transparency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Germany are concentrating open source services investment through tax incentives and infrastructure subsidies. These zones attract hyperscaler partnerships and systems integrators seeking proximity to automotive and financial services clusters. Regulatory pressure from the EU AI Act and HIPAA compliance timelines is accelerating migration patterns.
United States
Financial services modernization in New York and Chicago drives premium consulting demand for core banking platform replacements. HIPAA audit trail requirements push hospital networks toward auditable open source databases with community-verified encryption. The Dallas-Fort Worth metroplex hosts expanding data center capacity for hybrid cloud deployments serving energy and telecommunications sectors.
Germany
Industrial automation OEMs in Stuttgart and Munich migrate legacy control systems to containerized open source architectures. The EU AI Act mandates algorithmic transparency for high-risk automotive applications, compelling inspectable machine learning frameworks. Bavaria's manufacturing corridor pilots WebAssembly runtimes for 5G-connected factory floor controllers.
India
Domestic cloud providers in Bangalore and Hyderabad capture mid-market SME demand through managed platform-as-a-service offerings. The country's special economic zones offer tax holidays for open source support centers serving European and North American clients. Maharashtra's IT corridor concentrates certified Kubernetes architect training programs for nearshore delivery models.
France
Healthcare providers in Paris and Lyon prioritize open source machine learning frameworks with documented training data lineage for diagnostic applications. ANSM and CNIL guidance on algorithmic accountability reinforces procurement preferences for transparent code bases. The Île-de-France region hosts specialized consultancies serving medical device manufacturers restructuring product roadmaps for CE marking compliance.
South Korea
Telecommunications operators deploy containerized open source stacks at cell tower sites for 5G edge computing convergence. MFDS digital health regulations create demand for auditable software supply chains in Seoul's medical device cluster. The Busan-Ulsan industrial zone experiments with WebAssembly-based runtime deployment for smart manufacturing cells.
Global Open Source Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated enterprise Linux subscriptions anchoring vendor revenue while implementation services fragment across regional consultancies. The market exhibits tiered concentration: hyperscaler-affiliated distributions capture volume, boutique Kubernetes specialists command premium rates, and Indian IT services firms scale through managed platform offerings. Strategic moves center on multi-year managed service contract capture and certified architect talent acquisition.
Within the enterprise distribution tier, IBM Corporation, Red Hat, Inc., and Oracle Corporation exemplify contrasting archetypes. IBM Corporation leverages hybrid cloud portfolio breadth to anchor multi-year agreements. Red Hat, Inc. sits within the certified subscription model, capturing recurring revenue from compliance-heavy workloads. Oracle Corporation occupies a position tied to legacy modernization budgets through MySQL and Java support streams.
| Leading Market Players |
|---|
| IBM Corporation |
| Red Hat, Inc. |
| Oracle Corporation |
| Accenture Plc. |
| Cisco Systems, Inc. |
| SUSE |
| Wipro Limited |
| Infosys Limited |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Fortune 500 procurement offices concentrate contract value for certified open source support, anchoring a subscription-dominant pricing model that rewards compliance documentation and penalizes velocity gaps. This buyer archetype's risk-averse sourcing patterns feed into supply chain choices favoring established distributions with proven security patch cadences.
Pricing Analysis
Lead-time-driven pricing premiums attach to expedited Kubernetes architect deployment for EU AI Act compliance deadlines, while spot consulting capacity trades at discounts during non-peak procurement windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and SLA response velocity. Cost compression in economy-tier training services is intensifying because Indian IT services firms scale nearshore delivery models. SMEs exhibit the highest price sensitivity, while German automotive OEMs accept premium rates for documented supply chain transparency.
Supply Chain Analysis
Single-source vulnerability sits with Red Hat's enterprise Linux subscription channel for North American hospital networks, creating concentration risk in compliance-critical healthcare deployments. Talent pipelines for certified Kubernetes architects draw from India, Germany, and the United States, with Maharashtra's training corridors feeding nearshore delivery models. Supply chain risk centers on acute certified architect scarcity extending implementation timelines. Distribution runs through hyperscaler marketplaces with fragmented billing integration across AWS, Azure, and Google Cloud.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The open source services market functions as a cost-of-compliance story where ISO/IEC 5230 procurement gates erect barrier-to-entry moats favoring certified incumbents with documented security patch velocity.
For Market Incumbents: Extend multi-year managed service contract capture into French healthcare networks facing ANSM algorithmic accountability deadlines. Deepen upstream control over certified architect training pipelines in Bangalore and Hyderabad to defend against boutique Kubernetes specialists eroding margin in premium consulting tiers. For New Entrants and Emerging Players: The price-point gap between premium enterprise subscriptions and economy-tier SME platforms offers white-space entry through managed platform-as-a-service bundling. Target Indian mid-market firms previously excluded from enterprise support contracts, leveraging domestic cloud provider marketplace integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional consultancies with ISO/IEC 5230 compliance practices in Germany and France. Long-term viability hinges on regulatory tailwinds from EU AI Act enforcement expanding auditable infrastructure mandates. Watch security patch velocity disclosure requirements as the inflection signal separating acquisition-ready targets from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Architect Talent Acquisition | Secures premium consulting rates for EU AI Act compliance deadlines in Stuttgart automotive clusters. |
| Multi-Year Managed Service Contract Capture | Locks recurring revenue from HIPAA-bound hospital networks in Dallas-Fort Worth metroplex. |
| Hyperscaler Marketplace Integration | Standardizes consumption billing for South Korean telecommunications edge deployments. |
| ISO/IEC 5230 Compliance Investment | Qualifies vendors for Fortune 500 procurement gates in financial services modernization. |
| Nearshore Delivery Model Expansion | Scales economy-tier platform access for Indian SME demand through Bangalore cloud providers. |
Research Methodology
Independent corroboration across primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners, plus secondary validation through SEC filings, hyperscaler capex disclosures, and open source foundation contribution reports, underwrites the qualitative findings. Bottom-up service provider revenue estimates triangulate against top-down enterprise IT spending allocations across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across deployment model, organization size, vertical, and regional adoption pattern dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation with macro IT services spending trajectories. Forecast inputs incorporate EU AI Act implementation timelines and HIPAA audit trail requirement evolution.
Underlying measurement precision varies by segment; large enterprise support contracts carry tighter precision than fragmented SME platform consumption. Forecasts reflect assumptions about regulatory enforcement velocity and certified architect supply expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Indonesia IT Services Market
Software & Services
Content Curation Software Market
Software & Services
Europe Business Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Global Intranet Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Voting Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Ipad POS Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
API Testing Market
Software & Services
Theatrical Distribution Software Market