
 Europe Human Resource (HR) Technology Market | 2026-2036
Europe Human Resource (HR) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Human Resource (HR) Technology Market Intelligence
Artificial intelligence is expanding its footprint across core HR workflows, displacing manual resume screening and static performance reviews with predictive analytics engines. HiBob leverages native payroll automation to anchor its position among scaling mid-market employers. Randstad competes through workforce data integration that connects temporary staffing pools with client ERP systems. Workhuman specializes in peer-to-peer recognition architectures that sustain engagement metrics across distributed teams.
Europe Human Resource Technology encompasses software platforms, analytics tools, and service layers that automate employee lifecycle management from recruitment through offboarding, typically operating through API-connected cloud architectures with SOC 2 Type II and ISO 27001 security protocols. The primary commercial purpose is reducing administrative overhead while improving workforce planning accuracy and regulatory compliance documentation. Recruitment Software and Talent Management segments lead current spending as skills shortages intensify across technical and healthcare occupations. Cloud-Based and SaaS deployment models capture the fastest expansion as legacy on-premises installations face migration pressure from cybersecurity mandates and remote-work infrastructure requirements.
GDPR enforcement by national data protection authorities across France, Germany, and Ireland directly shapes platform architecture requirements for cross-border employee data transfers. The EU AI Act classification of high-risk automated decision systems imposes conformity obligations on algorithmic hiring and performance evaluation tools. Stakeholders must monitor evolving supervisory guidance on automated profiling in employment contexts to anticipate compliance redesign cycles.
Market Dynamics
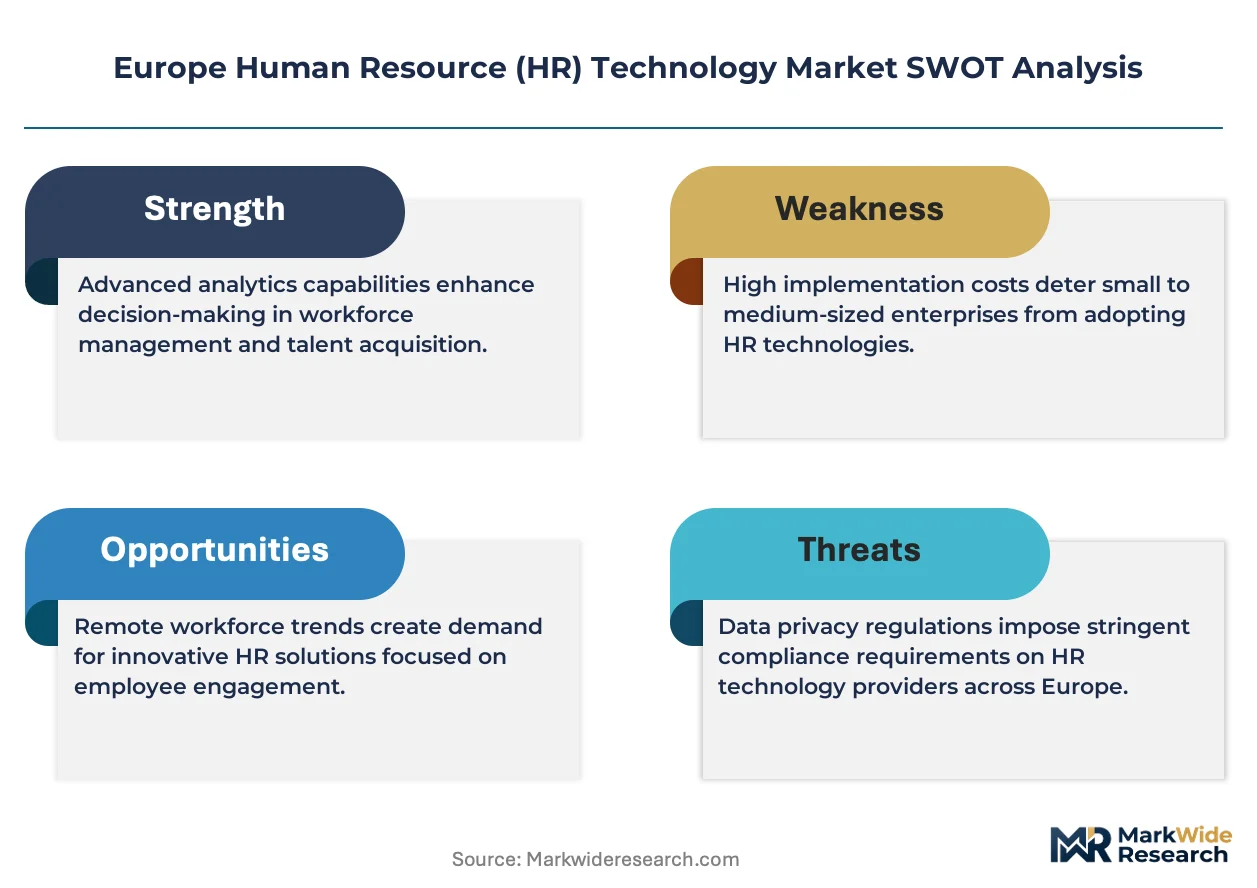
EU AI Act compliance deadlines and GDPR cross-border data transfer rulings are forcing HR technology vendors to rebuild platform architectures around explainable algorithms and sovereign cloud hosting, compressing product development cycles while opening procurement windows for compliant substitutes.
Growth Catalysts
- GDPR Article 49 derogations:German automotive manufacturers are accelerating investment in workforce analytics platforms that automate compliance documentation for international employee data transfers to non-adequate jurisdictions.
- Skills verification protocols:France's precision engineering sector demands integrated talent management systems that map competency matrices against production line automation roadmaps.
- Netherlands remote-work infrastructure:Mid-sized employers across Amsterdam-Rotterdam corridor prioritize API-connected payroll and benefits administration for distributed technical teams.
Market Restraints
- Algorithmic audit costs:EU AI Act conformity assessments for high-risk automated hiring systems impose six-figure certification burdens that freeze procurement decisions at sub-500 employee firms.
- Cloud concentration risk:Three hyperscale providers dominate sovereign hosting capacity in Frankfurt and Dublin, creating single-point-of-failure exposure for workforce data lakes.
- Legacy ERP entrenchment:SAP and Oracle on-premises installations in German industrial Mittelstand resist cloud migration due to customized shop-floor integration layers.
Strategic Opportunities
- Poland and Czech Republic expansion:Nearshoring of shared service centers by German and Austrian manufacturers creates demand for multilingual payroll automation and cross-border tax compliance modules.
- ESG reporting convergence:CSRD workforce disclosure mandates enable vendors to bundle carbon footprint tracking with employee commuting and remote-work energy consumption analytics.
- Edge-AI + blockchain verification:Converging technologies support decentralized credential verification for gig economy platforms serving Benelux logistics and last-mile delivery networks.
Industry Challenges
- Explainable AI engineering scarcity:Vendors struggle to recruit machine learning specialists capable of building interpretable models that satisfy French CNIL and German DPA audit requirements for automated performance scoring.
- ISO 27001 certification backlogs:Three-month assessment queues at accredited bodies delay go-live dates for SOC 2 Type II dependent procurement contracts.
- Interoperability fragmentation:Absence of unified API standards forces custom integration work for each client ERP and time-tracking system, eroding SaaS margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Human Resource (HR) Technology Market |
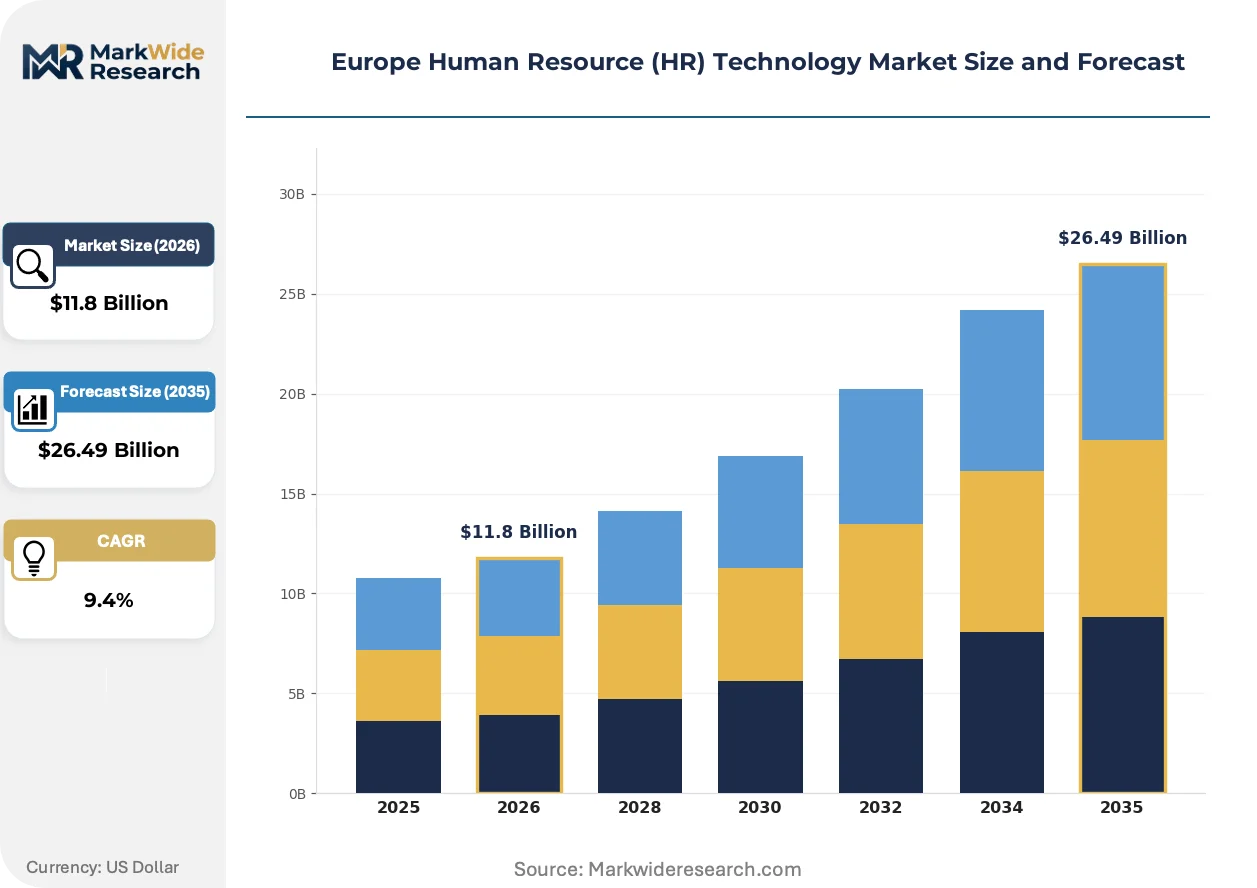
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recruitment Software, Payroll Systems, Performance Management, Talent Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Large Enterprises, Small and Medium Enterprises, Staffing Agencies, Freelancers Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | HiBob, Adecco, Leapsome, Randstad, Hays, Ashby, Workhuman, Humaans, Pirical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Human Resource (HR) Technology Market Strategic Shifts & Innovations
Workforce management technology is pivoting from centralized HRIS monoliths toward modular, API-first architectures that embed compliance automation directly into operational workflows. This structural shift rewards vendors who can deliver sovereign-cloud deployment with pre-certified regulatory mappings.
Embedded payroll engines are decentralizing compensation administration by pushing real-time calculation and tax filing capabilities to the edge of organizational networks. Mid-market manufacturers in Baden-Württemberg and Bavaria are adopting these modules to bypass shared service center bottlenecks. The technology is decentralizing control over wage compliance from headquarters HR functions to plant-level operations managers who require instant visibility into overtime and shift premium calculations.
EU AI Act risk classification rules are reshaping vendor product roadmaps by mandating human-in-the-loop overrides for algorithmic hiring and promotion recommendations. Industrial software providers must now maintain conformity documentation repositories that trace training data provenance and model drift metrics. German automotive and French aerospace contractors face the steepest compliance redesign cycles as their high-volume recruitment pipelines fall under high-risk system definitions.
Subscription fatigue among HR buyers is compressing vendor evaluation cycles and elevating preference for usage-based pricing tied to active employee counts rather than annual contracts. Dutch professional services firms and Belgian healthcare operators are piloting modular procurement that unbundles recruitment, performance management, and offboarding into separate best-of-breed purchases. This pattern is most visible in the Netherlands, where mid-sized employers have migrated fastest from single-suite legacy platforms to composable HR stacks.
Europe Human Resource (HR) Technology Market Segmentation
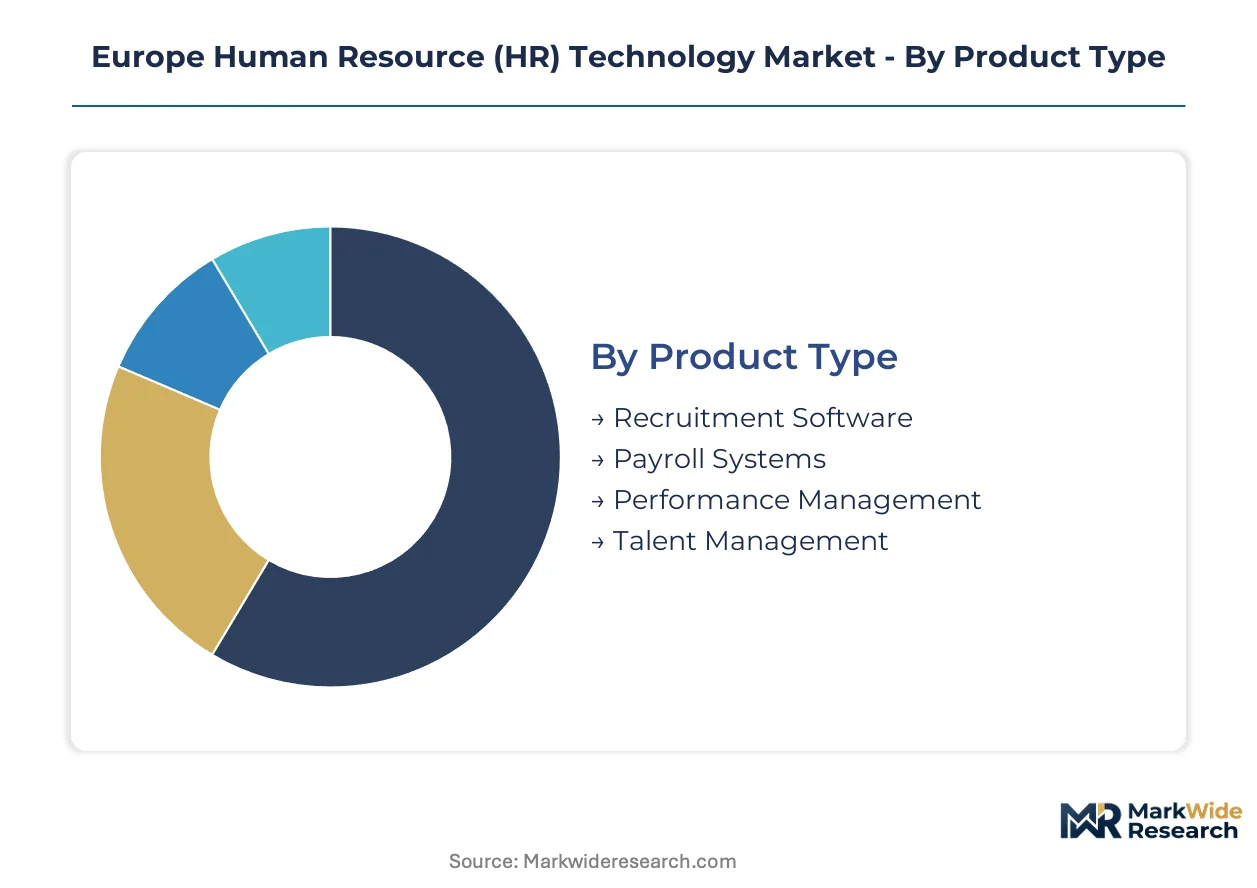
Segmentation reveals how procurement patterns diverge across buyer archetypes in Europe's HR technology landscape. Deployment preferences and service bundling strategies vary sharply between Germany's industrial Mittelstand and Netherlands-based professional services firms.
Product Type:
Supply concentrates in integrated suites that bundle recruitment, payroll, and talent modules under single vendor relationships.
- Recruitment Software:Applicant tracking systems with AI-powered candidate matching and GDPR-compliant data handling pipelines. German automotive manufacturers in Baden-Württemberg drive demand for high-volume screening tools that integrate with SAP ERP environments. EU AI Act risk classifications push vendors toward explainable matching algorithms with human-in-the-loop overrides.
- Talent Management:Competency mapping platforms that align workforce capabilities against production automation roadmaps. France's precision engineering sector in Auvergne-Rhône-Alpes prioritizes skills verification protocols tied to CNC programming and robotics maintenance certifications.
- Payroll Systems:Real-time calculation engines with multi-jurisdiction tax compliance for cross-border workforces.
- Performance Management:Continuous feedback architectures replacing annual review cycles with peer recognition and goal-tracking modules.
Today's leader: Recruitment Software. Tomorrow's challenger: Talent Management.
Deployment Model:
Cost tier differentiation separates premium sovereign-cloud deployments from economy-grade public SaaS offerings.
- Cloud-Based:Scalable infrastructure with SOC 2 Type II certification and EU data residency guarantees. Netherlands mid-sized employers across the Amsterdam-Rotterdam corridor adopt these for distributed technical teams requiring instant payroll access.
- SaaS:Subscription models with usage-based pricing tied to active employee counts. Belgian healthcare operators pilot modular procurement that unbundles core functions into separate best-of-breed purchases.
- Hybrid:Mixed architectures preserving sensitive payroll data on-premises while pushing recruitment workflows to cloud.
- On-Premises:Legacy installations resisting migration due to customized shop-floor integration layers in German industrial clusters.
Cloud-Based deployments hold current volume leadership. SaaS models are climbing the fastest as subscription fatigue compresses evaluation cycles.
End User:
Application requirements diverge between centralized HR functions and distributed operational managers seeking edge-level control.
- Large Enterprises:Multi-country implementations with complex Works Council consultation requirements across German, French, and Belgian operations. These buyers demand API ecosystems connecting workforce analytics to carbon footprint tracking for CSRD compliance.
- Small and Medium Enterprises:Mid-market manufacturers prioritizing out-of-box configurations with pre-built GDPR and EU AI Act compliance mappings. Bavarian precision engineering firms favor embedded payroll engines that decentralize compensation administration to plant level.
- Staffing Agencies:Temporary workforce platforms requiring real-time integration with client ERP systems and automated timesheet reconciliation.
- Freelancers:Solo-operator tools for invoice generation, tax withholding, and cross-border payment routing.
Large Enterprises dominate current procurement value. Small and Medium Enterprises represent the steepest expansion trajectory as compliance automation penetrates mid-market budgets.
Service Type:
Margin structures favor recurring maintenance contracts over one-time implementation fees.
- Implementation:System configuration with legacy ERP migration and custom API development for shop-floor integration layers.
- Support:Tiered helpdesk services with French and German language coverage for Works Council liaison.
- Consulting:Change management and compliance readiness assessments for EU AI Act conformity documentation.
- Maintenance:Security patch management, model drift monitoring, and regulatory update deployment.
Maintenance commands the most predictable revenue streams. Implementation faces margin pressure as pre-configured templates reduce customization scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Mittelstand anchors procurement volume for integrated talent management systems. The EU AI Act and GDPR enforcement by national data protection authorities reshape platform architecture requirements across the continent. Procurement patterns diverge sharply between centralized HR functions and distributed operational managers seeking edge-level control.
Germany
Automotive manufacturers in Baden-Württemberg and Bavaria drive demand for high-volume recruitment tools with SAP ERP integration. The Federal Data Protection Authority enforces strict cross-border data transfer documentation for workforce analytics platforms. Stuttgart's precision engineering corridor prioritizes skills verification protocols tied to CNC programming certifications.
France
Aerospace contractors and precision engineering firms in Auvergne-Rhône-Alpes require algorithmic hiring systems with human-in-the-loop overrides. CNIL audits impose conformity obligations on automated performance scoring tools. The Lyon-Grenoble industrial cluster accelerates investment in competency mapping platforms aligned with production automation roadmaps.
Netherlands
Mid-sized employers across the Amsterdam-Rotterdam corridor adopt API-connected payroll systems for distributed technical teams. The Dutch Data Protection Authority scrutinizes automated profiling in employment contexts under GDPR Article 22. Eindhoven's high-tech manufacturing ecosystem pilots modular procurement unbundling recruitment from performance management.
United Kingdom
London-based financial services firms and professional services operators demand SOC 2 Type II certified cloud deployments with EU data residency guarantees. The Information Commissioner's Office shapes vendor product roadmaps through enforcement actions on automated decision systems. The Thames Valley technology corridor concentrates procurement of embedded payroll engines for remote-work infrastructure.
Poland
Nearshoring of shared service centers by German and Austrian manufacturers creates demand for multilingual payroll automation. The Polish Data Protection Authority aligns enforcement with GDPR cross-border transfer rulings. Krakow and Wrocław emerge as hubs for cross-border tax compliance modules serving Central European workforces.
Europe Human Resource (HR) Technology Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors rebuild platform architectures around explainable algorithms and sovereign cloud hosting. The vendor base clusters around three tiers: established workforce management suites, mid-market specialists with native compliance automation, and emerging modular API-first platforms. Two archetypes define competitive positioning: integrated-suite providers bundling recruitment through offboarding, and best-of-breed specialists unbundling core functions. M&A activity and technology licensing agreements constitute the primary competitive moves.
Within the mid-market specialist tier, HiBob and Workhuman exemplify contrasting approaches to compliance-anchored growth. HiBob occupies a position among scaling employers prioritizing embedded payroll automation, while Workhuman represents peer-to-peer recognition architectures for distributed team engagement. Randstad sits within the staffing-centric archetype, connecting temporary workforce pools with client ERP systems through data integration layers.
| Leading Market Players |
|---|
| HiBob |
| Adecco |
| Leapsome |
| Randstad |
| Hays |
| Ashby |
| Workhuman |
| Humaans |
| Pirical |
| Others |
Cost & Logistics Intelligence
API-first modular architectures are displacing monolithic HRIS deployments across European mid-market employers, simultaneously compressing implementation cost structures and redistributing value capture toward sovereign-cloud infrastructure providers in Frankfurt and Dublin. This technology transition concentrates procurement leverage among hyperscale hosting vendors while fragmenting software margin pools across specialized compliance-automation modules.
Pricing Analysis
Input-cost pass-through from ISO 27001 certification backlogs and explainable-AI engineering scarcity is intensifying price pressure on high-risk automated hiring systems. SaaS subscription tiers with usage-based pricing tied to active employee counts dominate, with differentiation anchored in GDPR Article 49 derogation automation and EU AI Act conformity documentation. Cost compression runs through the mid-market as pre-configured compliance templates reduce customization scope. Small and medium enterprises exhibit highest price sensitivity due to six-figure algorithmic audit burdens, while large enterprises absorb premium sovereign-cloud deployments.
Supply Chain Analysis
Cross-border data residency requirements are elevating logistics costs for workforce analytics platforms serving multi-jurisdiction employers. Supply concentrates in Germany, Ireland, and the Netherlands, drawing from specialized machine-learning engineering talent pools and SOC 2 Type II certified hosting infrastructure. Dependencies on NVIDIA GPU clusters for model training and sovereign-cloud capacity in Frankfurt create single-point-of-failure exposure. Distribution runs through direct enterprise sales teams with Works Council liaison capabilities and systems-integrator partnerships for SAP ERP migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland and Czech Republic nearshoring corridors offer geographic arbitrage for payroll automation vendors, exploiting wage differentials against German shared-service-center costs while maintaining GDPR compliance equivalence.
For Market Incumbents: Cement platform stickiness through embedded payroll engines that decentralize compensation control to plant-level operations managers in Baden-Württemberg and Bavaria. Prioritize backward integration into sovereign-cloud hosting capacity to defend margin position against hyperscale provider concentration. Invest in explainable-AI engineering capabilities before French CNIL and German DPA audit requirements harden. For New Entrants and Emerging Players: Mid-sized precision engineering firms in Auvergne-Rhône-Alpes represent an underserved buyer archetype seeking skills-verification protocols tied to CNC programming certifications without full-suite procurement burden. Target modular API-first positioning that unbundles recruitment from performance management. Pursue channel partnerships with French aerospace contractors facing steepest EU AI Act compliance redesign cycles. For Investors and Strategic Acquirers: Roll-up economics work for mid-market HR technology specialists because compliance-automation capabilities create sticky recurring revenue with limited customer churn. Long-term viability hinges on pre-certified regulatory mappings that compress sales cycles. Watch ISO 27001 certification queue lengths as inflection indicator for vendor delivery capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Certification Investment | GDPR Article 49 automation secures procurement wins from German automotive manufacturers. |
| API Ecosystem Expansion | Pre-built SAP ERP connectors reduce implementation timelines for Mittelstand buyers. |
| Explainable-AI Talent Acquisition | Interpretable model engineering satisfies French CNIL audit requirements for automated scoring. |
| Modular Product Unbundling | Separate recruitment and performance modules capture Netherlands subscription-fatigue demand. |
| Poland Shared-Service Partnership | Multilingual payroll automation serves German-Austrian nearshoring corridors. |
Research Approach
Bottom-up workforce analytics platform deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with HR technology procurement officers, Works Council representatives, cloud infrastructure architects, and EU regulatory compliance consultants were combined with secondary validation against SEC filings of publicly traded workforce management vendors, EDPB guidance documentation, and national data protection authority enforcement registers.
Historical trendline analysis of cloud-migration patterns and compliance-investment cycles anchored the projection framework. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry concentration, integration complexity level, and regional regulatory cluster. CAGRs were derived from slope-adjusted trend extrapolation incorporating EU AI Act implementation timeline assumptions and GDPR cross-border transfer ruling trajectories.
Inputs from vendor financial disclosures and national data protection authority registers were available through the study window; gaps in private mid-market company revenue data introduce uncertainty bands around SME segment sizing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cloud-migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Performance Management Software Market
Software & Services
File Analysis Software Market
Software & Services
Media Editing App Market
Software & Services
Global Workforce Management Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Email Optimization Software Market
Software & Services
House Cleaning App Market
Software & Services
Ad Creation Software Market
Software & Services
MRP Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global Journal App Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Global Idea Management Software Market