
 North America Workforce Management Software Market | 2026-2036
North America Workforce Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Workforce Management Software Market Analytics
Subscription-based SaaS financing is rewriting competitive entry dynamics across the North America Workforce Management Software Market. WorkForce Software LLC leverages cloud-native architectures to compete against legacy incumbents. Oracle Corporation anchors its position through deep database integration and enterprise ERP connectivity. UKG Inc. differentiates via unified human capital management suites spanning payroll through workforce optimization.
Workforce management software encompasses integrated platforms that automate time capture, labor scheduling, absence management, and regulatory compliance through real-time data processing and algorithmic forecasting. These systems typically deploy via cloud APIs, mobile biometric interfaces, and machine learning-driven demand prediction to optimize labor allocation across distributed operations. Cloud-Based deployment leads segment momentum as enterprises abandon on-premise maintenance burdens. Healthcare and Retail verticals drive disproportionate solution demand due to shift-based labor complexity and seasonal volatility. Task Management and Scheduling solutions capture expanding margin pools as organizations prioritize operational visibility over basic attendance tracking.
The US Department of Labor enforces Fair Labor Standards Act provisions that mandate precise overtime calculation and record retention, directly shaping software feature requirements. California's state-level wage and hour regulations, plus Canada's federal labor standards under Employment and Social Development Canada, create multi-jurisdictional compliance complexity for cross-border operators. Stakeholders must monitor evolving state patchworks of predictive scheduling laws and paid leave mandates that will determine platform configurability requirements.
Market Dynamics
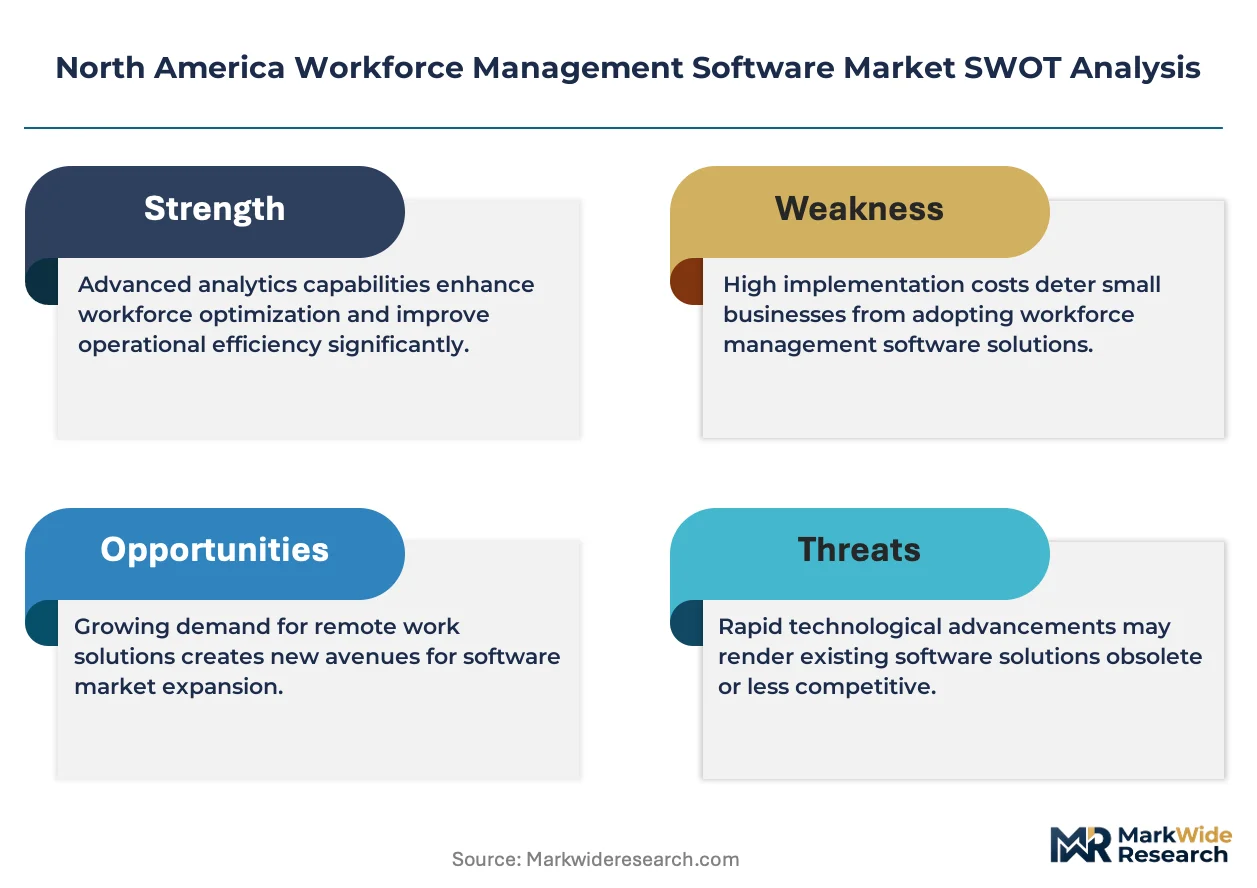
The US Department of Labor's overtime rule revisions are forcing enterprises to upgrade compliance capabilities, creating a structural pull toward algorithmic scheduling platforms that automate Fair Labor Standards Act adherence across multi-jurisdictional operations.
Growth Catalysts
- Healthcare Shift Complexity:Hospital systems and long-term care facilities deploy predictive scheduling to manage 24/7 coverage requirements and nurse union contract stipulations across rotating shifts.
- California Predictive Scheduling Mandates:State-level fair workweek legislation requires 14-day advance notice and premium pay for schedule changes, compelling retail and food service chains to automate labor forecasting.
- Biometric Time Capture:Fingerprint and facial recognition interfaces eliminate buddy-punching fraud while streamlining payroll reconciliation for hourly workforces in manufacturing and logistics.
Market Restraints
- Cloud Migration Costs:On-premise legacy system decommissioning requires substantial capital outlay for data migration, API reconfiguration, and parallel-running transition periods.
- Multi-State Compliance Fragmentation:Oregon, Seattle, and New York City predictive scheduling laws create conflicting rule sets that increase platform configuration complexity for national employers.
- Substitute Labor Marketplaces:Gig-economy platforms offering on-demand staffing reduce perceived urgency for permanent workforce optimization software among seasonal operators.
Strategic Opportunities
- Mexican Manufacturing Expansion:Nearshoring trends in automotive and electronics assembly create demand for bilingual scheduling platforms that harmonize US and Mexican labor law requirements.
- AI-Driven Demand Forecasting:Machine learning models integrating point-of-sale data, weather patterns, and local event calendars enable labor-to-revenue matching previously unavailable to mid-market retailers.
- Canada Federal Labor Standards Modernization:Employment and Social Development Canada rule changes around flexible work arrangements create white space for absence management and leave-tracking modules.
Industry Challenges
- Integration Architectures:Enterprise resource planning connectivity with SAP, Oracle, and Workday environments demands specialized middleware development that extends implementation timelines.
- Change Management Resistance:Frontline manager adoption of algorithmic scheduling recommendations conflicts with traditional intuition-based staffing practices in unionized environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Workforce Management Software Market |
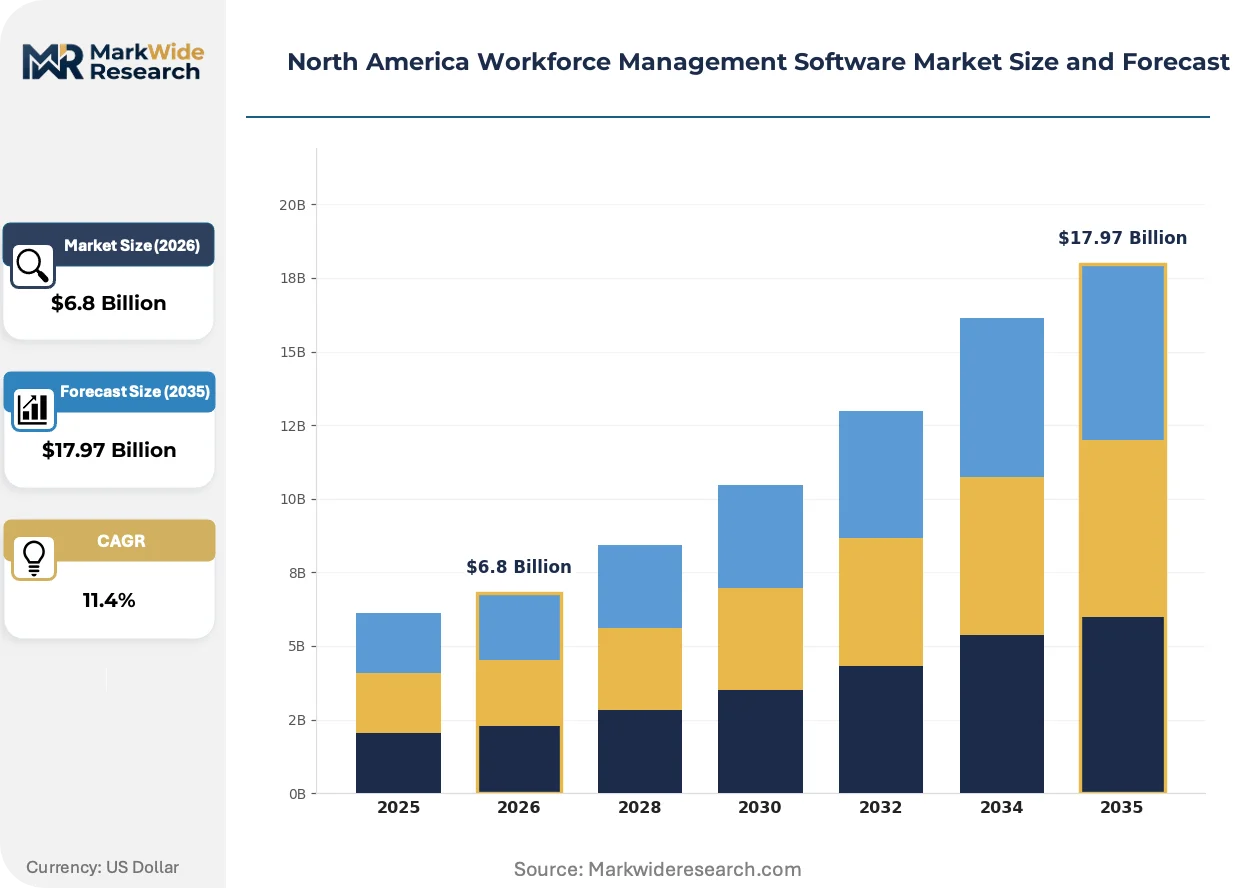
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Industry Vertical: Healthcare, Retail, Manufacturing, BFSI End User: Small Businesses, Large Enterprises, Government, Non-Profits Solution: Time Tracking, Scheduling, Task Management, Attendance |
| Companies Covered | WorkForce Software LLC, ADP, Oracle Corporation, SAP SE, Kronos (US) Inc, Workday, Inc., IBM Corporation, Ceridian, UKG Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Workforce Management Software Market Evolving Landscape
Algorithmic workforce platforms are collapsing the latency between operational demand signals and labor deployment decisions, compressing what required days into minutes across shift-based industries.
Machine learning-driven demand prediction is collapsing the traditional gap between sales forecasting and labor scheduling. Retail chains and hospitality operators deploy neural networks that ingest traffic counters, reservation systems, and supply chain data to generate shift recommendations automatically. This capability is collapsing manual scheduler headcount requirements while improving labor-to-revenue ratios in high-volatility environments.
The US Department of Labor's Fair Labor Standards Act enforcement priorities are elevating audit-ready timekeeping from back-office function to C-suite risk management concern. Record retention mandates and overtime calculation precision requirements are driving replacement of spreadsheet-dependent processes with certified software platforms. Healthcare systems and government contractors face the steepest compliance exposure and are accelerating procurement of integrated time-and-attendance suites.
Subscription financing models are displacing perpetual license purchases across mid-market buyers. Monthly SaaS arrangements reduce capital approval cycles and transfer infrastructure maintenance burdens to vendors, enabling faster deployment decisions among franchise operators and regional healthcare networks. Texas metropolitan hubs and California's technology corridor exhibit the highest concentration of this procurement pattern.
North America Workforce Management Software Market Segmentation
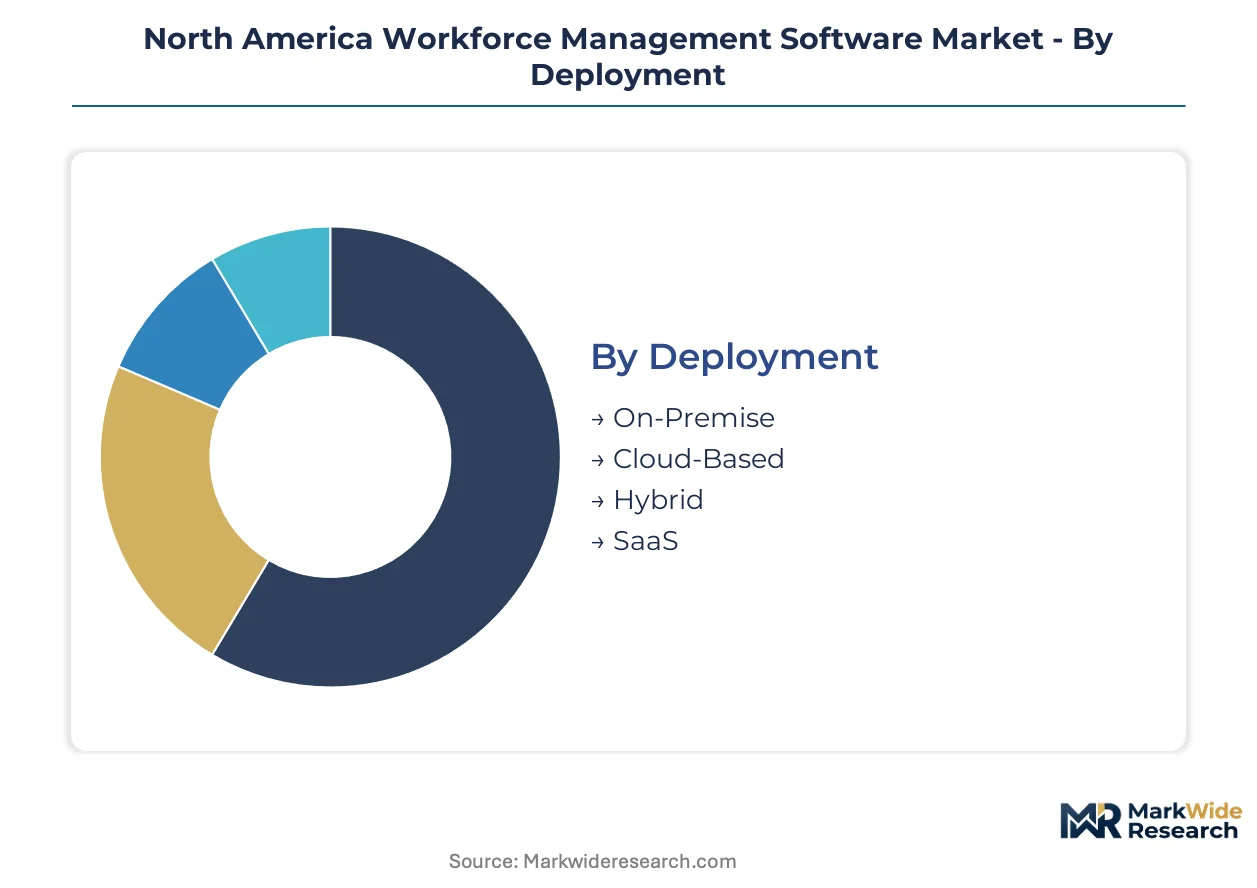
Workforce management software vendors architect product portfolios around deployment economics, vertical compliance requirements, and organizational scale. Segment boundaries determine API configurations, pricing models, and implementation complexity across the North American installed base.
Deployment:
Cost tier determines infrastructure ownership, maintenance burden, and upgrade velocity for platform selection.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance and enable automatic feature updates through browser-based interfaces. Hospital systems in Texas metropolitan hubs and retail chains across California's technology corridor prioritize this model to bypass capital expenditure approval cycles.
- SaaS:Subscription financing transfers infrastructure risk to vendors while reducing implementation timelines through pre-configured modules. Franchise operators and regional healthcare networks leverage monthly arrangements to accelerate procurement decisions without IT department bottlenecks.
- On-Premise:Single-tenant installations retain full data sovereignty within corporate firewalls for defense contractors and financial institutions with stringent audit requirements.
- Hybrid:Split architectures isolate sensitive payroll data on local servers while pushing scheduling functions to cloud environments for workforce accessibility.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
Industry Vertical:
Application-specific compliance mandates and labor volatility patterns shape feature prioritization across buyer categories.
- Healthcare:24/7 coverage requirements, nurse union contract stipulations, and Joint Commission audit protocols demand predictive scheduling with credential tracking and overtime alert systems. Hospital systems and long-term care facilities across the United States deploy these platforms to manage rotating shifts and maintain staffing ratios.
- Retail:Seasonal volatility and California predictive scheduling mandates require 14-day advance notice capabilities with premium pay automation for schedule changes. Food service chains and big-box operators leverage demand forecasting to align labor hours with foot traffic patterns.
- Manufacturing:Shift-based production lines and OSHA record-keeping requirements drive biometric time capture integration with shop-floor data collection systems.
- BFSI:Financial services firms prioritize audit-ready timekeeping with SEC-compliant record retention and branch-level labor cost allocation across multi-state operations.
Healthcare anchors current revenue concentration. Retail is gaining share fastest through predictive scheduling mandates.
End User:
Customer type scales platform complexity from single-location configurations to multi-entity ERP integrations.
- Large Enterprises:Multi-jurisdictional operations across US states and Canadian provinces require configurable rule engines for Fair Labor Standards Act and Employment and Social Development Canada compliance. These buyers demand SAP, Oracle, and Workday connectivity through specialized middleware.
- Small Businesses:Limited IT staff drives preference for out-of-box mobile applications with simplified scheduling and basic time-off tracking without customization overhead.
- Government:Federal contractors and municipal agencies prioritize certified time-and-attendance suites with audit trails satisfying US Department of Labor record retention mandates.
- Non-Profits:Grant-funded operations require labor allocation reporting by funding source with volunteer hour tracking integrated alongside paid staff management.
Large Enterprises command implementation value. Small Businesses are climbing the fastest as SaaS financing removes capital barriers.
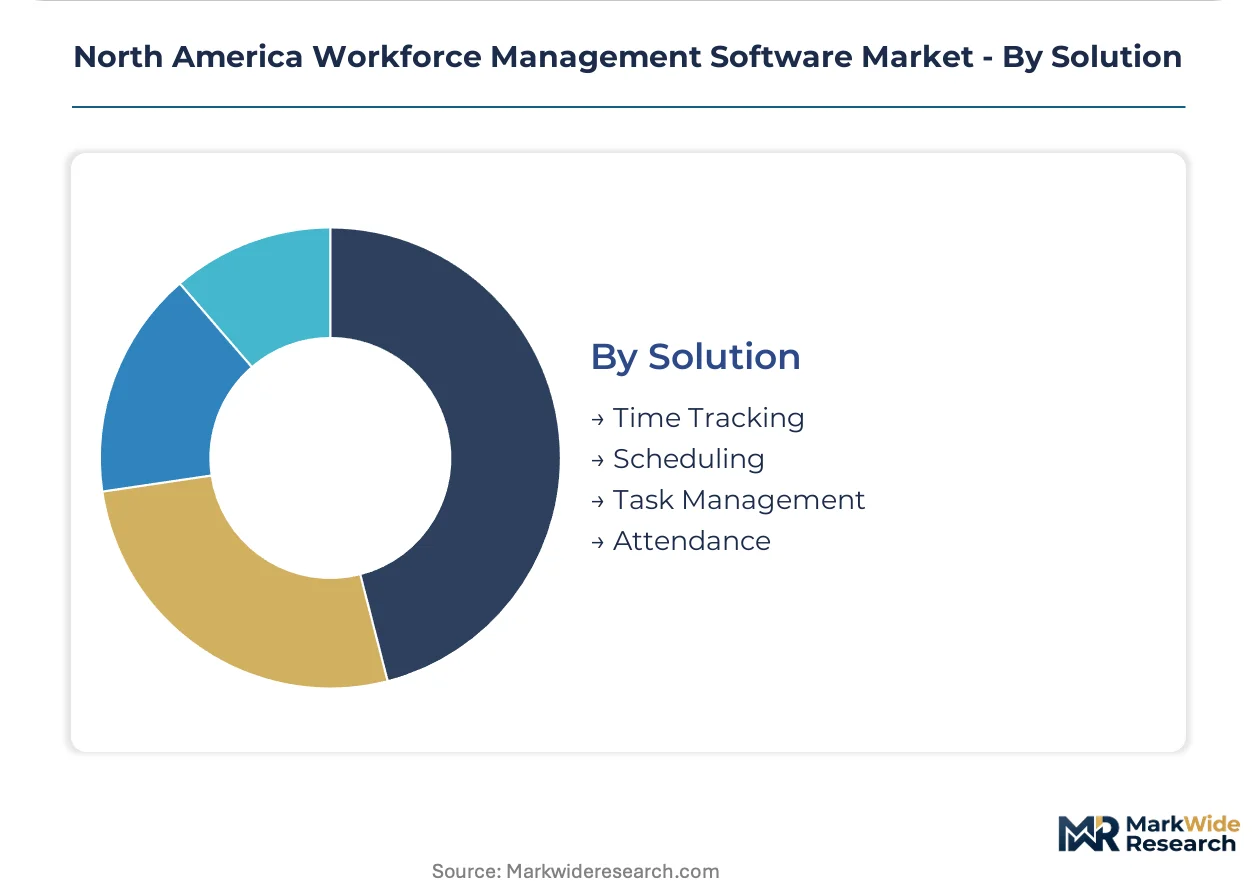
Solution:
Functional module selection reflects organizational maturity from basic attendance verification to algorithmic labor optimization.
- Scheduling:Algorithmic platforms ingest point-of-sale data, weather patterns, and local event calendars to generate shift recommendations automatically. Neural networks collapse manual scheduler headcount requirements while improving labor-to-revenue ratios in high-volatility retail and hospitality environments.
- Task Management:Operational visibility modules prioritize workforce deployment across distributed locations, capturing expanding margin pools as organizations move beyond basic attendance tracking toward productivity measurement.
- Time Tracking:Biometric fingerprint and facial recognition interfaces eliminate buddy-punching fraud while streamlining payroll reconciliation for hourly workforces in manufacturing and logistics operations.
- Attendance:Core absence management functions automate leave accrual, FMLA eligibility tracking, and real-time availability dashboards for frontline supervisors.
Scheduling holds technology leadership. Task Management is expanding most quickly as mid-market buyers prioritize operational visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software exports from the United States dominate regional trade flows, while Canadian enterprises import specialized compliance modules and Mexican manufacturers adopt bilingual scheduling platforms to harmonize cross-border labor operations.
United States
Hospital systems in Texas metropolitan hubs deploy predictive scheduling to manage 24/7 nurse coverage requirements. The US Department of Labor enforces Fair Labor Standards Act provisions mandating precise overtime calculation and record retention. California's technology corridor exhibits concentrated procurement of cloud-native workforce platforms among franchise operators and regional healthcare networks.
Canada
Employment and Social Development Canada rule changes around flexible work arrangements create demand for absence management and leave-tracking modules. Federal labor standards under the Canada Labour Code shape multi-jurisdictional compliance complexity for cross-border operators. Ontario and Quebec anchor enterprise adoption, with Toronto-based financial services firms prioritizing audit-ready timekeeping for SEC-compliant record retention.
Mexico
Nearshoring trends in automotive and electronics assembly create demand for bilingual scheduling platforms harmonizing US and Mexican labor law requirements. The country's federal labor law reforms under the 2019 Ley Federal del Trabajo mandate digital payroll receipts and attendance documentation. Nuevo León and the Bajío Region concentrate manufacturing investment, with Mexico City Metro serving as the primary hub for software distribution and implementation services.
North America Workforce Management Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in time-capture hardware and biometric interfaces. The vendor base organizes around three structural tiers: enterprise suites with ERP connectivity, mid-market SaaS offerings with rapid deployment, and niche compliance modules for specific verticals. Dominant competitive moves include strategic partnerships with payroll processors and vertical integration into adjacent human capital management functions.
Within the enterprise suite tier, Oracle Corporation and SAP SE occupy positions defined by deep database integration and multi-module ERP architectures. WorkForce Software LLC and UKG Inc. exemplify the cloud-native competitive vector, leveraging subscription financing to displace legacy perpetual-license incumbents. ADP anchors the payroll-integrated segment, representing the archetype of workforce management embedded within broader human capital services.
| Leading Market Players |
|---|
| WorkForce Software LLC |
| ADP |
| Oracle Corporation |
| SAP SE |
| Kronos (US) Inc |
| Workday, Inc. |
| IBM Corporation |
| Ceridian |
| UKG Inc. |
| Others |
Value Network & Pricing Analysis
California's technology corridor concentrates cloud-native workforce platform development, where vendor density in San Francisco and San Jose creates competitive pricing pressure that compresses margins for mid-market SaaS offerings while sustaining premium tiers for enterprise ERP-integrated suites.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium enterprise suites, standard mid-market SaaS modules, and economy-tier mobile-first applications. Price differentiation hinges on integration complexity with SAP and Oracle environments plus vertical-specific compliance certification levels. Pricing pressure intensifies in the standard tier as WorkForce Software LLC and UKG Inc. compete aggressively on subscription rates. Small franchise operators exhibit highest price sensitivity, while hospital systems absorbing Joint Commission audit costs show lowest elasticity.
Supply Chain Analysis
Export-control restrictions on biometric facial-recognition algorithms limit hardware component flows from Chinese manufacturers to North American time-capture device assemblers. Software supply chains draw from development centers in the United States, India, and Ireland, with cloud infrastructure resting on AWS, Azure, and Google Cloud data sovereignty architectures. Single-source vulnerability concentrates in specialized middleware connecting to legacy SAP and Workday ERP instances. Distribution runs through direct enterprise sales teams, value-added resellers, and payroll processor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock enterprise buyers into integrated ERP suites, creating sustainable margin pools for incumbents who master multi-jurisdictional compliance rule engines.
For Market Incumbents: Harden platform stickiness through deeper Oracle and SAP connector development that extends implementation timelines and raises replacement costs. Expand biometric time-capture hardware backward integration to reduce dependency on external device manufacturers. Consolidate position against emerging cloud-native entrants by embedding predictive scheduling algorithms directly into payroll workflows.
For New Entrants and Emerging Players: Mid-market retail chains in Texas metropolitan hubs represent the most penetrable entry point given their urgent need for California predictive scheduling compliance without legacy ERP baggage. Canadian federal contractors modernizing under Employment and Social Development Canada rules offer white-space demand for absence management modules. Lead with rapid-deployment SaaS pricing that bypasses capital expenditure approval cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among healthcare systems facing Joint Commission audit mandates and nurse union contract complexity. Long-term viability favors vendors with embedded compliance engines spanning Fair Labor Standards Act and multi-provincial Canadian labor standards. Monitor US Department of Labor enforcement priority shifts as the critical inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP connectivity raises switching costs for hospital systems and government contractors. |
| Geographic Expansion | Bilingual platforms capture nearshoring manufacturing investment in Nuevo León and Bajío Region. |
| Acquisition of Specialist Firm | Biometric hardware targets eliminate buddy-punching fraud in logistics and manufacturing verticals. |
| Strategic Partnership | Payroll processor alliances embed scheduling within broader human capital management workflows. |
| Product Launch | AI-driven demand forecasting modules collapse manual scheduler headcount in volatile retail environments. |
Research Methodology
A standing panel of workforce management software executives, healthcare IT procurement officers, retail operations directors, and payroll integration specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, US Department of Labor enforcement bulletins, and Employment and Social Development Canada regulatory updates. Bottom-up deployment counts and top-down enterprise software spend estimates were triangulated to establish market boundaries.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of cloud adoption velocity and compliance mandate expansion timelines. Segmentation dimensions modeled include deployment architecture, organization scale, vertical industry, solution module type, and regional regulatory cluster. CAGRs were derived from algorithmic curve-fitting against historical SaaS subscription growth patterns, with inputs weighted by hospital system EHR integration backlogs and retail chain foot-traffic volatility indices.
Practitioners should monitor US Department of Labor overtime rule litigation outcomes and California fair workweek enforcement intensity for early signals of procurement cycle acceleration. Forecasts reflect assumptions around sustained cloud migration momentum and stable federal labor standards interpretation. Material shifts in multi-state predictive scheduling law fragmentation or biometric privacy regulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Specification Management Software Market
Software & Services
Email Checker Tools Market
Software & Services
CAM Software Market
Software & Services
Job Description Management Software Market
Software & Services
North America Automotive Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Virtual Fitting Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Testing Software Market
Software & Services
Image Analysis Software Market
Software & Services
Petcare Software Market