
 Miniature Atomic Clock Market | 2026-2036
Miniature Atomic Clock Market Size, Share, and Industry Trends Forecast 2026-2036
Miniature Atomic Clock Market Insights
ITAR compliance is rotating as the decisive gating mechanism for defense-grade miniature atomic clock procurement, restricting qualified supplier pools to vendors with sustained U.S. State Department authorization. Microchip Technology leverages its vertically integrated semiconductor fabrication to dominate chip-scale atomic clock volume. Spectratime anchors European satellite navigation programs through Swiss-based manufacturing with ESA qualification heritage. Frequency Electronics sustains its position in space-qualified rubidium standards through decades of NASA mission heritage.
A miniature atomic clock is a compact frequency reference device exploiting atomic resonance—typically rubidium-87 or cesium-133 hyperfine transitions—to maintain stability within one part in 10^11 over extended operating intervals, primarily serving applications where GPS denial or signal unavailability demands autonomous precision timing. Chip-scale atomic clocks built on microelectromechanical systems platforms occupy the highest volume tier as telecommunications and drone-navigation budgets expand, while cold atom architectures command premium positioning in scientific research and advanced defense programs where fractional-frequency uncertainty below 10^14 justifies unit costs orders of magnitude higher. Vapor cell technology using rubidium vapor dominates current military procurement, with laser-cooled configurations representing the fastest-growing segment as quantum sensing investments accelerate.
The U.S. Department of Defense mandates MIL-STD-461 and MIL-STD-810 qualification for deployed atomic clock systems, while the European Space Agency imposes ECSS-Q-ST-70-38C standards for space-grade frequency sources, collectively elevating R&D barriers and extending product development cycles. NIST traceability requirements and the IEEE 1139 time and frequency metrology standard further constrain which architectures achieve commercial viability in precision-dependent sectors. Stakeholders must monitor how export-control alignment between ITAR and emerging EU dual-use regulations reshapes cross-border supply access for strategic timing components.
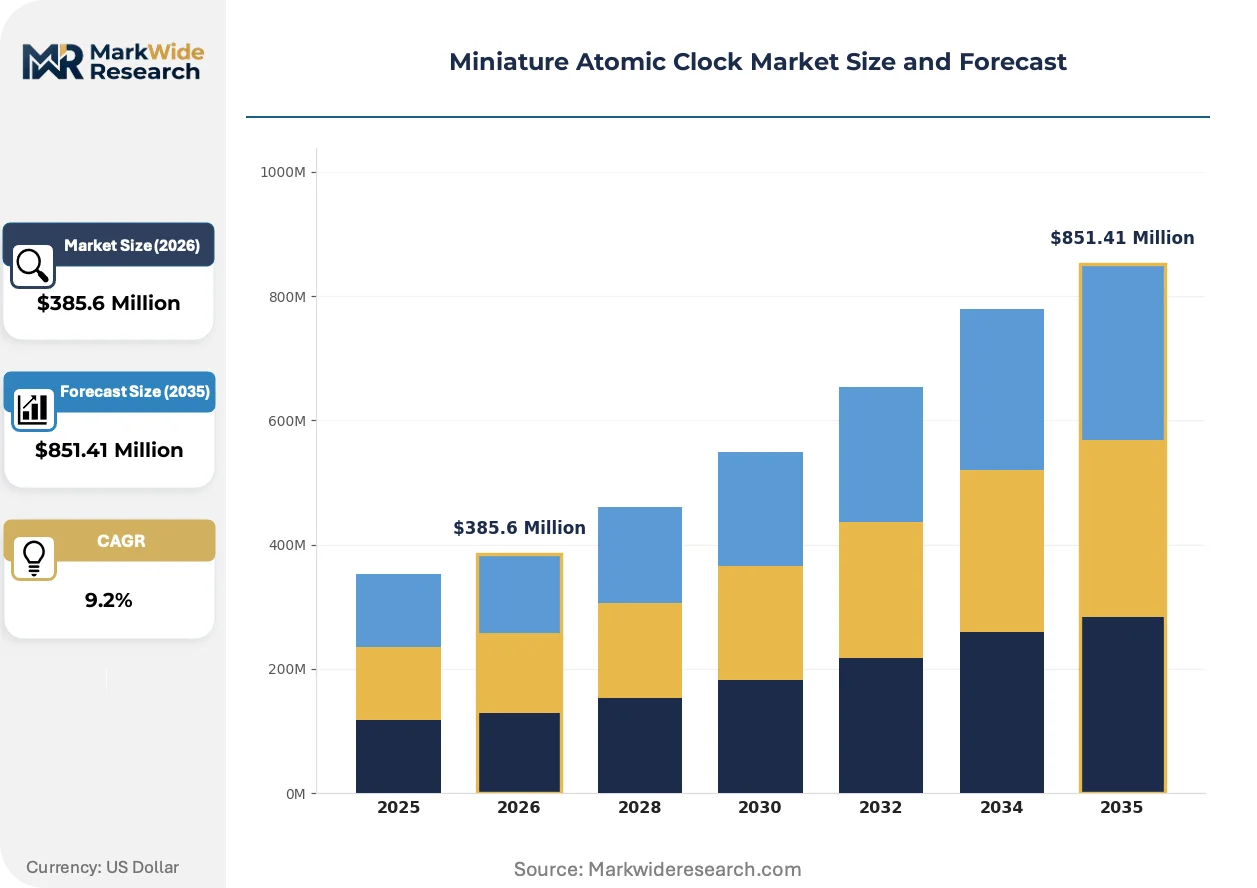
Market Dynamics
ITAR compliance is compressing the qualified supplier pool for defense-grade miniature atomic clocks, while ESA frequency-stability mandates are accelerating vendor qualification cycles and reshaping procurement timelines across satellite navigation programs.
Growth Catalysts
- LEO constellation deployment:Satellite operators are expanding chip-scale atomic clock procurement for low-earth-orbit networks requiring autonomous timing redundancy.
- ECSS-Q-ST-70-38C tightening:The European Space Agency's evolving space-grade frequency source standards are forcing architecture upgrades that favor qualified incumbent vendors.
- Vapor cell miniaturization:Advances in microelectromechanical systems fabrication are reducing unit footprint for rubidium-based military timing systems.
Market Restraints
- Rubidium supply concentration:Primary rubidium extraction concentrates in Canadian and Namibian mining operations, creating raw material vulnerability for vapor cell manufacturers.
- Laser-cooled system cost floors:Cold atom architectures require stabilized optical benches and magnetic shielding that resist cost-down engineering at volume.
- ITAR authorization barriers:U.S. State Department export controls restrict technology transfer to non-U.S. entities, fragmenting cross-border R&D collaboration.
Strategic Opportunities
- Drone navigation autonomy:Uncrewed aerial systems operating in GPS-denied environments represent an underpenetrated demand vertical for chip-scale atomic clocks.
- Quantum sensing convergence:Integration of atomic clock cores with inertial measurement units is opening defense and geophysical survey applications.
- NASA deep-space timing:Artemis program lunar and cislunar missions are generating qualification pathways for next-generation space-qualified standards.
Industry Challenges
- Atomic physicist scarcity:The specialized workforce for laser cooling and vapor cell engineering is concentrated in national laboratories and select university programs.
- MIL-STD-810 qualification timelines:Environmental testing for shock, vibration, and thermal cycling extends product development cycles beyond typical commercial electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miniature Atomic Clock Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $851.41 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-Scale Atomic Clock, Vapor Cell Atomic Clock, Cold Atom Atomic Clock, Hydrogen Maser Clock Technology: Microelectromechanical Systems, Optical Pumping, Laser Cooling, Cesium Beam, Rubidium Vapor Application: Telecommunications, Navigation Systems, Defense & Aerospace, Scientific Research, Finance & Trading End User: Satellite Operators, Military Agencies, Research Laboratories, Financial Institutions |
| Companies Covered | Spectratime, IQD Frequency Products, Microchip Technology, Excelitas Technologies, Frequency Electronics, Oscilloquartz, AccuBeat, Stanford Research Systems, Orolia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miniature Atomic Clock Market Trends and Innovations
Atomic clock architecture is splitting along performance-cost axes, with diverging development paths for telecommunications volume applications versus scientific and defense precision requirements.
Chip-scale atomic clocks built on MEMS platforms is bifurcating the installed base between telecommunications and drone navigation budgets seeking sub-$1000 units versus cold atom systems serving defense programs where fractional-frequency uncertainty below 10^-14 justifies premium positioning. Military procurement continues favoring rubidium vapor cell reliability while research laboratories drive laser-cooled adoption.
ECSS-Q-ST-70-38C revisions are mandating tighter frequency stability margins for European satellite navigation payloads, compelling vendors to redesign thermal compensation and magnetic shielding subsystems. Swiss and French manufacturers with ESA qualification heritage are capturing specification-setting influence, while U.S. vendors face parallel MIL-STD-461 electromagnetic compatibility requirements.
Buyers are unbundling after-sales calibration services from initial hardware procurement, pressuring vendors to establish regional service centers or certify third-party metrology laboratories. Defense primes with captive timing expertise are internalizing routine maintenance, while commercial telecommunications operators demand subscription-based performance guarantees with remote diagnostics.
Miniature Atomic Clock Market Segmentation
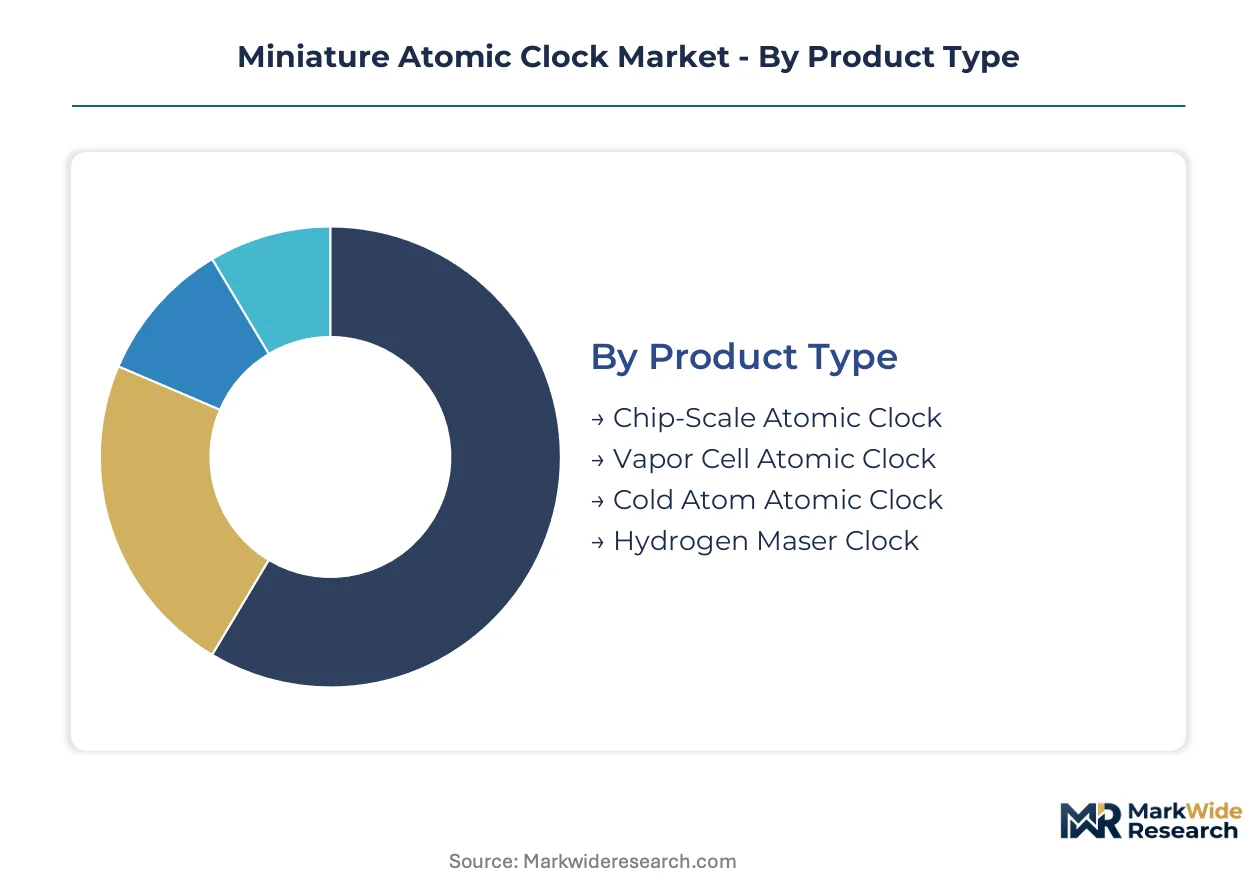
Segmentation in the miniature atomic clock market reveals how performance requirements and procurement budgets fragment across radically different use cases. Understanding these divisions exposes where volume economics clash with precision premiums, and which technology platforms capture sustained defense spending versus commercial expansion.
Product Type:
Margin pools concentrate in vapor cell architectures where military procurement reliability commands sustained pricing power, while chip-scale variants compete on telecommunications volume economics.
- Vapor Cell Atomic Clock:Rubidium-87 vapor cell technology delivers stability within one part in 10^11 through sealed glass cavities with integrated magnetic shielding. Defense primes in the United States anchor procurement for GPS-denied navigation systems, with ITAR compliance restricting qualified suppliers to vendors with sustained State Department authorization.
- Chip-Scale Atomic Clock:MEMS-fabricated devices integrate atomic vapor cells with semiconductor photonics on centimeter-scale footprints. Telecommunications infrastructure and uncrewed aerial system operators in the United States drive procurement for autonomous timing redundancy where unit costs must fall below $1,000 at volume.
- Cold Atom Atomic Clock:Laser-cooled cesium or rubidium atoms achieve fractional-frequency uncertainty below 10^-14 through optical lattice confinement. NASA-funded research laboratories and advanced defense programs justify premium unit costs for deep-space navigation and quantum sensing applications.
- Hydrogen Maser Clock:Hydrogen atomic transitions in storage bulbs provide exceptional short-term stability for radio astronomy and geodetic measurements. Scientific research facilities with national laboratory funding maintain limited installed bases where size constraints are secondary to precision.
Vapor cell architectures hold installed capacity across defense programs. Chip-scale atomic clocks are rotating up the share rankings as LEO constellation deployment accelerates.
Technology:
Volume manufacturing gravitates toward semiconductor-compatible fabrication methods, while precision tiers demand specialized atomic physics expertise that resists cost-down engineering.
- Rubidium Vapor:Optical pumping of rubidium-87 hyperfine transitions dominates military procurement through proven reliability in shock and thermal environments. Defense agencies in the United States specify rubidium vapor for field-deployable systems where MIL-STD-810 qualification is mandatory.
- Microelectromechanical Systems:Silicon wafer-level fabrication enables batch production of vapor cells with integrated lasers and photodetectors. Telecommunications equipment manufacturers and drone navigation system integrators in the United States prioritize MEMS platforms for supply chain scalability.
- Laser Cooling:Magneto-optical traps and optical molasses configurations achieve sub-microkelvin temperatures for atomic ensemble manipulation. Research laboratories with National Science Foundation and Department of Energy funding drive adoption for quantum information science and advanced inertial sensing.
- Optical Pumping:Circularly polarized laser light drives population inversion in alkali vapor without requiring sub-Doppler cooling techniques. Satellite navigation payload manufacturers balance frequency stability against power and mass constraints for space-qualified implementations.
- Cesium Beam:Thermal atomic beams with magnetic state selection provide primary frequency standards traceable to SI definitions. National metrology institutes maintain cesium fountain clocks as reference standards, with limited miniaturization potential for portable applications.
Rubidium vapor holds installed capacity across deployed military systems. MEMS platforms are climbing the fastest as commercial telecommunications budgets expand.
Application:
Procurement authority splits between classified defense programs with captive timing expertise and commercial operators demanding performance guarantees with remote diagnostics.
- Defense & Aerospace:GPS-denied navigation, secure communications, and electronic warfare systems require autonomous frequency references with MIL-STD-461 electromagnetic compatibility. The U.S. Department of Defense mandates NIST-traceable calibration cycles for deployed atomic clock networks.
- Telecommunications:5G network synchronization and fiber optic backbone timing demand holdover stability during GPS outages. Federal Communications Commission regulations on network reliability are pressuring carriers to deploy redundant atomic timing at cell tower locations.
- Navigation Systems:Satellite constellations and autonomous vehicle platforms require local oscillators that maintain position accuracy when external signals are unavailable. The European Space Agency's ECSS-Q-ST-70-38C standards are tightening frequency stability margins for navigation payloads.
- Scientific Research:Gravitational wave detection, geodesy, and tests of fundamental physics demand fractional-frequency uncertainty below 10^-14. National laboratories with NASA and National Science Foundation funding operate cold atom systems where scientific output justifies capital intensity.
- Finance & Trading:High-frequency trading infrastructure requires timestamp synchronization within microseconds for regulatory compliance and transaction ordering. Financial institutions in the United States deploy atomic clocks to satisfy Securities and Exchange Commission requirements on market access timing.
Defense and aerospace applications hold installed capacity across classified programs. Telecommunications is gaining share fastest as 5G infrastructure deployment extends timing redundancy requirements.
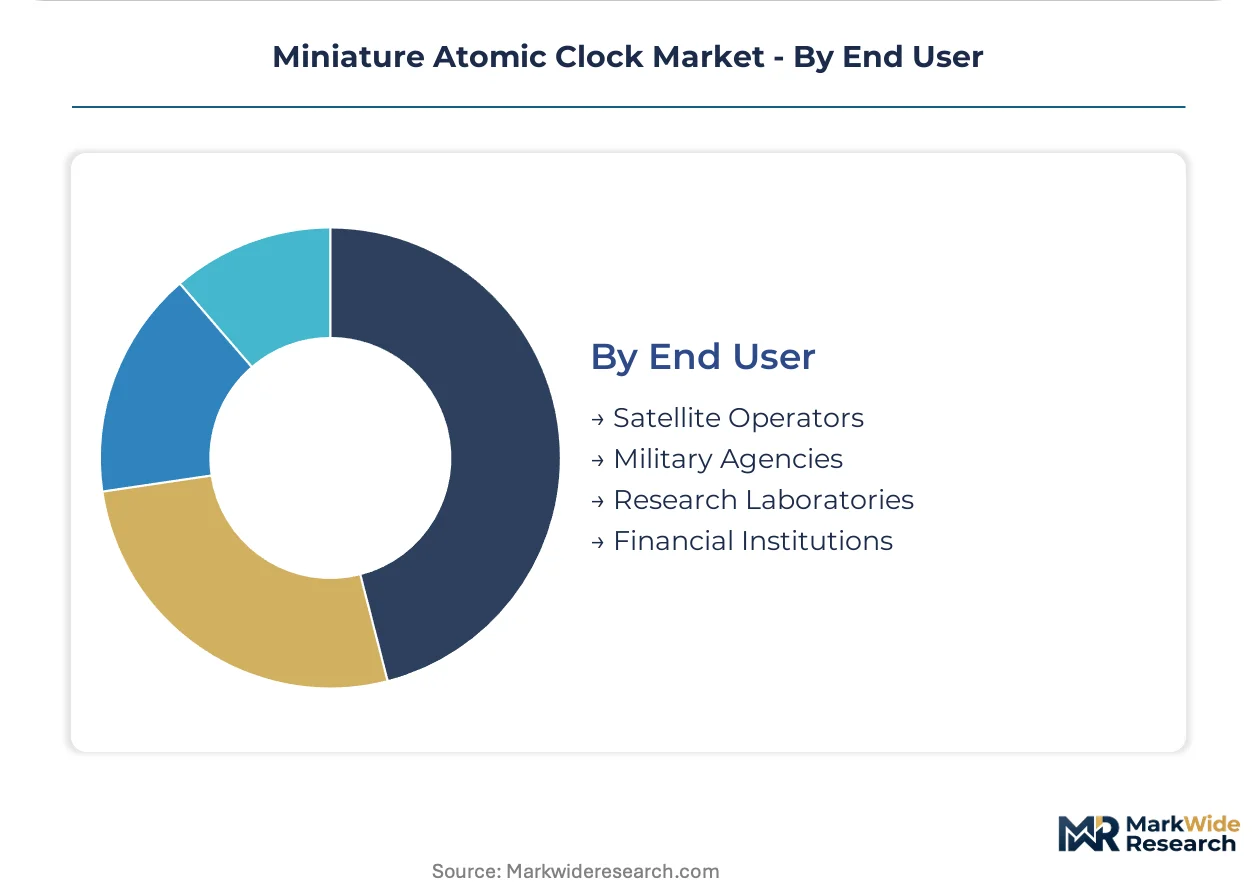
End User:
Customer concentration varies from single-source defense procurement with decade-long qualification cycles to fragmented commercial operators with subscription-based service expectations.
- Military Agencies:The U.S. Department of Defense and intelligence community operate the largest installed base of miniature atomic clocks, with procurement governed by ITAR restrictions and MIL-STD qualification requirements. Program offices prioritize vendor heritage over cost optimization for mission-critical timing systems.
- Satellite Operators:Commercial constellation developers and government space agencies procure chip-scale and vapor cell clocks for autonomous navigation redundancy. NASA's Artemis program is generating qualification pathways for next-generation space-qualified standards through lunar and cislunar mission requirements.
- Research Laboratories:National Institute of Standards and Technology facilities, Department of Energy national laboratories, and university physics departments operate cold atom systems for precision measurement and quantum information science. Funding cycles from the National Science Foundation and Defense Advanced Research Projects Agency determine procurement timing.
- Financial Institutions:Investment banks, exchanges, and high-frequency trading firms deploy atomic clocks to satisfy regulatory timestamp requirements and minimize latency arbitrage. Procurement emphasizes remote diagnostics and subscription-based performance guarantees over capital equipment ownership.
Military agencies hold installed capacity across classified defense programs. Satellite operators are rotating up the share rankings as LEO constellation deployment accelerates vendor qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement budgets and satellite navigation mandates are redrawing geographic demand patterns for miniature atomic clocks. National security classifications and export control regimes fragment supplier access across borders.
United States
Department of Defense GPS-denied navigation programs and NASA deep-space missions anchor the largest installed base of vapor cell and chip-scale systems. ITAR restrictions administered by the U.S. State Department limit qualified suppliers to vendors with sustained authorization. The Greater Boston corridor hosts concentrated atomic physics research capacity feeding defense prime contractors.
Switzerland
European Space Agency satellite navigation payloads drive procurement of space-qualified frequency standards with ECSS-Q-ST-70-38C heritage requirements. Swissmedic and federal export control frameworks govern technology transfer for precision timing components. The Lake Geneva region concentrates vendors with decades of ESA qualification experience.
China
Domestic satellite constellation deployment and quantum sensing research programs are expanding captive production capacity for rubidium vapor systems. MIIT standards and national dual-use export regulations shape technology access for foreign entities. The Yangtze River Delta hosts emerging MEMS fabrication clusters targeting telecommunications timing applications.
United Kingdom
Defense and aerospace procurement through the Ministry of Defence sustains demand for MIL-STD-qualified atomic clocks in electronic warfare platforms. UK Space Agency funding for navigation payloads aligns with ESA frequency stability mandates. The Cambridge-Oxford arc maintains atomic physics research infrastructure supporting precision timing development.
Japan
METI-funded quantum technology initiatives and domestic telecommunications infrastructure upgrades drive adoption of chip-scale atomic clocks for 5G network synchronization. JIS standards and national security export controls govern strategic timing component trade. The Tokyo-Yokohama corridor concentrates precision instrument manufacturing with semiconductor supply chain integration.
Miniature Atomic Clock Market Competitive Landscape
Player mix skews toward defense-aerospace specialists with qualification heritage and semiconductor-integrated volume manufacturers. The vendor base splits between ITAR-authorized U.S. suppliers serving classified programs and ESA-qualified European incumbents capturing satellite navigation procurement. Three archetypes dominate: vertically integrated semiconductor fabricators, precision timing specialists with space mission heritage, and national laboratory spin-offs commercializing cold atom research. Competitive moves center on qualification cycle acceleration and regional service center establishment to unbundle after-sales calibration from hardware sales.
Among defense-aerospace specialists with ESA heritage, Spectratime and Frequency Electronics exemplify the qualification-dependent tier where mission heritage sustains pricing power. Microchip Technology occupies the volume-manufacturing position, leveraging semiconductor fabrication integration to serve telecommunications and uncrewed system demand. These three anchors illustrate how supplier positioning splits between heritage-dependent premium positioning and scale-driven cost optimization.
| Leading Market Players |
|---|
| Spectratime |
| IQD Frequency Products |
| Microchip Technology |
| Excelitas Technologies |
| Frequency Electronics |
| Oscilloquartz |
| AccuBeat |
| Stanford Research Systems |
| Orolia |
| Others |
Pricing and Supply Chain Analysis
MEMS fabrication substitution for traditional glass-blown vapor cells is redrawing supply geography toward semiconductor foundries in Taiwan and the United States while compressing unit economics for telecommunications-grade atomic clocks. This materials transition simultaneously fragments supplier tiers between precision-defense heritage manufacturers and volume-scaled chip producers.
Pricing Analysis
Certification level—ITAR authorization versus ESA heritage versus commercial-grade—creates the primary spread across pricing tiers. Three-tier pricing structure across ITAR-restricted defense, ESA-qualified space, and unqualified commercial levels separates captive procurement from open-market sales. Price compression runs through chip-scale tiers as telecommunications buyers demand sub-thousand-dollar units at volume. Defense agencies exhibit lowest price sensitivity where mission assurance overrides cost optimization.
Supply Chain Analysis
Extended qualification timelines—eighteen to thirty-six months for MIL-STD-810 and ECSS-Q-ST-70-38C—force inventory pre-positioning at prime contractor facilities. Rubidium feedstock concentrates in Canadian and Namibian mining operations, while MEMS fabrication draws from Taiwan and United States semiconductor infrastructure. Single-source vulnerability sits with ITAR-authorized vapor cell suppliers serving classified programs. Distribution runs through defense prime contractor captive procurement channels and telecommunications equipment OEM direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The miniature atomic clock market is cycling through a recovery phase as LEO constellation deployment restores procurement momentum after pandemic-era qualification delays. Satellite operator capital commitments to autonomous navigation redundancy provide the cyclical driver.
For Market Incumbents: Fortify ITAR authorization status through sustained State Department compliance investment, as export control tightening threatens non-U.S. market access. Deepen captive rubidium vapor cell production to insulate against Canadian and Namibian supply concentration. Accelerate regional calibration service center deployment to defend against unbundling of after-sales revenue streams.
For New Entrants and Emerging Players: Anchor in drone navigation autonomy as the most penetrable white-space vertical, where GPS-denied operation requirements outpace qualified supplier capacity. Target commercial telecommunications infrastructure as secondary entry point through MEMS-compatible foundry partnerships. Pursue qualification pathway sponsorship through NASA Artemis program subcontracting relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision timing specialists holding ESA heritage but lacking ITAR authorization for U.S. defense access. Five-to-ten-year viability hinges on dual-use technology transfer alignment between U.S. and European export control regimes. Monitor ECSS-Q-ST-70-38C revision timing as inflection indicator for vendor consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Cycle Acceleration | Reduces time-to-revenue for ESA and MIL-STD certification pathways. |
| Regional Service Center Establishment | Captures recurring calibration revenue from telecommunications operators demanding subscription models. |
| MEMS Foundry Partnership | Enables batch production scale for chip-scale atomic clocks serving LEO constellation procurement. |
| Rubidium Supply Agreement | Secures vapor cell feedstock against Canadian and Namibian mining concentration risk. |
| Quantum Sensing Integration R&D | Positions cold atom architectures for Defense Advanced Research Projects Agency funding cycles. |
Research Methodology
Operator-level perspectives from satellite procurement officers, defense prime contractor timing engineers, telecommunications infrastructure planners, and atomic physics research directors anchored the qualitative base. Primary interviews combined with secondary validation against NASA mission databases, ESA procurement records, FCC 5G deployment filings, and defense budget justification documents. Bottom-up unit economics triangulated against top-down defense and space agency expenditure tracking.
Sensitivity analysis tested forecast robustness across rubidium price volatility, ITAR authorization denial scenarios, and LEO constellation deployment schedule variations. Segmentation modeling spanned product architecture, qualification tier, application vertical, and end-user procurement authority. CAGRs derived from installed base replacement cycles and new constellation deployment trajectories. Quantum sensing investment flows and GPS denial threat assessments provided industry-specific forecast inputs.
Material uncertainties—ITAR-EU dual-use regulatory divergence, rubidium supply disruption, and cold atom architecture cost-floor persistence—sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline stability and defense procurement continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
PXI SMU Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Crock Meter Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Dosimeter Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Analog Multimeters Market