
 Online Tutoring Services Market | 2026-2036
Online Tutoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Online Tutoring Services Market Intelligence
Asset-light subscription models are narrowing the capital barrier for new entrants in online tutoring. Chegg Inc. leverages its textbook rental heritage to anchor recurring revenue streams in homework help. BYJU'S sustains aggressive geographic expansion through its freemium content funnel. Khan Academy competes on zero-price positioning while controlling donor-funded R&D intensity.
Online tutoring services deliver synchronous and asynchronous educational instruction through internet-connected platforms, typically employing video conferencing protocols, interactive whiteboards, and adaptive assessment algorithms to personalize learning pathways. The primary commercial purpose centers on supplementing or replacing traditional classroom instruction across academic, professional, and recreational knowledge domains. One-on-one tutoring commands premium pricing due to customization intensity, while test preparation captures concentrated margin pools from high-stakes examination cycles. Learning Management Systems represent the fastest-growing technology segment as institutions seek integrated administrative and pedagogical control.
The US Department of Education coordinates Title I funding flows that subsidize tutoring access for low-income districts, while the EU AI Act imposes transparency obligations on algorithmic tutoring recommendations. India's National Education Policy framework encourages digital platform integration without prescribing specific technical standards. Stakeholders must monitor how procurement rules for supplemental educational services evolve across federal, state, and institutional buyers.
Market Dynamics
AI-driven personalization engines are compressing the cost-to-serve ratio for individualized instruction while EU AI Act transparency mandates force platform redesigns. This structural tension between capability expansion and compliance burden defines current competitive positioning.
Growth Catalysts
- EU AI Act:Mandatory algorithmic transparency for automated tutoring systems creates compliance-as-a-service revenue streams for audit-ready platforms operating across member states.
- India's National Education Policy:Digital platform integration incentives accelerate institutional procurement cycles for supplemental learning infrastructure in urban districts.
- Adaptive assessment algorithms:Real-time learning pathway optimization reduces instructor time-per-student while maintaining outcome quality for K-12 adoption.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominance in video conferencing backbone services creates single-point vulnerability for synchronous tutoring uptime guarantees.
- Qualified instructor scarcity:STEM-specialized educators command premium compensation that erodes unit economics in one-on-one delivery models.
- Data localization requirements:India's PDP Bill and EU GDPR divergence force redundant server architecture investments for cross-border platform operators.
Strategic Opportunities
- Vocational reskilling applications:Corporate L&D budgets for technical certification prep represent underpenetrated B2B demand outside traditional academic segments.
- US Title I funding flows:Federal supplemental educational services procurement rules create mandated demand pools in low-income district clusters.
- Immersive technology convergence:VR classroom environments combined with haptic feedback hardware enable premium-priced experiential learning for medical and engineering simulation.
Industry Challenges
- Learning outcome verification:Absence of standardized competency measurement frameworks complicates B2B contract renewals and insurance-backed performance guarantees.
- Platform integration complexity:Legacy school district LMS architectures require custom API development that extends sales cycles and inflates implementation costs.
- Instructor credential authentication:Cross-border teaching licenses and subject-specific certification validation create operational friction for on-demand tutor marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Tutoring Services Market |
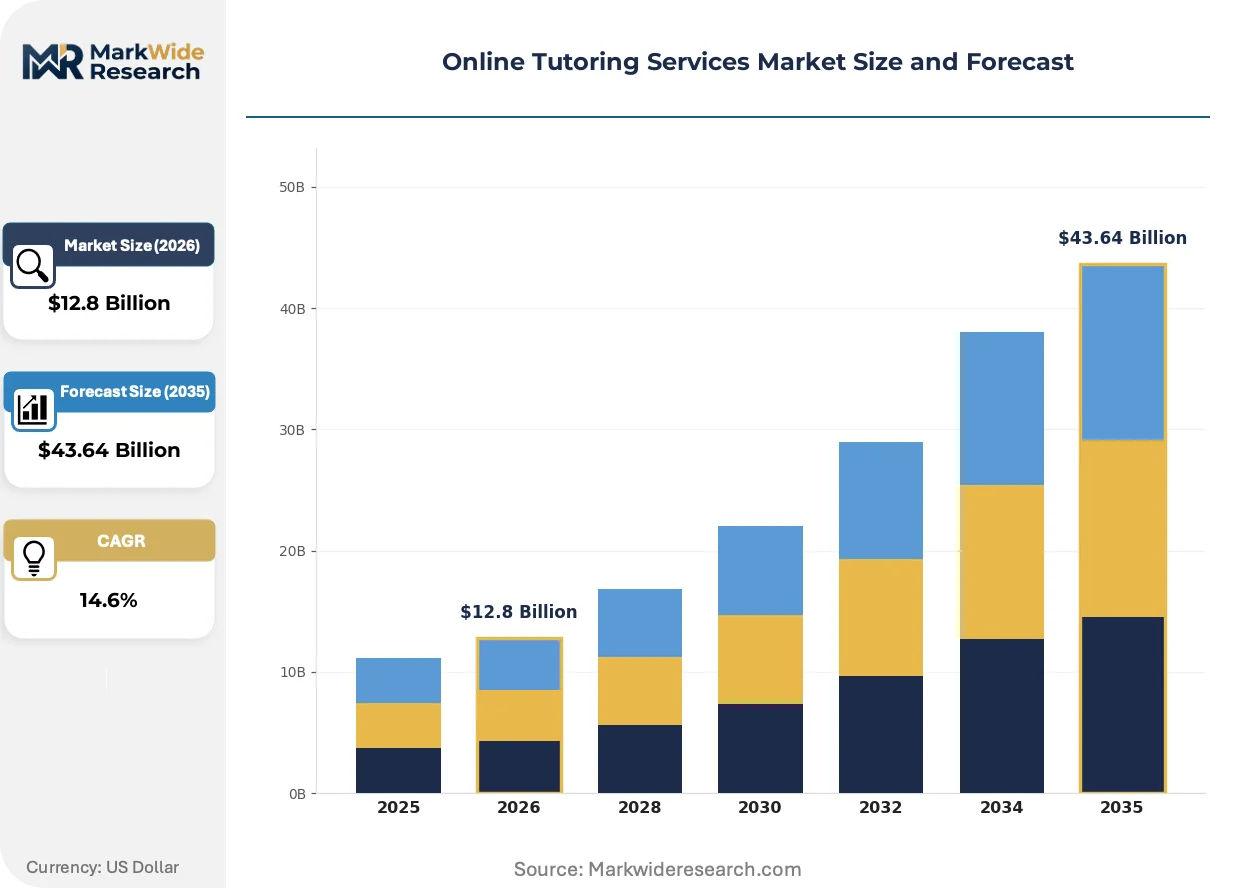
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: One-on-One Tutoring, Group Sessions, Test Preparation, Language Instruction Technology: Video Conferencing, Learning Management Systems, Interactive Whiteboards, Mobile Apps Target Audience: Students, Professionals, Parents, Lifelong Learners Content Type: Academic Subjects, Skill Development, Certification Courses, Hobby Learning |
| Companies Covered | Chegg Inc., Tutor.com, Varsity Tutors, BYJU'S, Preply Inc., Wyzant Inc., Khan Academy, Vedantu, Brainfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Tutoring Services Market Strategic Shifts & Innovations
Generative AI is compressing content production timelines while regulatory fragmentation forces architectural bifurcation. Platform operators must simultaneously accelerate capability deployment and harden compliance infrastructure.
Multimodal large language models are hybridizing text, voice, and visual explanation capabilities into unified tutoring interfaces. K-12 districts with 1:1 device programs are piloting these systems for after-hours homework support. This convergence is hybridizing the distinction between synchronous instructor-led and asynchronous self-paced delivery, collapsing pricing tiers that previously separated live tutoring from recorded content libraries.
The EU AI Act's risk classification framework for educational applications imposes documentation burdens on algorithmic recommendation engines. Automated tutoring platforms must now maintain technical files demonstrating bias mitigation and human oversight protocols. High-stakes test preparation segments face the steepest compliance costs, with operators in Germany and France front-loading legal review cycles before feature deployment.
Enterprise buyers are unbundling after-sales support from core platform subscriptions, demanding à-la-carte instructor access without annual commitments. This procurement pattern disrupts traditional SaaS renewal models and pressures vendors toward consumption-based pricing. The shift is most visible in India's competitive exam preparation market, where urban students increasingly purchase micro-tutoring sessions tied to specific test dates rather than semester-long packages.
Online Tutoring Services Market Segmentation
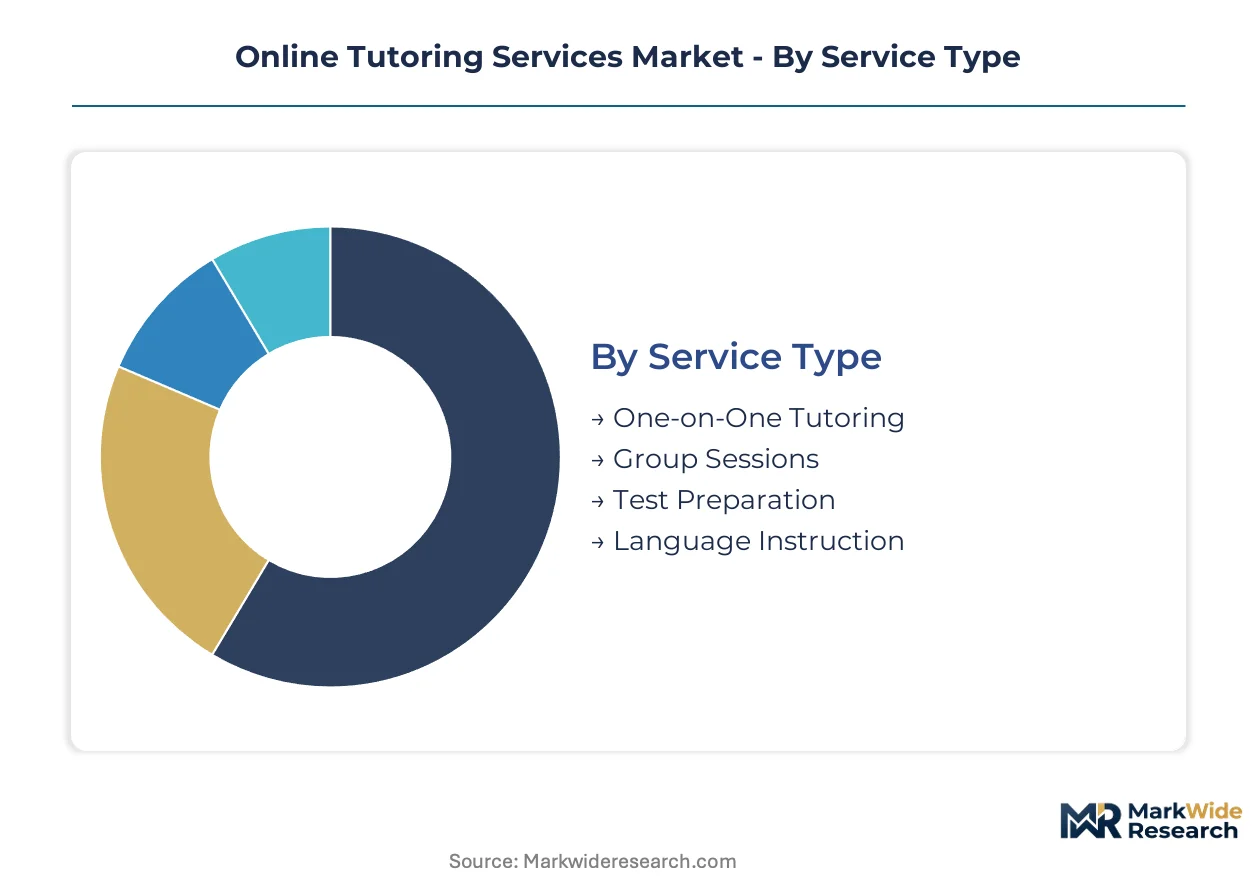
Segmentation in online tutoring services determines platform architecture, pricing elasticity, and customer acquisition costs. Service delivery models and technology infrastructure choices cascade into divergent margin structures and retention mechanics across each slice.
Service Type:
After-sales service intensity varies sharply across delivery formats, with one-on-one tutoring requiring continuous instructor matching and outcome tracking while group sessions shift support burden to community moderation.
- One-on-One Tutoring:Live synchronous instruction between single student and dedicated instructor, typically scheduled through platform marketplaces or assigned through institutional contracts. Demand concentrates in India's competitive exam corridors—Mumbai, Delhi, Bangalore—where parents pay premium rates for JEE and NEET preparation, though instructor scarcity inflates customer acquisition costs.
- Group Sessions:Synchronous instruction delivered to cohorts of 5-50 students, enabling cost distribution across participants while sacrificing personalization depth. US Title I districts in Texas and California procure these for after-school supplemental programs, driven by federal funding flows that mandate measurable literacy gains.
- Test Preparation:Structured curricula aligned to high-stakes examination schedules, combining live instruction with practice assessment banks. EU AI Act compliance costs bite hardest here, with French and German operators front-loading algorithmic transparency documentation.
- Language Instruction:Conversation-focused tutoring targeting fluency certification or professional mobility, often delivered through subscription models with native speaker matching. Corporate L&D budgets in Japan and South Korea sustain B2B demand for English business communication.
By volume, Group Sessions leads. By growth pace, Test Preparation is ahead.
Technology:
Platform technology choices dictate capital intensity and operational leverage, with video infrastructure representing fixed cost anchors while adaptive systems enable margin expansion at scale.
- Video Conferencing:Real-time audiovisual delivery backbone, typically layered with screen sharing and session recording. AWS, Azure, and Google Cloud concentration creates uptime vulnerability for synchronous tutoring guarantees, forcing redundant provider contracts.
- Learning Management Systems:Integrated administrative and pedagogical control layers enabling curriculum sequencing, progress tracking, and outcome reporting. K-12 districts in Florida and Ohio pilot these for hybrid classroom integration, though legacy SIS architectures demand custom API development.
- Interactive Whiteboards:Collaborative canvas tools for visual explanation, particularly critical for STEM problem-solving workflows. Mathematics and physics tutoring segments in Singapore and Hong Kong show highest adoption intensity.
- Mobile Apps:Asynchronous content access and micro-session delivery, optimized for commute-time consumption patterns. Urban Indian students leverage these for spaced repetition drilling during transit.
Learning Management Systems capture the steepest expansion trajectory as institutional procurement accelerates. Video Conferencing retains the largest installed base.
Target Audience:
Customer type determines pricing power, session frequency, and lifetime value calculations, with professional segments showing higher willingness-to-pay but lower retention elasticity.
- Students:K-12 and higher education learners seeking grade improvement or examination success. India's National Education Policy digital integration incentives accelerate platform adoption in Maharashtra and Tamil Nadu urban districts.
- Professionals:Mid-career workers pursuing technical certification or leadership training. Corporate training budgets in Germany and Netherlands sustain B2B contract values for project management and data analytics credentials.
- Parents:Procurement decision-makers for dependent learners, often prioritizing instructor credential transparency and progress visibility. US suburban districts in Virginia and Massachusetts show highest platform subscription rates.
- Lifelong Learners:Self-directed adults pursuing recreational or enrichment knowledge, typically price-sensitive and session-sporadic. Retiree segments in Australia and New Zealand sustain demand for language and arts instruction.
Students generate the highest session volume. Professionals command the steepest per-hour rates.
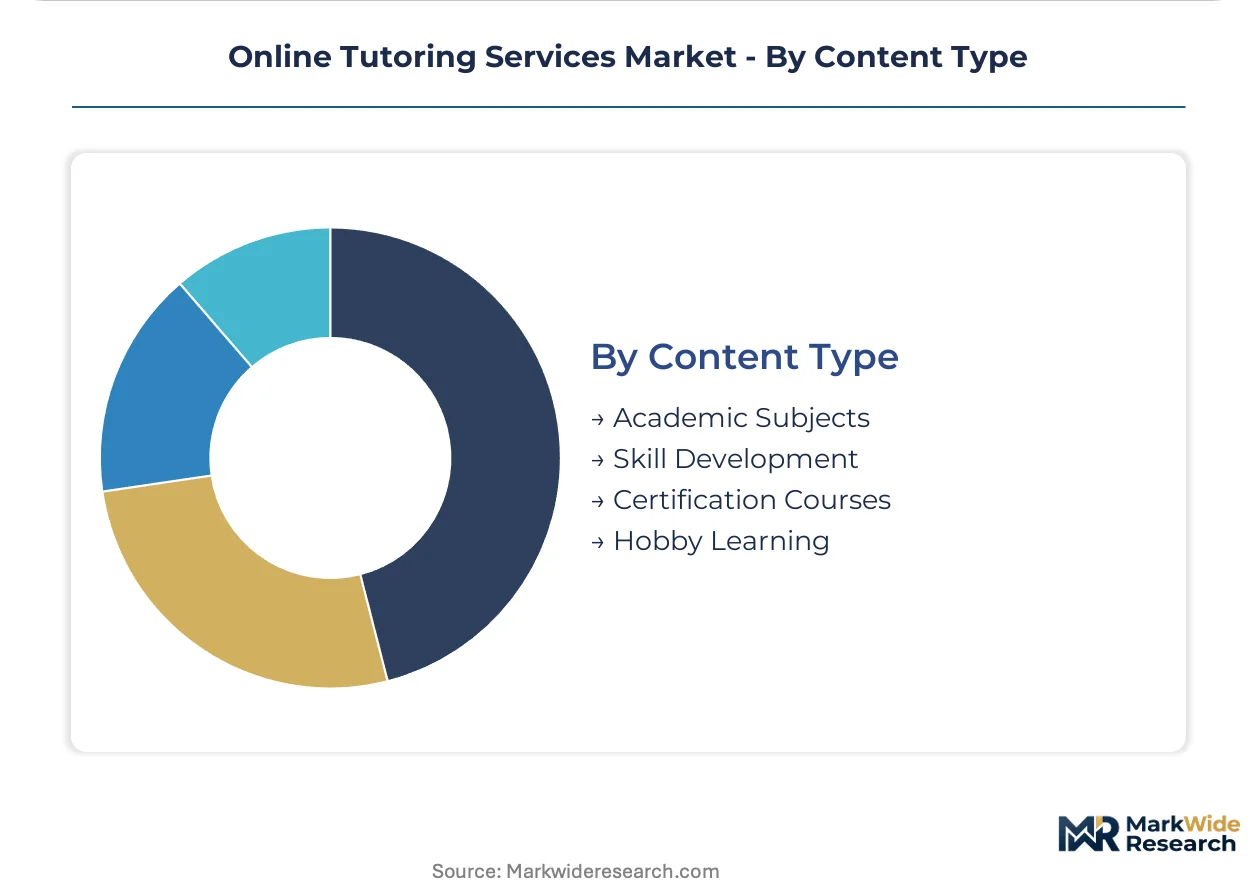
Content Type:
Content category shapes content production economics, instructor qualification requirements, and outcome verification complexity, with certification-aligned material facing steepest compliance burdens.
- Academic Subjects:Curriculum-aligned instruction in mathematics, sciences, humanities, and languages mapped to school or university standards. Texas and California state assessment alignment requirements drive platform content versioning costs.
- Skill Development:Practical competency building in areas like coding, design, or financial literacy, often delivered through project-based workflows. Bangalore and Hyderabad tech workers sustain demand for Python and cloud architecture tutoring.
- Certification Courses:Structured preparation for professional credentials with standardized examination gates. PMP, CFA, and AWS certification prep in Singapore and Dubai show highest B2B procurement rates.
- Hobby Learning:Recreational instruction in music, visual arts, or crafts, typically delivered through casual subscription tiers. Retiree concentrations in Florida and Arizona sustain demand for piano and watercolor instruction.
Academic Subjects dominate session count. Skill Development is climbing fastest as corporate reskilling budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border platform licensing generates net service exports from the United States and India while EU regulatory compliance costs tilt the trade balance toward imported technology infrastructure. Capital flows concentrate where subscription revenue scales fastest and localization requirements remain permissive.
United States
Federal Title I funding mandates subsidize tutoring access across low-income districts, with procurement concentrated in Texas and California urban corridors. The Department of Education coordinates supplemental educational services eligibility rules that shape vendor qualification requirements. District administrators in Houston and Los Angeles pilot integrated LMS platforms for after-school programs.
India
Urban centers in Maharashtra, Karnataka, and Tamil Nadu drive platform subscriptions for JEE and NEET competitive examination preparation. The National Education Policy framework encourages digital integration without prescribing technical standards, accelerating institutional procurement cycles. Bangalore and Delhi-NCR host the densest concentrations of venture-backed tutoring startups.
Germany
Corporate L&D budgets sustain B2B demand for technical certification tutoring, particularly in project management and data analytics credentials. The EU AI Act imposes algorithmic transparency obligations on automated tutoring recommendations, front-loading legal review cycles for platform operators. Munich and Frankfurt clusters show highest enterprise adoption rates for reskilling applications.
United Kingdom
Suburban parent segments in Greater London and Southeast England prioritize instructor credential transparency and progress visibility in platform selection. GDPR compliance requirements shape data architecture decisions for cross-border operators serving domestic learners. Oxford and Cambridge university towns sustain premium pricing for admissions preparation tutoring.
Singapore
Mathematics and physics tutoring segments show highest interactive whiteboard adoption intensity, driven by examination-focused parental investment. The national skills framework aligns platform content versioning with workforce credential requirements. Corporate training budgets in the central business district sustain English business communication demand.
Online Tutoring Services Market Key Industry Players
On the supply side, the industry is fragmented across asset-light platform operators and vertically integrated content producers. Three archetypes dominate: textbook-rental heritage players with recurring revenue anchoring, freemium funnel expansionists, and donor-funded zero-price competitors. Consolidation pressure concentrates on M&A activity targeting regional content libraries and strategic partnerships for cloud infrastructure redundancy.
Within the venture-backed expansionist tier, BYJU'S and Vedantu exemplify aggressive geographic scaling through freemium content funnels. Khan Academy occupies a position as the archetypal donor-funded operator competing on zero-price positioning while controlling R&D intensity through philanthropic capital. Chegg Inc. anchors the heritage-anchored tier, leveraging textbook rental infrastructure to sustain recurring revenue in homework help segments.
| Leading Market Players |
|---|
| Chegg Inc. |
| Tutor.com |
| Varsity Tutors |
| BYJU'S |
| Preply Inc. |
| Wyzant Inc. |
| Khan Academy |
| Vedantu |
| Brainfuse |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure concentration in AWS, Azure, and Google Cloud data centers anchors cost structures for synchronous tutoring platforms, compressing margin pools at the video delivery tier while concentrating pricing power with hyperscalers.
Pricing Analysis
Parental buyers in India's competitive exam corridors anchor premium pricing for one-on-one JEE and NEET preparation, while US Title I districts procure group sessions through federal mandate. Three-tier pricing structure across premium live instruction, standard asynchronous libraries, and economy self-paced tiers separates customization depth from content access scope. Cost compression in the group session tier is intensifying because enterprise buyers unbundle after-sales support from core subscriptions. Lifelong learners in Australia and New Zealand show highest price sensitivity; corporate L&D managers in Germany and Singapore show lowest.
Supply Chain Analysis
Upstream content production feeds from educator labor pools in India, the Philippines, and Eastern Europe, where STEM-specialized instructors command premium compensation that erodes unit economics. Raw material dependencies center on cloud compute cycles, video encoding software licenses, and adaptive algorithm training data. Single-source vulnerability in AWS us-east-1 and Azure West Europe regions creates uptime risk for synchronous session guarantees. Distribution runs through direct platform subscriptions, institutional procurement contracts, and mobile app stores with 15-30% revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress. Platform learning history and progress data accumulation create regulatory-entrenchment moats that complicate student migration between providers.
For Market Incumbents: Harden compliance infrastructure against EU AI Act documentation burdens before algorithmic feature deployment in France and Germany. Deepen backward integration into proprietary adaptive assessment engines to reduce third-party algorithm licensing exposure. Instructor credential authentication databases represent a consolidation lever against on-demand marketplace entrants.
For New Entrants and Emerging Players: Rural Indian districts outside Maharashtra and Tamil Nadu urban cores offer procurement white-space with lighter competitive density. Vocational reskilling applications for corporate L&D budgets in Netherlands and Japan represent underpenetrated B2B demand outside academic segments. Freemium content funnels with micro-session conversion paths offer the most penetrable go-to-market angle against semester-long incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward regional content library specialists with established instructor networks in high-stakes examination corridors. Long-term viability hinges on regulatory audit-readiness rather than pure user growth acceleration. Monitor EU AI Act enforcement patterns in Germany and France as inflection indicators for compliance-cost winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Documentation | EU AI Act compliance front-loads legal review cycles for French and German operators. |
| Cloud Infrastructure Redundancy | Multi-provider contracts mitigate AWS and Azure concentration risk for uptime guarantees. |
| Instructor Credential Authentication | Cross-border teaching license databases reduce operational friction for on-demand marketplaces. |
| Vocational Reskilling Platform Launch | Corporate L&D budgets in Netherlands and Japan sustain B2B contract values. |
| Micro-Session Pricing Unbundling | Urban Indian students purchase test-date-specific tutoring rather than semester packages. |
Research Approach
A spread of perspectives from platform product managers, district procurement officers, corporate L&D directors, and cloud infrastructure specialists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against SEC filings, EU regulatory documentation, National Education Policy framework texts, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked projections across service type, technology infrastructure, and target audience dimensions.
Demand-supply balance modeling anchored volume and value outputs across the projection horizon. Segmentation dimensions included service delivery format, platform technology layer, learner type, and content category. CAGRs derived from enrollment trend extrapolation, subscription pricing trajectory analysis, and institutional procurement cycle timing. Cloud infrastructure cost curves and instructor compensation inflation patterns fed specific forecast inputs for margin compression scenarios.
Practitioners should monitor EU AI Act enforcement intensity, India PDP Bill passage timelines, and Title I funding reauthorization debates for early signals. Forecasts reflect assumptions about regulatory stability, cloud pricing continuity, and competitive entry rates. Cross-checking against World Bank education expenditure data and national skills framework alignment metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Massive Open Online Courses Market