
 Massive Open Online Courses Market | 2026-2036
Massive Open Online Courses Market Size, Share, and Industry Trends Forecast 2026-2036
Massive Open Online Courses Market Intelligence
Generative AI integration into learning management systems is narrowing the gap between standardized curricula and personalized instruction at scale. Coursera, Inc. leverages university partnerships to sustain premium certificate credibility across professional segments. Udemy, Inc. anchors its position through marketplace breadth, while Pluralsight, LLC specializes in enterprise technology upskilling for cloud and cybersecurity roles.
Massive Open Online Courses are web-based educational programs designed for unlimited participation and open access via the internet, typically delivered through video lectures, automated assessments, and peer-reviewed assignments with modular completion tracking. Professional Development and Skill-Based Training course types attract the deepest employer reimbursement flows, while Subscription-Based pricing models concentrate recurring revenue and reduce customer acquisition cost burdens. Mobile Learning technology extends reach into bandwidth-constrained environments, though Learning Management Systems capture the highest enterprise attach rates for workforce analytics integration.
The US Department of Education and regional accrediting bodies shape credit-transfer eligibility and Title IV financial aid access for degree-aligned offerings. GDPR in Europe and India's Digital Personal Data Protection Act constrain cross-border learner data architectures, forcing localized infrastructure deployment. Stakeholders must weigh platform build-versus-partner decisions against shifting credential recognition standards and emerging national qualification frameworks.
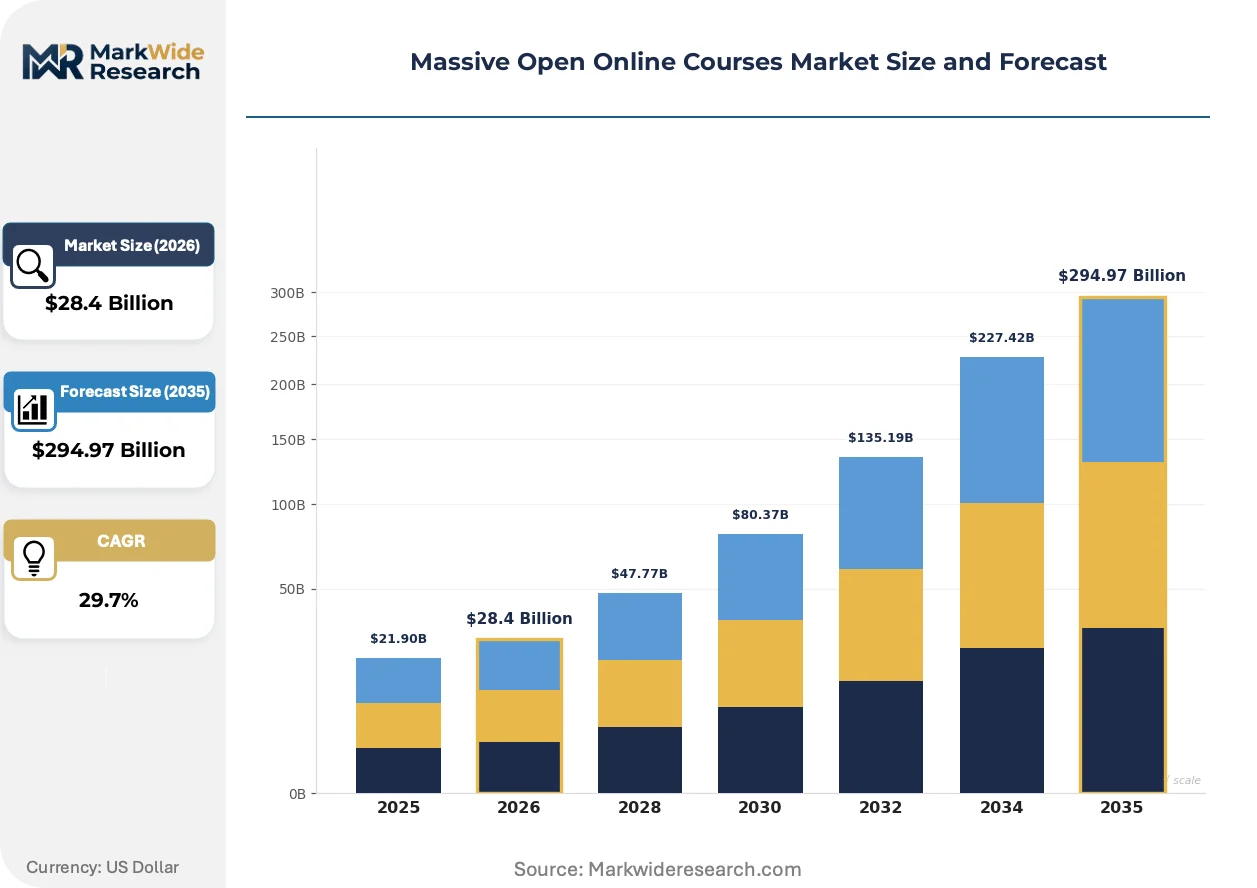
Market Dynamics
AI-driven adaptive learning engines are compressing course completion timelines by personalizing content sequencing in real time, forcing platform providers to reconfigure their infrastructure investments around inference costs rather than content production scale.
Growth Catalysts
- India's Digital Personal Data Protection Act:The regulation mandates localized learner data storage, accelerating domestic cloud infrastructure deployment and reducing latency for mobile-first course delivery across tier-2 and tier-3 cities.
- Fortune 500 corporate training budgets:These enterprises redirect spend toward scalable credentialing platforms as they seek measurable skill outcomes over traditional seminar-based professional development.
- Generative AI integration:Large language models embedded in learning management systems automate assessment generation and feedback loops, lowering instructional design costs while maintaining personalization depth.
Market Restraints
- Cross-border data architecture constraints:GDPR in Europe and India's Digital Personal Data Protection Act fragment platform infrastructure, forcing redundant regional deployments that inflate operational overhead.
- Credential recognition fragmentation:The US Department of Education and regional accrediting bodies maintain inconsistent credit-transfer standards, limiting degree-aligned MOOC portability across institutions.
- Bandwidth infrastructure gaps:Mobile learning penetration in dense growth corridors encounters last-mile connectivity limitations that degrade video streaming quality and completion rates.
Strategic Opportunities
- Brazil's national digital education mandates:Federal funding for workforce reskilling programs creates procurement pipelines for Portuguese-language professional development content at scale.
- Learning Management System convergence:Integration of workforce analytics with credential verification APIs opens enterprise attach-rate expansion beyond standalone course consumption.
- Subscription model migration:Recurring revenue concentration reduces customer acquisition cost burdens compared to per-course transactional pricing, improving lifetime value metrics for platform operators.
Industry Challenges
- Instructional designer talent scarcity:The specialized skill set combining pedagogy and AI tool operation commands premium compensation, constraining content velocity for mid-tier platforms.
- Title IV financial aid compliance:Eligibility requirements for US federal student aid impose administrative complexity that smaller providers struggle to navigate without dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Massive Open Online Courses Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $294.97 Billion |
| CAGR (2026 – 2036) | 29.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Course Type: Professional Development, Academic Courses, Certificate Programs, Skill-Based Training Technology: Mobile Learning, Virtual Classrooms, Learning Management Systems, Video Conferencing Target Audience: Working Professionals, College Students, Lifelong Learners, Corporate Employees Pricing Model: Free Courses, Subscription-Based, Pay Per Course, Donation-Based |
| Companies Covered | LinkedIn Corporation, Skillshare, Inc., Coursera, Inc., Udacity, Inc., FutureLearn Limited, Udemy, Inc., Pluralsight, LLC, Alison Technologies Limited, 2U, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Massive Open Online Courses Market Strategic Shifts & Innovations
Generative AI is collapsing the traditional trade-off between instructional quality and delivery scale, enabling platforms to automate content adaptation that previously required human intervention at every learner touchpoint.
Adaptive learning algorithms are collapsing the gap between standardized curricula and personalized instruction by sequencing modules based on real-time competency detection rather than fixed progression paths. Enterprise technology upskilling programs for cloud and cybersecurity roles deploy these engines most aggressively, compressing certification preparation timelines from months to weeks. The structural consequence is a shift in platform value capture from content libraries toward inference infrastructure and learner data refinement capabilities.
The EU AI Act establishes risk-classification requirements for educational algorithms that influence learner progression or assessment outcomes, imposing documentation and audit obligations on adaptive systems deployed in European markets. Platforms must now maintain algorithmic impact assessments and human oversight protocols that increase compliance overhead but create competitive moats against under-resourced entrants. Professional certificate programs aligned with European qualification frameworks face the steepest adaptation requirements, particularly those serving regulated industries like healthcare and finance.
Employer reimbursement flows are consolidating around skill-verification outcomes rather than seat-time completion, shifting procurement criteria toward platforms with integrated assessment-to-placement tracking. This pattern disrupts traditional marketplace breadth strategies that prioritized course volume over demonstrable competency signals. The United States exhibits the most pronounced behavioral shift, where Fortune 500 learning and development departments now mandate third-party skills audits before approving platform contracts.
Massive Open Online Courses Market Segmentation
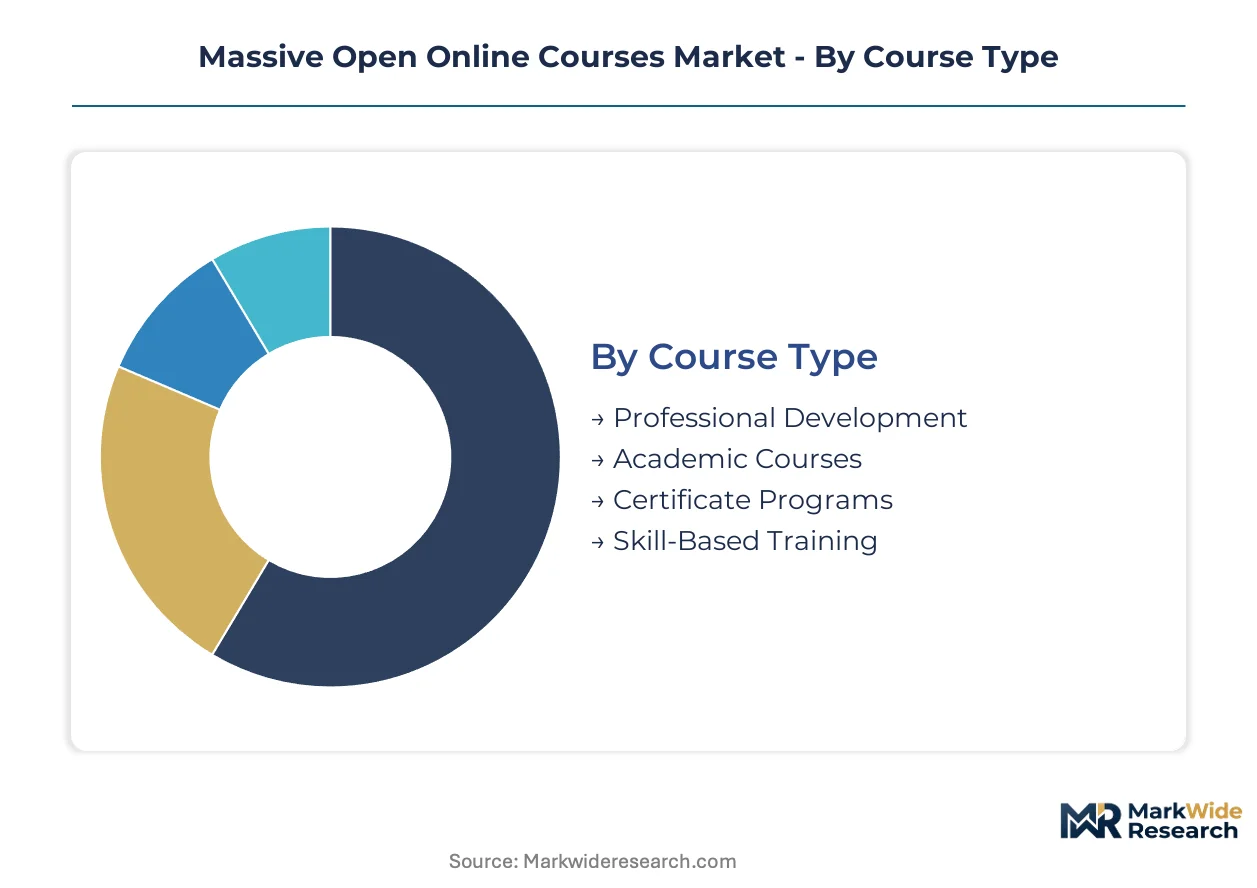
Platform operators configure infrastructure and monetization strategies around distinct learner profiles and delivery modalities. Segmentation reveals where credential credibility, engagement mechanics, and pricing elasticity concentrate revenue potential across the value chain.
Course Type:
Application focus determines content production investment, partnership requirements, and employer reimbursement eligibility.
- Professional Development:Modular curricula target role-specific competencies with immediate workplace applicability. Fortune 500 learning and development departments direct reimbursement flows here, prioritizing platforms with verified skill-to-placement tracking.
- Skill-Based Training:Competency-based modules compress certification timelines through intensive practice environments. Cloud and cybersecurity domains attract the deepest enterprise procurement in India and Brazil.
- Academic Courses:Degree-aligned offerings require regional accreditation partnerships for credit transfer eligibility.
- Certificate Programs:Stackable credentials bridge non-degree training and formal qualification pathways.
Professional Development commands the established base. The steepest expansion runs through Skill-Based Training.
Technology:
Delivery infrastructure shapes learner reach, engagement depth, and enterprise attach rates for workforce analytics.
- Learning Management Systems:Integrated platforms capture the highest enterprise adoption through credential verification APIs and progress dashboards. GDPR and India's Digital Personal Data Protection Act force localized deployments that inflate operational overhead but deepen institutional stickiness.
- Mobile Learning:Lightweight delivery extends into bandwidth-constrained environments across tier-2 and tier-3 Indian cities. Last-mile connectivity gaps degrade video streaming quality and compress completion rates in dense growth corridors.
- Virtual Classrooms:Synchronous environments support cohort-based progression with real-time instructor interaction.
- Video Conferencing:Standalone tools integrate with broader platform stacks for office-hour and peer collaboration functions.
Learning Management Systems anchor enterprise procurement. Mobile Learning is climbing the fastest as infrastructure penetration deepens.
Target Audience:
Customer type dictates pricing tolerance, engagement patterns, and the balance between individual and institutional payment responsibility.
- Working Professionals:Time-constrained learners prioritize credential velocity and employer reimbursement eligibility. United States Fortune 500 firms now mandate third-party skills audits before approving platform contracts for this segment.
- Corporate Employees:Enterprise-provisioned access concentrates recurring revenue and reduces customer acquisition cost burdens. Procurement criteria shift from course volume toward demonstrable competency verification.
- College Students:Price-sensitive demand gravitates toward free tiers and financial aid-aligned degree pathways.
- Lifelong Learners:Discretionary engagement supports breadth-focused marketplace models with lower completion expectations.
Working Professionals sustain premium pricing tiers. Corporate Employees are gaining share fastest as enterprise training budgets consolidate.
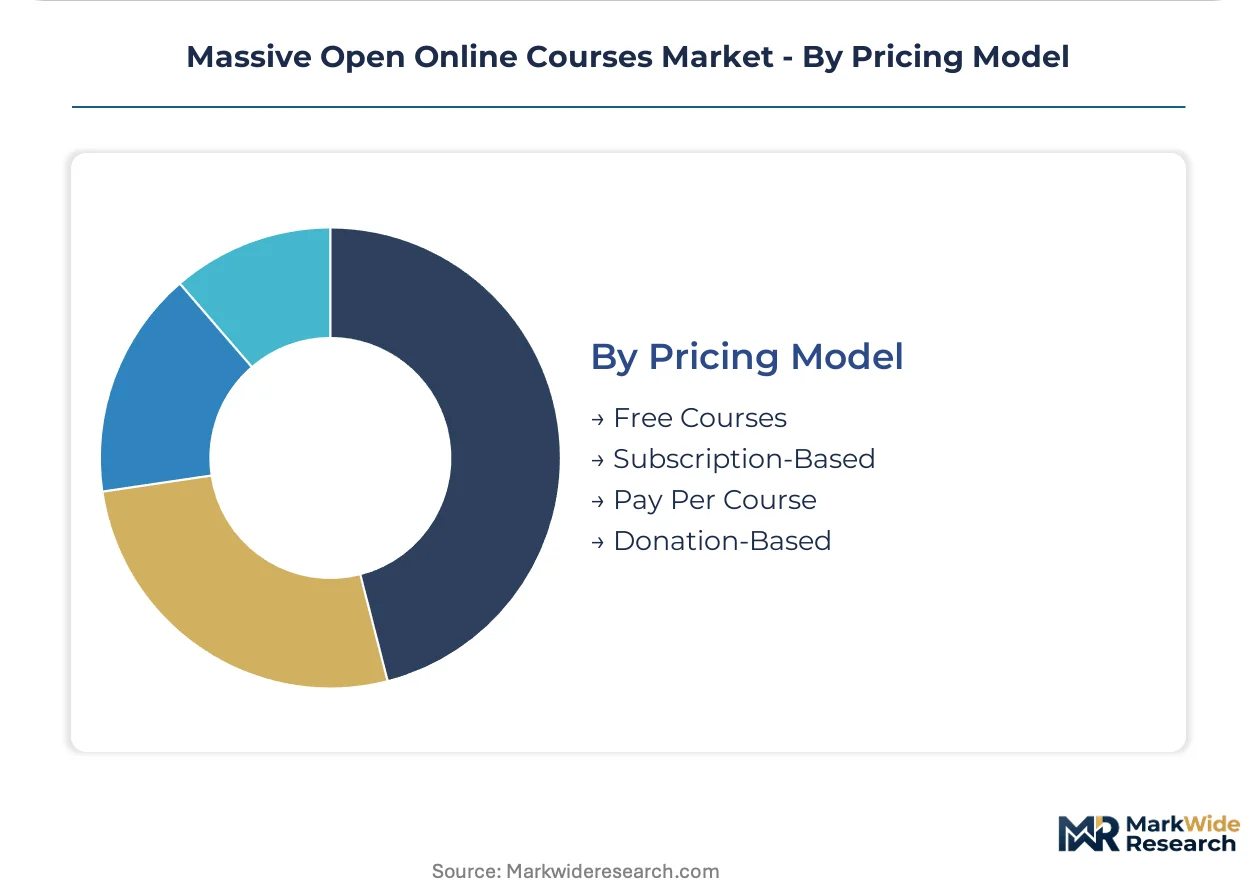
Pricing Model:
Revenue architecture determines customer lifetime value, acquisition cost recovery, and platform cash flow stability.
- Subscription-Based:Recurring revenue concentration improves unit economics and funds continuous content refresh. This model reduces customer acquisition cost burdens compared to transactional alternatives.
- Pay Per Course:Transactional pricing captures high-intent learners with specific credential goals but elevates re-engagement friction.
- Free Courses:Freemium tiers drive top-of-funnel acquisition and upsell conversion into paid credentials.
- Donation-Based:Philanthropic support sustains open-access missions with limited scalability for platform infrastructure investment.
Subscription-Based pricing anchors sustainable platform economics. Pay Per Course retains relevance for specialized certification preparation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports MOOC platform services to Fortune 500 enterprises across the United States and Europe, while Brazil delivers Portuguese-language professional development content to corporate clients throughout Latin America and the Iberian Peninsula.
United States
Fortune 500 learning and development departments now mandate third-party skills audits before approving platform contracts. The US Department of Education and regional accrediting bodies maintain inconsistent credit-transfer standards that limit degree-aligned MOOC portability across institutions. Corporate training budgets in New York and California redirect spend toward scalable credentialing platforms with measurable skill outcomes.
India
Youth demographics and national digital education mandates fuel dense growth corridors outside metropolitan centers. The Digital Personal Data Protection Act mandates localized learner data storage, accelerating domestic cloud infrastructure deployment across tier-2 and tier-3 cities. Bangalore and Hyderabad host the highest concentration of platform engineering talent and mobile-first course delivery operations.
Brazil
Federal funding for workforce reskilling programs creates procurement pipelines for Portuguese-language professional development content at scale. ANVISA and national education regulators shape credential recognition standards for healthcare and finance sector training modules. São Paulo anchors corporate adoption while Rio de Janeiro supports creative industry upskilling clusters.
Germany
Enterprise technology upskilling demand concentrates in automotive and industrial automation sectors seeking cloud and cybersecurity certification pathways. The EU AI Act imposes documentation and audit obligations on adaptive learning systems deployed in European markets. Munich and Berlin house the densest concentrations of B2B platform procurement decision-makers.
United Kingdom
Professional certificate programs aligned with European qualification frameworks face steep adaptation requirements under post-Brexit regulatory divergence. GDPR compliance frameworks constrain cross-border learner data architectures, forcing redundant regional deployments. London's financial services sector drives demand for stackable credentials bridging non-degree training and formal qualification pathways.
Massive Open Online Courses Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that fragments between premium credential platforms and breadth-focused marketplaces. The vendor base organizes into three tiers: university-partnered credential providers, open marketplace aggregators, and enterprise-specialized technology upskilling platforms. Consolidation pressure intensifies as Fortune 500 procurement criteria shift from course volume toward demonstrable competency verification. Dominant competitive moves include strategic partnerships with accrediting bodies and geographic expansion through localized content production.
Within the university-partnered credential tier, Coursera, Inc. and FutureLearn Limited exemplify platform archetypes that leverage institutional partnerships to sustain premium certificate credibility. Udemy, Inc. anchors the marketplace breadth segment with transactional course access models. Pluralsight, LLC occupies a specialized position in enterprise technology upskilling for cloud and cybersecurity roles.
| Leading Market Players |
|---|
| LinkedIn Corporation |
| Skillshare, Inc. |
| Coursera, Inc. |
| Udacity, Inc. |
| FutureLearn Limited |
| Udemy, Inc. |
| Pluralsight, LLC |
| Alison Technologies Limited |
| 2U, Inc. |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure concentration in the United States and India anchors margin capture downstream, where Learning Management System operators with localized data centers command premium enterprise attach rates against mobile-first delivery competitors.
Pricing Analysis
Legacy per-course transactional models face compression from next-generation subscription architectures that concentrate recurring revenue and reduce customer acquisition cost burdens. Pricing stratifies across premium credential tiers with university partnership backing, standard marketplace breadth offerings, and economy freemium pathways with limited assessment depth. Cost compression in the standard tier intensifies as generative AI tools automate instructional design and lower content production barriers. Corporate Employees exhibit the lowest price sensitivity due to enterprise-provisioned access, while College Students gravitate toward free tiers and financial aid-aligned pathways.
Supply Chain Analysis
Instructional content feedstock draws from specialized talent pools concentrated in the United States, India, and Brazil, where pedagogical expertise intersects with AI tool operation capabilities. Raw material dependencies center on cloud compute infrastructure, video streaming bandwidth, and credential verification API integrations. Single-source vulnerability in adaptive learning algorithm providers creates concentration risk for mid-tier platforms lacking in-house inference capabilities. Distribution runs through direct-to-learner digital channels and enterprise procurement contracts with Fortune 500 learning and development departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
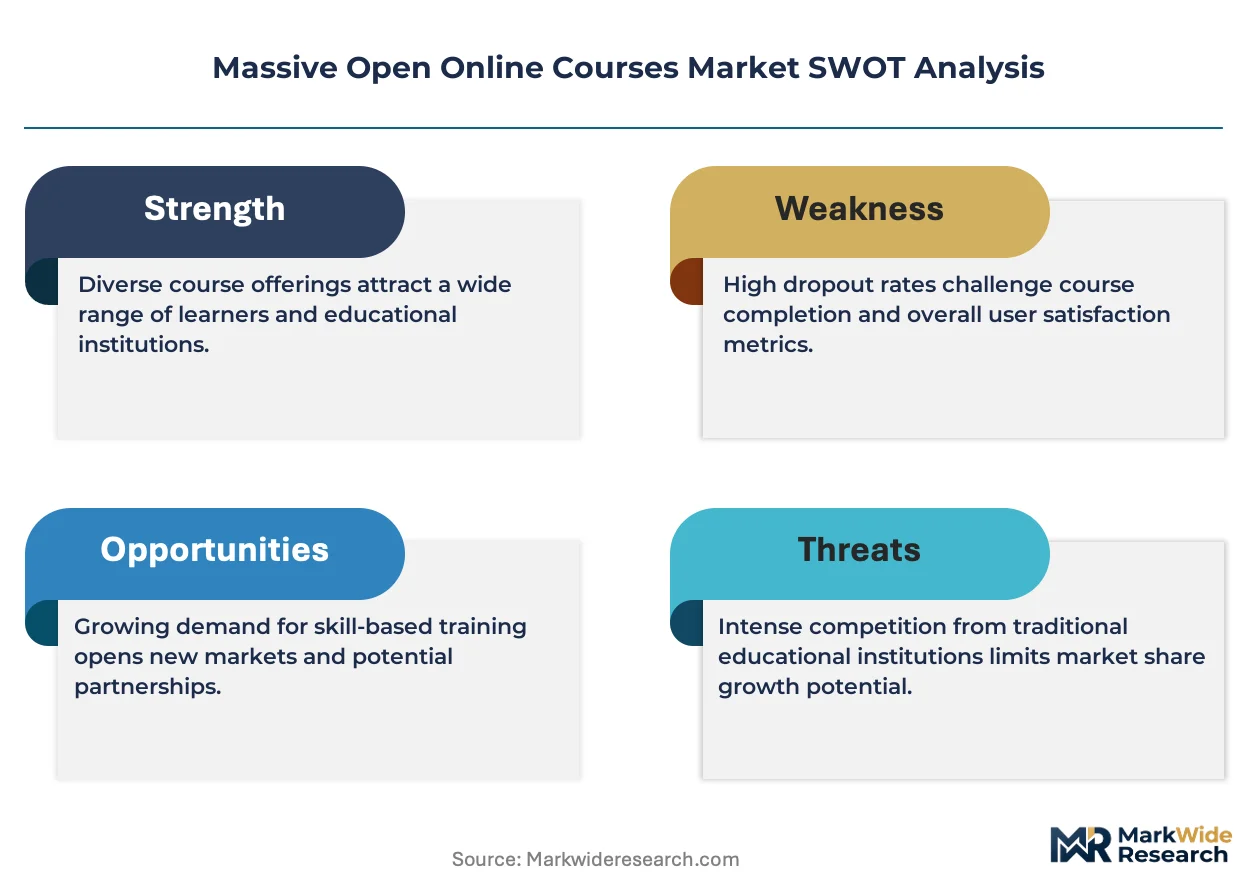
The Massive Open Online Courses Market sits at a platform-economics inflection where credential interoperability across national qualification frameworks will determine which operators capture enterprise training budget consolidation.
For Market Incumbents: Harden data residency compliance through redundant regional cloud deployments that satisfy India's Digital Personal Data Protection Act and GDPR requirements without latency degradation. Fortify university partnership exclusivity against emerging marketplace aggregators by embedding stackable credentials into European qualification frameworks. Deepen workforce analytics integration to defend enterprise attach rates as procurement criteria shift from course volume toward demonstrable competency verification.
For New Entrants and Emerging Players: Build out Portuguese-language professional development content pipelines targeting Brazil's federal workforce reskilling procurement channels. Exploit tier-2 and tier-3 Indian cities where mobile-first delivery gaps persist and domestic cloud infrastructure deployment lags metropolitan penetration. Pursue white-label Learning Management System partnerships with regional corporate training providers rather than competing directly for Fortune 500 contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward enterprise-specialized technology upskilling platforms with cloud and cybersecurity certification concentration rather than breadth-focused marketplace models facing margin compression. Long-term viability hinges on inference infrastructure ownership and learner data refinement capabilities rather than content library scale. Watch for EU AI Act compliance certification as an inflection signal separating regulated-market-ready operators from geographically constrained competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding credential verification APIs into enterprise HR systems deepens institutional stickiness against standalone competitors. |
| Geographic Expansion | Localized content production in Portuguese and Hindi captures procurement flows from Brazil and India's national digital education mandates. |
| Strategic Partnership | University accreditation alliances sustain premium certificate credibility as employer reimbursement flows consolidate around verified outcomes. |
| Acquisition of Specialist Firm | Purchasing adaptive learning algorithm developers secures inference infrastructure ownership and reduces dependency on third-party AI providers. |
| Product Launch | Mobile-optimized delivery for bandwidth-constrained environments extends reach into tier-2 and tier-3 Indian growth corridors. |
Research Approach
Cross-validation between primary interviews with platform engineering directors, enterprise learning and development officers, instructional designers, and regulatory compliance leads anchors the qualitative findings against secondary sources including SEC filings from listed operators, EU AI Act implementation guidance, and India's Digital Personal Data Protection Act compliance documentation. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across course type, technology delivery modality, target audience archetype, and pricing model dimensions.
Calibration against historical completion rate trajectories and enterprise procurement pattern shifts shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include professional development versus skill-based training intensity, Learning Management System versus mobile-first delivery infrastructure, and subscription versus transactional revenue architecture. CAGRs derive from learner enrollment elasticity functions and corporate training budget reallocation velocity observed through the analysis window, with AI-driven personalization adoption curves and credential recognition standardization progress serving as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive infrastructure localization moves by hyperscale cloud providers or sudden shifts in US Department of Education credit-transfer policy would shift outcomes materially. Cross-checking against enterprise learning and technology spend surveys from established HR consultancies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market