
 Africa E-Learning Market | 2026-2036
Africa E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Africa E-Learning Market Intelligence
South African edtech infrastructure is consolidating around cloud-native delivery networks. Nafham leverages Arabic-localized video libraries to anchor Egyptian K-12 engagement. Ubongo sustains Swahili-language animation pipelines across East African broadcast and mobile channels. CoGrammar specializes in software development bootcamps that compete for corporate training budgets in Cape Town and Johannesburg.
Africa e-learning denotes digitally delivered educational content accessed through internet-connected devices, typically requiring bandwidth above 2 Mbps for synchronous video and below 500 kbps for adaptive text-based modules, designed to extend formal instruction beyond physical classroom boundaries. Mobile learning dominates volume due to smartphone penetration rates that outpace fixed broadband across the continent, while corporate end users concentrate margin pools through subscription-based workforce upskilling contracts. Interactive modules represent the fastest-growing content format as institutions shift from passive video consumption toward simulation-based assessment.
Nigeria's National Universities Commission mandates minimum digital content standards for distance programs, while South Africa's Council on Higher Education audits online degree equivalency. Kenya's Communications Authority enforces data cost transparency rules that directly shape platform pricing and student access. Stakeholders must monitor spectrum allocation decisions and national content localization requirements to anticipate which delivery modes achieve regulatory preference.
Market Dynamics
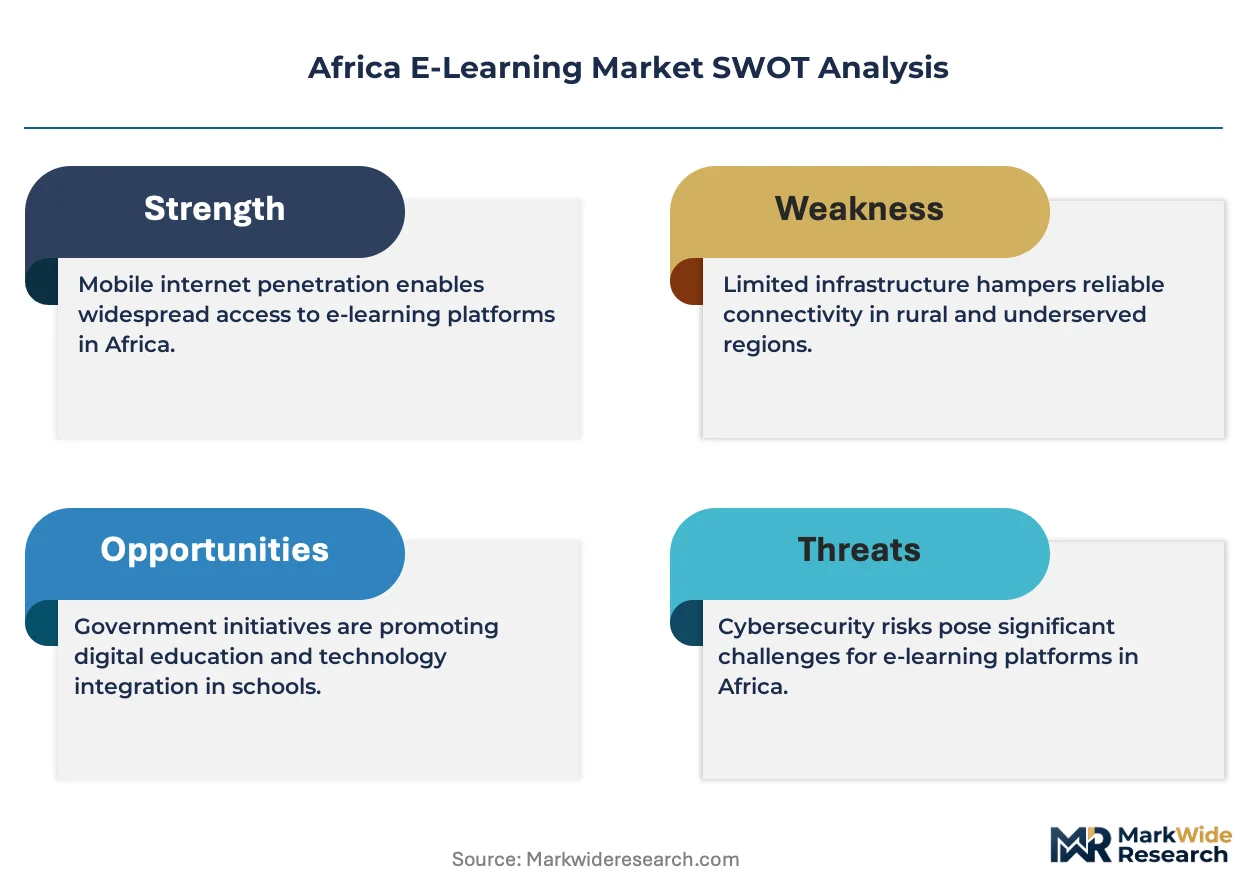
Mobile network expansion across Kenya and Nigeria is compressing platform delivery costs while Francophone content gaps create asymmetric competition windows for localized providers.
Growth Catalysts
- Kenya's Communications Authority data cost transparency rules:These regulations force platform pricing visibility that expands student access across East African markets.
- Smartphone penetration outpacing fixed broadband:Mobile learning volumes surge as device affordability unlocks K-12 segments previously blocked by infrastructure gaps.
- UNESCO education targets:International procurement standards reshape national bidding processes and accelerate public-sector platform adoption.
Market Restraints
- Bandwidth threshold fragmentation:Synchronous video requires 2 Mbps while adaptive text modules function below 500 kbps, forcing dual-track content development that raises production costs.
- Francophone West Africa content concentration:French-language curriculum gaps limit platform scalability in Senegal, Côte d'Ivoire, and Mali despite addressable demand.
- Spectrum allocation uncertainty:National regulator decisions on 4G and 5G band licensing create delivery mode risk for live interactive modules.
Strategic Opportunities
- Swahili-language animation pipelines:East African broadcast-mobile convergence offers content localization advantages that French-dominant competitors cannot easily replicate.
- Egyptian Arabic video libraries:North African K-12 engagement remains underpenetrated relative to Anglophone markets, creating first-mover positioning potential.
- South African corporate training budgets:Software development bootcamps tap into Cape Town and Johannesburg enterprise upscaling demand through subscription workforce contracts.
Industry Challenges
- Cloud-native infrastructure migration:Legacy server architectures in established institutions require capital-intensive retooling to match latency demands of simulation-based assessment formats.
- Cross-border degree equivalency audits:South Africa's Council on Higher Education and Nigeria's National Universities Commission maintain divergent online credential standards that complicate multi-country platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa E-Learning Market |
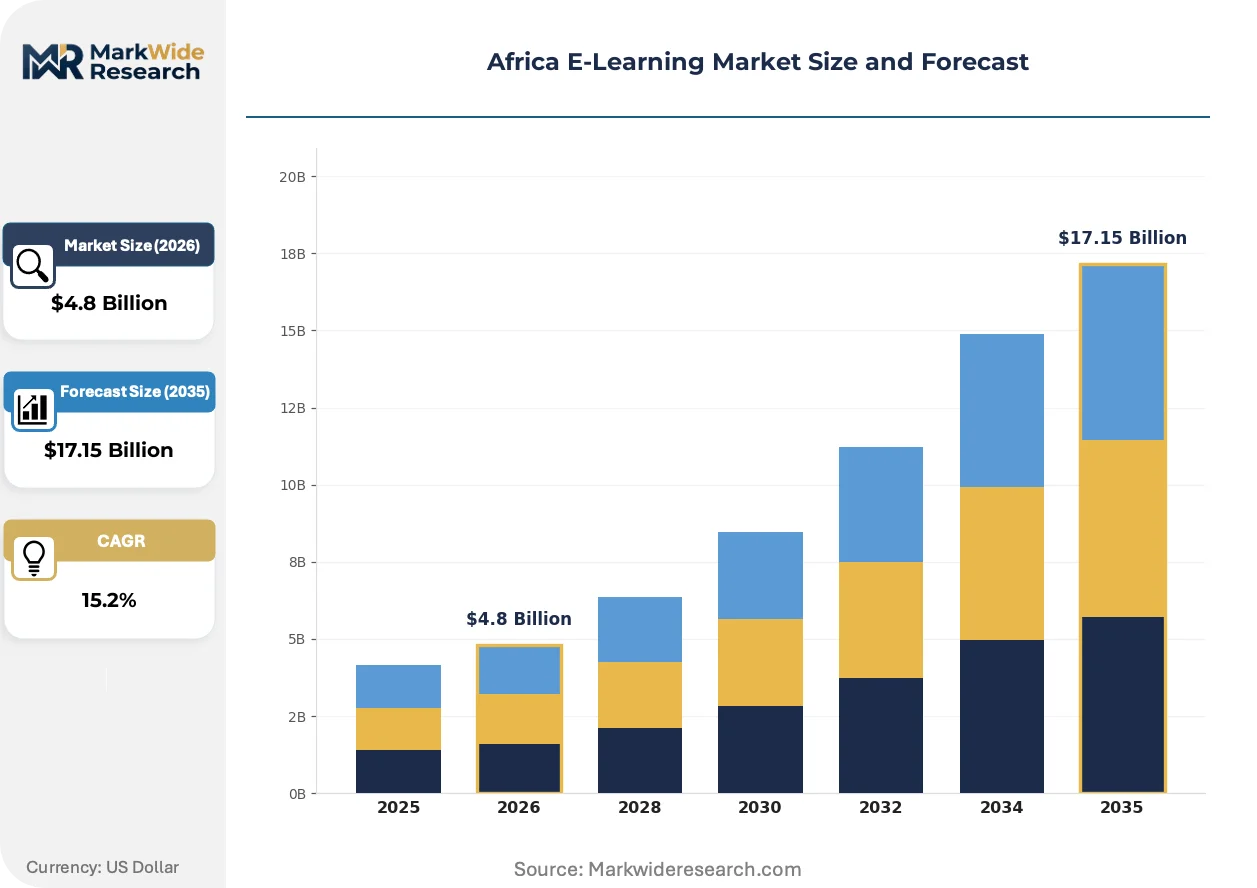
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $17.15 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online Learning, Blended Learning, Mobile Learning, Self-Paced Learning End User: Schools, Universities, Corporate, Individuals Content Type: E-Books, Video Courses, Webinars, Interactive Modules Technology: LMS, AR, VR, Cloud Computing |
| Companies Covered | Nafham, Vambo Academy, Go1, Blaqgold Holdings, Ello, Ubongo, CoGrammar, Epsionyx, Edukoya, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa E-Learning Market Strategic Shifts & Innovations
Interactive assessment formats are compressing passive video consumption models as institutions demand measurable competency verification rather than completion metrics.
Adaptive learning algorithms that personalize content sequencing based on real-time performance data are overtaking static courseware in K-12 procurement evaluations. Kenyan and Nigerian education ministries now weight interactivity metrics in platform tenders. This compression favors vendors with in-house assessment engineering over video-library aggregators.
Nigeria's National Universities Commission mandates minimum digital content standards that force distance program providers to document learning outcome equivalence. The regulation compresses informal course offerings from uncredentialed platforms. Private universities in Lagos and Abuja are responding by partnering with accredited content developers rather than building proprietary modules.
Corporate buyers in South African tech hubs now unbundle training contracts from annual software licensing agreements. Cape Town and Johannesburg enterprises negotiate outcome-verified bootcamp subscriptions tied to placement guarantees rather than seat-time pricing. This procurement rotation pressures generalized e-learning platforms to demonstrate hiring pipeline connections or lose enterprise accounts to specialized workforce developers.
Africa E-Learning Market Segmentation
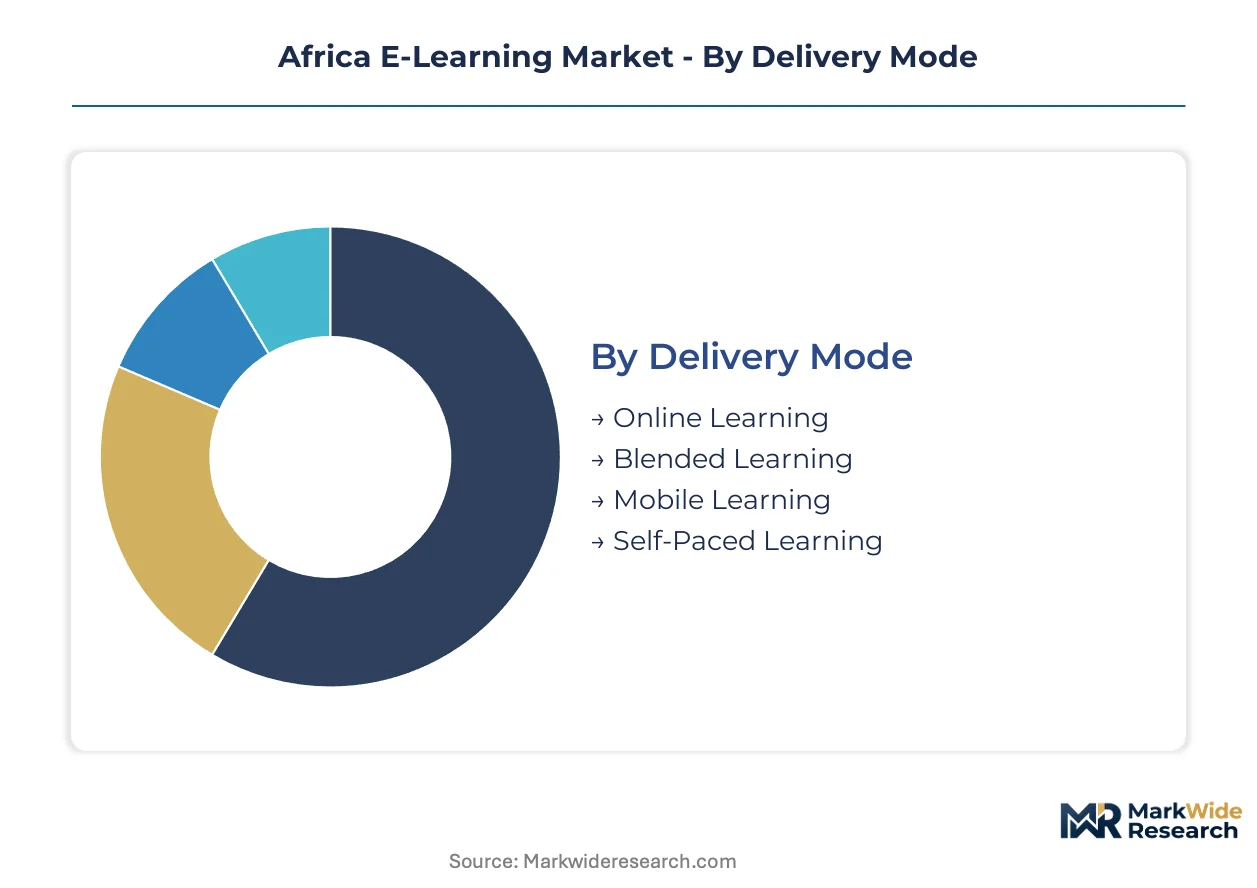
Segmentation in African e-learning reveals how infrastructure constraints and language diversity fragment addressable demand. Delivery mode selection directly determines capital requirements and geographic reach. Content format choices shape production economics and regulatory compliance across national education systems.
Delivery Mode:
Capital intensity peaks with synchronous infrastructure while self-paced models minimize fixed costs.
- Online Learning:Real-time video delivery demands server clusters and CDN nodes with sub-100ms latency to major cities. Nigerian universities in Lagos and Abuja concentrate procurement here as the National Universities Commission mandates live instructor contact hours for degree equivalence.
- Mobile Learning:Adaptive compression algorithms optimize content for 3G and 4G bandwidth variability. Kenyan K-12 adoption surges under Communications Authority data transparency rules that reduce student cost barriers.
- Blended Learning:Combines physical campus sessions with digital supplementation. South African institutions favor this format to satisfy Council on Higher Education audit requirements for contact hour documentation.
- Self-Paced Learning:Asynchronous modules function below 500 kbps. Francophone West African learners access these through downloaded content packages where live connectivity remains intermittent.
Most installed capacity flows through Mobile Learning. Expansion is steepest in Online Learning.
End User:
Customer type determines contract structure and pricing power in procurement negotiations.
- Corporate:Subscription-based workforce upskilling contracts with placement guarantees dominate revenue per seat. Cape Town and Johannesburg tech enterprises unbundle training from software licensing, demanding outcome verification rather than completion metrics.
- Universities:Public institutions in Egypt and Nigeria drive platform standardization through national accreditation mandates. Procurement concentrates around learning management systems with integrated assessment engines.
- Schools:K-12 ministries in Kenya and Tanzania weight interactivity metrics in tender evaluations. Budget constraints favor low-bandwidth solutions with offline functionality.
- Individuals:Direct-to-consumer sales rely on mobile money integration and micro-payment structures. Swahili and Arabic localization unlocks penetration in East and North African markets.
Corporate contracts command premium pricing. Individual subscriptions are climbing the fastest.
Content Type:
Production cost tiers separate premium interactive formats from commoditized text libraries.
- Interactive Modules:Simulation-based assessment engines require specialized engineering talent and cloud-native architecture. Kenyan and Nigerian education ministries now mandate these formats in procurement scoring.
- Video Courses:Arabic-localized libraries anchor Egyptian K-12 engagement while Swahili animation pipelines sustain Ubongo's East African broadcast-mobile convergence. Production costs scale with dubbing and cultural adaptation.
- Webinars:Live expert sessions demand synchronous infrastructure with failover redundancy. Corporate buyers in South African tech hubs use these for rapid skill updates in software development tracks.
- E-Books:Static text modules function on minimal bandwidth. Francophone West African markets rely heavily on these where French-language curriculum gaps limit video library availability.
Video Courses hold the largest installed base. Interactive Modules are gaining share fastest.
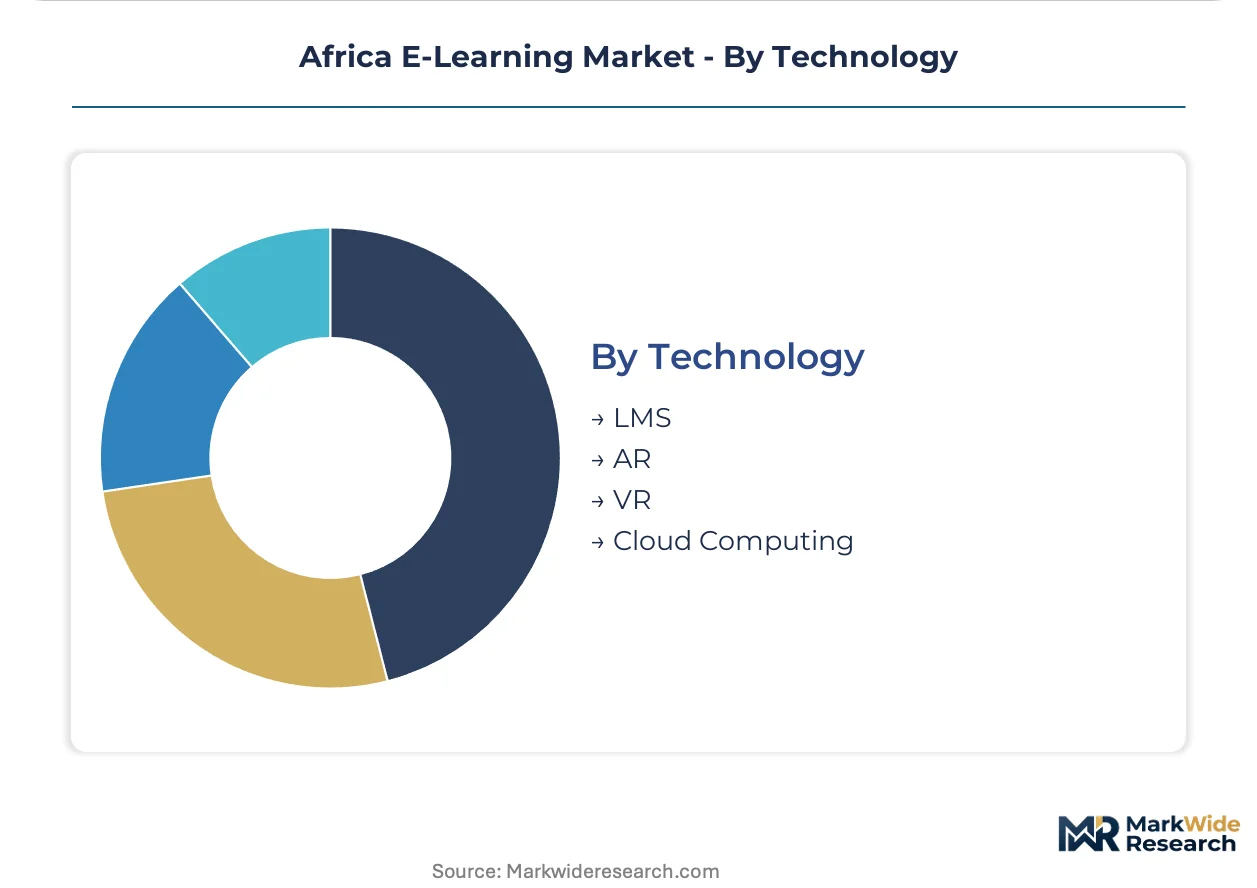
Technology:
Platform architecture choices determine scalability and integration complexity with legacy systems.
- Cloud Computing:Elastic infrastructure enables rapid scaling across peak academic calendars. South African institutions lead migration as established universities retool server architectures to match latency demands of simulation-based formats.
- LMS:Learning management systems form the integration layer for content delivery and assessment tracking. Nigerian National Universities Commission mandates minimum functionality standards that compress informal platform offerings.
- AR:Augmented reality modules require device capability thresholds that limit addressable market. Medical and technical training applications in Egyptian universities pilot these formats.
- VR:Virtual reality demands specialized hardware procurement that corporate training budgets in Johannesburg occasionally accommodate for high-stakes simulation environments.
LMS deployments constitute the dominant installed technology. Cloud Computing infrastructure shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform localization strategies as providers migrate toward jurisdictions with clearer accreditation pathways and lower content compliance costs. National broadband policies and education procurement standards create divergent cost-of-compliance environments across the continent.
Nigeria
Lagos and Abuja universities drive demand for synchronous video infrastructure under National Universities Commission mandates. The Commission's minimum digital content standards compress informal platform offerings while forcing accredited partnerships. Private institutions in these cities now outsource module development to compliant vendors rather than building proprietary systems.
Kenya
Communications Authority data transparency rules reduce student cost barriers and accelerate K-12 mobile adoption. Nairobi anchors East African platform development with broadcast-mobile convergence clusters. Local ministries weight interactivity metrics in tender evaluations, favoring vendors with assessment engineering capabilities over video aggregators.
South Africa
Cape Town and Johannesburg corporate training budgets unbundle from software licensing agreements. The Council on Higher Education audits online degree equivalency, creating compliance complexity for multi-country deployments. Cloud-native infrastructure migration concentrates among established universities retooling server architectures.
Egypt
Cairo and Alexandria K-12 engagement remains underpenetrated relative to Anglophone markets. Arabic-localized video libraries anchor North African platform strategies. National regulators emphasize learning outcome documentation, compressing informal course offerings from uncredentialed providers.
Senegal
Dakar represents the Francophone West African opportunity where French-language curriculum gaps limit incumbent scalability. Self-paced downloaded content packages dominate where live connectivity remains intermittent. Localization advantages for Swahili and Arabic competitors create asymmetric competition windows.
Africa E-Learning Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue language-specific localization and corporate workforce verticals. The vendor base clusters around three strategic archetypes: mobile-first K-12 platforms, Arabic and Swahili content specialists, and corporate bootcamp operators. Consolidation pressure intensifies as national accreditation mandates raise compliance costs. Dominant competitive moves include strategic partnerships with accredited universities and geographic expansion through localized content pipelines.
Within the localization-specialist tier, Nafham and Ubongo exemplify regional content anchoring strategies. Nafham represents Egyptian Arabic video library approaches, while Ubongo occupies Swahili-language animation positioning across East African markets. CoGrammar sits within the corporate training archetype, targeting software development bootcamp contracts in South African tech hubs.
| Leading Market Players |
|---|
| Nafham |
| Vambo Academy |
| Go1 |
| Blaqgold Holdings |
| Ello |
| Ubongo |
| CoGrammar |
| Epsionyx |
| Edukoya |
| Others |
Cost & Logistics Intelligence
Content localization costs flow from Egyptian and Kenyan production studios through tiered platform pricing, with Arabic and Swahili dubbing expenses compressing margins at the economy tier while premium corporate subscriptions absorb these overheads through outcome-based contracts.
Pricing Analysis
Platform licensing fees to universities and K-12 ministries anchor the pricing structure, with subscription tiers separating accredited degree pathways from informal skill modules. Price differentiation hinges on assessment engine sophistication and national accreditation status, with Nigerian National Universities Commission compliance commanding substantial premiums. Pricing pressure stems from mobile data cost transparency rules in Kenya that force student-facing price visibility. Individual learners in Francophone West Africa exhibit highest price sensitivity, while South African corporate training budgets show lowest elasticity due to placement-guarantee procurement.
Supply Chain Analysis
Cross-border content delivery costs concentrate around submarine cable landing points in Lagos, Mombasa, and Cape Town, with last-mile mobile distribution tethered to national carrier pricing. Cloud infrastructure draws from South African server clusters, Egyptian CDN nodes, and Kenyan edge computing investments. Content production relies on Cairo animation studios, Nairobi broadcast facilities, and Johannesburg software engineering academies. Single-source vulnerability sits with pan-African mobile network operators controlling spectrum allocation timelines. Distribution runs through ministry procurement portals in Nigeria and Kenya, direct-to-consumer app stores for individual subscriptions, and enterprise sales teams targeting Johannesburg and Cape Town corporate buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in corporate training verticals where outcome-verified contracts displace seat-time pricing, and in Arabic-localized content where production cost amortization across North African markets outpaces Swahili-language competition.
For Market Incumbents: Cement first-mover positioning in Egyptian Arabic video libraries and Swahili animation pipelines through exclusive broadcaster partnerships that block competitor access to established distribution channels. Invest in cloud-native assessment engineering capabilities before Kenyan and Nigerian ministry tenders mandate interactivity metrics as scoring requirements. Threat of specialized workforce bootcamps unbundling corporate contracts demands preemptive hiring-pipeline demonstration. For New Entrants and Emerging Players: Mobile network operators offer partnership pathways into Francophone West African markets where French-language curriculum gaps limit incumbent scalability. Target Senegal and Côte d'Ivoire self-paced learning segments with downloaded content packages designed for intermittent connectivity. Go-to-market execution should prioritize ministry pilot programs that convert to multi-year procurement contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where national accreditation mandates raise compliance costs beyond bootstrap capital reach, compressing informal platform viability. Long-term positioning favors acquisition of Arabic and Swahili content specialists with established broadcaster relationships and ministry procurement track records. Signal to monitor: Nigerian National Universities Commission expansion of digital content standards to private university segments currently outsourcing module development.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Partnership | Compliant vendor status with Nigerian National Universities Commission unlocks public university procurement. |
| Localization Pipeline | Swahili and Arabic content libraries establish defensible geographic moats against Anglophone competitors. |
| Corporate Outcome Contracting | Placement-guaranteed bootcamp subscriptions capture premium pricing from Johannesburg and Cape Town enterprises. |
| Mobile Data Integration | Direct carrier billing partnerships reduce student cost barriers under Kenyan Communications Authority transparency rules. |
| Assessment Engine Development | Simulation-based competency verification meets Kenyan and Nigerian ministry interactivity tender requirements. |
Research Approach
Bottom-up corporate training and K-12 adoption modeling reconciled against top-down platform infrastructure deployment tracking forms the analytical core. Primary interviews engaged chief learning officers at Lagos and Johannesburg enterprises, curriculum directors at Egyptian and Kenyan education ministries, platform engineering leads at mobile-first providers, and procurement officers at Nigerian public universities. Secondary validation drew from National Universities Commission accreditation filings, Communications Authority data cost reports, Council on Higher Education audit documentation, and UNESCO education target progress assessments.
Historical trendline analysis of mobile penetration rates, smartphone affordability curves, and ministry procurement volumes established baseline trajectory assumptions. Segmentation modeling spanned delivery mode, end user archetype, content format, and technology stack dimensions across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating bandwidth threshold fragmentation and language localization cost curves. Forecast inputs included national broadband policy implementation timelines and spectrum allocation decision schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 4G and 5G spectrum allocation delays, Francophone content production cost inflation, and cross-border degree equivalency harmonization failures. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Global Virtual Classroom Market