
 Global Online Tutoring Software Market | 2026-2036
Global Online Tutoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Tutoring Software Market Foresight
The capital-intensity divergence between cloud-native specialists and legacy publishers is bifurcating competitive dynamics in online tutoring software. Pearson PLC leverages its institutional licensing infrastructure to sustain long-term contracts with university systems. BYJU'S anchors its position through aggressive geographic expansion and proprietary content libraries across multiple curricula.
Online tutoring software encompasses digital platforms that deliver synchronous instruction, asynchronous content delivery, and learner analytics through web interfaces and mobile applications, typically requiring sub-200ms latency for real-time video interaction and AES-256 encryption for student data protection. Cloud-based deployment leads in new implementations due to lower upfront infrastructure requirements and automatic scalability during peak enrollment periods. Live classes command premium pricing relative to self-paced learning modules, while assessment and analytics tools represent the fastest-growing solution type as institutions prioritize measurable learning outcomes.
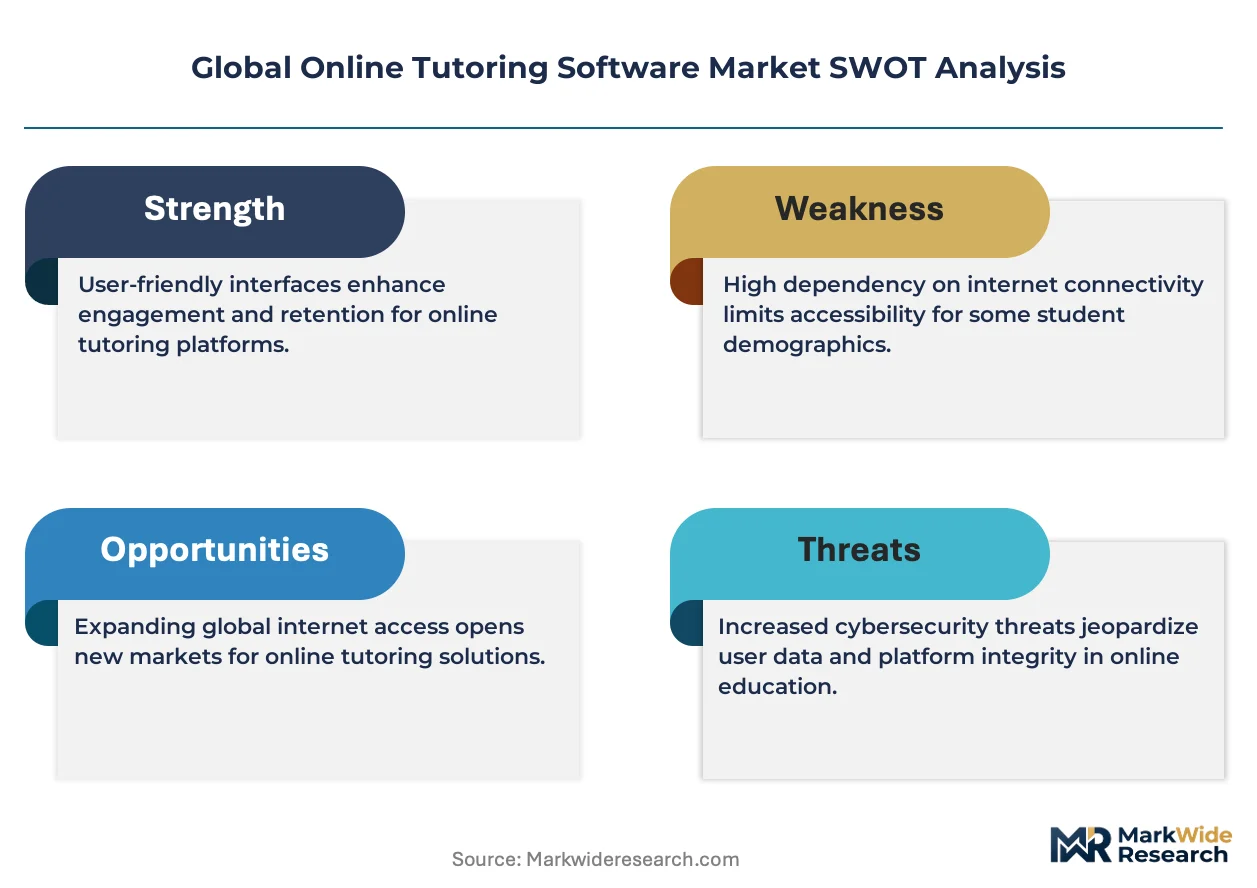
The EU AI Act, enforced by national regulators in Germany and France, imposes algorithmic transparency requirements on adaptive tutoring systems that personalize content delivery. The US Family Educational Rights and Privacy Act and Children's Online Privacy Protection Act constrain how platforms collect and monetize student behavioral data. India's Digital Personal Data Protection Act introduces consent-layer complexity for tutoring services targeting minors. Stakeholders must monitor whether emerging AI literacy mandates in OECD member states create new certification requirements for platform vendors.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing adaptive tutoring platforms to reengineer personalization engines, while India's Digital Personal Data Protection Act introduces consent-layer complexity that reshapes vendor compliance roadmaps across multiple jurisdictions.
Growth Catalysts
- EU AI Act enforcement:Germany and France now mandate explainability in adaptive content delivery, pushing vendors toward interpretable machine learning architectures that institutions prefer for audit readiness.
- Urban tutoring center consolidation in India:Metro-area coaching chains in Mumbai, Delhi, and Bangalore are standardizing on single-platform subscriptions to replace fragmented instructor tools.
- Cloud-native latency optimization:Edge computing deployments now achieve sub-100ms video synchronization, enabling synchronous instruction at scale previously limited by infrastructure costs.
Market Restraints
- AES-256 encryption compliance costs:Student data protection requirements in multiple jurisdictions force redundant security infrastructure that raises operational overhead for cross-border providers.
- Live-class bandwidth concentration:Peak enrollment periods strain last-mile connectivity in tier-2 Indian cities, creating service quality variance that limits addressable market expansion.
- Legacy publisher licensing lock-in:University systems with multi-year Pearson PLC contracts face switching costs that delay cloud-native platform adoption cycles.
Strategic Opportunities
- Brazilian K-12 procurement modernization:ANVISA-aligned digital health frameworks are creating regulatory templates that edtech vendors can leverage for platform certification in Latin America's largest education market.
- Assessment-analytics convergence:Real-time learning outcome measurement is merging with automated grading workflows, opening premium pricing tiers for institutions purchasing integrated suites rather than point solutions.
- OECD AI literacy mandates:Emerging certification requirements for algorithmic competency in member states are generating demand for vendor-provided educator training modules as bundled offerings.
Industry Challenges
- Cross-border data residency engineering:India's data localization requirements conflict with EU GDPR portability provisions, forcing architecture fragmentation that complicates product roadmaps.
- Adaptive algorithm audit preparation:Documentation standards for content personalization logic remain undefined in most jurisdictions, creating uncertainty for platform engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Tutoring Software Market |
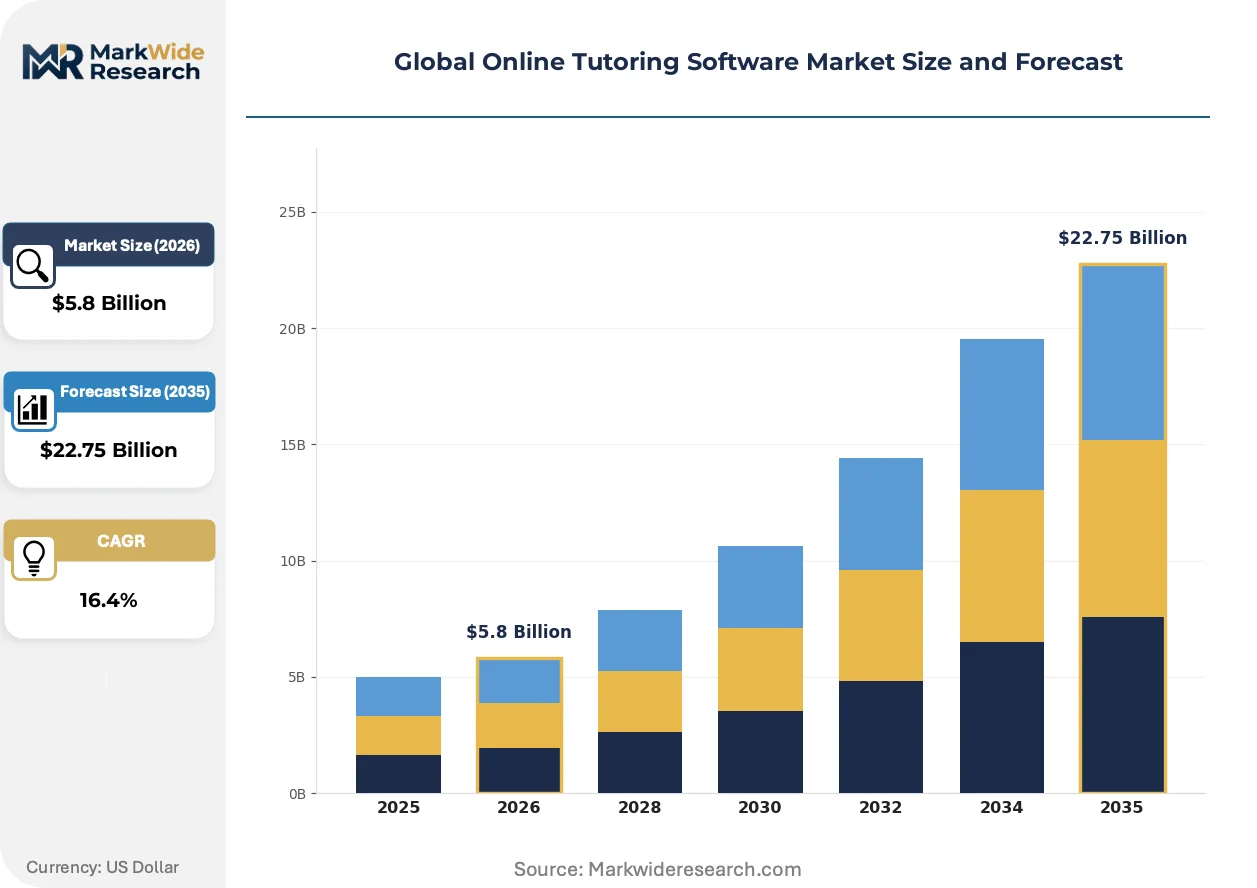
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Web-Based Solution Type: Live Classes, Self-Paced Learning, Assessment & Analytics, Homework Assistance, Collaborative Tools Use Case: K-12 Education, Higher Education, Corporate Training, Language Learning, Test Preparation End User: Academic Institutions, Individual Learners, Corporate Clients, Tutoring Centers, eLearning Platforms |
| Companies Covered | Chegg Inc., Pearson PLC, TAL Education Group, BYJU'S, Tutor.com, Khan Academy, Vedantu, Preply, Varsity Tutors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Tutoring Software Market Shifts & Advancements
Generative AI integration is bifurcating platform architectures between those embedding large language models for real-time tutoring assistance and those maintaining rule-based systems for regulatory predictability. This technological divergence is reshaping vendor R&D allocation and partnership strategies.
Generative AI tutoring assistants now handle routine student queries through natural language interfaces, reducing instructor bandwidth requirements. K-12 districts in Texas and Florida are piloting these tools for after-hours homework support. The technology is bifurcating vendor strategies between premium AI-augmented offerings and compliance-focused stripped-down alternatives.
The EU AI Act's risk classification system places adaptive tutoring algorithms in the "limited risk" category, triggering transparency documentation obligations that did not exist previously. Vendors serving German and French institutional clients must now maintain algorithmic decision logs. This regulatory layer is compressing time-to-deployment for new personalization features as legal review cycles lengthen.
Institutional purchasing committees are unbundling live-class platforms from content libraries, reversing prior bundled procurement patterns. University systems in Canada and Australia now issue separate RFPs for synchronous delivery infrastructure and curriculum materials. This disaggregation is visible most acutely in North American community college districts seeking specialized workforce training content without platform switching costs.
Global Online Tutoring Software Market Segmentation
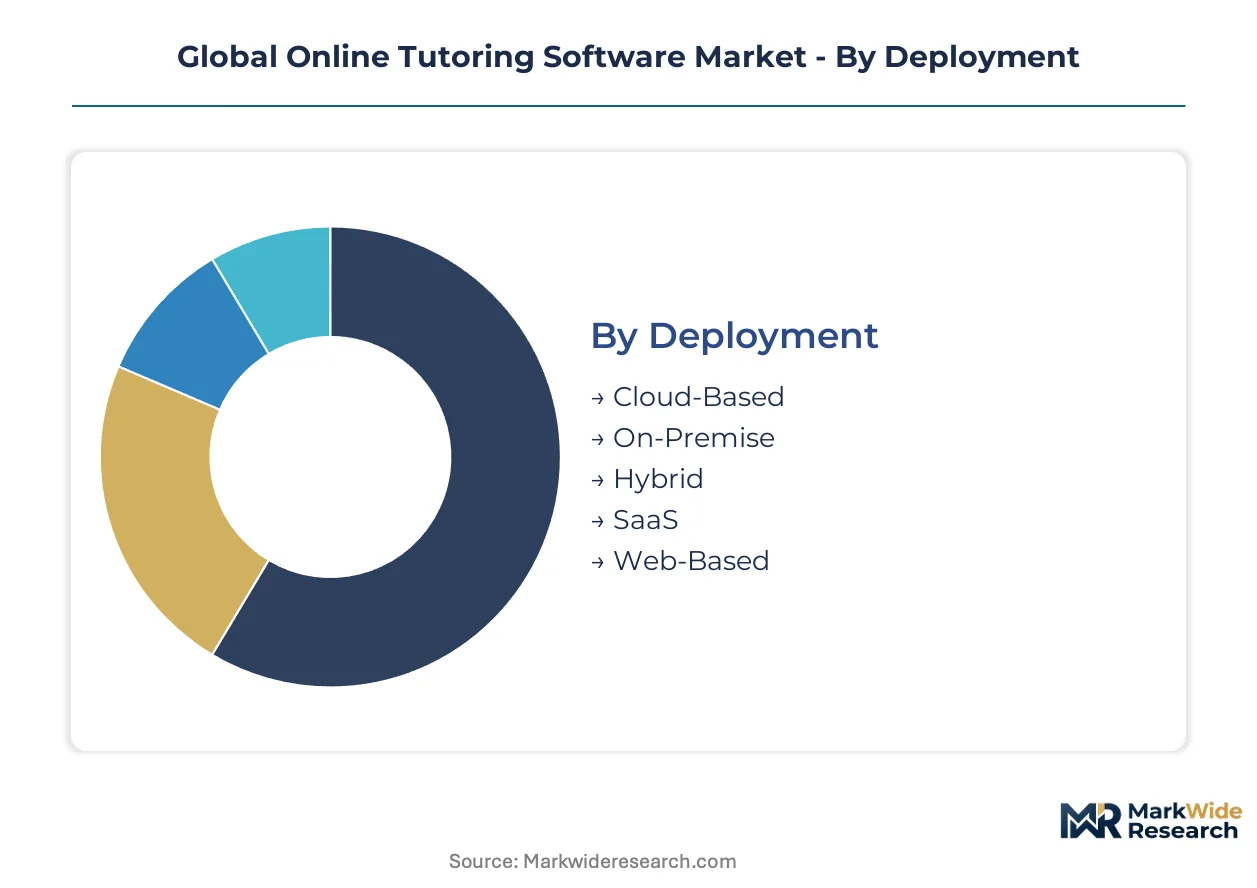
Segmentation in online tutoring software reveals how procurement priorities diverge across infrastructure preferences, pedagogical models, and institutional buyer types. Understanding these fault lines helps vendors allocate engineering resources and pricing architecture to where contract values concentrate.
Deployment:
Margin pools concentrate in cloud-native architectures where recurring subscription revenue and automatic scalability reduce customer acquisition costs relative to perpetual license models.
- Cloud-Based:Platforms deploy on distributed server infrastructure with automatic load balancing during enrollment spikes. K-12 districts in Texas and Florida prioritize these implementations for disaster recovery flexibility and reduced IT staffing overhead.
- SaaS:Multi-tenant architectures enable vendors to serve thousands of tutoring centers through single codebase maintenance. Indian urban coaching chains in Mumbai and Delhi standardize on SaaS subscriptions to replace fragmented instructor tools.
- On-Premise:University systems with legacy security audits maintain datacenter control for FERPA compliance.
- Hybrid:Split architectures serve corporate clients needing local video storage with cloud analytics.
- Web-Based:Browser-first delivery eliminates app store friction for individual learners.
The dominant share belongs to Cloud-Based deployments, while SaaS is closing the gap fastest through vertical specialization for tutoring center chains.
Solution Type:
Application-level differentiation separates synchronous instruction platforms commanding premium pricing from asynchronous modules competing on content library depth.
- Assessment & Analytics:Real-time learning outcome measurement merges with automated grading workflows through machine learning models. OECD member states prioritizing measurable competency frameworks drive institutional procurement of these integrated suites.
- Live Classes:Sub-100ms latency video synchronization enables synchronous instruction at scale through edge computing deployments. German and French institutional clients now require algorithmic decision logs for adaptive features under EU AI Act mandates.
- Self-Paced Learning:Modular content libraries serve corporate training budgets with completion tracking.
- Homework Assistance:Generative AI tutoring assistants handle routine queries for after-hours support.
- Collaborative Tools:Shared whiteboards and breakout rooms target project-based learning in higher education.
Live Classes retains the largest revenue base, though Assessment & Analytics is expanding most quickly as procurement committees unbundle evaluation infrastructure from content delivery.
Use Case:
Volume concentration follows public education procurement cycles, with K-12 and higher education representing multi-year contract opportunities distinct from individual subscription models.
- K-12 Education:District-level purchasing committees issue RFPs for synchronous delivery infrastructure separate from curriculum materials. Canadian community college districts seek specialized workforce training content without platform switching costs.
- Test Preparation:High-stakes exam coaching in India drives premium platform subscriptions with diagnostic analytics. Urban centers in Bangalore and Chennai consolidate onto single platforms to standardize instructor workflows.
- Higher Education:University systems maintain multi-year contracts with legacy publishers for institutional licensing infrastructure.
- Corporate Training:Workforce upskilling budgets favor modular self-paced modules with certification tracking.
- Language Learning:Individual learners dominate this segment with app-store subscription patterns.
K-12 Education holds the dominant position, while Test Preparation is gaining share fastest through India's urban coaching center consolidation.
End User:
Customer type determines pricing architecture complexity, with academic institutions demanding procurement compliance features that individual learners ignore.
- Academic Institutions:University systems require AES-256 encryption, FERPA compliance documentation, and multi-year contract terms. Australian and Canadian institutional purchasing committees now issue separate RFPs for synchronous infrastructure and curriculum materials.
- Tutoring Centers:Metro-area coaching chains need instructor management dashboards with scheduling optimization. India's Digital Personal Data Protection Act introduces consent-layer complexity for services targeting minors in these centers.
- Individual Learners:Mobile-first subscriptions with minimal onboarding friction drive volume in language learning.
- Corporate Clients:Learning management system integration requirements dominate procurement criteria.
- eLearning Platforms:White-label infrastructure seekers prioritize API flexibility and customization depth.
Academic Institutions command the dominant share, while Tutoring Centers are climbing the fastest through India's urban consolidation wave.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Individual learners in India exhibit extreme price sensitivity, driving volume through low-cost mobile subscriptions. German university systems accept premium pricing for compliance-certified platforms with full audit trails.
United States
K-12 districts in Texas and Florida pilot generative AI tutoring assistants for after-hours homework support. FERPA and COPPA constrain behavioral data monetization, forcing vendors toward subscription models over advertising. The Greater Boston corridor houses edtech clusters developing latency-optimized synchronous delivery infrastructure.
Germany
University systems prioritize algorithmic transparency under EU AI Act enforcement. CNIL-aligned national regulators mandate explainable machine learning architectures for adaptive content delivery. The Munich-Berlin axis concentrates vendor engineering teams focused on interpretable personalization engines for institutional audit readiness.
India
Urban coaching chains in Mumbai, Delhi, and Bangalore consolidate onto single-platform subscriptions to replace fragmented instructor tools. The Digital Personal Data Protection Act introduces consent-layer complexity for services targeting minors. Karnataka's Bangalore cluster anchors domestic platform development with edge computing deployments achieving sub-100ms video synchronization.
United Kingdom
University systems issue separate RFPs for synchronous delivery infrastructure and curriculum materials, reversing bundled procurement patterns. GDPR compliance requirements shape vendor data architecture decisions. London's edtech corridor drives white-label platform development for corporate training integration.
Brazil
ANVISA-aligned digital health frameworks create regulatory templates that edtech vendors leverage for platform certification in Latin America's largest education market. Federal procurement modernization programs expand K-12 district technology budgets. São Paulo's metropolitan tutoring centers drive demand for instructor management dashboards with scheduling optimization.
Global Online Tutoring Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Cloud-native specialists compete on latency optimization and automatic scalability, while legacy publishers leverage institutional licensing infrastructure for multi-year contract retention. The market fragments across three strategic archetypes: proprietary content aggregators, infrastructure-as-a-service platforms, and adaptive algorithm specialists. Dominant competitive moves include geographic expansion into high-growth jurisdictions and portfolio diversification through assessment-analytics convergence.
Within the proprietary content tier, BYJU'S exemplifies the geographic expansion archetype through multi-curriculum content library development. Pearson PLC represents institutional licensing incumbency, anchoring long-term university system relationships. Chegg Inc. occupies a position bridging individual learner subscriptions with institutional homework assistance tools.
| Leading Market Players |
|---|
| Chegg Inc. |
| Pearson PLC |
| TAL Education Group |
| BYJU'S |
| Tutor.com |
| Khan Academy |
| Vedantu |
| Preply |
| Varsity Tutors |
| Others |
Supply & Pricing Matrix
Edge computing infrastructure replacing centralized cloud data centers simultaneously redistributes supply geography toward regional server clusters and compresses latency-premium pricing for synchronous instruction tiers.
Pricing Analysis
After-sales revenue from multi-year institutional support contracts drives lifetime value more than initial platform licensing. Subscription-SaaS tiering dominates, with premium pricing anchored in EU AI Act compliance certification and FERPA audit documentation. Price differentiation hinges on algorithmic explainability grade and geographic data residency guarantees. Cost compression in mid-market tiers intensifies as Indian coaching chains standardize on single-platform subscriptions. Individual learners exhibit extreme price sensitivity, while German university systems accept premium positioning for full audit trail capabilities.
Supply Chain Analysis
Inventory and lead-time compression for AI inference chips now determines platform scalability during enrollment spikes. Supply concentrates in Taiwan for advanced semiconductors, the United States for cloud infrastructure orchestration, and India for edge computing deployment engineering. Component dependencies span NVIDIA GPU clusters, low-latency fiber networks, and AES-256 encryption modules. Single-source vulnerability in specialized AI accelerators threatens capacity expansion timelines. Distribution runs through direct enterprise sales for institutional clients and app store marketplaces for individual subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks cyclical recovery patterns tied to K-12 district procurement budget cycles, which expand following federal education technology allocation renewals.
For Market Incumbents: Fortify institutional licensing relationships through proactive EU AI Act compliance documentation and embedded assessment-analytics bundling. Counter cloud-native specialist encroachment by deepening proprietary content library moats. Prioritize certification investment in interpretable machine learning architectures for German and French audit readiness. For New Entrants and Emerging Players: Differentiate on sub-100ms latency optimization for tier-2 Indian cities where incumbent service quality variance creates white-space. Target Brazilian K-12 districts amid ANVISA-aligned procurement modernization. Pursue white-label infrastructure partnerships with metro-area coaching chains seeking scheduling optimization dashboards. For Investors and Strategic Acquirers: Capital is best deployed toward adaptive algorithm specialists with established algorithmic decision logging for EU institutional clients. Long-term viability favors platforms with demonstrated cross-border data residency engineering capabilities. Monitor OECD AI literacy mandate progression as certification requirement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Assessment-analytics convergence enables premium pricing for integrated suites versus point solutions. |
| Geographic Expansion | Brazilian K-12 procurement modernization opens Latin America's largest education market for certified vendors. |
| Strategic Partnership | Edge computing deployments with Indian telecom operators achieve sub-100ms video synchronization at scale. |
| Acquisition of Specialist Firm | Interpretable machine learning boutiques accelerate EU AI Act compliance for institutional audit readiness. |
| Product Launch | Generative AI tutoring assistants reduce instructor bandwidth requirements for Texas and Florida K-12 districts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Interviews with CTOs, K-12 procurement officers, platform engineers, and tutoring center operations directors informed demand-side validation. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against institutional technology spending aggregates anchored value estimates.
Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and regional regulatory cluster across the projection horizon. CAGRs derive from enrollment growth trajectories, procurement cycle timing, and compliance cost absorption curves. Forecast inputs incorporate edge computing penetration rates and AI literacy mandate adoption patterns.
The analysis sits within stated boundaries; outcomes outside sustained federal education technology allocations or accelerated EU AI Act enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding bandwidth infrastructure expansion and cross-border data portability frameworks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Cloud-Based Training Software Market