
 United States E-Learning Market | 2026-2036
United States E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Learning Market Intelligence
STEM teacher shortages across K-12 districts is redrawing procurement priorities for digital curriculum platforms. Coursera leverages university partnerships to sustain credential credibility in professional upskilling. Pluralsight anchors enterprise software training through specialized technical content libraries. Blackboard competes in institutional learning management through deep integration with student information systems.
United States E-Learning comprises digitally delivered instructional content, assessment protocols, and learner administration tools operating across cloud infrastructure with SCORM or xAPI interoperability standards. The primary commercial purpose is to reduce per-learner training costs while enabling measurable skill outcomes at scale. Courseware and Learning Management Systems dominate procurement budgets, with AI-Based Learning representing the fastest-expanding technology layer as adaptive algorithms replace static content sequencing. Cloud-Based Solutions now command the largest margin pools by eliminating on-premise infrastructure overhead for school districts and mid-sized employers.
FDA oversight of medical device training modules, FCC broadband accessibility mandates, and state-level Department of Education accreditation standards collectively shape product requirements and market access thresholds for platform vendors. The Department of Education enforces Section 508 accessibility compliance, forcing continuous interface redesign and multimodal content delivery. Stakeholders must weigh interoperability investments against the risk of proprietary AI tutor architectures that lock learner data into single-vendor ecosystems.
Market Dynamics
Corporate training departments at Fortune 500 manufacturers now mandate AI-based certification programs for frontline supervisors, compressing procurement cycles and forcing platform vendors to rearchitect delivery infrastructure around adaptive assessment engines.
Growth Catalysts
- Title IV Eligibility Modernization:The Department of Education's updated distance education rules accelerate platform investments in learning analytics infrastructure across state university systems.
- STEM Teacher Shortage Response:K-12 districts are redrawing procurement priorities toward digital curriculum platforms that reduce per-student instructional delivery costs.
- Cloud Migration Economics:Texas, California, and Florida state university systems have scaled systemwide LMS contracts, eliminating on-premise infrastructure overhead for mid-sized employers.
Market Restraints
- Section 508 Compliance Burden:Continuous interface redesign and multimodal content delivery requirements force sustained R&D expenditure without direct revenue recovery.
- Proprietary AI Lock-In Risk:Single-vendor ecosystems trap learner data inside proprietary tutor architectures, raising switching costs and interoperability failure exposure.
- Broadband Accessibility Gaps:FCC mandates highlight uneven infrastructure deployment that limits platform reach in rural district catchments.
Strategic Opportunities
- Medical Device Training Modules:FDA oversight creates specialized compliance requirements that premium platform vendors can capture through validated content libraries.
- Enterprise Software Upskilling:Technical content specialization for software certification tracks opens margin pools distinct from commoditized general education.
- AI-Assessment Convergence:Adaptive algorithms replacing static content sequencing enable outcome-based pricing models for corporate training contracts.
Industry Challenges
- SCORM-xAPI Interoperability Complexity:Legacy learning management systems resist seamless integration with next-generation analytics stacks, forcing costly middleware development.
- Credential Credibility Maintenance:University partnership negotiations require sustained investment to sustain market recognition against non-accredited alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Learning Market |
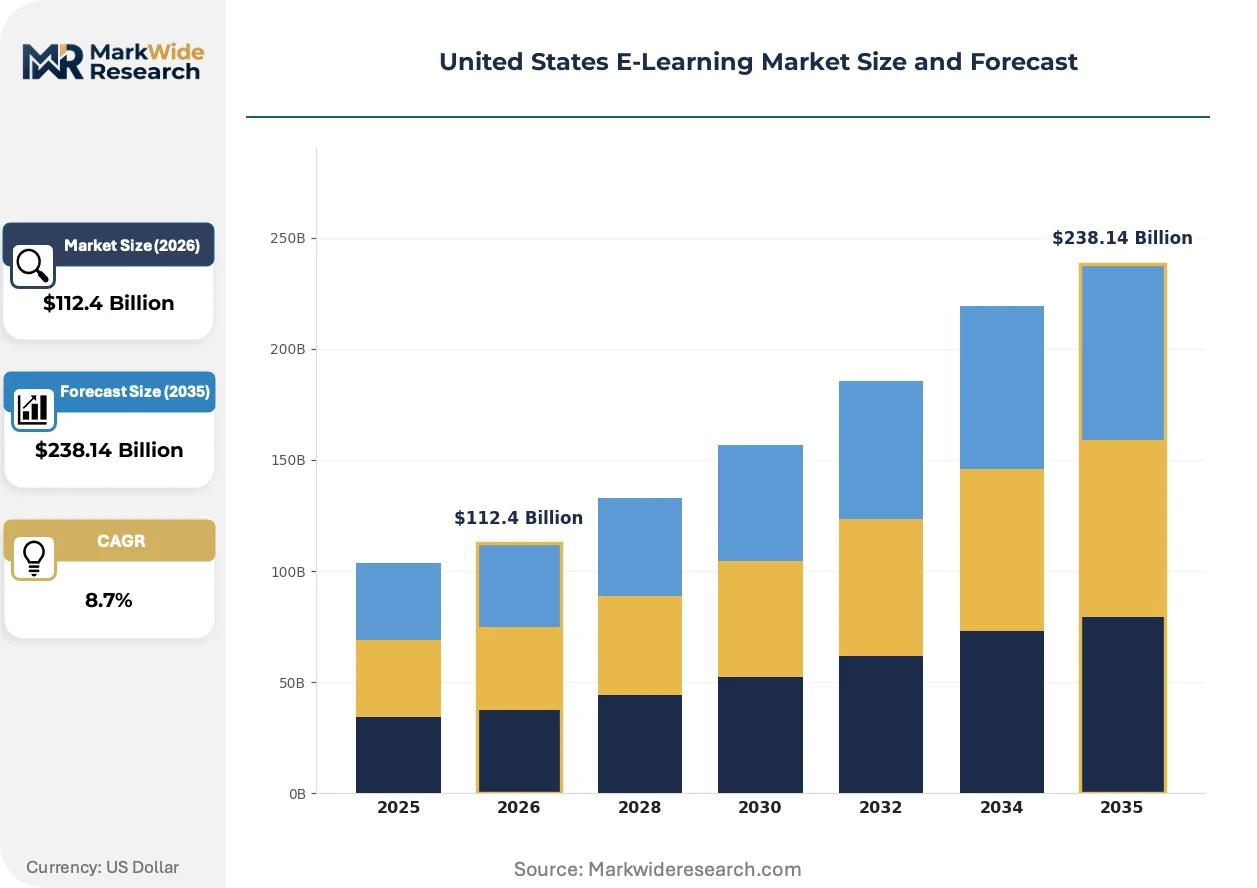
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Courseware, Learning Management Systems, Assessment Tools, Content Management Systems End User: Students, Corporate Employees, Educators, Professionals Delivery Mode: Self-Paced, Instructor-Led, Blended Learning, Mobile Learning Technology: AI-Based Learning, Virtual Reality, Augmented Reality, Cloud-Based Solutions |
| Companies Covered | Coursera, Udemy, edX, Udacity, LinkedIn Learning, Pluralsight, Blackboard, Adobe, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Learning Market Strategic Shifts & Innovations
Adaptive learning engines are compressing content delivery timelines while regulatory pressure on accessibility and data portability forces architectural redesign across vendor portfolios.
AI-powered assessment engines are miniaturizing the unit of instructional delivery from course-level modules to competency micro-credentials. Fortune 500 manufacturers now deploy these engines for frontline supervisor certification, compressing training cycles from quarters to weeks. The structural consequence is miniaturizing procurement decisions downward from enterprise-wide LMS contracts to departmental subscription tiers.
Section 508 accessibility mandates from the Department of Education now require continuous multimodal content delivery across all federally funded platforms. This forces vendors to maintain parallel audio, visual, and haptic output streams, raising fixed cost structures. K-12 districts in high-poverty catchments face the steepest compliance burden as they lack internal accessibility expertise.
Supervisory certification requirements are rotating procurement authority from HR departments to operational line managers with direct P&L accountability. This fragments buying power across manufacturing plants and compresses vendor sales cycles. Texas and California industrial corridors exhibit the most pronounced shift, where plant managers now hold direct subscription authority.
United States E-Learning Market Segmentation
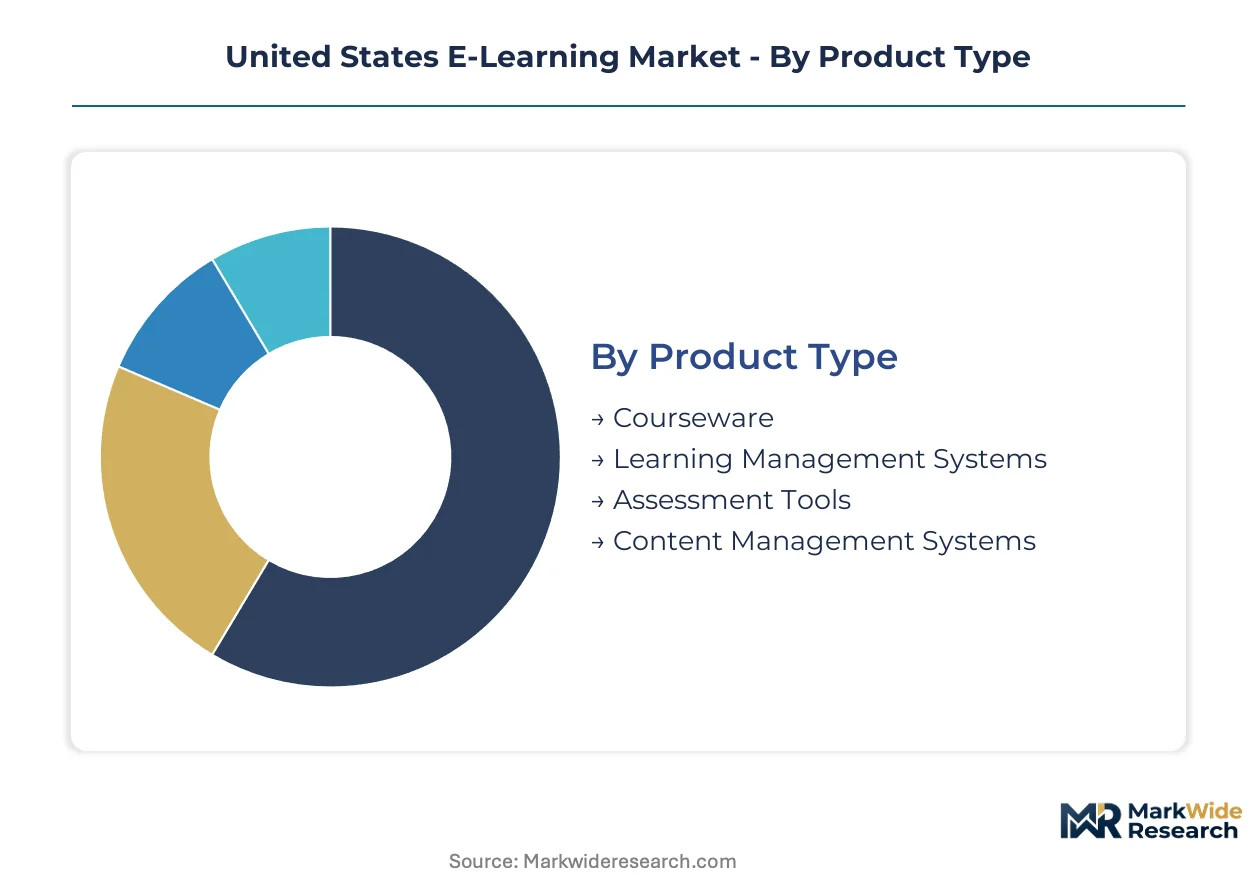
Segmentation in United States E-Learning reveals how procurement authority fragments across institutional buyers with divergent technical requirements and compliance obligations. Understanding these divides exposes where platform vendors can capture premium pricing versus commoditized volume.
Product Type:
Margin pools concentrate in systems that lock institutional clients into recurring subscription architectures with high switching costs.
- Learning Management Systems:These platforms integrate student information systems, gradebooks, and analytics dashboards into unified administrative environments. Texas, California, and Florida state university systems have scaled systemwide LMS contracts, compressing procurement into fewer vendors with deeper integration capabilities.
- Courseware:Digitally delivered instructional content with embedded assessments and progress tracking. K-12 districts confronting STEM teacher shortages are redrawing procurement priorities toward digital curriculum platforms that reduce per-student instructional delivery costs.
- Assessment Tools:Protocols for measuring learner competency against standardized benchmarks. FDA oversight of medical device training modules creates specialized compliance requirements for validated assessment engines.
- Content Management Systems:Repositories for organizing, versioning, and distributing learning materials. Corporate training departments leverage these for frontline supervisor certification content libraries.
Learning Management Systems hold installed capacity. Courseware is rotating up the share rankings.
End User:
Customer type determines pricing power, with enterprise buyers commanding volume discounts while individual professionals absorb premium rates.
- Corporate Employees:Fortune 500 manufacturers now mandate AI-based certification programs for frontline supervisors, compressing procurement cycles and forcing adaptive assessment engine integration.
- Students:Learners in formal degree programs accessing content through institutional LMS contracts. The Department of Education's updated Title IV eligibility rules for distance education accelerate platform investments in learning analytics infrastructure.
- Professionals:Individual credential-seekers purchasing upskilling content directly. Section 508 accessibility compliance requirements force continuous interface redesign for this price-sensitive segment.
- Educators:Teachers and instructors creating or curating content for their classrooms. Broadband accessibility gaps in rural district catchments limit platform reach for this user base.
Corporate Employees generate the steepest expansion trajectory. Students maintain the deepest contract renewals.
Delivery Mode:
Volume concentrates in modalities that minimize live instructor overhead while preserving completion rate metrics.
- Self-Paced:Learner-controlled progression through modular content without scheduled instructor interaction. Cloud-based infrastructure eliminates on-premise overhead for mid-sized employers deploying at scale.
- Blended Learning:Hybrid models combining synchronous digital sessions with asynchronous content consumption. State university systems favor this modality for balancing accessibility with engagement benchmarks.
- Mobile Learning:Content optimized for smartphone and tablet consumption. FCC broadband accessibility mandates highlight uneven infrastructure deployment that constrains reach in rural district catchments.
- Instructor-Led:Scheduled sessions with live facilitator presence, delivered synchronously online. Procurement authority for supervisory certification is rotating from HR departments to operational line managers with direct P&L accountability.
Self-Paced commands the largest volume base. Blended Learning is climbing the fastest in procurement priority.
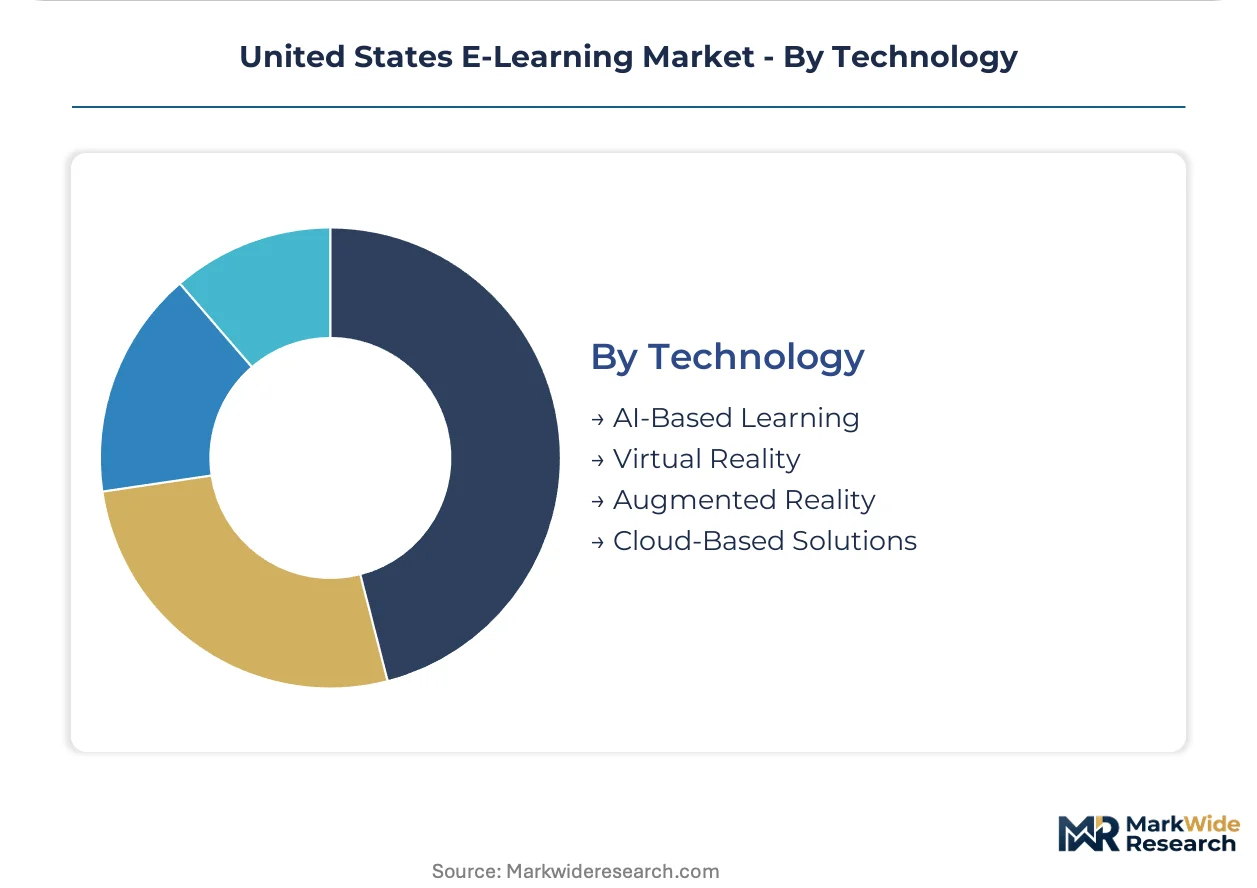
Technology:
Maturity divides the category, with established cloud infrastructure competing against emerging immersive and adaptive layers.
- Cloud-Based Solutions:Delivery architectures eliminating client-side infrastructure through centralized hosting. These now command the largest margin pools by removing on-premise overhead for school districts and mid-sized employers.
- AI-Based Learning:Adaptive algorithms replacing static content sequencing with personalized pathway generation. Outcome-based pricing models for corporate training contracts are emerging around this capability layer.
- Virtual Reality:Immersive simulations for procedural training and hazardous environment replication. FDA oversight of medical device training modules creates specialized compliance requirements for validated VR content libraries.
- Augmented Reality:Overlay of digital information onto physical environments for contextual instruction. Manufacturing plant managers in Texas and California industrial corridors now hold direct subscription authority for AR-based supervisor certification.
Cloud-Based Solutions anchor current procurement budgets. AI-Based Learning is gaining share fastest as adaptive engines displace static sequencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's corporate training intensity diverges sharply from Texas's K-12 procurement concentration, while Florida's blended modality preference separates it from both coasts. These consumption-pattern fractures shape vendor go-to-market strategies across the United States E-Learning Market.
California
Enterprise software upskilling and professional credential programs concentrate in Silicon Valley and Los Angeles corporate corridors. The California Department of Education enforces accessibility standards that exceed federal Section 508 baselines, forcing platform vendors to maintain dual compliance architectures. San Francisco Bay Area technology firms now mandate AI-based certification programs for frontline supervisors, compressing procurement cycles for adaptive assessment engines.
Texas
Manufacturing plant supervisors in Houston and Dallas industrial corridors drive demand for technical content libraries and AR-based training modules. The Texas Higher Education Coordinating Board oversees systemwide LMS contracts across public university systems, consolidating procurement authority into fewer vendors with deep integration capabilities. Austin's technology sector anchors cloud-based solution adoption, eliminating on-premise infrastructure overhead for mid-sized employers.
Florida
State university system scaling of blended learning modalities concentrates procurement in Miami and Tampa educational technology corridors. The Florida Department of Education administers distance learning accreditation standards that accelerate platform investments in learning analytics infrastructure. Orlando's simulation training cluster feeds specialized demand for VR-based procedural instruction in healthcare and aviation verticals.
New York
Financial services compliance training and professional upskilling dominate Manhattan corporate procurement, with distinct seasonal patterns tied to regulatory reporting cycles. The New York State Education Department enforces Title IV eligibility standards for distance education that shape platform architecture decisions. Greater Boston's adjacent edtech corridor supplies specialized assessment tool vendors serving K-12 districts confronting STEM teacher shortages.
Illinois
Chicago's diversified industrial base spans manufacturing certification, healthcare compliance training, and logistics workforce development. The Illinois State Board of Education coordinates procurement for digital curriculum platforms across high-poverty rural catchments facing broadband accessibility gaps. The Midwest manufacturing belt's plant manager community now holds direct subscription authority for supervisory certification programs, fragmenting buying power across industrial facilities.
United States E-Learning Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with cloud infrastructure scale separating the upper echelon from content-focused challengers. The upper tier commands systemwide LMS contracts through deep student information system integration, while specialists capture departmental subscription tiers with vertical-specific content libraries. Strategic archetypes include university-affiliated credential platforms, enterprise technical training specialists, and institutional learning management incumbents. Competitive moves concentrate on adaptive assessment engine integration and outcome-based pricing model development for corporate training contracts.
Within the university-affiliated credential tier, Coursera and edX occupy positions that leverage institutional partnerships to sustain market recognition against non-accredited alternatives. Among enterprise technical training specialists, Pluralsight anchors a position through specialized content libraries for software certification tracks. Blackboard represents the institutional incumbent archetype, competing through administrative system integration rather than pedagogical innovation. These three exemplify how vendor strategy fragments across credential credibility, technical specialization, and institutional lock-in vectors.
| Leading Market Players |
|---|
| Coursera |
| Udemy |
| edX |
| Udacity |
| LinkedIn Learning |
| Pluralsight |
| Blackboard |
| Adobe |
| Cisco Systems |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure scale economies at AWS, Azure, and Google Cloud compress marginal delivery costs for platform vendors while establishing minimum viable scale thresholds that price out regional challengers. Texas and California state university system contracts demonstrate how concentrated procurement authority forces tiered pricing structures downward, squeezing margin pools for mid-sized LMS providers lacking comparable scale.
Pricing Analysis
Long-term enterprise subscription contracts dominate the United States E-Learning market, with annual or multi-year SaaS agreements replacing transactional courseware purchases. Pricing stratifies across premium, standard, and economy tiers based on integration depth with student information systems and AI-assessment engine inclusion. Cost compression in standard-tier subscriptions is intensifying because cloud hyperscalers absorb infrastructure overhead into bundled offerings. K-12 districts in high-poverty catchments exhibit the steepest price sensitivity, while Fortune 500 manufacturers absorb premium rates for validated compliance content.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure provisioning for North American E-Learning delivery, with secondary capacity scaling in Singapore and Frankfurt for redundancy. Platform vendors draw from specialized content production ecosystems in India and the Philippines for curriculum development, while AI-assessment engines rest on GPU clusters concentrated in Nevada and Virginia data center corridors. Single-source vulnerability in cloud provider relationships exposes vendors to service continuity risk during hyperscaler pricing renegotiations. Distribution runs through direct enterprise sales teams for institutional contracts and self-service marketplaces for individual professional subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States E-Learning market sits at a platform-economics inflection where SCORM-xAPI interoperability failures threaten to fragment vendor ecosystems into proprietary data silos. This interoperability tension rewards vendors who architect open-standards compliance while punishing those who optimize for lock-in.
For Market Incumbents: Fortify installed base retention through deeper student information system integration and preemptive AI-tutor architecture investments that raise switching costs before open-standards mandates materialize. Blackboard and institutional incumbents face substitute pressure from modular, API-first challengers; vertical integration into proprietary assessment engines provides defensive moat depth against disaggregation. For New Entrants and Emerging Players: Lead with vertical-specific content libraries in FDA-regulated medical device training or manufacturing safety certification, where compliance validation requirements filter out generalist competitors. Rural K-12 districts confronting broadband accessibility gaps represent the most penetrable geography; partner with regional telecommunications providers to bundle connectivity with curriculum subscriptions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among university-affiliated credential platforms with established accreditation pathways and enterprise technical training specialists with validated certification pipelines. Over the projection horizon, acquisition targets should demonstrate outcome-based pricing model traction with corporate training departments. The signal to watch as inflection indicator is procurement authority rotation from centralized HR to operational line managers with direct P&L accountability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assessment Engine Integration | Adaptive algorithms enable outcome-based pricing for Fortune 500 manufacturing certification contracts. |
| SCORM-xAPI Interoperability Investment | Open-standards compliance prevents learner data lock-in and preserves switching flexibility for institutional buyers. |
| Vertical Content Library Acquisition | Specialized FDA-validated medical device training modules capture premium pricing in regulated healthcare verticals. |
| Cloud Infrastructure Partnership | AWS and Azure co-selling agreements reduce customer acquisition costs for mid-sized employer segments. |
| University Credential Affiliation | Institutional partnerships sustain market recognition against non-accredited professional upskilling alternatives. |
Research Approach
Cross-validation between primary interviews with chief learning officers, K-12 district procurement directors, platform engineering leads, and corporate training executives anchors the qualitative findings in operational reality. Secondary validation draws from Department of Education Title IV filings, FCC broadband deployment data, state university system RFP documentation, and SEC 10-K disclosures from publicly traded platform vendors. Bottom-up and top-down triangulation reconciles individual contract values with aggregate market sizing estimates.
Sensitivity analysis across deployment model, organization size, vertical specialization, and integration complexity dimensions tests forecast robustness throughout the projection horizon. CAGRs derive from segmented growth rate assumptions calibrated against historical procurement cycle data and cloud infrastructure adoption curves. AI-assessment engine penetration rates and SCORM-xAPI migration timelines constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in Department of Education Section 508 enforcement and FDA medical device training oversight; material policy shifts would require re-modeling accessibility compliance cost structures and validated content approval pathways. Recalibration cycles align with material shifts in Title IV eligibility interpretations and hyperscaler pricing architecture changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market