
 Online Examination Service Market | 2026-2036
Online Examination Service Market Size, Share, and Industry Trends Forecast 2026-2036
Online Examination Service Market Insights
India's ed-tech infrastructure expansion is tilting competitive dynamics toward Asia-Pacific delivery centers. Meazure Learning leverages its dual-technology stack to serve both K-12 and enterprise clients across multiple continents. Proctorio specializes in browser-lockdown and machine-learning proctoring for high-stakes university exams. Examity anchors its position through live human proctors combined with automated workflow tools.
An online examination service constitutes a digitally delivered assessment ecosystem encompassing test authoring, delivery, identity authentication, remote supervision, and analytics reporting. These platforms integrate biometric verification, screen monitoring, and keystroke analysis to ensure exam integrity without physical testing centers. Cloud-based solutions dominate deployment preferences due to elastic scaling during peak academic calendars. Proctoring services capture the largest revenue pool, while simulation assessments represent the fastest-expanding assessment type as technical and medical fields adopt virtual practical exams.
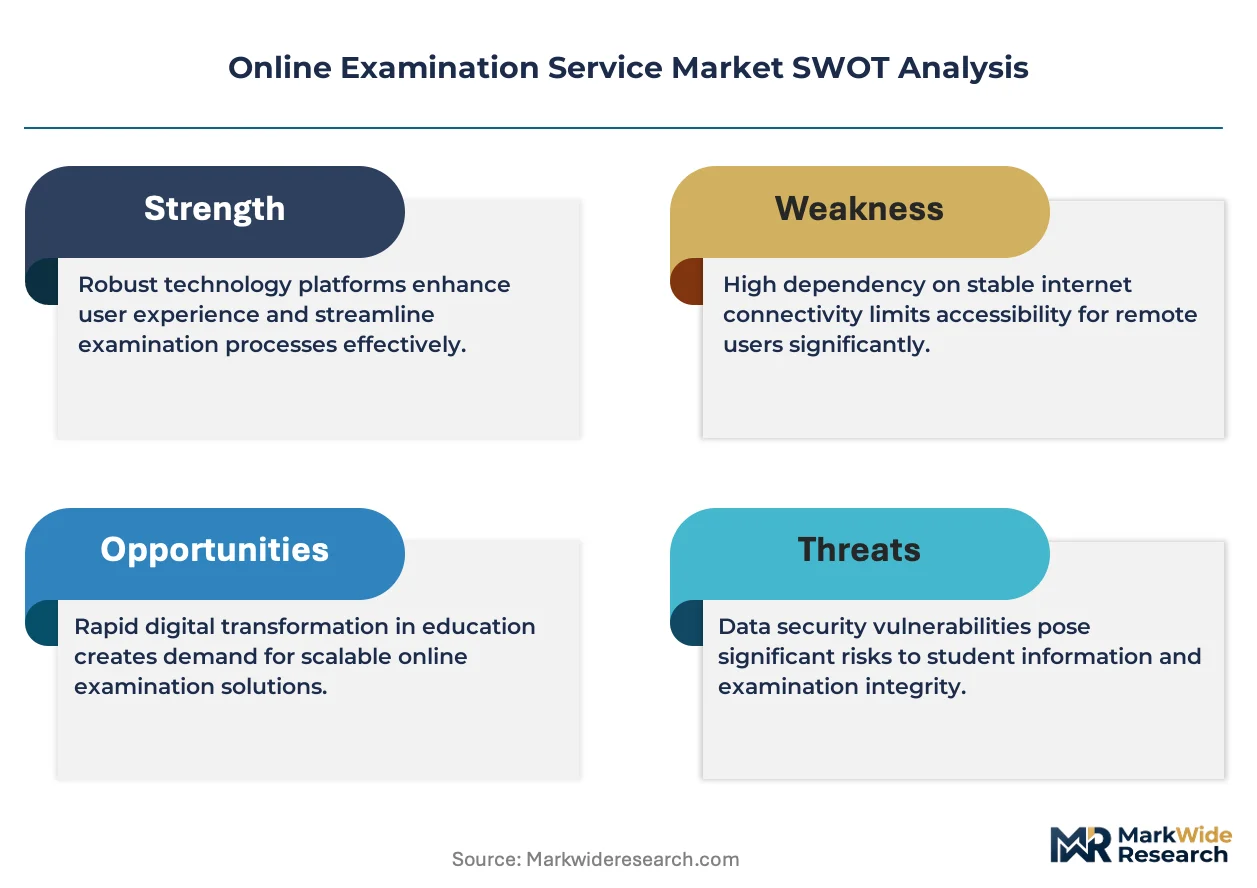
India's BIS data localization mandates and the United States' FERPA privacy requirements shape how vendors architect server infrastructure and student data handling. The EU AI Act's risk classification system directly affects automated proctoring algorithms deployed across European universities. Stakeholders must weigh compliance investment against platform agility as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
AI-driven behavioral analytics is compressing the cost structure of exam integrity assurance while fragmenting vendor differentiation around data sovereignty architectures. Platform providers now compete on biometric accuracy and jurisdictional compliance rather than proctor headcount alone.
Growth Catalysts
- FERPA compliance mandates:US higher education institutions face heightened audit scrutiny over student data handling, accelerating replacement of legacy testing centers with cloud-native platforms that embed privacy-by-design workflows.
- Medical licensing boards:North American healthcare regulators are approving virtual OSCE stations for clinical skills assessment, creating demand for simulation-capable examination infrastructure.
- Keystroke dynamics:Continuous authentication through typing pattern analysis eliminates session hijacking risks without hardware dependencies, lowering deployment friction for community colleges.
Market Restraints
- Data localization requirements:India's BIS mandates force vendors to maintain in-country server farms, raising fixed costs for platforms serving South Asian universities.
- Algorithmic bias liability:The EU AI Act classifies automated proctoring as high-risk, requiring conformity assessments that extend sales cycles by 8-14 months in European markets.
- Screen-sharing workarounds:Browser-lockdown technologies face persistent circumvention through virtual machine environments, eroding customer confidence in unsupervised high-stakes testing.
Strategic Opportunities
- Brazil's ENADE expansion:Federal university system modernization is creating procurement windows for multi-tenant platforms capable of serving 2.5 million annual test-takers across 2,000 campuses.
- Corporate credentialing:Technology certification bodies are unbundling exam delivery from content ownership, opening white-label platform partnerships.
- Blockchain credentialing convergence:Integration of immutable transcript verification with live proctoring is virtualizing the entire credential lifecycle from assessment to employment verification.
Industry Challenges
- Biometric engineer scarcity:Facial liveness detection and gaze-tracking algorithm development requires specialized computer vision talent concentrated in San Francisco, Tel Aviv, and Beijing.
- LMS integration complexity:Legacy Blackboard and Canvas deployments demand custom API middleware that consumes 30-40% of implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Examination Service Market |
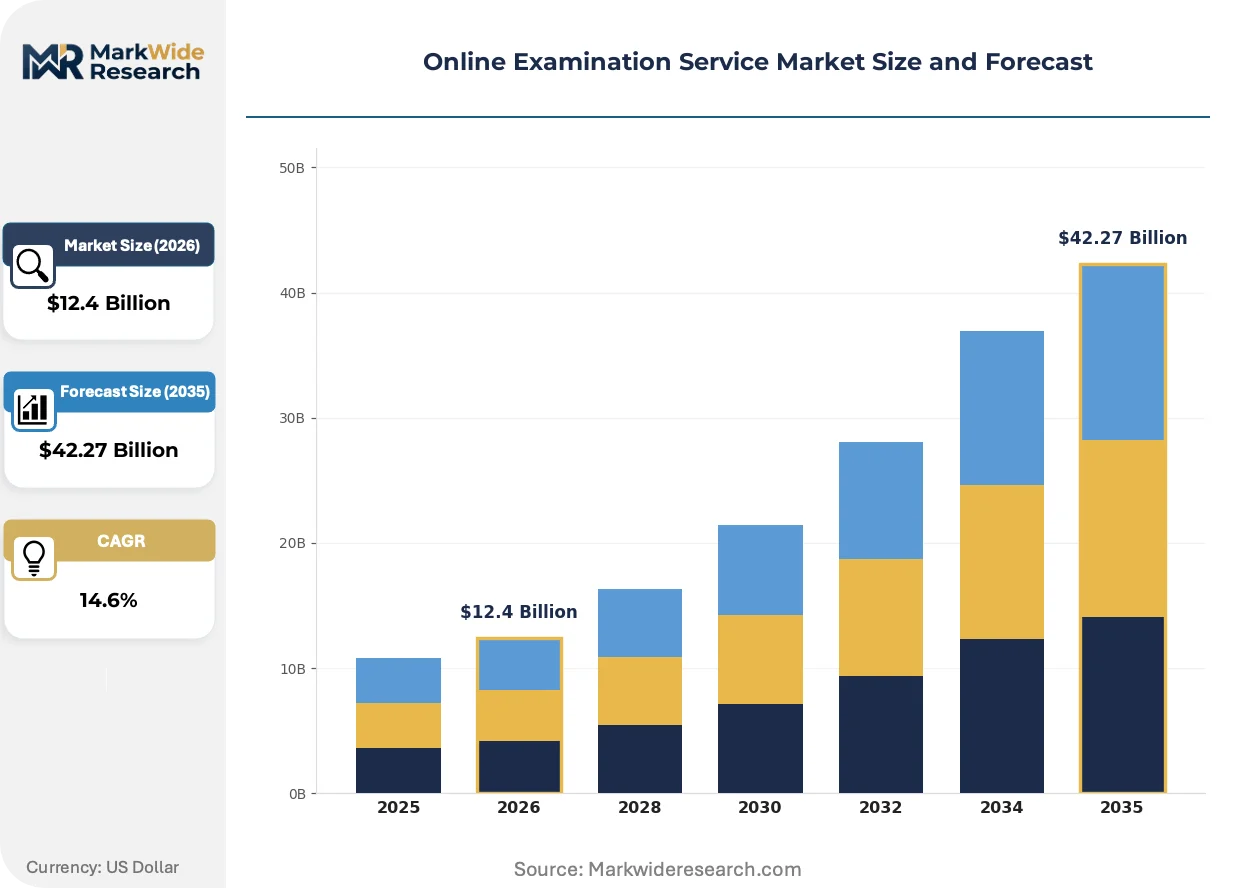
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Proctoring Services, Assessment Platforms, Custom Test Creation, Reporting Tools End User: Educational Institutions, Corporations, Certification Bodies, Government Agencies Deployment: Cloud-Based Solutions, On-Premises Software, Hybrid Models, Mobile Applications Assessment Type: Objective Tests, Subjective Tests, Practical Exams, Simulation Assessments |
| Companies Covered | Mettl, PSI Bridge, Meazure Learning, Honorlock, ProctorExam, ProctorU, Proctorio, BlinkExam, Examity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Examination Service Market Trends and Innovations
Examination platforms are converging on immersive simulation environments while regulatory fragmentation forces modular compliance architectures. Vendors must now engineer for simultaneous deployment across incompatible data sovereignty regimes.
Extended reality headsets are virtualizing practical skills assessment for nursing, engineering, and aviation certification. American community college systems are piloting VR-based clinical simulations at 400% the pace of 2019 baselines. This modality is virtualizing the capital structure of skills validation, compressing per-student equipment costs from physical mannequins to software licenses.
The EU AI Act's risk classification system is forcing algorithmic transparency disclosures for automated proctoring vendors serving European universities. Providers must now document training data provenance and bias testing protocols to maintain market access. German and French accreditation bodies are demanding third-party conformity assessments before platform approval, extending procurement timelines.
Subscription-based procurement is displacing per-exam transaction models among multi-campus university systems. Arizona State University and similar institutions are negotiating enterprise licenses with unlimited seat capacity. This shift is most visible in US public university systems consolidating vendor relationships under state-level master agreements.
Online Examination Service Market Segmentation
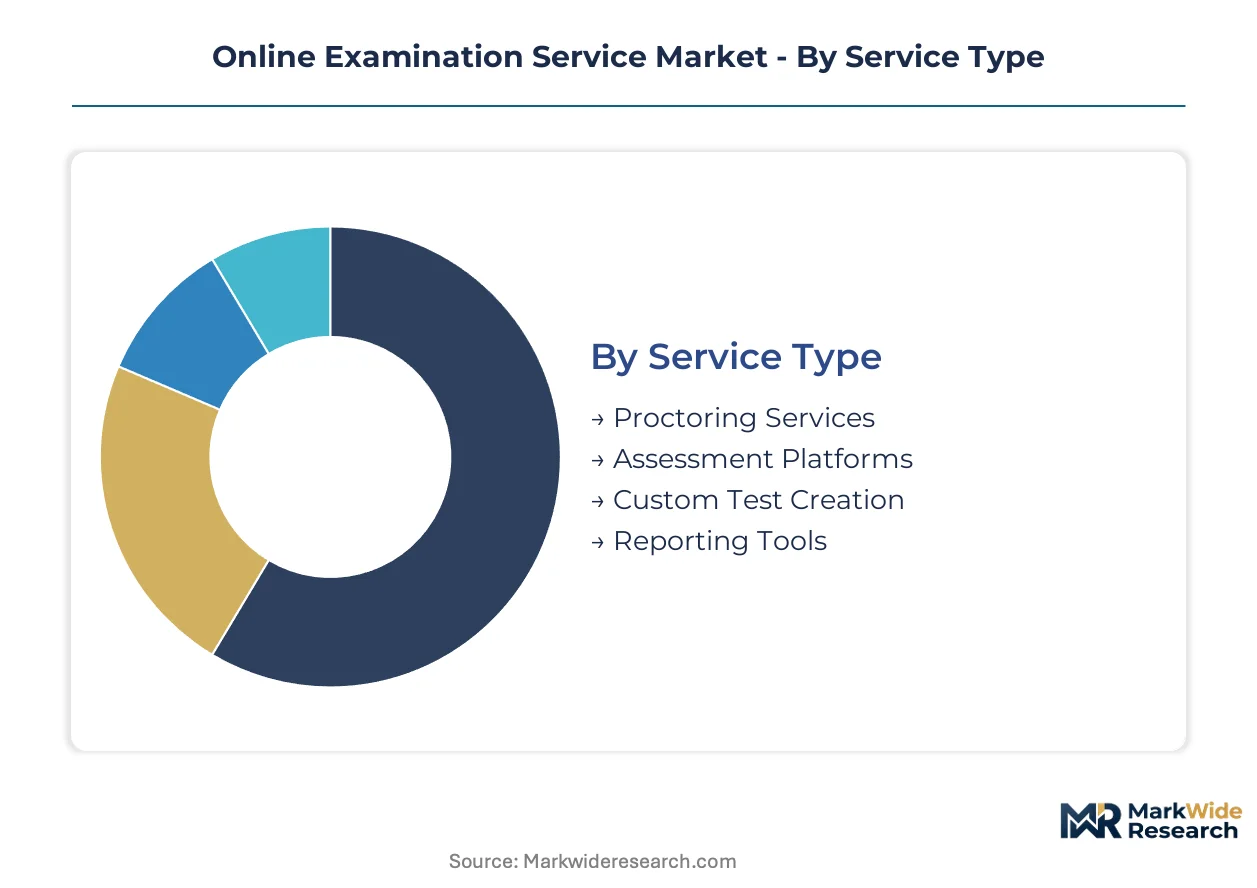
Segmentation in the Online Examination Service Market reveals distinct procurement patterns across service delivery models and institutional buyer types. Cloud-native proctoring platforms command premium pricing from universities replacing physical testing infrastructure, while corporate training departments prioritize assessment platforms with embedded analytics dashboards.
Service Type:
Institutional buyers navigate a use-case spectrum spanning high-stakes credentialing to low-stakes formative assessment, with each service tier demanding different integrity architectures.
- Proctoring Services:Live human proctors, AI-driven behavioral monitoring, and browser lockdown technologies form the integrity backbone for medical licensing and bar examinations. North American universities are consolidating vendor relationships under enterprise licenses that bundle automated flagging with human review workflows.
- Assessment Platforms:End-to-end ecosystems encompassing item banking, adaptive delivery algorithms, and psychometric analytics serve certification bodies unbundling content from delivery infrastructure. Brazil's ENADE federal expansion is driving procurement of multi-tenant platforms capable of elastic scaling across 2,000 campuses.
- Custom Test Creation:Bespoke item development and blueprint alignment services support specialized professional credentials with niche competency frameworks.
- Reporting Tools:Dashboard analytics and longitudinal performance tracking modules integrate with learning management systems for continuous improvement cycles.
The dominant share belongs to Proctoring Services, while Assessment Platforms is closing the gap fastest.
End User:
Buyer sophistication varies sharply across organizational maturity, with procurement authority concentrating in centralized IT functions for large systems and remaining decentralized among individual departments for smaller institutions.
- Educational Institutions:K-12 districts, community colleges, and research universities represent the foundational demand pool, with procurement patterns bifurcating between state-level master agreements and campus-by-campus vendor selection. FERPA compliance mandates are accelerating replacement of legacy testing centers with privacy-by-design cloud platforms.
- Corporations:Technology certification bodies and enterprise learning departments are white-labeling examination infrastructure to unbundle delivery from proprietary content ownership.
- Certification Bodies:Medical licensing boards and professional associations require simulation-capable platforms for virtual OSCE stations and practical skills validation.
- Government Agencies:Civil service commissions and regulatory bodies procure secure examination infrastructure for high-integrity credentialing at national scale.
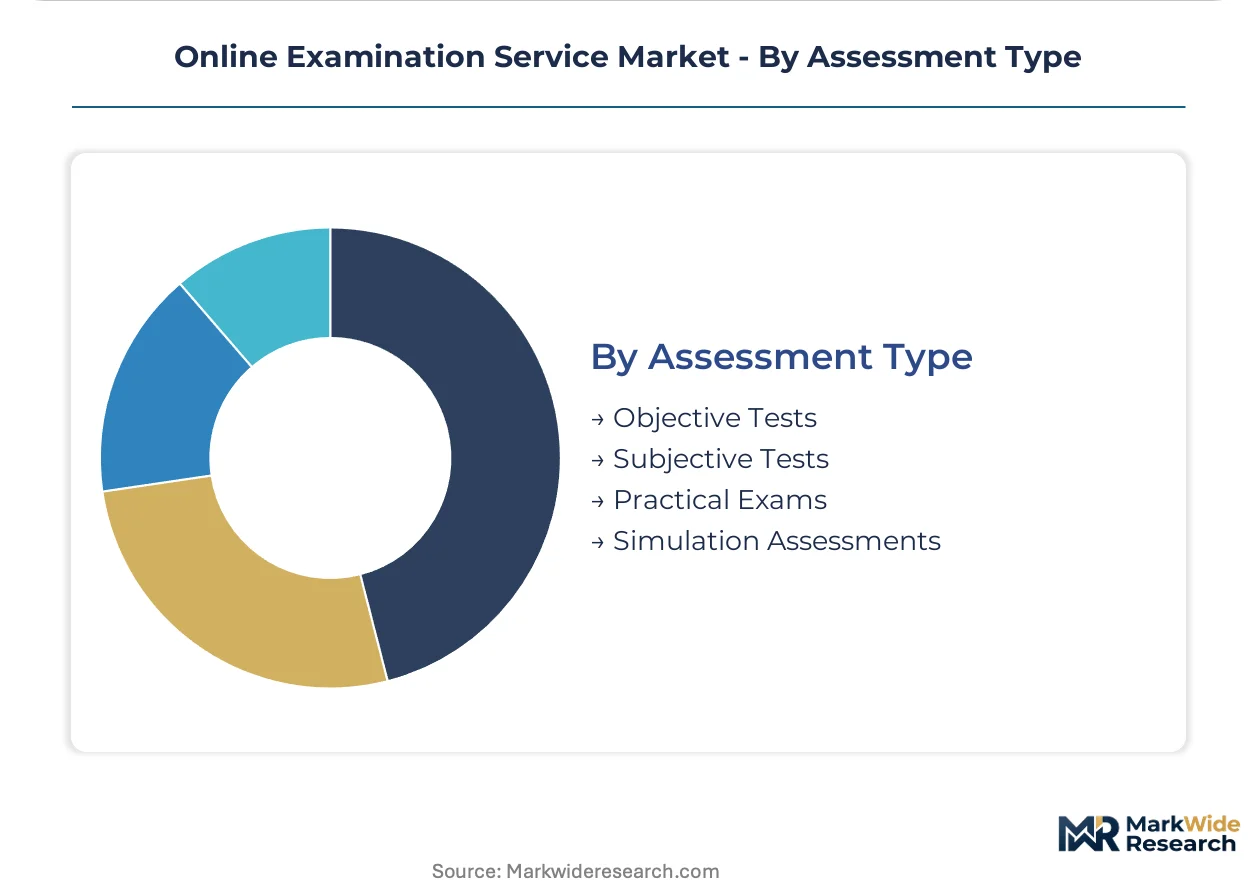
Educational Institutions retain the largest procurement volume, though Corporations are expanding their platform spending most aggressively.
Deployment:
Infrastructure decisions increasingly hinge on data sovereignty requirements rather than purely technical specifications, with regulatory fragmentation forcing modular compliance architectures.
- Cloud-Based Solutions:Elastic scaling during peak academic calendars dominates deployment preferences, though India's BIS data localization mandates and EU GDPR requirements force vendors to maintain jurisdiction-specific server farms. Arizona State University and similar multi-campus systems are negotiating unlimited-seat enterprise licenses.
- On-Premises Software:Air-gapped installations serve defense contractors and intelligence community training programs with classified assessment requirements.
- Hybrid Models:Split architectures route sensitive identity data through local infrastructure while leveraging cloud elasticity for delivery and analytics.
- Mobile Applications:Smartphone-native proctoring extends reach to broadband-constrained regions, with keystroke dynamics and facial liveness detection replacing hardware-dependent authentication.
Cloud-Based Solutions command the predominant deployment share, while Hybrid Models are gaining traction fastest among multinational institutions.
Assessment Type:
Format selection tracks the capital intensity of skills being validated, with virtual modalities compressing per-student equipment costs from physical infrastructure to software licensing.
- Objective Tests:Multiple-choice and computer-adaptive formats dominate high-volume credentialing with scalable automated scoring. Browser-lockdown technologies face persistent circumvention through virtual machine environments, eroding confidence in unsupervised deployments.
- Simulation Assessments:Extended reality environments virtualize practical skills assessment for nursing, engineering, and aviation certification. American community college systems are piloting VR-based clinical simulations at quadruple the pace of 2019 baselines.
- Subjective Tests:Essay and constructed-response formats require AI-assisted scoring validation combined with human expert review for high-stakes decisions.
- Practical Exams:Performance-based assessment of procedural competencies demands video capture infrastructure with timestamped artifact submission.
Objective Tests maintain the largest volume share, while Simulation Assessments are climbing the fastest as technical and medical fields adopt virtual practical examinations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERPA compliance mandates in the United States are accelerating cloud-native platform procurement across higher education systems. University consortia in multiple countries are consolidating vendor relationships under enterprise licensing frameworks.
United States
Arizona State University and similar multi-campus systems negotiate unlimited-seat enterprise licenses for cloud-based proctoring. Medical licensing boards under FDA oversight are approving virtual OSCE stations for clinical skills assessment. The Boston-Cambridge corridor concentrates AI-driven behavioral analytics development for exam integrity applications.
Germany
Federal university system modernization is creating procurement windows for multi-tenant assessment platforms. The EU AI Act's high-risk classification for automated proctoring requires conformity assessments extending sales cycles. Berlin-Brandenburg hosts accreditation bodies demanding third-party algorithmic transparency disclosures before platform approval.
India
BIS data localization mandates force vendors to maintain in-country server farms for South Asian university clients. Federal university system expansion under the Ministry of Education is driving demand for platforms serving 2.5 million annual test-takers. Bangalore and Hyderabad clusters concentrate ed-tech infrastructure development for examination delivery.
Brazil
ENADE federal expansion is creating procurement opportunities for platforms capable of elastic scaling across 2,000 campuses. ANVISA and federal education regulators are establishing frameworks for virtual practical examinations in medical and technical fields. São Paulo state anchors demand concentration for corporate credentialing and professional certification bodies.
United Kingdom
Oxbridge and Russell Group universities are consolidating proctoring vendor relationships under centralized IT procurement functions. GDPR requirements shape server infrastructure decisions for student data handling across multi-campus deployments. London metropolitan area concentrates white-label platform partnerships for technology certification bodies unbundling delivery from content ownership.
Online Examination Service Market Competitive Landscape
Full-stack platform providers and specialized proctoring vendors split the market along integration depth versus functional purity lines. The vendor base organizes into three strategic archetypes: enterprise-scale assessment ecosystems, AI-native proctoring specialists, and hybrid human-machine workflow platforms. Competitive moves concentrate on biometric accuracy investment and jurisdictional compliance architecture rather than proctor headcount expansion alone.
Within the hybrid workflow tier, Examity and ProctorU exemplify the convergence of live human proctors with automated flagging systems. Meazure Learning occupies a position spanning both K-12 and enterprise client segments across multiple continents. These three companies represent the dominant competitive positioning around dual-technology service delivery models.
| Leading Market Players |
|---|
| Mettl |
| PSI Bridge |
| Meazure Learning |
| Honorlock |
| ProctorExam |
| ProctorU |
| Proctorio |
| BlinkExam |
| Examity |
| Others |
Pricing and Supply Chain Analysis
Server farm undercapacity in India is forcing vendors to accelerate capital deployment ahead of BIS compliance deadlines, compressing margins for platforms serving South Asian universities while elevating pricing power for cloud infrastructure providers with established local presence.
Pricing Analysis
Geographic price spreads between North American enterprise licenses and South Asian per-exam contracts exceed threefold, reflecting divergent buyer sophistication and regulatory compliance burdens. Subscription-based SaaS tiers dominate procurement among multi-campus university systems, while transactional per-assessment pricing persists in emerging markets. Price differentiation hinges on biometric accuracy certification and jurisdictional data sovereignty compliance, with FERPA-aligned platforms commanding premiums. Pricing pressure stems from algorithmic commoditization in browser-lockdown segments, eroding vendor margins. Community college systems exhibit highest price sensitivity, whereas medical licensing boards demonstrate lowest sensitivity due to high-stakes integrity requirements.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor suppliers dominates hardware cost volatility for facial recognition edge devices deployed in proctoring endpoints. Software development concentrates in the United States, India, and Israel, with algorithmic talent clustering in San Francisco, Bangalore, and Tel Aviv. Raw material dependencies span GPU accelerators, cloud compute instances, and biometric sensor modules. Single-source vulnerability in NVIDIA's datacenter chip supply creates procurement risk for AI-driven behavioral analytics platforms. Distribution runs through direct enterprise sales teams for large university systems, supplemented by channel partners serving mid-market certification bodies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from open-source proctoring toolkits and hyperscaler-native assessment platforms, requiring defensive repositioning around compliance depth and biometric accuracy moats.
For Market Incumbents: Entrench market position through backward integration into facial liveness detection algorithm development, reducing dependence on Tel Aviv and Beijing computer vision talent pools. Consolidate vendor relationships under state-level master agreements to lock out challenger platforms. Counter open-source substitution threats by embedding FERPA and EU AI Act compliance workflows as non-replicable service layers. For New Entrants and Emerging Players: Corporate credentialing white-label partnerships represent the most penetrable entry point, as technology certification bodies unbundle delivery from content ownership. Brazil's ENADE federal expansion offers procurement windows for multi-tenant platforms without incumbent relationship overhead. Target community college VR simulation pilots with lightweight browser-based alternatives to hardware-intensive clinical mannequin deployments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among assessment platform providers with embedded analytics dashboards serving corporate training departments. Long-term viability favors vendors with modular compliance architectures spanning FERPA, GDPR, and BIS regimes. Monitor EU AI Act conformity assessment backlog duration as inflection signal for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Accuracy Certification | FDA-aligned liveness detection standards unlock medical licensing board procurement pipelines. |
| Jurisdictional Server Farm Expansion | BIS-compliant India infrastructure captures Ministry of Education federal expansion contracts. |
| VR Simulation Platform Launch | American community college clinical skills pilots quadruple addressable assessment modality. |
| Enterprise License Consolidation | Arizona State-style unlimited-seat agreements displace per-exam transactional competitors. |
| Blockchain Credential Integration | Immutable transcript verification virtualizes full credential lifecycle from assessment to employment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor RFP documentation, university procurement databases, and regulatory filing corpora. Primary interviews engaged chief technology officers at multi-campus university systems, platform engineering leads at proctoring vendors, federal education procurement officers, and learning management system integration specialists. Secondary validation drew from FERPA audit reports, EU AI Act conformity assessment registries, BIS certification listings, and hyperscaler datacenter expansion disclosures. Bottom-up demand modeling triangulated against top-down market sizing across deployment models and end-user segments.
Forecast inputs span service type adoption curves, end-user procurement authority centralization trends, and regulatory compliance cost trajectories across jurisdictions. Segmentation dimensions modeled include delivery model architecture, institutional buyer sophistication tier, assessment format capital intensity, and regional data sovereignty regime. CAGRs derived from elasticity-adjusted demand projections and vendor capacity expansion timelines. Industry-specific inputs incorporate medical licensing board virtual OSCE approval velocity and keystroke dynamics authentication deployment friction indices.
Practitioners should monitor EU AI Act enforcement consistency, India BIS server farm commissioning delays, and open-source proctoring toolkit maturity for early signals of competitive displacement or margin compression. Forecasts reflect assumptions regarding sustained higher education digital transformation budgets and regulatory fragmentation persistence. Macroeconomic contraction in university endowments, algorithmic bias liability precedent, or hyperscaler platform bundling would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Asia Pacific HR Professional Services Market
Education & Training
Digital Marketing Courses Market
Education & Training
AI in K-12 Education Market
Education & Training
US Child Care Market
Education & Training
GCC E-Learning Market
Education & Training
Child Care Services Market
Education & Training
Qatar E-Learning Management System Market
Education & Training
Corporate Training Software Market
Education & Training
Bilingual Education for Children Market
Education & Training
Healthcare LMS Software Market
Education & Training
Higher Education Learning Systems Market
Education & Training
Asia-Pacific Digital Education Market
Education & Training
Global Outplacement Services Market
Education & Training
Global Smart Classroom Market
Education & Training
Global Language Service Market
Education & Training
Micro Learning Platform Market