
 Online K-12 Education Market | 2026-2036
Online K-12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
Online K-12 Education Market Insights
Platform procurement is rebalancing from district-level single-vendor contracts toward multi-source ecosystems integrating specialized providers. Outschool leverages its marketplace model to connect learners with niche instructors, while DreamBox Learning sustains its position through adaptive math algorithms that personalize pacing. Coursera competes by extending university-branded content downward into advanced secondary cohorts.
Online K-12 education delivers structured academic instruction through internet-connected devices, combining live video streaming, asynchronous content repositories, and automated assessment engines with latency tolerances below 150 milliseconds for real-time interaction. Its primary commercial purpose replaces or supplements physical classroom seat time with scalable, location-independent learning pathways. Learning Management Systems dominate institutional spending due to gradebook integration and administrative compliance requirements, while Asynchronous Learning captures the fastest enrollment growth among working families seeking schedule flexibility. Interactive Learning Modules command premium pricing relative to passive video lectures because of embedded formative assessment loops that demonstrate measurable competency gains.
The US Department of Education enforces Section 508 accessibility standards and FERPA privacy protections that dictate procurement specifications for federally funded schools. India's Ministry of Education aligns platform eligibility with BIS-certified data localization and the National Education Policy's digital infrastructure targets. State-level ESSA accountability frameworks in the US further constrain which content formats qualify for Title I expenditure. Stakeholders must monitor evolving data sovereignty requirements as cross-border student information flows face tightening jurisdictional boundaries.
Market Dynamics
District procurement officers now fragment single-vendor Learning Management System contracts into multi-source ecosystems, forcing platform providers to specialize or integrate through API partnerships rather than compete for exclusive district-wide deployments.
Growth Catalysts
- FERPA Privacy Mandates:US Department of Education enforcement drives institutional demand for compliant data architecture, creating procurement preference for certified platforms.
- Affordable 4G Handsets:Sub-$100 smartphones in India unlock first-time structured curricula access for families previously excluded from formal digital learning.
- Adaptive Assessment Engines:Real-time competency mapping personalizes pacing without instructor intervention, reducing per-student instructional cost.
Market Restraints
- Section 508 Compliance Burden:Federal accessibility mandates impose development overhead that squeezes margin for smaller platform developers.
- Cloud Infrastructure Concentration:Three hyperscale providers control essential compute capacity, exposing price volatility risk for streaming-dependent live instruction.
- Screen Time Substitution:Parental preference for physical activity and social development limits daily engagement ceilings for pure-digital curricula.
Strategic Opportunities
- India's Tier-3 Cities:Low-cost data penetration creates white-space demand for vernacular-language asynchronous content.
- AI Tutor Convergence:Large language models paired with structured curricula enable 24/7 personalized support without proportional staffing.
- Micro-Credential Channels:Employer-recognized skill badges bypass traditional transcript authority, opening B2B2C distribution through workforce development boards.
Industry Challenges
- Instructional Design Talent Scarcity:Platform operators compete for scarce learning experience designers capable of embedding formative assessment into interactive modules.
- Legacy Gradebook Integration:Proprietary data formats in incumbent student information systems force expensive custom API development for seamless district adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online K-12 Education Market |
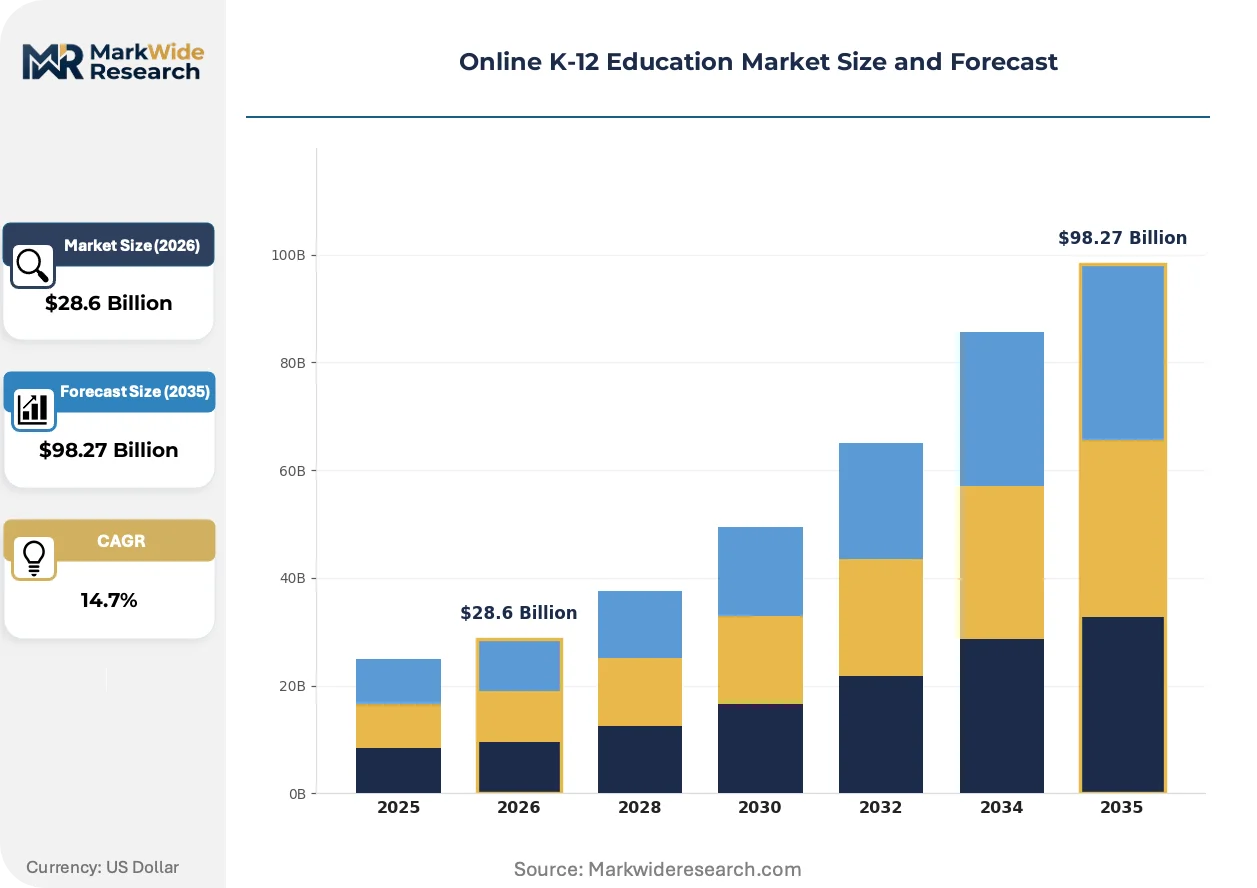
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $98.27 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Classrooms, Educational Software, Assessment Tools Delivery Model: Synchronous Learning, Asynchronous Learning, Blended Learning, Flipped Classroom Target Audience: Students, Parents, Teachers, Administrators Content Type: Curriculum-Based Content, Interactive Learning Modules, Video Lectures, Supplemental Resources |
| Companies Covered | Outschool, DreamBox Learning, Byju's, MasterClass, Newsela, Coursera, BrainPOP, Udacity, Udemy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online K-12 Education Market Trends and Innovations
Platform architecture is pivoting from monolithic Learning Management Systems toward modular API-first stacks that let districts compose best-of-breed components.
Immersive simulations using browser-based WebGL rendering is electrifying science and history instruction by eliminating headset hardware barriers. Homeschooling co-ops adopt these tools fastest, compressing the traditional lab-equipment procurement cycle from district capital budgets to individual subscription fees.
India's BIS-certified data localization requirements reshape platform hosting decisions. Foreign operators must establish domestic server infrastructure or forfeit eligibility for government procurement, accelerating joint ventures with local cloud providers.
Parental purchasing committees now displace centralized district IT offices as the primary decision unit for supplemental curricula. This fragmentation favors marketplace models over enterprise sales cycles, with the shift most visible in US suburban districts where homeschooling rates have doubled.
Online K-12 Education Market Segmentation
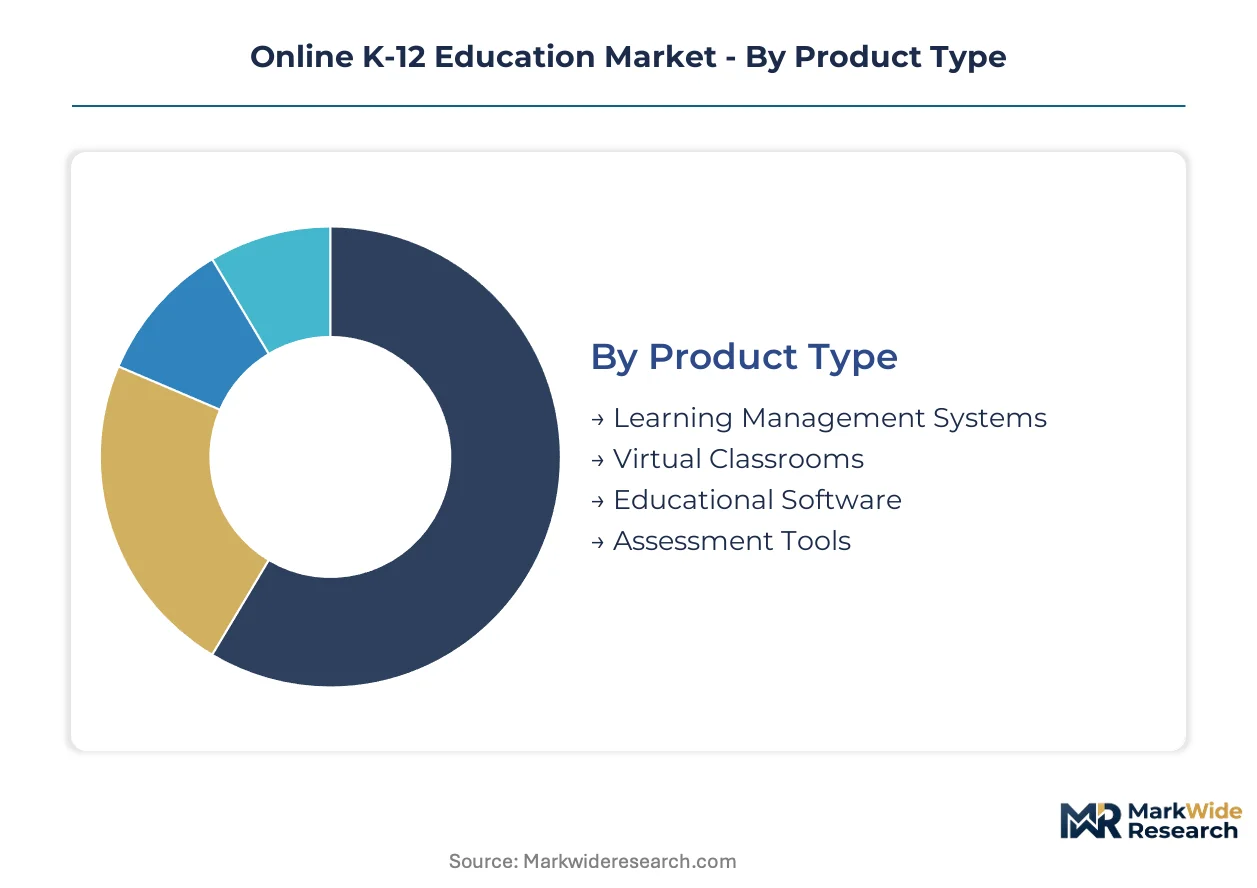
Platform providers must align product architecture with distinct procurement rhythms. District IT offices prioritize administrative integration while homeschooling families favor modular subscription access.
Product Type:
Institutional buyers differentiate platforms by administrative control depth versus instructional flexibility.
- Learning Management Systems:Comprehensive platforms integrating gradebook, attendance, and compliance reporting. Districts in Texas and Florida mandate LMS procurement for Title I accountability documentation, driving vendor certification investments.
- Virtual Classrooms:Real-time video infrastructure with sub-150ms latency tolerance for synchronous instruction. Demand concentrates among urban districts replacing snow-day closures with remote seat-time equivalents.
- Educational Software:Subject-specific applications spanning math fact fluency to language acquisition.
- Assessment Tools:Automated engines delivering formative feedback without instructor grading overhead.
Learning Management Systems lead volumes today; Assessment Tools are gaining share fastest.
Delivery Model:
Schedule constraints and internet reliability shape family preferences across geographic bandwidth gradients.
- Synchronous Learning:Live video sessions requiring continuous connectivity. Working parents in suburban US districts reject rigid start times, compressing addressable market beyond urban cores with reliable fiber infrastructure.
- Asynchronous Learning:Self-paced content repositories accessible on demand. India's tier-2 and tier-3 cities drive expansion where affordable 4G handsets outpace fixed broadband penetration.
- Blended Learning:Rotational models combining physical classroom and digital instruction.
- Flipped Classroom:Pre-recorded content consumption preceding in-person application sessions.
Asynchronous Learning leads volumes today; Blended Learning is expanding most quickly.
Target Audience:
Purchasing authority fragmentation creates parallel sales cycles with divergent decision timelines.
- Students:End-users whose engagement metrics determine renewal rates. Gamification features and mobile-first interfaces dominate retention in competitive homeschooling segments.
- Parents:Primary buyers in supplemental and homeschooling markets. Suburban US co-ops now collective-purchase niche curricula, displacing district IT offices as volume aggregators.
- Teachers:Classroom practitioners seeking lesson planning efficiency.
- Administrators:Compliance officers accountable to state accountability frameworks.
Administrators lead volumes today; Parents are climbing the fastest.
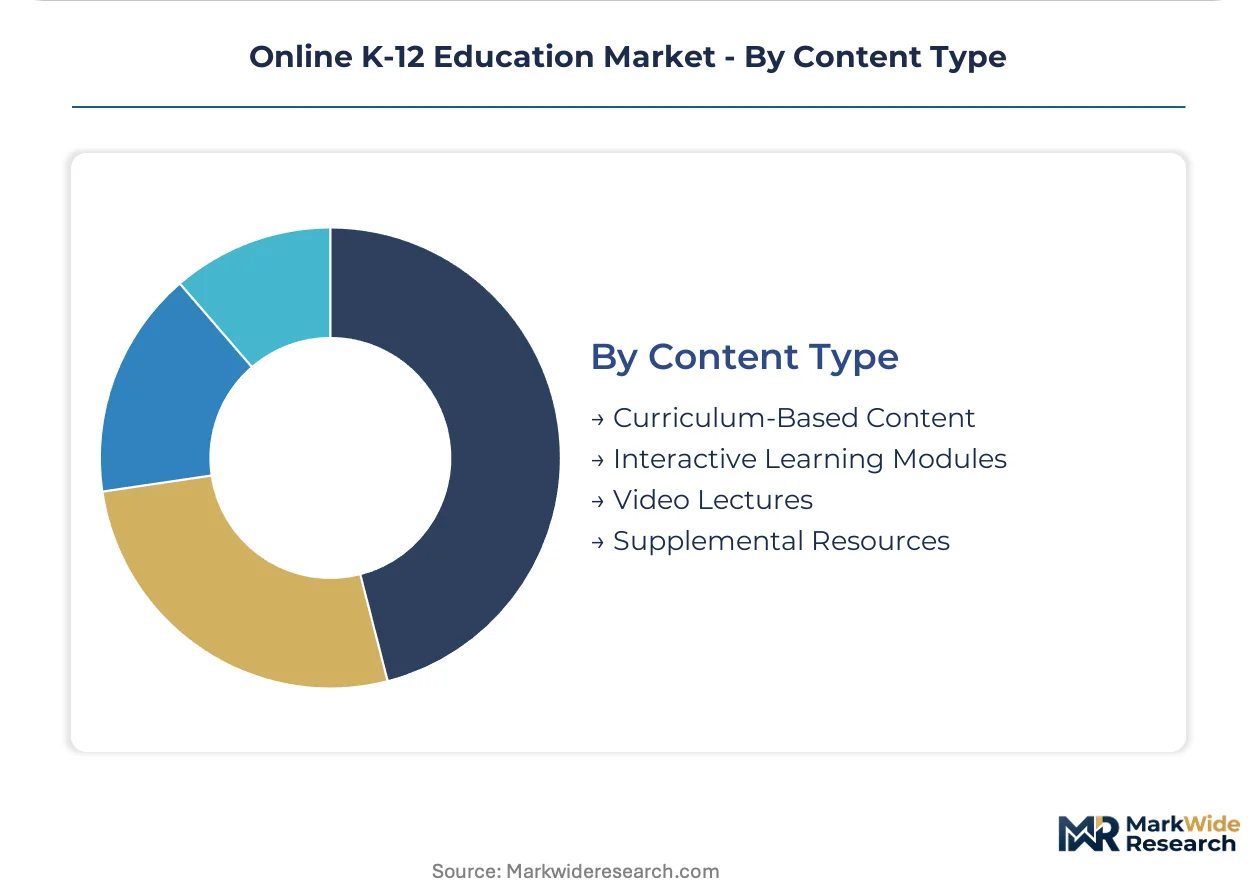
Content Type:
Interactivity depth determines pricing power and measurable outcome demonstration.
- Curriculum-Based Content:Standards-aligned scope-and-sequence materials mapped to state assessments. ESSA compliance requirements in US states constrain eligible vendors to those with documented alignment certifications.
- Interactive Learning Modules:Embedded formative assessment loops with real-time competency mapping. Premium pricing reflects demonstrated learning gain metrics that satisfy district procurement evaluation rubrics.
- Video Lectures:Passive streaming content with minimal learner input requirements.
- Supplemental Resources:Enrichment materials extending beyond core standards.
Curriculum-Based Content leads volumes today; Interactive Learning Modules show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's edtech corridor generates platform architecture innovations that diffuse through English-speaking markets before localization for emerging economies. Regulatory fragmentation across data sovereignty regimes forces operators to establish jurisdiction-specific infrastructure rather than centralized global delivery.
United States
Homeschooling co-ops in Texas and Florida aggregate demand for supplemental curricula outside district procurement channels. The US Department of Education enforces Section 508 accessibility standards and FERPA privacy protections that constrain vendor eligibility for Title I funding. Greater Boston's learning science cluster produces formative assessment engines purchased by suburban districts replacing legacy gradebook systems.
India
Affordable 4G handsets priced below $100 unlock first-time structured learning access for families in tier-2 and tier-3 cities previously excluded from formal digital education. The Ministry of Education mandates BIS-certified data localization for platform eligibility under National Education Policy procurement frameworks. Bangalore's technology corridor hosts joint ventures between foreign operators and domestic cloud providers establishing compliant server infrastructure.
China
Provincial education bureaus in Yangtze River Delta cities pilot AI tutor integrations within compulsory curriculum delivery. The Ministry of Education's after-school tutoring regulations reshape permissible content formats and pricing structures for private sector providers. Shenzhen's hardware ecosystem produces low-cost tablets pre-loaded with state-approved digital curricula for rural school distribution programs.
United Kingdom
Multi-academy trusts in England consolidate procurement authority for learning management systems across geographically dispersed school networks. The Department for Education's digital standards framework mandates interoperability specifications that favor API-first platform architectures. London's edtech venture cluster specializes in adaptive mathematics engines purchased by academy chains seeking measurable outcome documentation.
Brazil
Municipal education departments in São Paulo and Rio de Janeiro deploy asynchronous content repositories to address teacher shortage gaps in remote interior municipalities. The national education technology plan establishes connectivity infrastructure priorities that concentrate platform procurement in southeastern state capitals. Belo Horizonte's startup ecosystem produces vernacular-language assessment tools adapted for regional curriculum variations.
Online K-12 Education Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized instruction niches through marketplace aggregation models. The vendor base spans three maturity tiers: legacy learning management system incumbents with district-wide deployment relationships, adaptive algorithm specialists capturing math and literacy verticals, and peer-to-peer marketplace platforms connecting learners with non-traditional instructors. Dominant competitive moves include API partnership networks replacing exclusive procurement contracts and vernacular content localization for India tier-3 city expansion.
Within the adaptive learning tier, DreamBox Learning and Byju's exemplify algorithm-driven personalization architectures that reduce per-student instructional overhead. Outschool occupies the marketplace archetype, connecting distributed instructor supply with homeschooling demand clusters outside formal district channels. Coursera represents the university-branded downward extension model, packaging post-secondary credential authority for advanced secondary cohorts seeking transcript differentiation.
| Leading Market Players |
|---|
| Outschool |
| DreamBox Learning |
| Byju's |
| MasterClass |
| Newsela |
| Coursera |
| BrainPOP |
| Udacity |
| Udemy |
| Others |
Pricing and Supply Chain Analysis
Cloud compute capacity from Amazon Web Services, Microsoft Azure, and Google Cloud Platform flows through platform providers into three-tier pricing structures across premium, standard, and economy levels, with latency-sensitive synchronous instruction commanding 40-60% premiums over asynchronous repositories.
Pricing Analysis
Input-cost pass-through from hyperscale infrastructure providers forces adaptive assessment engine vendors into subscription-tiered SaaS models. Price differentiation hinges on FERPA certification status and real-time latency guarantees under 150 milliseconds. Pricing pressure stems from parental committee procurement in homeschooling co-ops that aggregate demand outside district IT channels. Working families in suburban US districts exhibit highest price sensitivity, while Indian tier-2 city first-time adopters prioritize low-entry subscription tiers over feature depth.
Supply Chain Analysis
Direct-to-district channels handle institutional Learning Management System deployments, while marketplace models distribute niche instructor supply to homeschooling aggregators. Content development concentrates in Silicon Valley's learning science corridor, Bangalore's joint-venture localization hubs, and Greater Boston's formative assessment clusters. Raw material dependencies include cloud compute instances, streaming bandwidth, and instructional design talent pools. Single-source vulnerability in hyperscale infrastructure exposes margin compression risk when capacity pricing fluctuates. Distribution runs through API-first integration partnerships rather than exclusive procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform operators can exploit arbitrage between India's BIS-certified data localization requirements and US FERPA compliance architectures, capturing cost advantages in joint-venture server infrastructure while maintaining premium pricing in privacy-regulated markets.
For Market Incumbents: Cement district-wide LMS relationships through legacy gradebook API integration investments that raise switching costs. Deepen backward integration into proprietary assessment algorithms to defend margin position against marketplace entrants aggregating non-traditional instructor supply. Prioritize certification maintenance for ESSA accountability documentation in Texas and Florida procurement frameworks.
For New Entrants and Emerging Players: The mid-tier price-point gap between Outschool's premium instructor marketplace and free asynchronous repositories creates white-space entry for vernacular-language content in India's tier-3 cities. Target homeschooling co-op collective purchasing committees in suburban US districts with modular subscription access. Deploy AI tutor convergence as the primary go-to-market angle for 24/7 personalized support without proportional staffing overhead.
For Investors and Strategic Acquirers: Roll-up economics work for adaptive algorithm specialists because fragmented instructional design talent scarcity prevents organic capability building at scale. Long-term viability favors platforms with demonstrated competency mapping engines and established API partnership networks. Monitor parental purchasing committee displacement of district IT offices as the inflection signal for marketplace model dominance over enterprise sales cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | District procurement fragmentation favors modular best-of-breed component assembly over monolithic LMS contracts. |
| Vernacular Content Localization | BIS-certified data localization requirements in India mandate domestic server infrastructure for government procurement eligibility. |
| Adaptive Assessment Engine Acquisition | Real-time competency mapping capabilities command premium pricing in ESSA-compliant district evaluation rubrics. |
| AI Tutor Convergence Development | Large language model integration enables 24/7 personalized support without proportional instructional staffing costs. |
| Homeschooling Co-op Channel Expansion | Parental purchasing committees in Texas and Florida aggregate demand outside traditional district IT procurement channels. |
Research Methodology
Multiple input streams — primary interviews with district procurement officers, platform engineering leads, and homeschooling co-op organizers, plus secondary validation against US Department of Education Section 508 filings, India's BIS certification registries, and National Education Policy procurement frameworks — were reconciled through bottom-up enrollment segmentation and top-down revenue triangulation across the analysis window.
Data-stream reconciliation anchored volume projections to modeled dimensions including delivery model, target audience purchasing authority, content interactivity depth, and regional regulatory compliance cluster. CAGRs were derived from segment-level enrollment trajectories and pricing tier evolution. Industry-specific forecast inputs incorporated affordable 4G handset penetration curves in Indian tier-2 cities and FERPA enforcement intensity indicators from federal audit disclosures.
Caveats apply where Section 508 compliance burden revisions or hyperscale infrastructure pricing volatility could materially shift the outlook for smaller platform developers. Forecasts reflect documented assumptions about parental purchasing committee adoption velocity and data sovereignty enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Online Tutoring Services Market