
 Digital Course Recorder Market | 2026-2036
Digital Course Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Course Recorder Market Insights
High-definition 4K capture specification is collapsing the gap between premium and mid-tier product tiers. Panasonic Corporation leverages its broadcast camera heritage to sustain professional-grade positioning. Sony Corporation anchors institutional procurement through direct education channel relationships. Kaltura, Inc. competes on software integration depth across learning management systems.
A digital course recorder captures, stores, and distributes audio-video instructional content through embedded codecs with H.264/H.265 compression and network-attached storage protocols. The device serves universities and corporate training departments seeking searchable, indexed lecture archives for asynchronous learner access. Cloud-based solutions represent the fastest-expanding product type as institutions shed on-premises server maintenance burdens. Educational institutions command the largest end-user segment, though corporate training exhibits steeper growth curves as enterprises standardize knowledge management platforms.
FCC equipment authorization requirements govern wireless transmission modules in US-sold units, while GDPR compliance shapes cloud storage architectures for European deployments. The Department of Education's accessibility guidelines under Section 508 mandate closed-caption integration, forcing hardware-software bundling strategies. Procurement officers must weigh total cost of ownership against interoperability certifications when evaluating vendor ecosystems.
Market Dynamics
Cloud migration mandates from the US Department of Education are compressing replacement cycles and forcing interoperability certifications across university procurement departments, reshaping vendor competitive positioning.
Growth Catalysts
- Section 508 Accessibility Mandates:Closed-caption integration requirements under Department of Education guidelines are forcing hardware-software bundling strategies that expand average contract values.
- Corporate Knowledge Management Standardization:Enterprise training departments are adopting searchable lecture archives to support asynchronous workforce development programs.
- H.265 Compression Adoption:Next-generation codec efficiency is reducing storage infrastructure requirements and enabling 4K capture at mid-tier price points.
Market Restraints
- Semiconductor Component Volatility:Image signal processors and wireless transmission modules face supply concentration risks concentrated in East Asian foundry networks.
- FCC Equipment Authorization Friction:Wireless transmission module certification timelines create six-to-nine month product launch delays for US market entry.
- On-Premises Server Substitution:Legacy institutions maintaining captive data centers resist cloud migration despite total cost of ownership advantages.
Strategic Opportunities
- GDPR-Compliant Cloud Architectures:European deployments require data residency controls that create first-mover advantages for vendors with EU-based infrastructure.
- AI-Generated Transcription Convergence:Natural language processing integration with capture hardware is creating searchable metadata layers that differentiate premium offerings.
- K-12 District Expansion:Underpenetrated primary and secondary education systems in Canada and Australia represent greenfield procurement opportunities.
Industry Challenges
- Legacy LMS Integration Complexity:Proprietary learning management system protocols require custom API development that extends deployment timelines.
- Interoperability Certification Backlogs:IMS Global conformance testing queues create bottlenecks for vendors seeking education sector procurement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Course Recorder Market |
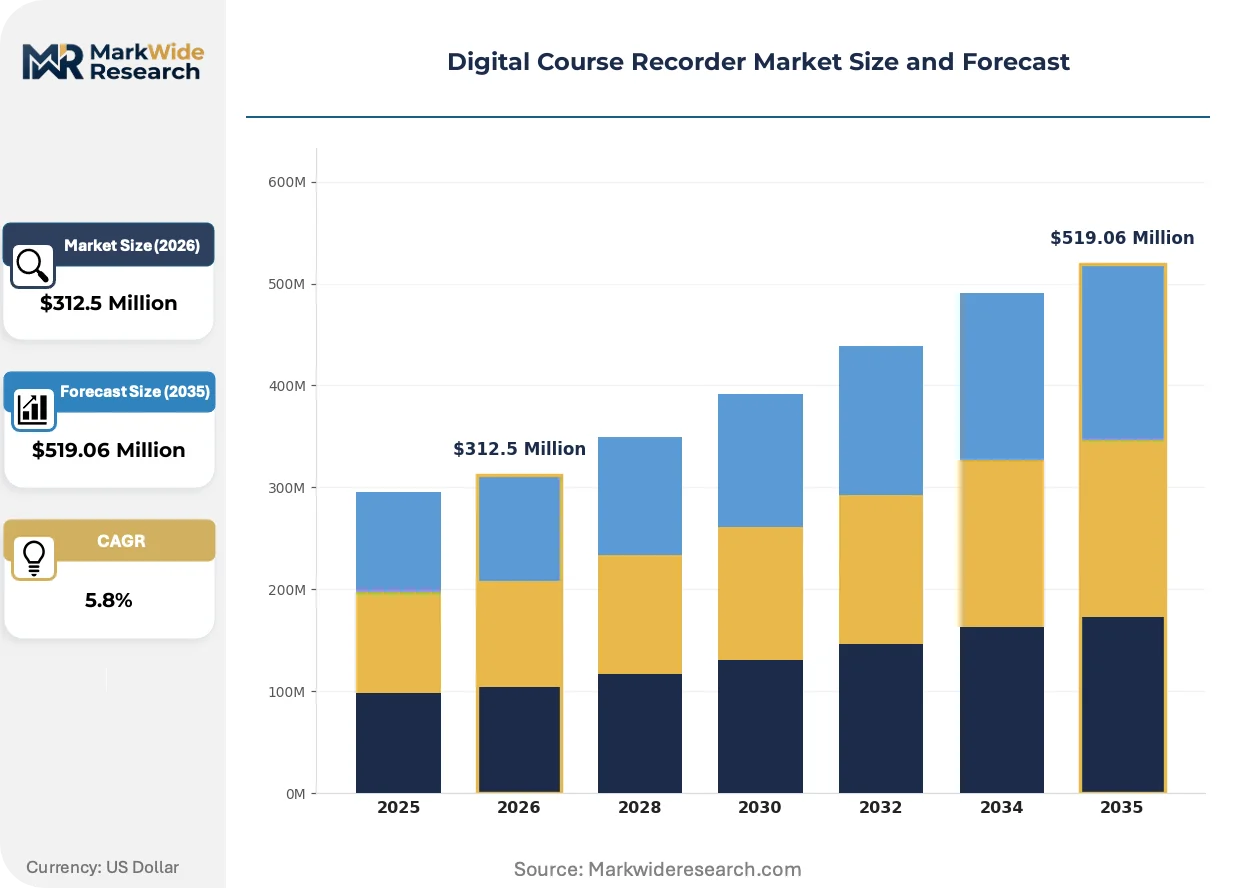
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Recorders, Integrated Systems, Cloud-Based Solutions, Hybrid Recorders Technology: Audio Capture, Video Capture, Streaming, Software Integration End User: Educational Institutions, Corporate Training, Online Learning Platforms, Government Agencies Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | TechSmith Corporation, Panopto, Inc., Echo360, Inc., Kaltura, Inc., Sony Corporation, Zoom Corporation, Panasonic Corporation, Samsung Electronics Co., Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Course Recorder Market Trends and Innovations
Artificial intelligence integration is reshaping how capture hardware generates metadata, while regulatory pressure on data residency and accessibility compliance is forcing architectural redesigns across vendor roadmaps.
Edge-based AI inference engines are decomposing the traditional separation between capture hardware and post-production workflows. University IT departments are deploying these modules to generate real-time transcription and automated chapter indexing without cloud round-trips. This capability compression is collapsing the feature gap between installed appliances and software-as-a-service alternatives.
FCC equipment authorization requirements for wireless transmission modules are tightening electromagnetic compatibility testing standards. Vendors must now submit pre-production units for extended evaluation periods before US market release. Higher education procurement officers are responding by prioritizing wired Ethernet variants that bypass certification delays entirely.
Subscription-based hardware provisioning is displacing capital expenditure models in community college systems. Leasing arrangements bundle capture appliances with cloud storage and technical support into per-seat annual contracts. California and Texas public institutions are piloting these arrangements to align classroom technology spending with enrollment fluctuations.
Digital Course Recorder Market Segmentation
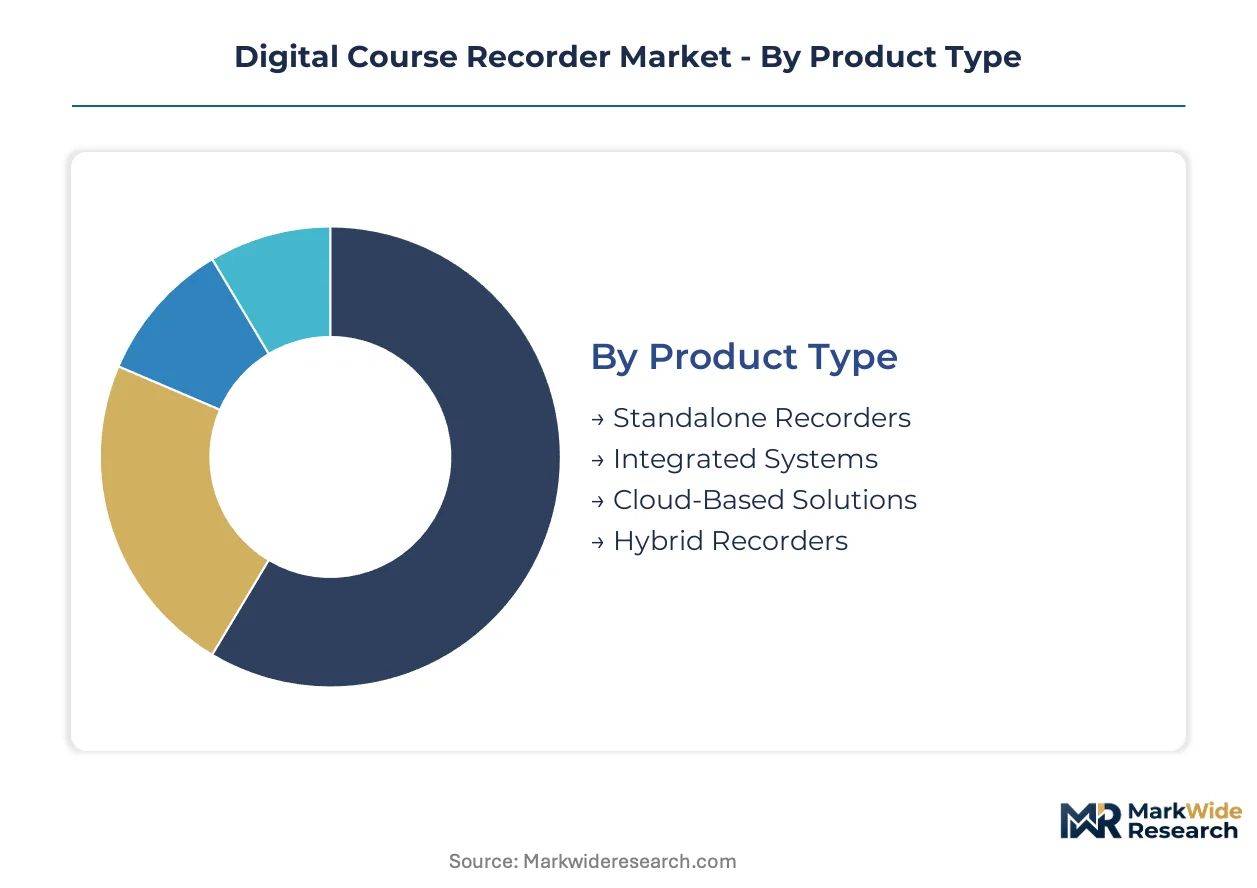
Segmentation in the digital course recorder market reveals distinct procurement patterns across hardware-centric and software-centric buyers. Channel strategy and technology integration depth vary sharply between educational bulk contracts and corporate self-service purchases.
Product Type:
Channel mix splits sharply: standalone units flow through distributors to budget-constrained institutions, while cloud-based solutions bypass hardware channels entirely via direct vendor relationships.
- Standalone Recorders:Self-contained appliances with embedded codecs and local storage targeting departments with limited IT support. Procurement concentrates in United States community college systems where capital expenditure cycles align with state budget approvals and on-premises data retention policies persist.
- Cloud-Based Solutions:Browser-accessible capture platforms with vendor-managed infrastructure and API-first architectures. Demand is accelerating fastest among research universities in California and Massachusetts seeking to eliminate server maintenance overhead and scale across distributed campuses.
- Integrated Systems:Room-scale installations combining capture hardware with control systems and display management.
- Hybrid Recorders:Appliances with selective cloud synchronization for institutions navigating mixed data sovereignty requirements.
By volume, standalone recorders lead. By growth pace, cloud-based solutions are expanding most quickly.
Technology:
Cost tiering separates premium multi-codec stacks from baseline single-stream offerings, with software integration commanding the highest per-seat pricing.
- Software Integration:Middleware layers connecting capture hardware to learning management systems via IMS Global conformance. Corporate training departments in Texas and Illinois prioritize these stacks for Salesforce and Workday embedding.
- Video Capture:H.264 and H.265 encoding engines with 1080p to 4K resolution pipelines. United States higher education procurement favors 4K specification for lecture hall renovations, compressing price premiums historically attached to broadcast-grade tiers.
- Audio Capture:Multi-channel microphone arrays with noise cancellation and speaker identification.
- Streaming:Real-time protocol delivery for synchronous remote participation.
Software integration claims the steepest margin expansion. Video capture maintains the largest installed base.
End User:
Application context dictates feature prioritization: accessibility compliance dominates education, while analytics integration drives corporate selection.
- Educational Institutions:Universities and colleges requiring Section 508 closed-caption compliance and FERPA-aligned data handling. Deployment concentrates in United States public systems where Department of Education interoperability mandates accelerate replacement timelines.
- Corporate Training:Enterprise learning and development departments standardizing searchable knowledge archives. Financial services firms in New York and technology companies in Washington State exhibit the steepest adoption curves for asynchronous workforce development platforms.
- Online Learning Platforms:Massive open online course providers and credentialing platforms.
- Government Agencies:Federal and state training departments with classified or controlled unclassified information handling requirements.
Educational institutions dominate contract volume. Corporate training is climbing the fastest.
Distribution Channel:
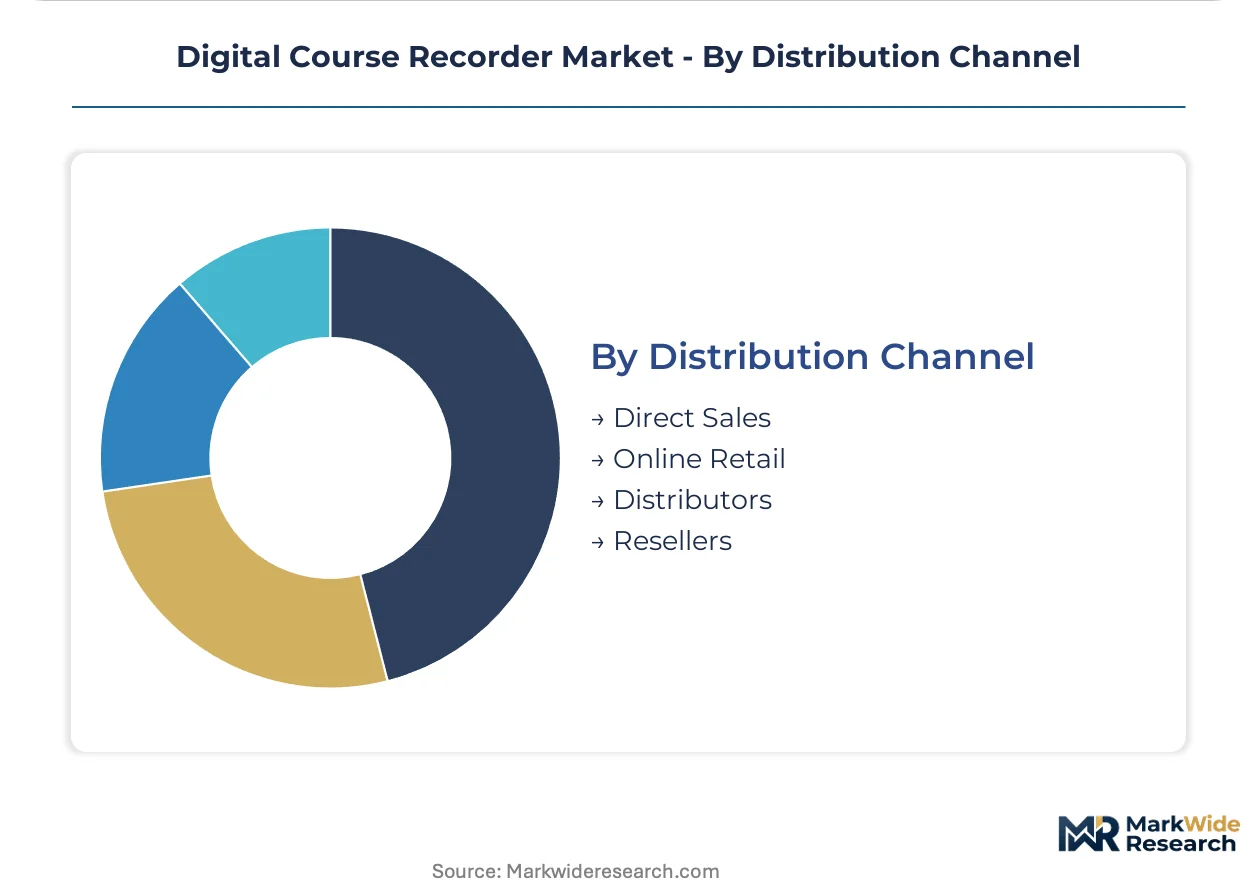
Customer type determines channel selection: large institutions negotiate direct, while mid-tier buyers rely on value-added resellers for implementation support.
- Direct Sales:Vendor field teams managing enterprise procurement cycles and custom integration scopes. United States research universities and Fortune 500 training departments transact primarily through this channel, with average contract values supporting dedicated account management.
- Distributors:Wholesale intermediaries stocking inventory for rapid fulfillment of standardized configurations. Regional education cooperatives in the Midwest and Southeast aggregate demand through this channel to achieve volume pricing.
- Online Retail:Self-service procurement portals targeting small departments and individual classroom deployments.
- Resellers:Value-added partners bundling installation, training, and local technical support.
Direct sales captures the highest revenue per transaction. Distributors move the greatest unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in educational technology hardware, exporting lecture capture systems to Canadian and Australian institutions while importing specialized codec components from Taiwanese and South Korean suppliers.
United States
Research universities in California and Massachusetts are driving replacement cycles as Department of Education interoperability mandates compress hardware refresh timelines. FCC equipment authorization requirements for wireless transmission modules create six-to-nine month certification delays, pushing procurement officers toward wired Ethernet configurations. The Boston-Cambridge cluster anchors institutional procurement volume, with MIT and Harvard systems influencing vendor roadmaps through direct collaboration.
Germany
Technical universities in Bavaria and Baden-Württemberg are standardizing searchable lecture archives for engineering and applied science programs. GDPR compliance requirements shape cloud storage architectures, forcing vendors to deploy EU-based infrastructure for data residency controls. The Munich-Stuttgart corridor concentrates deployment activity, with TU Munich and Karlsruhe Institute of Technology serving as reference sites for H.265 compression adoption.
United Kingdom
Russell Group universities are expanding lecture capture deployments to support hybrid delivery models and international student recruitment. The Office for Students accessibility guidelines mandate closed-caption integration, accelerating hardware-software bundling procurement strategies. The Oxford-Cambridge-London triangle dominates contract value, with Imperial College London and University College London driving 4K specification requirements for new lecture hall installations.
Japan
Corporate training departments in Tokyo and Osaka are adopting searchable knowledge archives to standardize workforce development across multinational operations. METI digital transformation incentives subsidize cloud migration for small and medium enterprises, expanding addressable market beyond large institutions. The Keihin industrial corridor concentrates deployment, with Hitachi and Toshiba training centers serving as reference implementations for AI-generated transcription integration.
Australia
Group of Eight universities are replacing legacy on-premises systems with vendor-managed cloud platforms to reduce server maintenance overhead. TGA-equivalent equipment safety standards govern hardware importation, creating compliance friction for non-established vendors. The Melbourne-Sydney corridor dominates procurement volume, with Monash University and University of Sydney piloting subscription-based hardware provisioning models aligned with enrollment fluctuations.
Digital Course Recorder Market Competitive Landscape
Listed leaders compete with private specialists across channel strategy and integration depth, creating a tiered structure where scale advantages in direct sales confront agility in custom deployments. Panasonic Corporation and Sony Corporation leverage broadcast heritage and institutional relationships to sustain premium positioning. Kaltura, Inc. competes through software integration depth across learning management systems. Three archetypes dominate: diversified electronics conglomerates with education verticals, pure-play lecture capture specialists, and video conferencing platforms extending into archival workflows. Competitive moves concentrate on interoperability certification acceleration and AI-generated transcription capability integration.
Within the diversified electronics tier, Panasonic Corporation and Sony Corporation exemplify heritage positioning through direct education channel relationships. Kaltura, Inc. occupies a specialist position, anchoring the software-centric competitive vector through API-first architectures and learning management system middleware. These three represent distinct strategic postures: hardware heritage, software integration depth, and platform extension from adjacent categories.
| Leading Market Players |
|---|
| TechSmith Corporation |
| Panopto, Inc. |
| Echo360, Inc. |
| Kaltura, Inc. |
| Sony Corporation |
| Zoom Corporation |
| Panasonic Corporation |
| Samsung Electronics Co., Ltd. |
| Koninklijke Philips N.V. |
| Others |
Pricing and Supply Chain Analysis
FCC equipment authorization requirements for wireless transmission modules gate both vendor qualification and price tiering simultaneously. Six-to-nine month certification timelines compress margins for entrants while allowing established players to command premiums on pre-certified wired Ethernet alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IMS Global certification depth and after-sales integration support. Pricing pressure stems from H.265 compression collapsing performance gaps between mid-tier and broadcast-grade tiers. Community college systems exhibit highest price sensitivity, while research universities prioritize interoperability over unit cost.
Supply Chain Analysis
Taiwanese foundry concentration for image signal processors and South Korean memory fabrication create chokepoint exposure for component sourcing. Supply draws from specialized codec component suppliers in Taiwan, South Korea, and Japan. Single-source vulnerability runs through East Asian semiconductor networks. Distribution runs through education-focused value-added resellers and direct vendor field teams serving large institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as Department of Education interoperability mandates force compressed replacement cycles across university procurement departments.
For Market Incumbents: Consolidate around IMS Global certification backlogs to lock out challengers. Deepen vertical integration into AI-generated transcription engines before software-as-a-service alternatives commoditize metadata layers. Acquire regional value-added resellers in the Midwest and Southeast to tighten channel control against direct-sales competitors. For New Entrants and Emerging Players: Differentiate on GDPR-compliant cloud architectures with EU-based infrastructure to capture European procurement share. Target K-12 districts in Canada and Australia where incumbent penetration remains shallow. Lead with subscription-based hardware provisioning pilots aligned to enrollment-driven budget cycles. For Investors and Strategic Acquirers: Section 508 accessibility mandate enforcement reshapes the acquisition landscape toward vendors with closed-caption integration capabilities. Five-to-ten year viability favors software-centric specialists over hardware-legacy conglomerates. Watch for IMS Global conformance testing queue clearance as inflection signal for vendor eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Transcription Engine Integration | Edge-based inference capabilities differentiate premium offerings from commodity capture hardware. |
| GDPR-Compliant Cloud Infrastructure | EU data residency controls unlock procurement eligibility in German and UK university systems. |
| IMS Global Certification Acceleration | Conformance testing clearance removes bottlenecks for education sector contract eligibility. |
| Subscription Hardware Provisioning | Per-seat annual contracts align classroom technology spending with enrollment fluctuations. |
| Regional Reseller Acquisition | Channel control in Midwest and Southeast aggregates demand through education cooperatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across university IT directors, classroom technology procurement officers, learning management system integration specialists, and vendor channel managers. Secondary validation drew from FCC equipment authorization filings, Department of Education interoperability guidelines, IMS Global conformance registries, and education technology trade data. Bottom-up unit deployment estimates triangulated against top-down institutional budget allocations.
Across the analysis window, forecasts model product type segmentation alongside deployment model, institution size tier, integration complexity, and regional regulatory cluster. CAGRs derive from replacement cycle compression rates and cloud migration penetration curves. H.265 codec adoption timelines and AI transcription capability diffusion serve as technology-specific forecast inputs.
Material uncertainties — semiconductor supply volatility, certification timeline extensions, and federal education funding shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Department of Education mandate enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Global Digital Education Market