
 E-Learning Services Market | 2026-2036
E-Learning Services Market Size, Share, and Industry Trends Forecast 2026-2036
E-Learning Services Market Intelligence
Enterprise buyer concentration is shifting as large corporations consolidate vendor relationships around full-stack learning platforms rather than point solutions. Coursera leverages its university partnerships to sustain premium credentialing revenue. Skillsoft competes through specialized leadership and compliance content libraries. Blackboard Inc. anchors its position in higher education institutional contracts across North American campuses.
E-learning services encompass the design, delivery, and administration of digital educational content through internet-connected platforms, typically utilizing cloud infrastructure with 99.9% uptime SLAs and SCORM-compliant content interoperability standards to enable scalable workforce reskilling and academic credentialing. The Learning Management System segment dominates institutional procurement cycles with multi-year enterprise agreements, while the Artificial Intelligence technology layer is expanding fastest through automated personalization engines that adjust content difficulty in real time. Corporate Training services command the strongest margin pools due to measurable ROI requirements and executive sponsorship budgets.
FDA oversight applies to clinical education modules, while GDPR and the EU AI Act impose strict data processing and algorithmic transparency mandates on European platform deployments. India's BIS standards and PLI scheme incentives are accelerating domestic platform development and localization requirements. Stakeholders must monitor how divergent regulatory timelines across jurisdictions will fragment compliance architectures and reshape vendor qualification criteria.
Market Dynamics
Enterprise procurement of AI-powered adaptive learning platforms is compressing vendor selection cycles while fragmenting compliance architectures across GDPR, the EU AI Act, and India's BIS standards.
Growth Catalysts
- GDPR and EU AI Act mandates:European data governance requirements are forcing platform upgrades, creating replacement demand for legacy LMS infrastructure that lacks algorithmic transparency features.
- Corporate training budgets:Fortune 500 enterprises are consolidating vendor relationships around full-stack solutions with measurable ROI dashboards for executive sponsorship.
- India's PLI scheme:Domestic platform developers are receiving production-linked incentives to localize cloud infrastructure and content libraries for government digital education initiatives.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud control essential hosting capacity, exposing mid-size edtech providers to margin pressure from hyperscaler pricing power.
- SCORM interoperability limitations:Legacy content standards create technical debt that blocks real-time personalization engine integration without expensive re-authoring.
- Clinical education FDA oversight:Medical training modules require 21 CFR Part 11 validation, extending deployment timelines and disqualifying non-compliant platforms from healthcare contracts.
Strategic Opportunities
- Tier-2 Indian city penetration:Broadband expansion into Nagpur, Indore, and Kochi is opening addressable student populations previously unreachable by metro-centric platforms.
- VR-AR convergence:Immersive simulation technology is merging with haptic feedback systems to create surgical training and industrial safety modules with premium pricing power.
- Outcome-based credentialing:Skills-verification APIs are enabling employers to bypass traditional degree requirements, creating direct-to-enterprise licensing models that bypass institutional intermediaries.
Industry Challenges
- SCORM-to-xAPI migration complexity:Learning record store integration requires specialized engineering talent scarce outside San Francisco, London, and Bangalore talent pools.
- Multi-jurisdiction data residency:EU AI Act algorithmic audit requirements conflict with India's data localization mandates, forcing expensive architectural duplication for cross-border deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Learning Services Market |
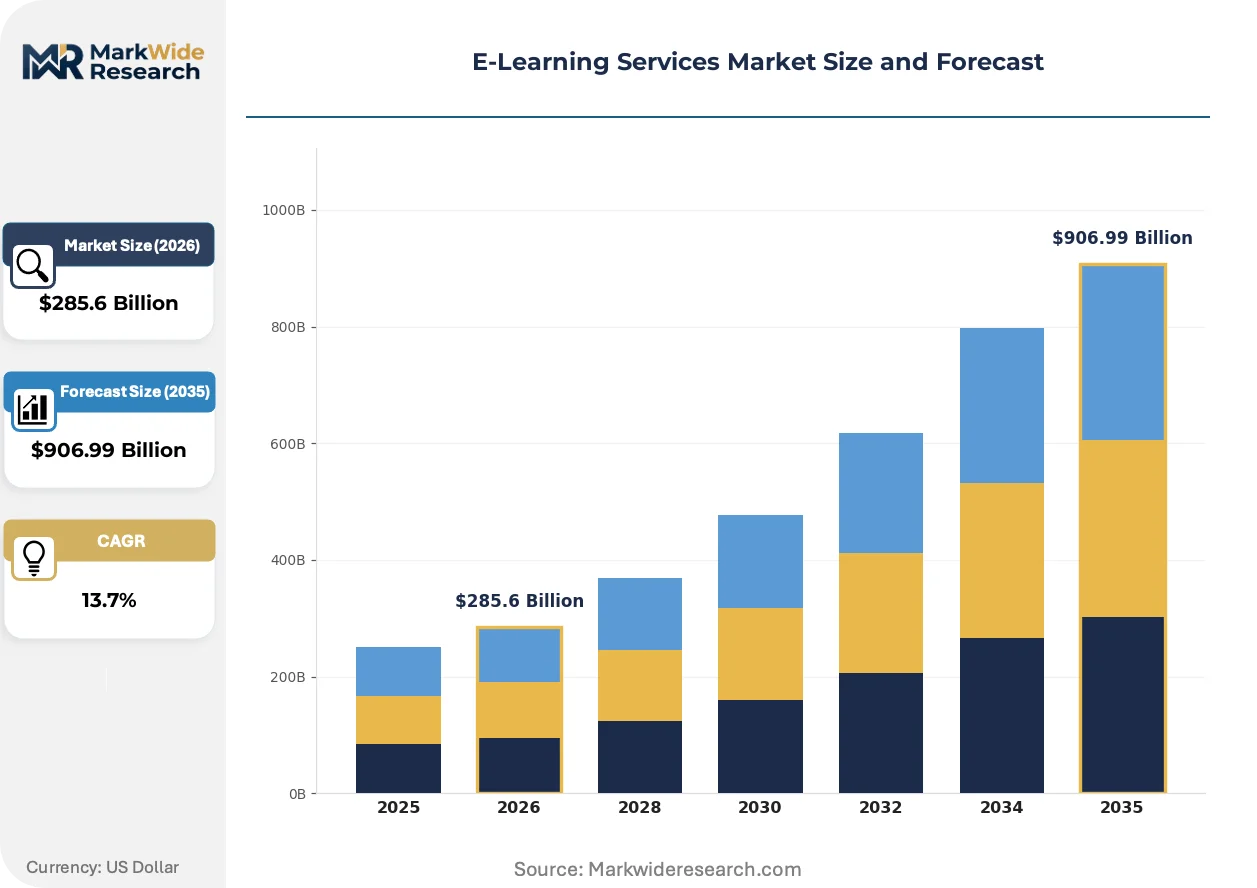
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $906.99 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Development, Learning Management System, Virtual Classroom, Assessment & Evaluation, Corporate Training, Technical Support Delivery Model: Self-Paced, Instructor-Led, Blended Learning, Gamified Learning, Microlearning, Social Learning End User: K-12 Schools, Higher Education Institutions, Corporate Enterprises, Government Agencies, Non-Profit Organizations, Vocational Institutes Technology: Cloud-Based Platforms, Mobile Learning, Artificial Intelligence, Virtual Reality, Augmented Reality, Big Data Analytics |
| Companies Covered | Coursera, Udemy, Inc., Skillsoft, LinkedIn Learning, Accenture, Infosys, NIIT Ltd., Blackboard Inc., Instructure Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Learning Services Market Strategic Shifts & Innovations
Generative AI is rewriting content production economics while regulatory fragmentation forces architectural specialization. Three developments are compressing competitive timelines.
Adaptive personalization engines are expanding into corporate compliance training, where Deutsche Bank and Unilever are deploying real-time difficulty adjustment to reduce seat time by thirty percent without sacrificing knowledge retention. The technology is expanding into previously static content categories, compressing the addressable market for traditional video-course libraries.
The EU AI Act's algorithmic transparency requirements are mandating explainable AI documentation for all automated grading and recommendation systems. European higher education institutions must now maintain audit trails for every learner pathway decision, favoring vendors with pre-built compliance tooling over retrofit-dependent competitors. German and French procurement officers are prioritizing platforms with certified conformity assessment procedures.
Skills-based hiring is displacing degree-centric credential verification across technology and healthcare verticals. LinkedIn and Indeed are integrating direct assessment APIs that bypass institutional transcripts, compressing the value capture opportunity for university-affiliated platforms. This pattern is most visible in Bangalore's software services sector and Austin's healthcare technology cluster, where employer consortia are building shared competency frameworks independent of academic accreditors.
E-Learning Services Market Segmentation
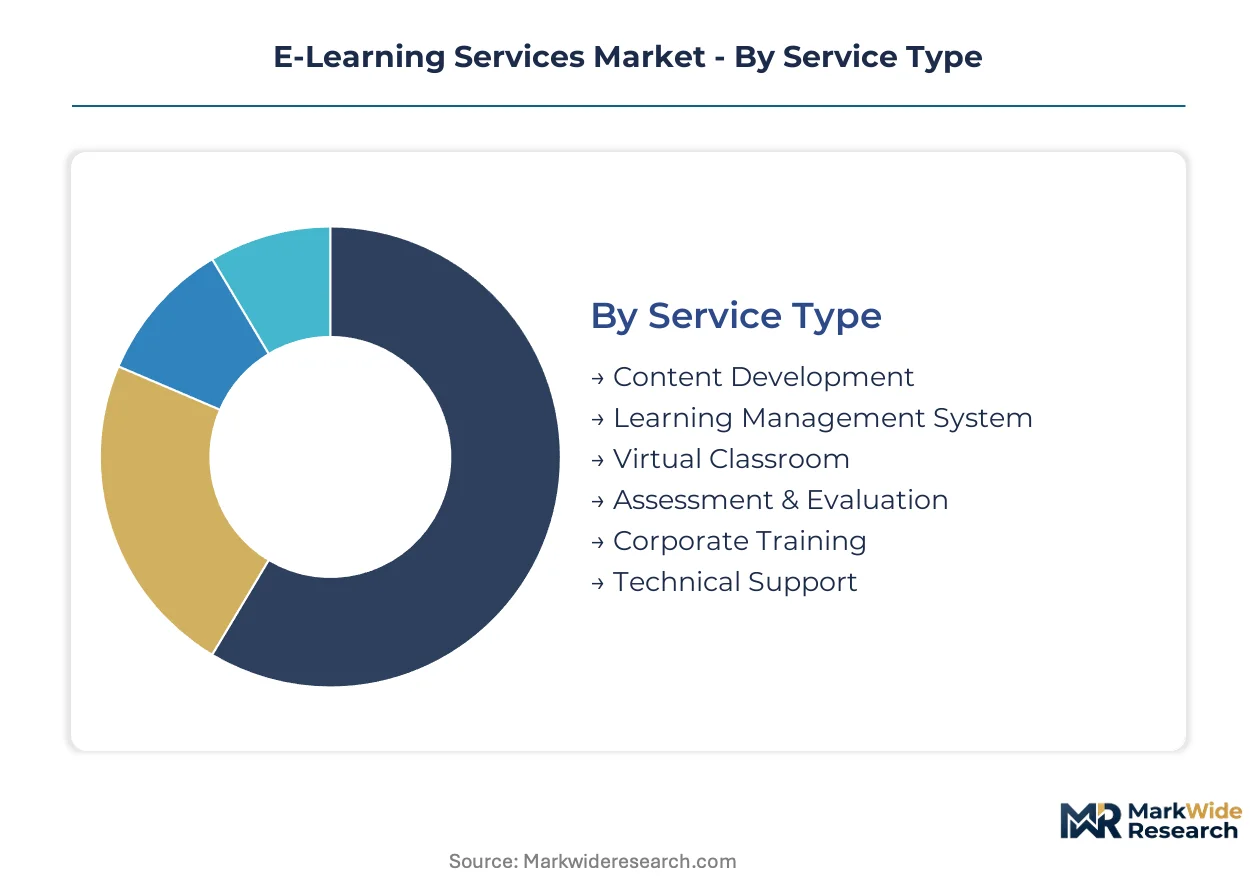
Segmentation reveals how procurement patterns diverge across institutional buyers, with cloud infrastructure choices and AI integration depth becoming primary vendor selection criteria. Enterprise contracts increasingly bundle multiple service layers, compressing the addressable market for standalone point solutions.
Service Type:
Upgrade cycles are accelerating as legacy SCORM-based installations face replacement pressure from xAPI-compliant architectures demanding real-time learning record interoperability.
- Content Development:Authoring tools now embed generative AI for automated module creation, with pharmaceutical and healthcare verticals driving demand for FDA-validated clinical education content. European universities are prioritizing vendors with pre-built GDPR-compliant asset libraries.
- Learning Management System:Multi-year enterprise agreements dominate institutional procurement, with 99.9% uptime SLAs and SCORM interoperability remaining baseline requirements. India's government digital education initiatives are accelerating campus-wide deployments across state universities.
- Virtual Classroom:Real-time video infrastructure with breakout room functionality serves K-12 districts and vocational institutes requiring synchronous instruction.
- Assessment & Evaluation:Automated proctoring and plagiarism detection tools address integrity requirements in higher education credentialing programs.
- Corporate Training:Measurable ROI dashboards and skills-verification APIs command premium pricing from Fortune 500 executive sponsors.
- Technical Support:24/7 helpdesk services with localized language coverage support platform adoption in tier-2 Indian cities.
Learning Management System sits at the top of the volume ranking, with Corporate Training climbing the fastest.
Delivery Model:
Cost tier differentiation separates premium adaptive engines from commoditized video libraries, with seat-time reduction metrics becoming the primary value justification.
- Self-Paced:Asynchronous module libraries serve individual learners and small teams with flexible completion schedules. Massive open online course platforms leverage this model for scale economics in emerging markets.
- Instructor-Led:Scheduled virtual sessions with live Q&A support complex technical certification programs requiring expert facilitation. German industrial training consortia favor this model for apprenticeship compliance.
- Blended Learning:Hybrid formats combining synchronous and asynchronous elements dominate K-12 and higher education institutional contracts. French vocational institutes mandate minimum on-site hours alongside digital components.
- Gamified Learning:Points, badges, and leaderboards drive engagement in corporate compliance training modules. Behavioral analytics integration enables difficulty adjustment based on performance patterns.
- Microlearning:Bite-sized content modules under ten minutes address mobile-first workforces and just-in-time skill gaps. Banking and financial services sectors deploy these for regulatory update distribution.
- Social Learning:Peer-to-peer discussion forums and collaborative project tools support cohort-based professional development programs.
Self-Paced captures the largest addressable base, while Microlearning gains share fastest among enterprise buyers.
End User:
Customer type concentration varies sharply by contract value, with corporate enterprises consolidating vendor relationships around full-stack platforms while K-12 remains fragmented across district-level procurement.
- K-12 Schools:District-wide learning management deployments require COPPA-compliant data handling and parent portal integration. State-level procurement consortia in Texas and California are consolidating vendor lists.
- Higher Education Institutions:University systems prioritize credentialing revenue protection through branded micro-certificate programs. European institutions face EU AI Act audit requirements for automated grading systems.
- Corporate Enterprises:Reskilling budgets with executive sponsorship drive demand for skills-verification APIs and competency framework alignment. Deutsche Bank and Unilever deployments emphasize seat-time reduction metrics.
- Government Agencies:Civil service training programs require localized content and multi-language support for federal workforce development.
- Non-Profit Organizations:Grant-funded initiatives prioritize open-source platforms with minimal licensing overhead for community education programs.
- Vocational Institutes:Hands-on trade certification programs integrate simulation technology for equipment training without physical asset risk.
Corporate Enterprises anchor contract value concentration, with Vocational Institutes expanding most quickly through simulation technology adoption.
Technology:
Application maturity separates proven cloud infrastructure from emerging immersive formats, with AI and analytics layers commanding implementation priority in enterprise roadmaps.
- Cloud-Based Platforms:AWS, Azure, and Google Cloud hosting underpins scalable delivery with 99.9% uptime SLAs. India's BIS standards and data localization mandates are forcing architectural duplication for domestic deployments.
- Mobile Learning:Responsive design and offline synchronization address connectivity gaps in tier-2 Indian cities and emerging market segments.
- Artificial Intelligence:Adaptive personalization engines adjust content difficulty in real time, with Deutsche Bank reporting thirty percent seat-time reduction. EU AI Act transparency requirements favor vendors with pre-built explainable AI documentation.
- Virtual Reality:Immersive simulation technology creates surgical training and industrial safety modules with premium pricing power. Haptic feedback integration is advancing procedural skill transfer fidelity.
- Augmented Reality:Overlay visualization supports equipment maintenance training and on-the-job guidance for field service technicians.
- Big Data Analytics:Learning record store integration enables predictive dropout intervention and curriculum optimization across large student populations.
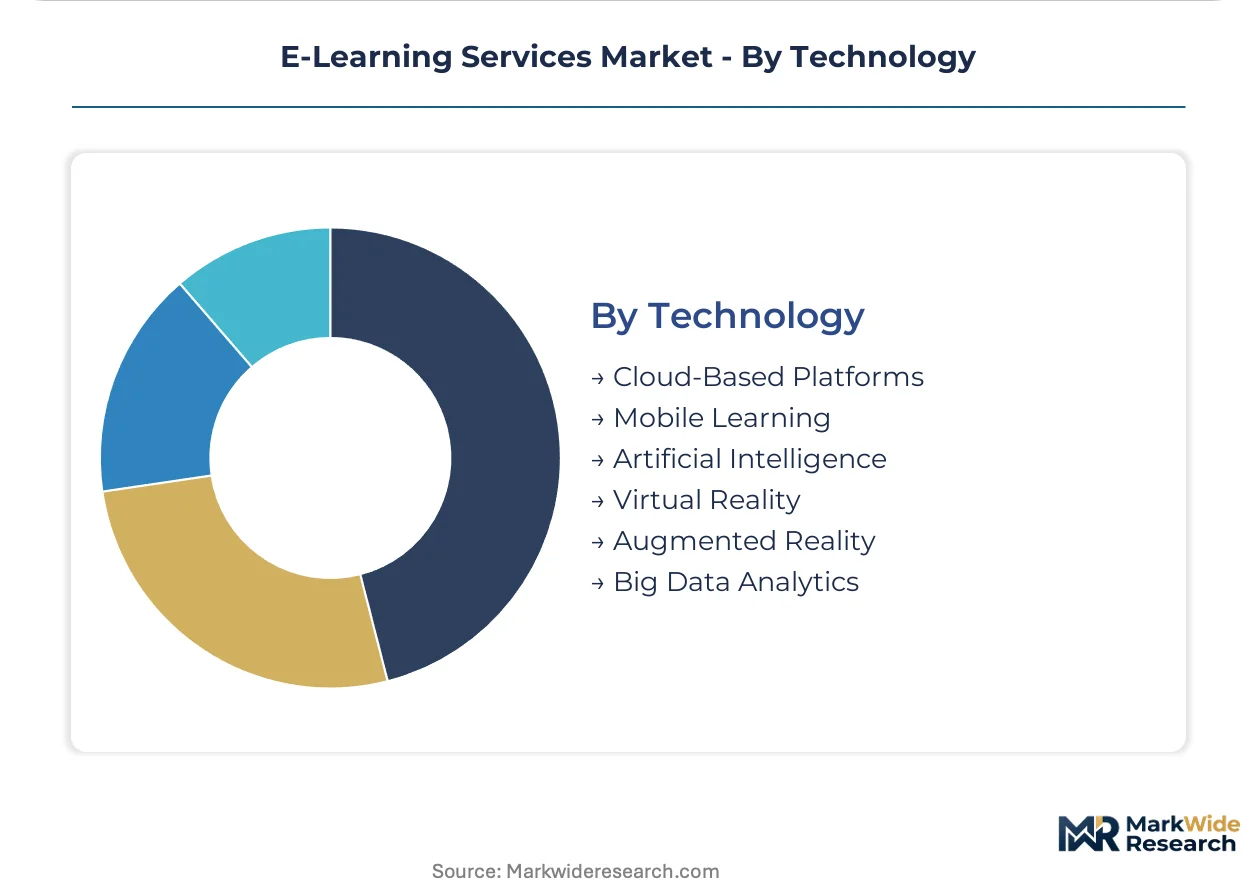
Cloud-Based Platforms dominate current infrastructure spend, with Artificial Intelligence attracting the steepest investment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's government digital education initiatives are accelerating platform deployment faster than European compliance upgrades, while the United States maintains the largest corporate training contract values. Regulatory fragmentation across GDPR, the EU AI Act, and India's BIS standards is forcing vendors into expensive architectural duplication.
United States
Fortune 500 enterprises are consolidating vendor relationships around full-stack learning platforms with measurable ROI dashboards. FDA oversight through 21 CFR Part 11 extends deployment timelines for clinical education modules in healthcare contracts. The Austin healthcare technology cluster and San Francisco Bay Area talent pools are driving skills-verification API development for employer consortia.
Germany
Industrial training consortia favor instructor-led formats for apprenticeship compliance, while Deutsche Bank deploys adaptive personalization engines reporting thirty percent seat-time reduction. The EU AI Act mandates explainable AI documentation for automated grading systems, favoring vendors with certified conformity assessment procedures. Procurement officers in Berlin and Munich prioritize platforms with pre-built algorithmic audit trails.
India
Government digital education initiatives and a massive student population are accelerating platform deployment across state universities. BIS standards and PLI scheme incentives are accelerating domestic platform development and localization requirements. Broadband expansion into Nagpur, Indore, and Kochi is opening addressable student populations previously unreachable by metro-centric platforms.
France
Vocational institutes mandate minimum on-site hours alongside digital components, creating hybrid procurement requirements for blended learning platforms. CNIL enforcement of GDPR data processing rules imposes strict learner data governance on higher education deployments. The Paris-Saclay university cluster is piloting EU AI Act-compliant automated recommendation systems with full algorithmic transparency documentation.
United Kingdom
University systems prioritize credentialing revenue protection through branded micro-certificate programs competing with direct-to-enterprise licensing models. ICO guidance on automated decision-making affects AI-powered adaptive learning platform deployments across London and Southeast institutional buyers. The Greater Manchester digital skills partnership is building employer-verified competency frameworks independent of traditional academic accreditors.
E-Learning Services Market Key Industry Players
United States producers anchor the premium enterprise tier; Indian specialists hold government contract and localization advantages. The vendor structure fragments across three tiers: full-stack platform consolidators, content-specialized libraries, and regional infrastructure providers. Two strategic archetypes dominate—university partnership credentialing platforms and corporate compliance training specialists. M&A activity concentrates on AI personalization engine acquisitions, while strategic partnerships target hyperscaler cloud infrastructure commitments.
Among platform providers, Coursera exemplifies the university-affiliated credentialing archetype, Skillsoft occupies the corporate compliance content specialization tier, and Blackboard Inc. anchors institutional learning management system deployments. These three represent distinct competitive positioning vectors: premium credentialing revenue protection, measurable enterprise ROI dashboards, and multi-year campus-wide procurement contracts respectively.
| Leading Market Players |
|---|
| Coursera |
| Udemy, Inc. |
| Skillsoft |
| LinkedIn Learning |
| Accenture |
| Infosys |
| NIIT Ltd. |
| Blackboard Inc. |
| Instructure Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up learning management specialists are consolidating fragmented vendor bases across North America and Europe, compressing margin pools for mid-tier content developers while concentrating pricing power among full-stack platform owners with multi-year enterprise lock-in contracts.
Pricing Analysis
Capacity additions in India's tier-2 cloud regions are reshaping price floors for localization-compliant deployments, forcing premium-tier vendors to justify cost differentials through EU AI Act audit tooling and FDA-validated clinical modules. SaaS-tiered subscriptions dominate enterprise procurement, with pricing stratifying across premium adaptive engines, standard LMS bundles, and economy self-paced libraries. Certification-grade differentiation separates GDPR-compliant European deployments from baseline cloud hosting. Price erosion runs through commoditized video-course segments as generative AI content tools democratize production. Corporate training buyers show lowest price sensitivity due to measurable ROI mandates, while K-12 districts face acute budget constraints.
Supply Chain Analysis
Cross-border data transfer costs are elevating total cost of ownership for multi-jurisdiction deployments, particularly where EU AI Act algorithmic audit requirements conflict with India's BIS localization mandates. Cloud infrastructure concentrates in the United States, Ireland, and Singapore for global delivery, with domestic replication mandated for Indian government contracts. Platform development draws from specialized engineering talent pools in San Francisco, London, and Bangalore. Single-source vulnerability rests on hyperscaler pricing power over AWS, Azure, and Google Cloud. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and regional system integrators for localized government deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory compliance costs in Europe create margin expansion opportunities for Indian platforms serving price-sensitive emerging markets with equivalent technical capabilities at lower operational overhead.
For Market Incumbents: Deploy pre-built algorithmic audit trail tooling to capture EU AI Act upgrade cycles before retrofit-dependent competitors achieve certification. Consolidate vendor relationships around full-stack platforms with embedded skills-verification APIs to defend against direct-to-enterprise licensing models displacing institutional intermediaries. Threat substitution from LinkedIn and Indeed assessment APIs compresses credentialing revenue capture for university-affiliated platforms. For New Entrants and Emerging Players: Enter via tier-2 Indian city penetration where broadband expansion into Nagpur, Indore, and Kochi has opened addressable student populations previously unreachable by metro-centric incumbents. Target vocational institutes adopting simulation technology for equipment training without physical asset risk. Go-to-market through state-level procurement consortia in Texas and California consolidates fragmented K-12 district relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap AI personalization engine developers lacking enterprise distribution but holding technical differentiation in adaptive difficulty adjustment. Long-term viability hinges on regulatory compliance tooling becoming table stakes rather than premium tier. Acquisition target archetype: xAPI-compliant learning record store specialists with scarce engineering talent. Signal to watch: employer consortia in Bangalore and Austin completing shared competency frameworks independent of academic accreditors.| Strategic Initiative | Industry Significance |
|---|---|
| AI Personalization Engine Acquisition | Deutsche Bank and Unilever deployments demonstrate thirty percent seat-time reduction validates premium pricing. |
| xAPI Compliance Migration | Learning record store integration enables real-time interoperability demanded by EU AI Act audit requirements. |
| Hyperscaler Cloud Partnership | AWS, Azure, and Google Cloud commitments secure 99.9% uptime SLAs essential for enterprise procurement. |
| VR-AR Simulation Module Launch | Surgical training and industrial safety applications command premium pricing through haptic feedback integration. |
| Skills-Verification API Development | Direct employer assessment integration bypasses institutional intermediaries compressing credentialing value capture. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief learning officers, IT procurement officers at Fortune 500 enterprises, platform engineers specializing in SCORM-to-xAPI migration, and regulatory affairs leads at European higher education institutions. Secondary validation drew from SEC filings of publicly traded edtech providers, EU AI Act implementation guidance documents, India's BIS standard releases, and hyperscaler capex disclosures. Bottom-up platform deployment counts across institutional segments were triangulated against top-down corporate training budget allocations.
Historical reference periods anchored the projection horizon through verified installation base data and contract renewal patterns across multi-year enterprise agreements. Segmentation dimensions modeled include service type, delivery model, end-user vertical, and technology layer with particular attention to AI integration depth and cloud infrastructure localization requirements. CAGRs were derived from trend extrapolation of vendor consolidation rates and regulatory upgrade cycle timing. Industry-specific inputs incorporated PLI scheme incentive disbursement trajectories and broadband penetration curves in Indian tier-2 cities.
The model holds under stable regulatory enforcement timelines and continued hyperscaler capacity expansion; deviation in EU AI Act audit stringency or India's data localization mandate expansion would shift vendor qualification criteria and deployment economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market