
 E-Learning Market | 2026-2036
E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
E-Learning Market Analysis
Subscription-based credentialing is restructuring how educational value gets packaged and monetized across the E-Learning landscape. Coursera leverages university partnerships to anchor degree-bearing programs at scale. Duolingo sustains freemium-to-paid conversion through gamified retention mechanics. Udemy competes on course volume and creator economics, occupying the long-tail skills market.
E-Learning comprises digitally delivered instructional content, assessment tools, and learner analytics platforms accessed through web browsers or native applications, typically requiring broadband connectivity and cloud-hosted infrastructure for real-time interaction and progress tracking. Its primary commercial purpose is to replace or supplement physical classroom delivery with scalable, measurable knowledge transfer. Learning Management Systems dominate institutional procurement budgets, while Artificial Intelligence segments capture expanding margin pools through adaptive tutoring and automated grading. Mobile Learning Solutions represent the fastest-growing delivery vector as smartphone-first learners enter formal and informal training environments across emerging economies.
FDA oversight of clinical training modules, EU GDPR constraints on learner data processing, and India's BIS standards for educational software interoperability collectively shape product architecture and market access requirements for platform providers. China's SAMR enforces content moderation protocols that foreign entrants must navigate through local hosting partnerships. Stakeholders must monitor how generative AI tooling alters content creation economics and regulatory classification before committing platform architecture decisions.
Market Dynamics
AI-driven personalization engines are compressing curriculum development cycles while fragmenting platform architecture requirements. Subscription credentialing models now command procurement priority across corporate learning budgets.
Growth Catalysts
- Corporate Subscription Migration:Enterprise training budgets are consolidating around credential-bearing platforms that bundle skills verification with continuous content access. This shift favors vendors with established university partnerships.
- EU AI Act Compliance:Automated tutoring systems deployed in European markets must document algorithmic decision pathways. Vendors investing in explainable AI architectures gain preferential procurement status from institutional buyers.
- Smartphone-First Learners:Mobile Learning Solutions capture disproportionate growth as India, Brazil, and Nigeria expand 4G infrastructure. Native app performance now determines platform selection in emerging economy tenders.
Market Restraints
- GDPR Data Processing Constraints:Learner analytics platforms face restricted cross-border data flows. European institutional contracts require local hosting infrastructure that elevates operational overhead.
- Broadband Infrastructure Gaps:Real-time video delivery depends on fiber and stable 4G coverage. Rural segments in India, Indonesia, and Nigeria remain inaccessible to synchronous learning models.
- Credential Inflation Risk:Micro-certificate proliferation dilutes employer confidence in platform-issued qualifications. Hiring managers increasingly demand third-party skills validation beyond platform credentials.
Strategic Opportunities
- German Dual Vocational Integration:Apprenticeship systems seek digital companions for hands-on training. Platforms embedding workplace simulation modules capture public procurement contracts.
- AI-Generated Content Convergence:Large language models paired with automated assessment engines reduce course production costs. Early adopters compress curriculum development from months to weeks.
- India BIS Interoperability Mandate:Educational software standards create compliant vendor lists for government tenders. Certification against BIS specifications opens state-level education department contracts.
Industry Challenges
- Instructional Designer Scarcity:Platforms struggle to hire talent capable of structuring adaptive learning pathways. Competition from technology firms elevates compensation benchmarks beyond education-sector norms.
- Legacy LMS Integration Complexity:Enterprises demand seamless data exchange with installed SAP, Oracle, and Workday systems. API standardization gaps force expensive custom development.
- FDA Clinical Module Validation:Healthcare training content requires regulatory review cycles that extend go-to-market timelines. Documentation burdens favor incumbents with established compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Learning Market |
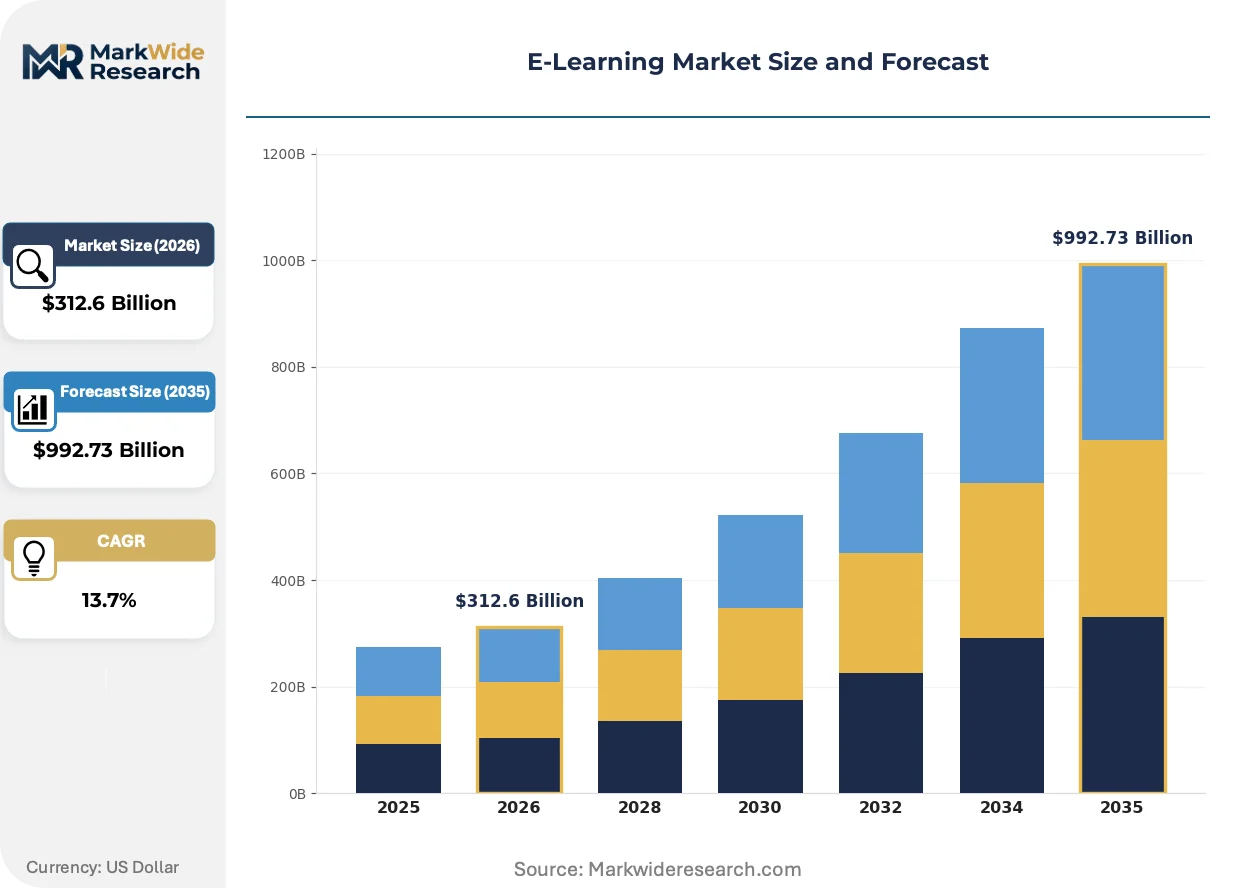
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $992.73 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Virtual Classrooms, Mobile Learning Solutions, Content Management Systems End User: Students, Corporates, Educational Institutions, Government Agencies Delivery Mode: Synchronous Learning, Asynchronous Learning, Blended Learning, Self-Paced Learning Technology: Artificial Intelligence, Augmented Reality, Cloud Computing, Video Conferencing Tools |
| Companies Covered | Duolingo, MasterClass, Coursera, Thinkific, Skillshare, LinkedIn Learning, Chegg, Mighty Networks, Udemy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Learning Market Emerging Trajectories
Generative AI tooling is restructuring content production economics while forcing regulatory reclassification debates. Platform architecture decisions made now will determine competitive position through the forecast window.
Adaptive tutoring engines is unifying diagnostic assessment with personalized content sequencing in real time. Corporate training departments are adopting these systems fastest, with financial services and technology sectors leading deployment. The technology is unifying previously separate budget lines for content licensing and learner support into single-platform procurement.
China's SAMR content moderation protocols are forcing foreign platforms to establish local hosting partnerships and data sovereignty architectures. The industrial consequence is elevated capital requirements for market entry that favor well-capitalized incumbents. Healthcare and professional certification segments are most affected, with vendors restructuring joint venture arrangements to maintain compliance.
Buyer preference is rotating from perpetual licenses toward consumption-based pricing tied to verified skill outcomes. Channel relationships with traditional education distributors are fragmenting as platforms build direct enterprise sales organizations. This shift is most visible in United States and German markets, where procurement teams now prioritize total cost of credential achievement over seat-based subscription metrics.
E-Learning Market Segmentation
E-Learning platforms compete across multiple technical and commercial dimensions. Procurement decisions hinge on integration requirements, learner demographics, and delivery infrastructure constraints.
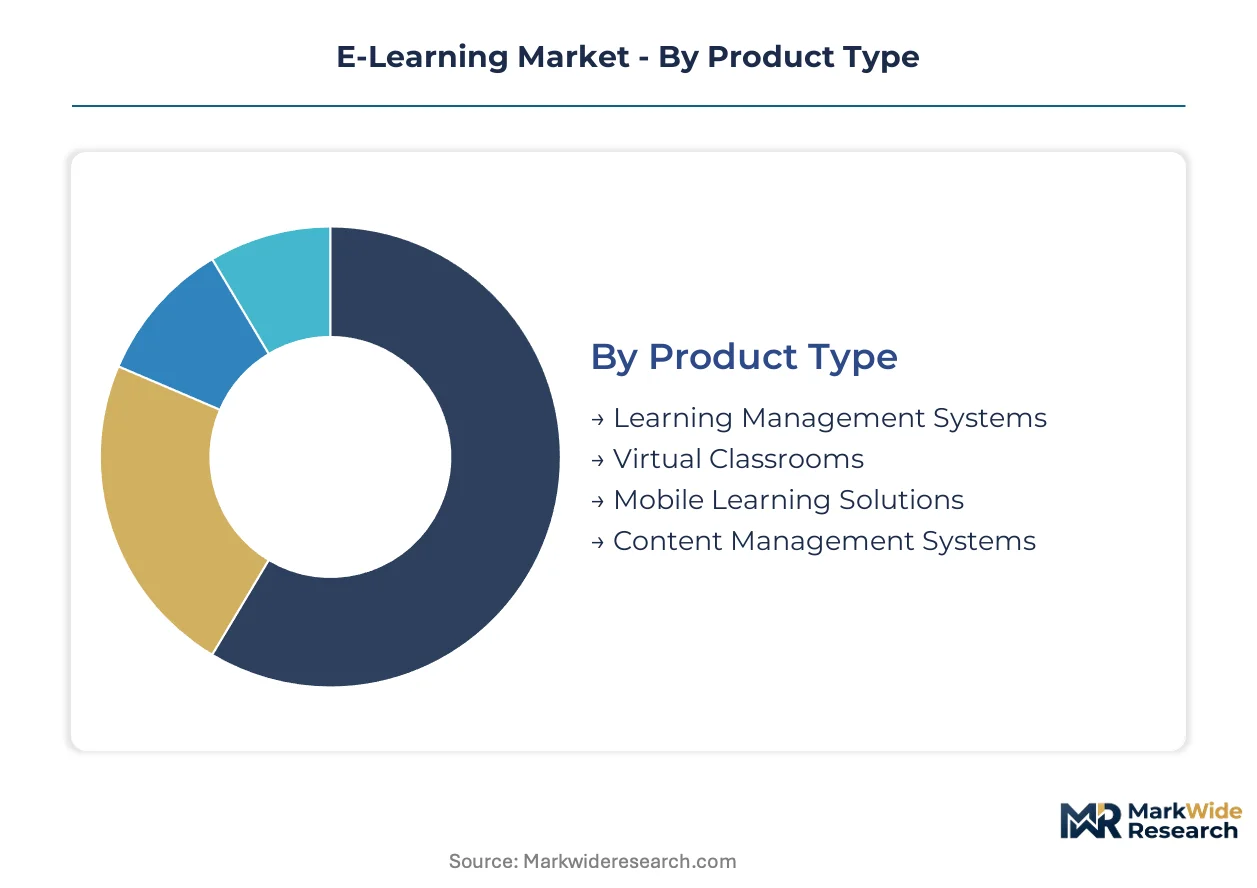
Product Type:
Upgrade cycles accelerate as institutions replace legacy installations with cloud-native architectures.
- Learning Management Systems:Centralized platforms manage course delivery, assessment, and learner analytics through browser-based interfaces. Procurement concentrates in United States and German corporate training departments seeking SAP and Oracle integration. GDPR compliance requirements favor vendors with EU data residency options.
- Virtual Classrooms:Real-time video conferencing tools replicate instructor-led sessions with breakout rooms and screen sharing. Demand clusters in Indian IT services firms onboarding distributed engineering teams. Bandwidth limitations in tier-2 cities constrain synchronous adoption.
- Mobile Learning Solutions:Native applications optimized for smartphone-first learners with offline content caching.
- Content Management Systems:Repositories for organizing, versioning, and distributing instructional assets across institutional networks.
Volume placements concentrate in Learning Management Systems; the faster expansion belongs to Mobile Learning Solutions.
End User:
Customer type determines pricing architecture and feature prioritization across platform roadmaps.
- Corporates:Enterprise buyers demand skills verification tied to HRIS systems and consumption-based pricing. United States financial services and technology sectors lead deployment of AI-driven personalization engines. Procurement teams prioritize outcome metrics over seat-based licensing.
- Students:Individual learners access degree-bearing programs and micro-credentials through subscription or per-course fees. Indian and Nigerian markets show steepest expansion trajectories as smartphone penetration rises.
- Educational Institutions:Universities and K-12 systems require FERPA compliance and legacy gradebook integration.
- Government Agencies:Public sector tenders mandate BIS certification in India and local hosting in China per SAMR protocols.
Revenue concentration sits with Corporates; the fastest share gains come from Students.
Delivery Mode:
Infrastructure maturity dictates feasible delivery models across geographic markets.
- Asynchronous Learning:Self-paced modules with recorded video and automated assessment accommodate variable schedules. German dual vocational programs embed asynchronous components alongside workplace training. Employer sponsorship drives procurement in manufacturing sectors.
- Blended Learning:Hybrid models combine online instruction with scheduled in-person sessions. Indian higher education institutions adopt blended formats to stretch physical campus capacity. UGC guidelines shape platform selection criteria.
- Synchronous Learning:Real-time scheduled sessions requiring stable broadband connectivity.
- Self-Paced Learning:Fully autonomous progression without instructor intervention or cohort structure.
Deployment scale favors Asynchronous Learning; the steepest expansion trajectory belongs to Blended Learning.
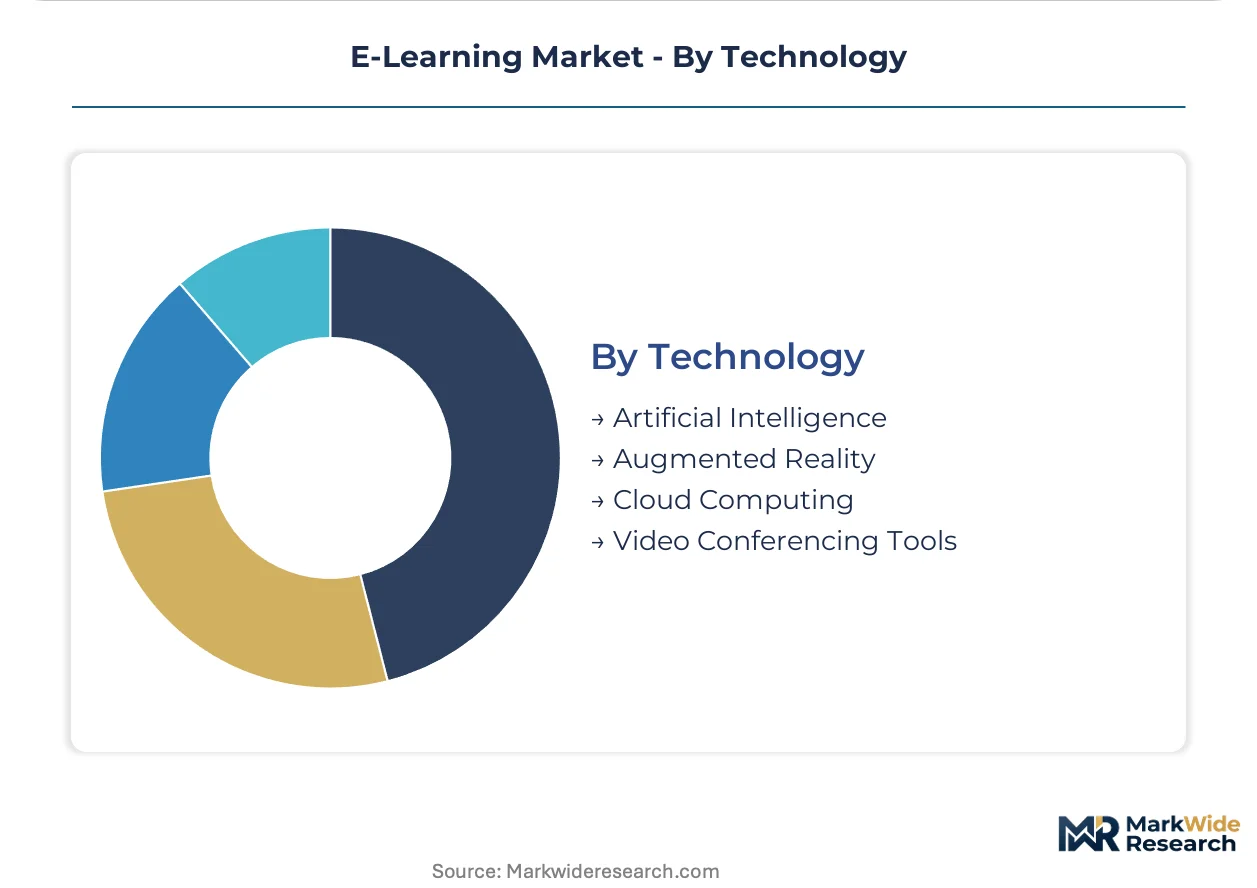
Technology:
Technology stack choices determine margin structure and regulatory exposure.
- Artificial Intelligence:Adaptive tutoring engines personalize content sequencing and automate grading. EU AI Act documentation requirements elevate vendor compliance costs. Financial services buyers in Germany and France demand explainable algorithmic decision pathways.
- Cloud Computing:Scalable infrastructure enables multi-tenant deployments and elastic capacity for enrollment spikes. Indian edtech startups leverage AWS and Azure to avoid capital-intensive data center builds. BIS interoperability standards govern government contract eligibility.
- Augmented Reality:Spatial computing overlays digital instruction onto physical environments for technical training.
- Video Conferencing Tools:Real-time communication infrastructure for instructor-led synchronous delivery.
Investment flows concentrate in Artificial Intelligence; Cloud Computing captures the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's Koramangala-Whitefield corridor hosts India's densest concentration of edtech engineering talent, with over 200 AI-driven learning startups clustered within a 15-kilometer radius. This concentration shapes procurement patterns across the broader E-Learning landscape.
United States
Enterprise training departments in New York and San Francisco prioritize consumption-based pricing tied to verified skill outcomes. FDA oversight of clinical training modules extends go-to-market timelines for healthcare-focused platforms. Austin's emerging edtech cluster attracts venture funding for credentialing infrastructure startups.
Germany
Dual vocational programs in Bavaria and North Rhine-Westphalia embed digital companions for hands-on apprenticeship training. EU AI Act documentation requirements elevate compliance costs for adaptive tutoring vendors. Berlin's SaaS corridor concentrates procurement platform development for Mittelstand manufacturers.
India
Smartphone-first learners in Maharashtra and Karnataka drive mobile-native platform adoption as 4G infrastructure penetrates tier-2 cities. BIS interoperability standards create compliant vendor lists for state education department tenders. Hyderabad's Gachibowli technology district anchors engineering centers for global LMS providers.
China
Corporate training budgets in Shanghai and Beijing consolidate around platforms with local hosting partnerships. SAMR content moderation protocols force foreign entrants into joint venture structures. Shenzhen's hardware-software convergence zone incubates AR-enabled technical training modules.
Brazil
Asynchronous learning models dominate São Paulo's corporate training market due to bandwidth variability across metropolitan zones. ANVISA-aligned healthcare training requirements shape platform content architecture decisions. Rio de Janeiro's creative economy cluster drives demand for portfolio-based credentialing systems.
E-Learning Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the E-Learning value chain. Cloud infrastructure providers and content licensing studios absorb fixed costs, while curriculum architects and personalization engine developers capture variable margins. Three archetypes dominate: university-anchored degree platforms, creator-marketplace aggregators, and enterprise-focused skill verification systems. Competitive moves concentrate on API standardization partnerships and outcome-based pricing renegotiations with corporate procurement teams.
Within the creator-economy tier, Thinkific and Skillshare occupy positions that exemplify platform-as-a-service models, enabling individual instructors to monetize specialized knowledge without institutional intermediaries. Coursera anchors the university-partnership archetype, representing the credential-bearing segment that commands premium pricing in enterprise renewal cycles. These three companies illustrate the structural divergence between open-marketplace and institution-anchored strategies.
| Leading Market Players |
|---|
| Duolingo |
| MasterClass |
| Coursera |
| Thinkific |
| Skillshare |
| LinkedIn Learning |
| Chegg |
| Mighty Networks |
| Udemy |
| Others |
Supply Flow & Price Mechanics
Degree-bearing credential tiers command subscription premiums tenfold above micro-certificate marketplaces, with this bifurcation anchoring divergent supply chain architectures across cloud infrastructure provisioning and content origination strategies.
Pricing Analysis
Margin tightening in micro-certificate tiers reflects creator-marketplace oversaturation as Udemy-style platforms compete on volume. Three-tier pricing structure across premium degree programs, standard professional certificates, and economy skills modules dominates procurement. Price differentiation hinges on university partnership prestige and AI-driven personalization depth. Corporate buyers in United States financial services show lowest price sensitivity; individual learners in India exhibit highest.
Supply Chain Analysis
India's BIS interoperability mandates and China's SAMR data sovereignty rules reshape cloud hosting partnerships for foreign platforms. Content production concentrates in United States, India, and Germany; cloud infrastructure draws from AWS, Azure, and regional providers. Single-source vulnerability sits with hyperscaler concentration. Distribution runs through direct enterprise sales and mobile app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary AI tutoring engines defines competitive positioning, with upstream control over adaptive assessment algorithms separating margin leaders from commodity aggregators.
For Market Incumbents: Acquire specialized instructional design studios to lock scarce talent capable of structuring adaptive learning pathways. Consolidate API standardization partnerships with SAP and Workday to entrench enterprise switching costs. Generative AI content tools threaten creator-economy positioning; preemptive certification against EU AI Act documentation requirements secures institutional procurement preference. For New Entrants and Emerging Players: AI-native assessment engines unburdened by legacy LMS technical debt offer wedge positioning against incumbent complexity. White-space concentrates in German dual vocational digital companions and India state education department BIS-compliant tenders. Freemium conversion mechanics modeled on Duolingo's retention architecture accelerate user acquisition without enterprise sales overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking credentialing infrastructure. Long-term viability favors platforms with locked university partnerships and explainable AI compliance infrastructure. Watch EU AI Act enforcement patterns as inflection signal for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Tutoring Engine Development | Adaptive personalization unifies content licensing and learner support budgets into single-platform procurement. |
| University Partnership Expansion | Degree-bearing programs anchor premium subscription tiers in corporate renewal cycles. |
| EU AI Act Compliance Certification | Explainable algorithmic documentation opens institutional procurement in Germany and France. |
| Mobile-First Platform Architecture | Native app performance determines tender outcomes in Indian and Nigerian 4G expansion zones. |
| API Standardization Partnership | Seamless SAP and Oracle integration reduces enterprise custom development friction. |
Methodological Framework
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineering consultations underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded edtech platforms, hyperscaler capex disclosures, and BIS certification registries. Bottom-up enrollment data triangulates against top-down corporate training budget allocations across the analysis window.
Comparable-period anchoring to historical subscription renewal rates and credential completion metrics shaped the projection horizon. Segmentation dimensions modeled include deployment model, organization size, delivery infrastructure, and regional regulatory cluster. CAGRs derive from enrollment trajectory analysis and pricing elasticity estimates. Forecast inputs incorporate 4G infrastructure buildout timelines and EU AI Act implementation phases.
Several conditions sit outside the modeled scope, including generative AI regulatory reclassification decisions and hyperscaler pricing volatility. Forecasts reflect documented assumptions about smartphone penetration curves and enterprise SaaS consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Homeschooling Market