
 Global Virtual Classroom Market | 2026-2036
Global Virtual Classroom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Classroom Market Foresight
Platform licensing revenue is tilting from perpetual on-premise contracts toward recurring cloud subscriptions. Microsoft Corporation leverages its enterprise productivity installed base to bundle classroom tools with existing Office deployments. Zoom Video Communications, Inc. competes on video fidelity and breakout-room architecture for synchronous instruction. Blackboard Inc. specializes in assessment workflows and learning analytics for accredited institutions.
A virtual classroom is a digitally mediated instructional environment that integrates real-time video streaming, interactive whiteboarding, and session recording with latency targets below 150 milliseconds for synchronous participation. Its commercial purpose centers on replicating physical classroom dynamics for geographically distributed learners. Cloud-based deployment leads in new installations because it offloads infrastructure capital to vendors and enables elastic scaling during enrollment surges. Video conferencing solutions capture the largest share of solution-type spending due to their centrality in live-lecture delivery. Corporate training represents the fastest-expanding end-user segment as enterprises replace in-person seminars with measurable digital alternatives.
The EU AI Act and GDPR impose algorithmic transparency and data-localization requirements on classroom platforms processing student biometric data. The U.S. Department of Education's FERPA enforcement and the FCC's E-Rate program shape procurement standards and broadband subsidy flows for connected learning. India's BIS cloud-security certifications and CDSCO guidelines for health-profession simulations add compliance layers for vendors entering regulated training markets. Stakeholders must weigh sovereign-data mandates against the cost of fragmented regional infrastructure stacks.
Market Dynamics
Cloud infrastructure elasticity is compressing vendor margins while expanding addressable institutional segments, forcing platform providers to rearchitect cost structures around consumption-based metering rather than fixed licensing.
Growth Catalysts
- GDPR-aligned data residency mandates:European procurement officers now require sovereign-cloud guarantees, creating upgrade cycles for compliant platform versions.
- Corporate training departments:Remote workforce upskilling programs in North American enterprises are expanding seat licenses for synchronous skill certification.
- K-12 digitization clusters:India's ed-tech corridor institutions and government skill programs are driving subscription volume through bundled hardware-platform contracts.
Market Restraints
- Biometric data processing restrictions:The EU AI Act imposes algorithmic transparency requirements that extend development timelines for emotion-recognition features.
- Bandwidth infrastructure gaps:Last-mile connectivity deficits in rural India and Southeast Asian provinces limit synchronous session quality below 150-millisecond latency thresholds.
- Substitution by asynchronous modules:Self-paced microlearning platforms from specialized vendors are capturing price-sensitive segments seeking certification without live instruction.
Strategic Opportunities
- Health-profession simulation standards:India's CDSCO guidelines for medical training simulations create a regulated entry path for vendors with compliant virtual-patient platforms.
- AI-augmented tutoring convergence:Large language model integration with real-time whiteboarding is opening premium tiers for personalized remediation in STEM curricula.
- FCC E-Rate subsidy flows:US K-12 broadband funding is expanding connected-learning procurement pools for vendors meeting competitive-bidding requirements.
Industry Challenges
- Cross-border data architecture complexity:Fragmented regional infrastructure stacks force vendors to maintain separate cloud instances for GDPR, BIS, and domestic Chinese compliance regimes.
- Legacy LMS integration friction:Higher-education IT departments face extended deployment cycles connecting modern video platforms to decades-old student-information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Classroom Market |
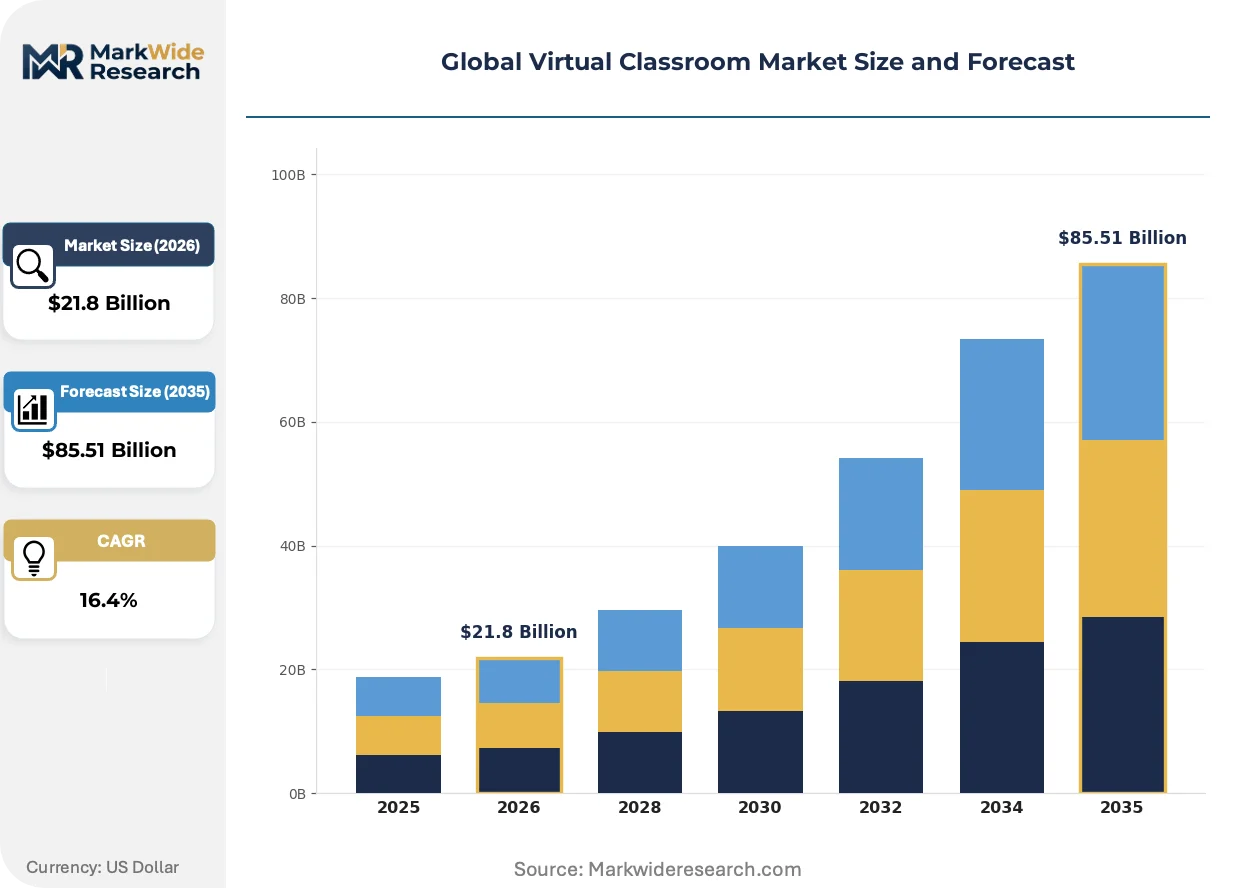
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Learning Management System, Video Conferencing, Interactive Whiteboard, Assessment Tools, Content Management End User: Higher Education, K-12 Institutions, Corporate Training, Government Organizations Application: Live Lectures, Collaborative Learning, Distance Training, Skill Development, Student Assessment |
| Companies Covered | Microsoft Corporation, Google LLC, Zoom Video Communications, Inc., Cisco Systems, Inc., Adobe Inc., IBM Corporation, Blackboard Inc., Hangzhou Hikvision Digital Technology Co., Ltd., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Classroom Market Shifts & Advancements
Artificial intelligence is rewriting the value architecture of instructional delivery, compressing the gap between standardized content and personalized learning paths while introducing new compliance burdens around algorithmic accountability.
Edge-computing nodes for video processing are rendering obsolete centralized cloud-rendering architectures that introduced latency for geographically dispersed learners. K-12 districts in bandwidth-constrained US counties are piloting local processing units. This shift is compressing infrastructure costs for synchronous platforms serving rural student populations.
The EU AI Act's risk-classification framework for educational algorithms is mandating human-in-the-loop oversight for automated assessment scoring. Vendors must now document training-data provenance and bias-audit trails. Accredited European institutions are delaying procurement decisions pending vendor compliance certification.
Outcome-verification contracts are displacing seat-based subscription models in corporate training procurement. Enterprise learning officers now demand competency-attestation guarantees before renewal. This pattern is most visible in US financial-services and healthcare verticals where regulatory training carries liability exposure.
Global Virtual Classroom Market Segmentation
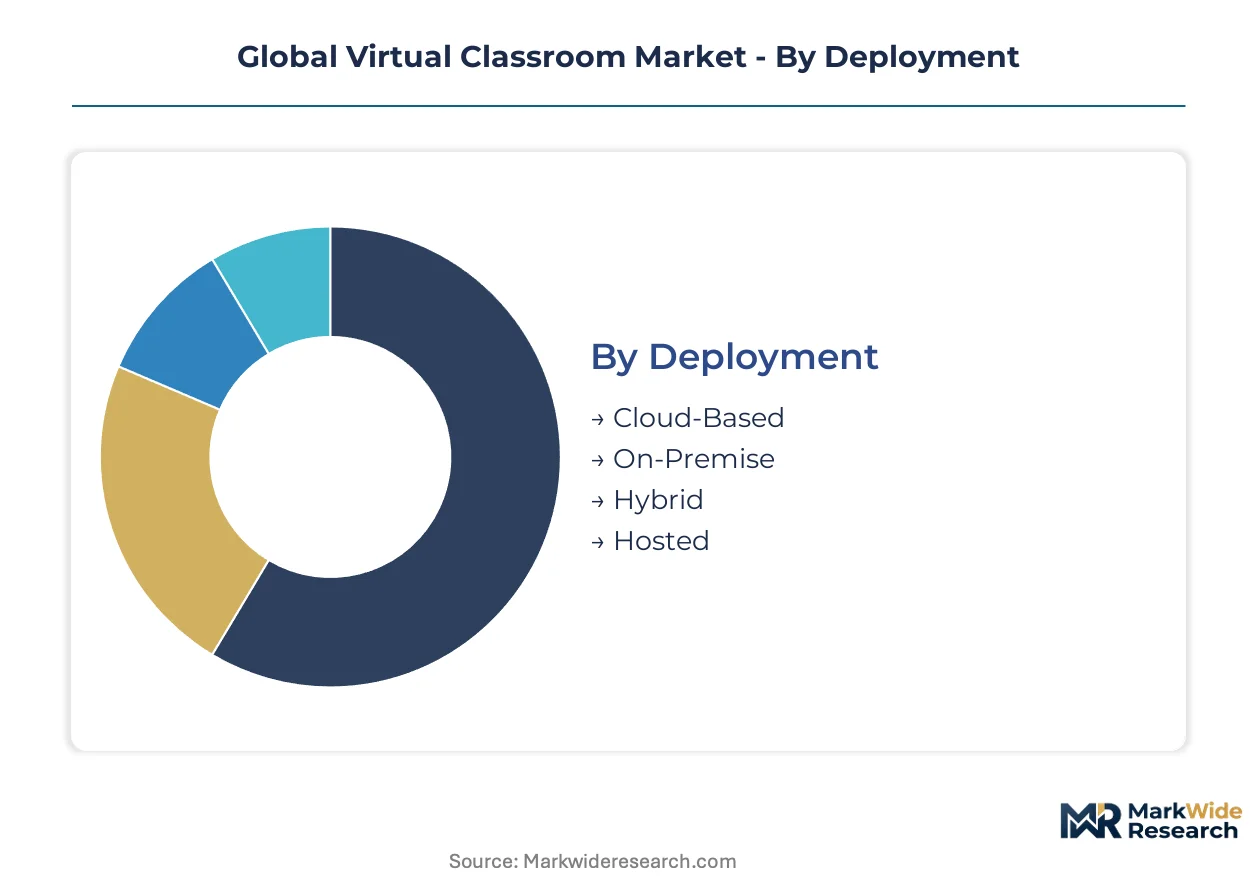
Segmentation in virtual classrooms reveals how procurement criteria diverge across infrastructure maturity, pedagogical requirements, and compliance burdens. Deployment architecture and solution bundling determine total cost of ownership, while end-user governance structures shape feature prioritization and vendor selection timelines.
Deployment:
Mature cloud architectures dominate new installations, while legacy on-premise estates persist in regulated environments with stringent data-sovereignty mandates.
- Cloud-Based:Elastic infrastructure offloads capital expenditure to vendors and enables automatic scaling during enrollment surges. North American corporate training departments favor this model for rapid workforce upskilling deployment without IT procurement cycles.
- On-Premise:Institutions with decades-old security certifications maintain physical server control for audit compliance. European universities under GDPR face extended procurement delays evaluating sovereign-cloud alternatives against retained on-premise estates.
- Hybrid:Sensitive student records reside on local servers while video processing leverages distributed cloud nodes.
- Hosted:Single-tenant managed deployments serve government skill programs with dedicated infrastructure isolation requirements.
Cloud-based retains volume leadership; hybrid holds the steepest expansion curve as regulated institutions seek phased migration paths.
Solution Type:
Cost tier stratification separates commodity video infrastructure from premium assessment and analytics modules with certified proctoring capabilities.
- Video Conferencing:Real-time streaming with sub-150-millisecond latency targets forms the functional core of synchronous instruction. Corporate training officers prioritize breakout-room architecture and recording fidelity over peripheral features.
- Assessment Tools:Automated proctoring, plagiarism detection, and competency-verification workflows carry premium pricing in accredited higher education. India's CDSCO guidelines for health-profession simulations create regulated demand for biometric-identity verification.
- Learning Management System:Gradebook integration and attendance tracking provide institutional workflow backbone.
- Interactive Whiteboard:Multi-user annotation and STEM equation rendering support collaborative problem-solving sessions.
- Content Management:Learning object repositories and version control enable curriculum standardization across distributed campuses.
Video conferencing retains volume leadership; assessment tools command the steepest expansion curve as outcome-verification contracts displace seat-based subscriptions.
End User:
Customer type determines procurement velocity, with corporate training departments moving fastest and government organizations slowest due to competitive-bidding mandates.
- Corporate Training:Measurable skill certification and compliance-attestation guarantees drive vendor selection. US financial-services and healthcare verticals demand liability-limiting documentation for regulatory training completion.
- K-12 Institutions:India's ed-tech corridor institutions bundle hardware-platform subscriptions with government skill program mandates. FCC E-Rate subsidy flows expand procurement pools for US districts meeting competitive-bidding requirements.
- Higher Education:Legacy student-information system integration extends deployment cycles for modern video platforms.
- Government Organizations:Sovereign-data mandates and public-procurement rules elongate vendor onboarding timelines.
Corporate training retains volume leadership; K-12 institutions show the steepest expansion curve through bundled hardware-platform contracts.
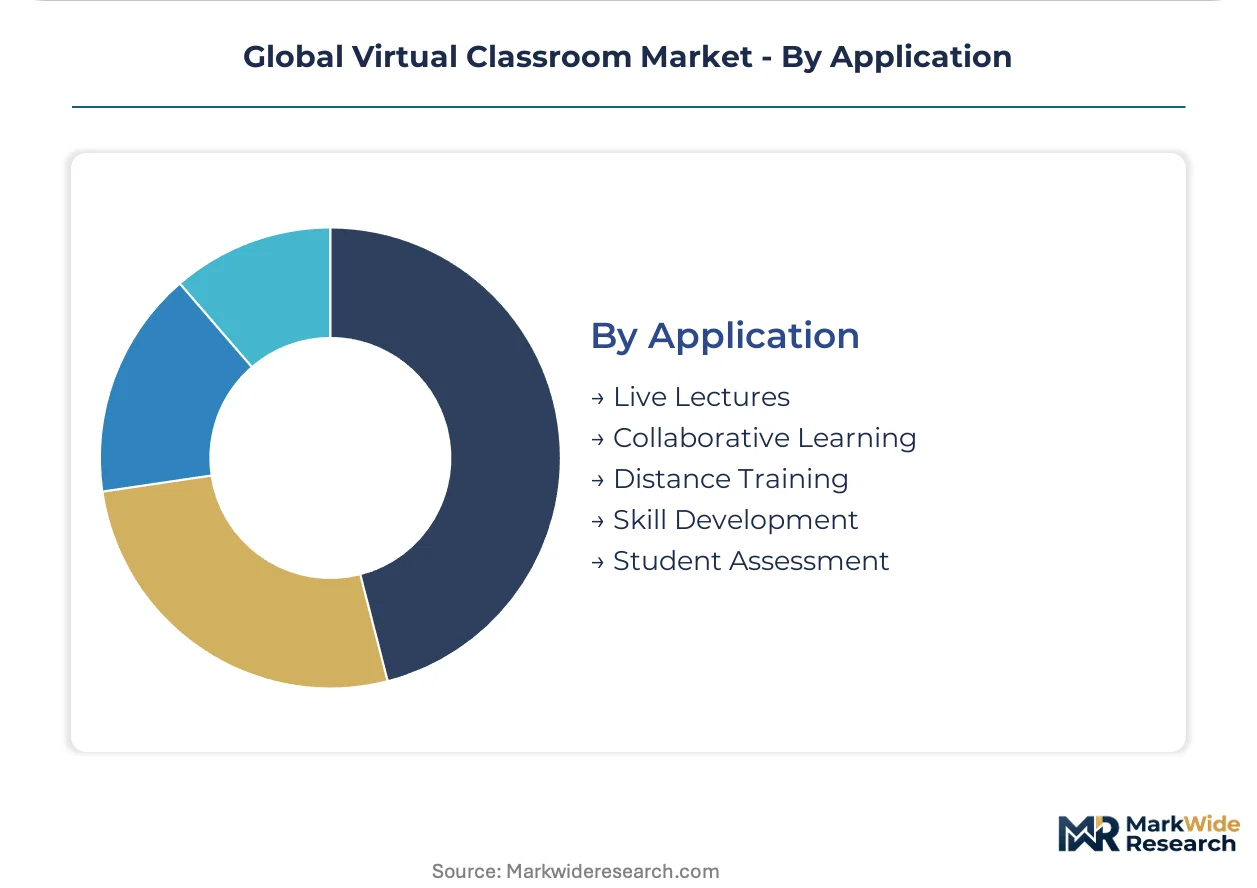
Application:
Geography shapes application prioritization, with bandwidth-constrained regions emphasizing asynchronous alternatives and connected corridors investing in synchronous fidelity.
- Live Lectures:Real-time instructor delivery with interactive Q&A replicates physical classroom dynamics. Last-mile connectivity deficits in rural India and Southeast Asian provinces limit quality below latency thresholds.
- Skill Development:Competency-based progression with employer-recognized certification drives subscription renewals. Self-paced microlearning platforms capture price-sensitive segments seeking certification without live instruction.
- Collaborative Learning:Peer interaction and group project coordination support constructivist pedagogical models.
- Distance Training:Remote workforce onboarding and compliance refreshers replace in-person seminars.
- Student Assessment:High-stakes examination proctoring with biometric identity verification serves regulated professions.
Live lectures retain volume leadership; skill development shows the steepest expansion curve as outcome-verification contracts reshape procurement economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in India and Southeast Asia drives bundled hardware-platform contracts, while US and German buyers prioritize compliance-attestation guarantees over unit cost. Elastic demand concentrates in corporate training corridors; rigid procurement governs government skill programs.
United States
Corporate training departments in financial-services and healthcare verticals demand liability-limiting documentation for regulatory training completion. The FCC's E-Rate program expands connected-learning procurement pools for K-12 districts meeting competitive-bidding requirements. Silicon Valley and Boston-Washington corridor institutions pilot edge-computing nodes for bandwidth-constrained rural counties.
Germany
European universities under GDPR face extended procurement delays evaluating sovereign-cloud alternatives against retained on-premise estates. The EU AI Act's risk-classification framework mandates human-in-the-loop oversight for automated assessment scoring. Berlin-Brandenburg and Bavarian technical universities anchor demand for compliant platform versions with algorithmic transparency documentation.
India
K-12 institutions and government skill programs in the ed-tech corridor drive subscription volume through bundled hardware-platform contracts. BIS cloud-security certifications and CDSCO guidelines for health-profession simulations add compliance layers for vendors entering regulated training markets. Karnataka's Bangalore cluster and Maharashtra's Pune corridor concentrate platform deployment for medical simulation standards.
Japan
Higher-education IT departments prioritize legacy student-information system integration with modern video platforms. METI standards influence procurement criteria for synchronous instruction quality. Tokyo-Osaka metropolitan institutions anchor demand for sub-150-millisecond latency architectures in STEM curricula delivery.
United Kingdom
Accredited institutions delay procurement decisions pending vendor compliance certification under GDPR-aligned data residency mandates. The CNIL-equivalent Information Commissioner's Office shapes algorithmic accountability requirements for classroom platforms processing student biometric data. London and Southeast England universities concentrate demand for assessment workflow platforms with learning analytics capabilities.
Global Virtual Classroom Market Competitive Landscape
Capability concentration sits with specialized assessment and analytics vendors; scale advantage sits with enterprise productivity suite providers with existing installed bases. The market structures around three tiers: cloud-native synchronous platforms, legacy learning management system incumbents, and vertical specialists in regulated training simulations. Dominant competitive moves include portfolio diversification into AI-augmented tutoring modules and strategic partnerships with sovereign-cloud providers for GDPR-compliant data residency.
Within the enterprise productivity tier, Microsoft Corporation leverages its Office deployment base to bundle classroom tools, while Zoom Video Communications, Inc. competes on video fidelity architecture. Blackboard Inc. occupies a position among assessment workflow specialists serving accredited higher-education institutions with learning analytics capabilities.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Zoom Video Communications, Inc. |
| Cisco Systems, Inc. |
| Adobe Inc. |
| IBM Corporation |
| Blackboard Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States and European Union determines where margin pools accumulate across virtual classroom value chains. Vendors with sovereign-cloud certifications capture premium pricing from GDPR-constrained European universities, while unbundled video infrastructure providers compete on metered consumption rates.
Pricing Analysis
After-sales revenue from multi-year platform support contracts and professional implementation services drives lifetime customer value beyond initial seat licenses. Three-tier pricing structure across enterprise, institutional, and education-discount levels segments buyers by procurement sophistication and compliance burden. Price differentiation rests on biometric proctoring certification grade and data residency guarantee tier. Cost compression in commodity video conferencing is intensifying because hyperscaler bundling erodes standalone vendor margins. K-12 institutions in bandwidth-constrained geographies exhibit highest price sensitivity; corporate training departments in regulated US verticals show lowest sensitivity due to liability-limiting documentation requirements.
Supply Chain Analysis
Contract manufacturing concentration for edge-computing hardware sits with Taiwanese ODMs and mainland Chinese EMS providers serving platform vendors. Software supply chains draw from Ireland and Singapore for GDPR-aligned data center operations, with secondary development hubs in India and Poland. Raw material dependencies center on semiconductor components for video encoding, optical fiber for backbone connectivity, and lithium-ion systems for portable edge units. Single-source vulnerability in sovereign-cloud infrastructure creates procurement risk for vendors serving European government skill programs. Distribution runs through direct enterprise sales teams for large corporate training contracts and value-added resellers for fragmented K-12 institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual classroom markets reward service-attach strategies because recurring cloud subscription revenue expands faster than perpetual license hardware sales. Platform providers capturing professional services and compliance certification workflows build defensible margin structures.
For Market Incumbents: Harden data residency architecture against emerging sovereign-cloud mandates in India and Southeast Asia. Invest in BIS certification pathways before CDSCO medical simulation standards harden. Acquire specialist assessment analytics vendors to fill competency-verification capability gaps threatening seat-based renewal rates.
For New Entrants and Emerging Players: Rural Indian districts with last-mile connectivity deficits offer white-space entry through edge-computing hardware bundling. Target health-profession simulation segments where CDSCO guidelines create regulated demand barriers for unqualified competitors. Pursue FCC E-Rate competitive-bidding qualification as primary go-to-market credential for US K-12 procurement pools.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corporate training platforms lacking AI-augmented tutoring integration. Five-to-ten year viability favors vendors with outcome-verification contract structures displacing seat-based subscriptions. Monitor EU AI Act compliance certification timelines as inflection signal for European institutional procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Partnership | GDPR-aligned data residency guarantees unlock European university procurement cycles. |
| AI-Augmented Tutoring Integration | Large language model personalization commands premium pricing in STEM remediation segments. |
| Edge-Computing Hardware Bundling | Local video processing units address bandwidth constraints in rural Indian and Southeast Asian provinces. |
| Assessment Workflow Acquisition | Competency-verification capabilities secure outcome-based corporate training contracts. |
| Regulatory Certification Investment | BIS and CDSCO compliance creates regulated entry barriers for health-profession simulation markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, government procurement databases, and regulatory filing repositories. Primary interviews engaged platform engineering directors, corporate learning officers at financial services and healthcare enterprises, K-12 technology coordinators, and higher-education IT procurement managers. Secondary validation drew from FCC E-Rate program disclosures, EU AI Act implementation guidance, BIS cloud-security certification registers, and CDSCO medical device training standards. Bottom-up subscription volume estimates triangulate against top-down addressable institutional spending assessments.
Forecast inputs include deployment model migration curves, sovereign-cloud infrastructure buildout timelines, and corporate training digitization rates across regulated verticals. Segmentation dimensions span cloud versus on-premise architecture, solution type tier, end-user governance structure, and regional compliance framework cluster. CAGRs derive from enrollment elasticity models and seat-license pricing trajectory analysis. Industry-specific inputs incorporate bandwidth infrastructure deployment schedules and algorithmic accountability regulatory phase-in patterns.
Practitioners should monitor sovereign-cloud mandate expansion, AI Act risk-classification enforcement, and outcome-verification contract adoption for early signals of forecast revision. Quarterly review of vendor compliance certification timelines, E-Rate competitive-bidding award flows, and edge-computing hardware shipment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
Remote Learning Technology Spending Market