
 Homeschooling Market | 2026-2036
Homeschooling Market Size, Share, and Industry Trends Forecast 2026-2036
Homeschooling Market Insights
Accredited curriculum tiering is rotating toward university-recognized and NCAA-approved pathways as families prioritize transcript portability and college admissions readiness. Khan Academy leverages its nonprofit scale to deliver zero-cost core instruction across mathematics and sciences, sustaining access for price-sensitive households. IXL Learning competes through granular skills-based analytics that let parents track mastery in real time. Outschool differentiates by connecting learners with live small-group classes spanning niche subjects and professional enrichment.
Homeschooling denotes parent-directed education conducted outside traditional institutional settings, typically involving customized curriculum selection, flexible scheduling, and multi-modal delivery through printed texts, software, or live virtual instruction. Educational software segments now embed machine-learning algorithms that auto-adjust problem difficulty based on learner response patterns, compressing remediation cycles. Online Courses represent the fastest-expanding delivery category as asynchronous formats reduce scheduling friction for working parents, while Curriculum Resources anchored in print retain durable share among families limiting screen exposure for primary-age learners. Hybrid Learning configurations that blend digital platforms with in-person co-op instruction capture margin pools where families pay premiums for socialization and specialized tutoring.
In the United States, state departments of education enforce varying notification, assessment, and subject-requirement standards that shape curriculum provider compliance burdens and product localization needs. The Department of Education's Office for Non-Public Education coordinates federal data collection while leaving operational authority to state legislatures, creating a patchwork that vendors must navigate. Families and platform developers should monitor state-level voucher and education-savings-account legislation, as these funding mechanisms determine whether homeschool expenditures qualify for public subsidy and directly influence addressable household budgets.
Market Dynamics
AI-powered adaptive learning platforms are fragmenting traditional curriculum hierarchies by compressing the feedback loop between assessment and remediation, forcing established publishers to rebuild around real-time competency tracking rather than fixed grade-level progressions.
Growth Catalysts
- Education Savings Account expansion:US state legislatures in Florida, Arizona, and Utah have enacted universal ESA eligibility, converting per-pupil funding into parent-controlled spending vehicles that cover homeschool curriculum and tutoring services.
- Neurodiverse learner accommodation:Parents of children with autism spectrum and ADHD diagnoses are migrating from institutional special education to customized home environments where pacing and sensory conditions are individually controlled.
- Asynchronous platform maturation:Machine-learning algorithms now auto-calibrate problem difficulty based on response latency and error patterns, collapsing the remediation cycle from weeks to single sessions.
Market Restraints
- State compliance fragmentation:The US Department of Education's delegation of operational authority to fifty state legislatures forces curriculum providers to maintain fifty distinct notification, assessment, and subject-requirement compliance matrices.
- Screen-time resistance among primary-age households:Families with children under age eight demonstrate durable preference for printed texts and manipulatives, capping the addressable base for fully digital solutions.
- Credential portability uncertainty:NCAA approval and university transcript recognition remain uneven across state boundaries, creating enrollment friction for college-bound homeschool graduates.
Strategic Opportunities
- Hybrid learning co-op networks:Micro-schools and parent cooperatives in Texas, North Carolina, and Tennessee are blending platform-based core instruction with in-person specialized tutoring, capturing premium pricing for socialization and lab science access.
- Career and technical education pathways:State vocational certification alignment for homeschool curricula opens addressable demand from families seeking alternatives to four-year college tracks.
- Dual-enrollment bridge programs:Community college partnerships that award concurrent credit for advanced homeschool coursework reduce the effective cost of postsecondary education and strengthen curriculum stickiness.
Industry Challenges
- Instructional design talent scarcity:Curriculum developers with combined expertise in learning science, subject-matter depth, and platform UX command compensation premiums that compress margin structures at mid-tier providers.
- Assessment standardization delays:The absence of federally mandated homeschool achievement metrics forces providers to self-certify alignment with multiple state testing regimes, inflating quality assurance overhead.
- Platform integration complexity:Legacy student information systems in state education agencies lack API compatibility with third-party homeschool analytics tools, requiring costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeschooling Market |
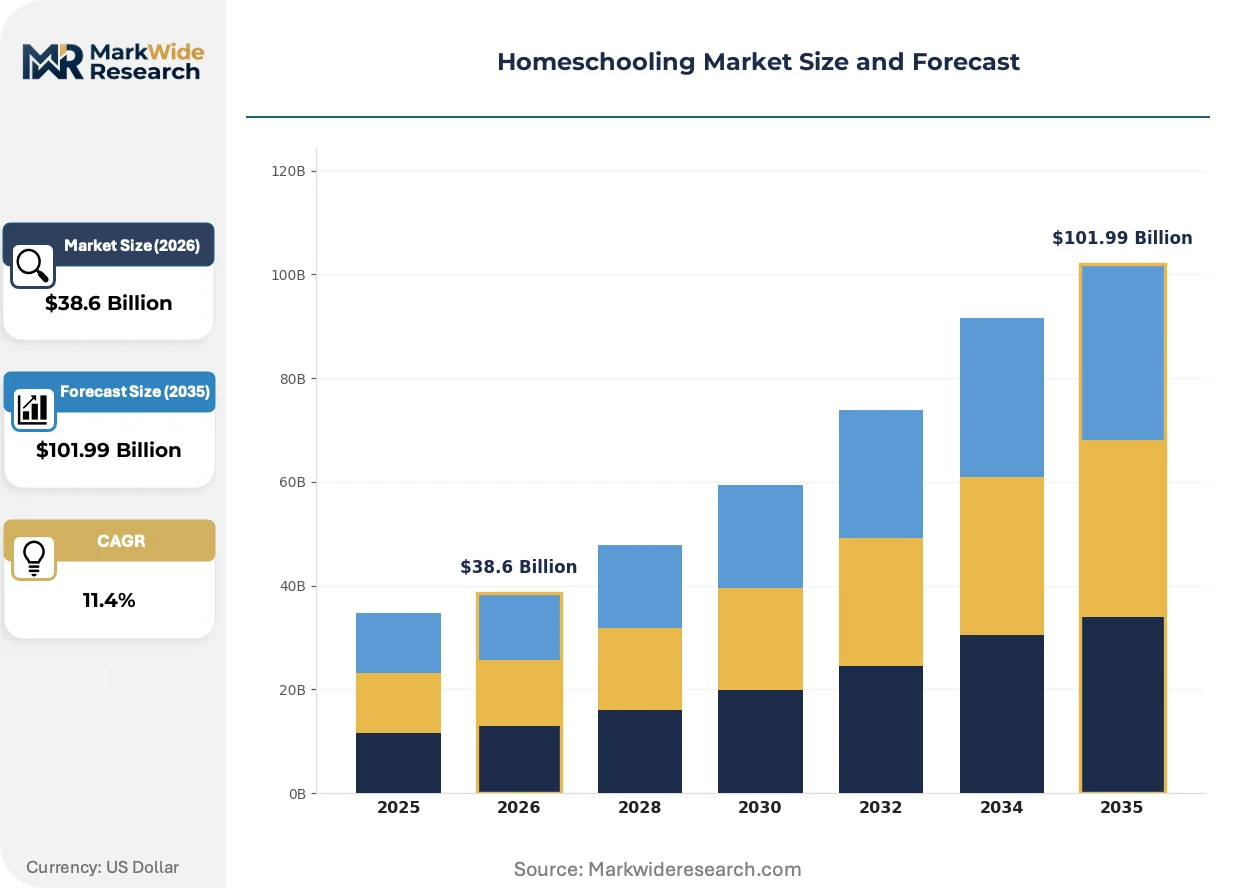
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curriculum Resources, Educational Software, Instructional Materials, Online Courses End User: Parents, Students, Educators, Tutors Delivery Mode: In-Person Classes, Digital Platforms, Hybrid Learning, Print Materials Age Group: Preschool, Primary, Secondary, High School |
| Companies Covered | Miacademy, IXL Learning, Brighterly, Time4Learning, Khan Academy, Acellus Academy, Bridgeway Academy, Outschool, Power Homeschool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeschooling Market Trends and Innovations
Adaptive assessment engines are compressing the traditional curriculum development cycle from annual revisions to continuous content calibration, while regulatory experimentation at the state level creates divergent compliance environments that favor modular, jurisdiction-agnostic platform architectures.
Generative AI tutoring assistants are fragmenting the role of human instructors by providing on-demand explanation, Socratic questioning, and error analysis across mathematics and written composition. Families in high-cost metropolitan areas adopt these tools fastest, substituting platform subscriptions for private tutoring hours. The structural consequence is a bifurcation between premium live instruction and algorithm-supported self-paced learning, with mid-market human tutoring services losing share to hybrid human-AI models.
State-level voucher and tax-credit scholarship programs are reshaping procurement patterns by converting homeschool expenditures from after-tax consumption to pre-tax or publicly subsidized transactions. Florida's universal ESA and Arizona's Empowerment Scholarship Account program demonstrate the industrial consequence: curriculum providers must now integrate with state payment portals and eligibility verification systems. The segment most affected is comprehensive curriculum suites, which are reconfiguring billing systems to accept direct state disbursement rather than parent reimbursement.
Buyer concentration is intensifying among households with annual incomes exceeding $150,000, who combine platform subscriptions with live enrichment classes and specialized tutoring. This segment is displacing the traditional price-sensitive homeschool demographic that relied on library resources and free open-source materials. The geographic concentration is most visible in suburban districts surrounding Austin, Nashville, and Raleigh-Durham, where dual-income professional families treat homeschooling as a customizable alternative to private school tuition.
Homeschooling Market Segmentation
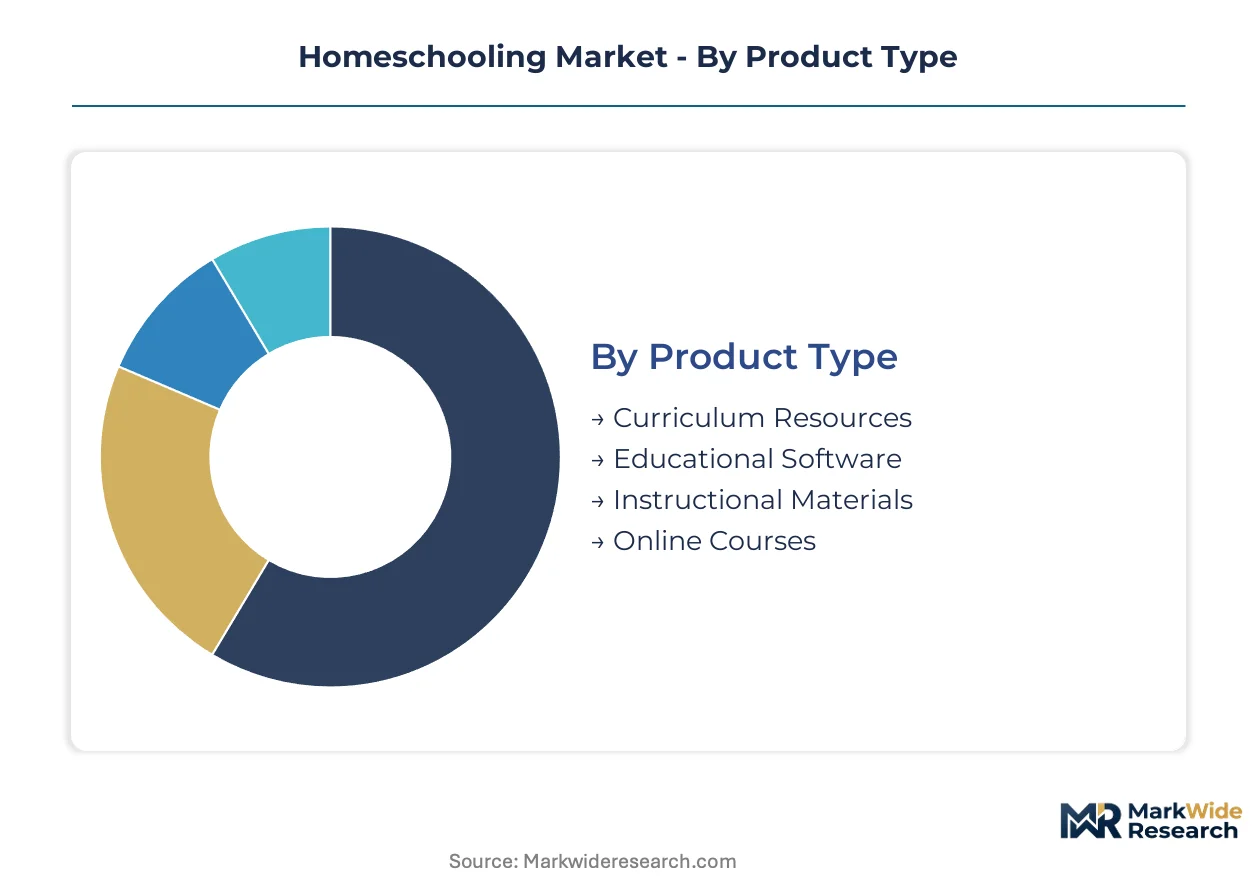
Segmentation in homeschooling reveals how substitution pressures reshape procurement hierarchies. Families constantly trade off between free open-source resources and paid comprehensive platforms, between human tutors and AI-assisted instruction, between print permanence and digital adaptability.
Product Type:
Curriculum Resources face the sharpest substitution threat from free alternatives, while Educational Software builds defensive moats through personalization algorithms that generic content cannot replicate.
- Curriculum Resources:Comprehensive subject packages spanning mathematics, language arts, and sciences with standardized scope-and-sequence frameworks. Demand concentrates among first-year homeschooling families in Texas and Florida seeking state-alignment assurance, though Khan Academy's zero-cost core instruction erodes price-paid volumes at the entry tier.
- Educational Software:Machine-learning platforms that auto-adjust problem difficulty based on response latency and error patterns. IXL Learning's granular skills-based analytics attract high-income households in Austin and Raleigh-Durham suburbs, where real-time mastery tracking justifies subscription premiums over static workbooks.
- Instructional Materials:Manipulatives, lab kits, and hands-on learning tools for STEM and art instruction.
- Online Courses:Asynchronous and live virtual classes spanning core academics and enrichment subjects.
Curriculum Resources anchors the volume base while Educational Software gains share at the steepest rate.
End User:
Cost tiering separates the market into parent-directed procurement, student self-service adoption, and institutional purchasing through cooperatives.
- Parents:Primary decision-makers controlling household education budgets and platform selection. Dual-income professional families exceeding $150,000 annual income in Nashville suburbs combine multiple paid subscriptions with specialized tutoring, displacing the traditional price-sensitive demographic that relied on library resources.
- Students:Direct users whose engagement patterns determine retention and renewal outcomes. Neurodiverse learners with autism spectrum diagnoses drive demand for self-paced interfaces in customized home environments where sensory conditions are individually controlled.
- Educators:Certified teachers providing supplemental instruction or co-op leadership.
- Tutors:Private instructors delivering specialized subject expertise or remediation support.
Parents dominate absolute spending while Students influence switching behavior most directly.
Delivery Mode:
Application context determines modality selection, with screen-time resistance among primary-age households creating durable print demand despite digital maturation.
- In-Person Classes:Co-operative instruction and micro-school gatherings for socialization and lab science access. Hybrid learning co-op networks in Texas, North Carolina, and Tennessee capture premium pricing for specialized tutoring that pure platforms cannot deliver.
- Digital Platforms:Fully online instruction through adaptive learning systems and virtual classrooms. Generative AI tutoring assistants fragment the human instructor role by providing on-demand explanation across mathematics and written composition in high-cost metropolitan areas.
- Hybrid Learning:Blended configurations combining platform-based core with in-person enrichment.
- Print Materials:Physical textbooks and workbooks preferred for primary-age screen-time limitation.
Digital Platforms command the largest addressable expansion while Hybrid Learning extracts the highest per-student revenue.
Age Group:
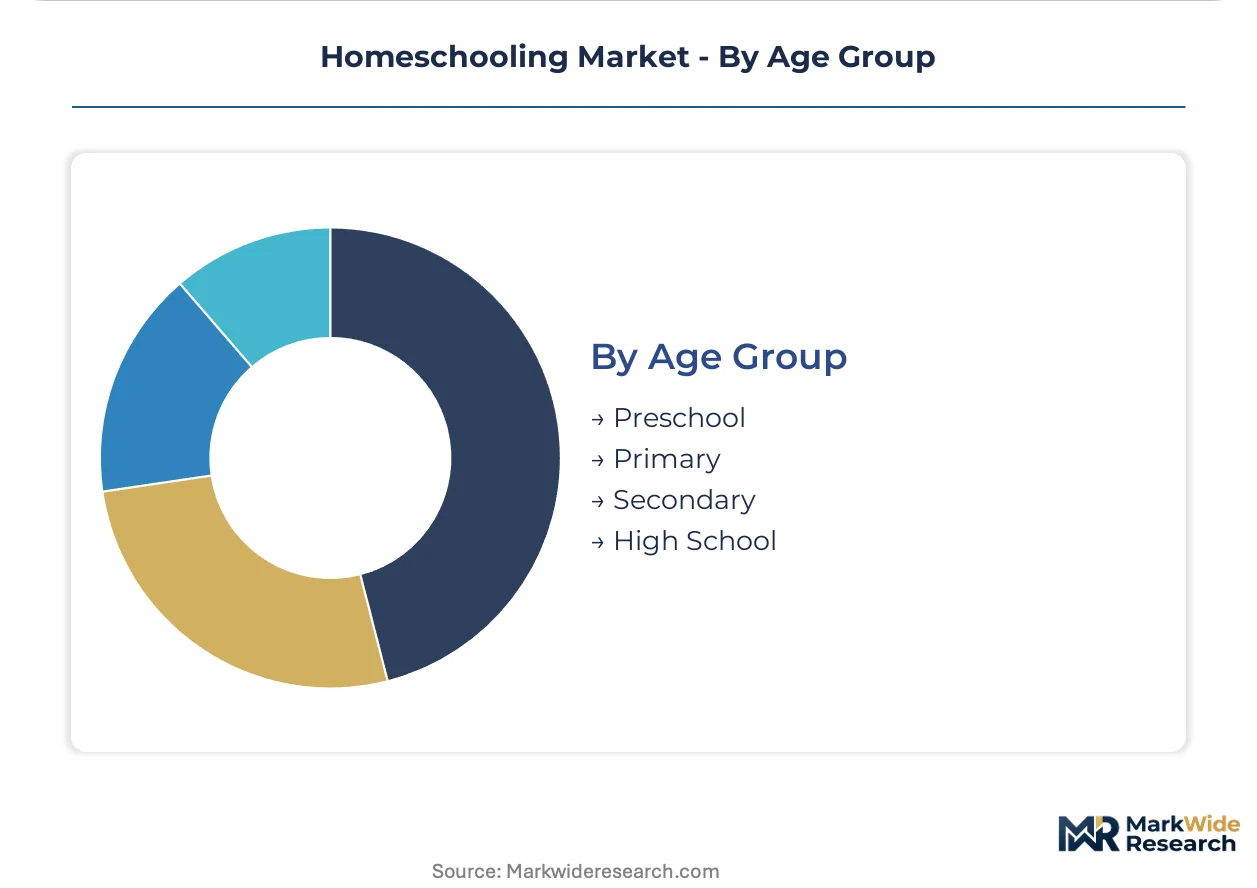
Maturity gradients separate established homeschooling traditions at secondary levels from emerging experimentation in early childhood.
- Preschool:Early childhood education focused on foundational literacy and numeracy through play-based methods. Families in suburban Raleigh-Durham districts treat this segment as a customizable alternative to private pre-K tuition, driving demand for Montessori-aligned and nature-based curricula.
- Primary:Elementary instruction spanning grades K-5 with emphasis on reading fluency and arithmetic. NCAA approval and university transcript recognition concerns remain distant, allowing greater curriculum flexibility before credential portability pressures intensify.
- Secondary:Middle school grades 6-8 bridging foundational skills and advanced coursework.
- High School:Grades 9-12 with dual-enrollment and college admissions readiness priorities.
High School generates the highest per-student expenditure while Primary shows the most durable print preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Curriculum provider headquarters cluster in the United States, where state-level funding flexibility and established homeschool networks concentrate platform development. State education agencies enforce divergent compliance matrices that shape product localization and market entry sequencing.
United States
Florida, Arizona, and Utah have enacted universal Education Savings Account eligibility, converting per-pupil funding into parent-controlled spending vehicles. The Department of Education's Office for Non-Public Education coordinates federal data collection while leaving operational authority to state legislatures. Austin, Nashville, and Raleigh-Durham suburbs anchor demand concentration among dual-income professional families combining platform subscriptions with specialized tutoring.
United Kingdom
Elective home education registrations have risen sharply in England, particularly among families seeking alternatives to standardized testing regimes. The Department for Education maintains a light-touch regulatory framework with no mandatory curriculum requirements, though local authorities conduct annual welfare checks. London and Southeast England concentrate platform adoption where household incomes support premium subscription stacking alongside private enrichment services.
Canada
Provincial education ministries exercise varying oversight intensity, with Alberta and British Columbia offering the most structured homeschooling frameworks including diploma pathway options. Provincial funding allocations differ dramatically, with some jurisdictions providing per-student grants while others offer no financial support. Ontario and Quebec present the largest addressable populations, though regulatory fragmentation complicates national curriculum standardization.
Australia
Home education regulation falls to state and territory governments, creating six distinct compliance environments ranging from notification-only to detailed curriculum approval requirements. The Australian Curriculum, Assessment and Reporting Authority provides national standards that families may voluntarily adopt. New South Wales and Victoria concentrate platform demand in metropolitan Sydney and Melbourne corridors where alternative education networks have matured.
Germany
Constitutional guarantees of compulsory school attendance severely restrict homeschooling except in exceptional circumstances, limiting formal market development. Families pursuing home education typically relocate to neighboring jurisdictions or operate in legal gray zones. Bavaria and Baden-Württemberg maintain the strictest enforcement, while Berlin presents marginally more flexibility for diplomatic families and transient professionals.
Homeschooling Market Competitive Landscape
Concentration sits with nonprofit and venture-backed platform developers rather than legacy educational publishers. The competitive terrain splits between zero-cost core instruction providers and premium subscription services with granular analytics capabilities. Two strategic archetypes dominate: adaptive learning platforms with machine-learning personalization engines, and live instruction marketplaces connecting learners with specialized tutors. Competitive moves center on state payment portal integration for ESA disbursement acceptance and dual-enrollment partnerships with community colleges.
Within the adaptive learning tier, IXL Learning and Khan Academy exemplify divergent monetization approaches—subscription-based granular analytics versus nonprofit scale delivering zero-cost core instruction. Outschool occupies a position on the live instruction vector, connecting learners with small-group classes spanning niche subjects. These three entities represent the structural fragmentation between algorithm-driven self-paced platforms and human-delivered enrichment services.
| Leading Market Players |
|---|
| Miacademy |
| IXL Learning |
| Brighterly |
| Time4Learning |
| Khan Academy |
| Acellus Academy |
| Bridgeway Academy |
| Outschool |
| Power Homeschool |
| Others |
Pricing and Supply Chain Analysis
Generative AI tutoring assistants substituting for human instructors simultaneously redraw supply geography toward cloud infrastructure hubs and compress pricing economics for mid-market tutoring services. This substitution dynamic concentrates value capture in platform engineering talent pools while eroding hourly-rate premiums that previously sustained regional tutoring networks.
Pricing Analysis
State Education Savings Account eligibility criteria dictate the pricing tier structure across curriculum suites, with Florida's universal ESA and Arizona's Empowerment Scholarship Account programs forcing providers to reconfigure billing systems for direct state disbursement acceptance. Three-tier pricing structure across premium analytics subscriptions, standard core curriculum packages, and economy open-source alternatives separates IXL Learning's granular mastery tracking from Khan Academy's zero-cost instruction. Cost compression in the mid-market tutoring tier is intensifying because generative AI tools in high-cost metropolitan areas substitute platform subscriptions for private instruction hours. Price-sensitive households relying on library resources and free materials face displacement by dual-income professional families exceeding $150,000 annual income who stack multiple paid subscriptions.
Supply Chain Analysis
Cloud infrastructure concentration in Amazon Web Services, Microsoft Azure, and Google Cloud Platform underwrites platform delivery economics for adaptive learning engines. Machine-learning algorithm development draws from specialized instructional design talent pools in Austin, Raleigh-Durham, and Nashville suburbs where combined expertise in learning science and platform UX commands compensation premiums. Single-source vulnerability in AI model training data licensing creates exposure for providers dependent on narrow content partnerships. Distribution runs through direct-to-parent digital channels with increasing integration into state payment portals for ESA disbursement processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homeschooling platforms function as service-attach businesses where ongoing subscription renewals and live enrichment class commissions expand faster than one-time curriculum license sales. The recurring revenue layer from specialized tutoring marketplaces and dual-enrollment bridge programs now outpaces hardware-like print kit shipments.
For Market Incumbents: Shield market position by deepening backward integration into proprietary AI tutoring engines that reduce dependence on third-party generative models, and by securing NCAA approval and university transcript recognition credentials that create switching costs for college-bound families. The threat of free open-source alternatives eroding entry-tier volumes demands certification investment as a defensive moat. For New Entrants and Emerging Players: Live small-group instruction for neurodiverse learners represents a service-layer gap where incumbents under-serve families seeking sensory-controlled environments with individually paced pacing. Texas hybrid learning co-op networks and Tennessee micro-school partnerships offer the most penetrable geography for platform-enabled specialized tutoring. A go-to-market angle anchored in state ESA payment portal integration captures parent-controlled funding flows directly. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors adaptive learning engines with demonstrated retention metrics over content library aggregators. Long-term viability over the next decade hinges on AI personalization depth and dual-enrollment partnership density. The acquisition target archetype combines machine-learning competency tracking with established community college credit pathways. Watch state voucher program expansion velocity as the inflection indicator for addressable household budget expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Tutoring Engine Development | Proprietary generative models reduce reliance on third-party APIs and capture margin from human tutoring substitution. |
| State ESA Portal Integration | Direct disbursement acceptance converts parent reimbursement friction into seamless procurement for curriculum suites. |
| NCAA Approval Pathway Investment | Transcript portability assurance locks in college-bound homeschool families through high school graduation. |
| Dual-Enrollment Partnership Expansion | Community college credit alignment reduces effective postsecondary costs and strengthens curriculum renewal stickiness. |
| Hybrid Co-Op Network Formation | Blended platform-core with in-person lab access captures premium pricing unavailable to pure digital competitors. |
Research Methodology
A spread of perspectives from curriculum platform executives, state education agency administrators, homeschool cooperative leaders, and special education parent advocates converged on the working assumptions underlying demand projections. Primary interviews with these stakeholders combined with secondary validation against state legislative databases, Department of Education Office for Non-Public Education filings, and ESA program enrollment records. Bottom-up triangulation across household expenditure patterns and top-down reconciliation with platform subscription revenue disclosures anchored the analysis.
Segmentation dimensions modeled include product type, delivery mode, age group, and state regulatory framework intensity across the projection horizon. CAGRs were derived from trend extrapolation adjusted for policy intervention scenarios. Forecast inputs incorporated Education Savings Account expansion trajectories and machine-learning platform adoption curves among high-income suburban districts.
Forecasts assume regulatory continuity in Florida, Arizona, and Utah ESA regimes; material policy shifts restricting parent-controlled funding would require re-modeling addressable household budgets. Practitioners should keep alternative scenarios live as state-level voucher legislation and NCAA transcript standardization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Africa E-Learning Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
Global Digital Education Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Digital Course Recorder Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market