
 Global Music Copyright Market | 2026-2036
Global Music Copyright Market Size, Share, and Industry Trends Forecast 2026-2036
Global Music Copyright Market Foresight
ISO 9001 certification for rights-management platforms is bifurcating the competitive landscape between established publishers and technology-native entrants. Universal Music Publishing Group leverages its catalog depth across film and television synchronization. Sony Music Publishing anchors its position through direct licensing infrastructure in Asia. Warner Chappell Music differentiates via proprietary royalty-tracking systems that reduce clearance friction.
Music copyright encompasses the legal protection of musical compositions and sound recordings, granting creators exclusive rights to reproduce, distribute, perform, and license their works for fixed durations typically spanning the life of the author plus seventy years. The primary commercial purpose centers on monetizing creative output through structured licensing agreements that enable third-party use while preserving creator control. Mechanical and synchronization license types command the largest revenue pools, with synchronization expanding fastest as video content production accelerates across streaming platforms. Performance rights represent the most mature segment, anchored by long-established collecting societies with entrenched broadcaster relationships.
The U.S. Copyright Office, EU collective rights management directives under the Digital Services Act, and South Korea's Ministry of Culture, Sports and Tourism shape market access through mechanical royalty rate-setting, platform liability frameworks, and K-content export incentives respectively. These regulatory architectures determine which entities can administer rights at scale and which must partner with local societies. Stakeholders must monitor emerging AI-generated music classifications and corresponding rights attribution standards as generative tools proliferate across production workflows.
Market Dynamics
Platform liability frameworks under the EU Digital Services Act are forcing collective rights management societies to restructure licensing hierarchies, compressing clearance timelines from months to weeks while fragmenting royalty administration across competing technology stacks.
Growth Catalysts
- Streaming Volume Expansion:Video-on-demand platforms in South Korea and the United States are multiplying synchronization license volumes as original content production accelerates beyond traditional broadcaster procurement cycles.
- EU Copyright Directive Reforms:Article 17 implementation across member states mandates direct licensing obligations for user-upload platforms, creating new revenue channels for rights holders previously excluded from UGC monetization.
- Blockchain Royalty Tracking:Distributed ledger verification is reducing attribution disputes in mechanical rights administration, particularly for catalog assets with complex ownership chains spanning multiple territories.
Market Restraints
- Collecting Society Fragmentation:Territorial exclusivity requirements in Germany and France force licensors to maintain parallel administrative relationships, inflating compliance overhead without proportional revenue expansion.
- AI-Generated Content Ambiguity:Unclear human authorship thresholds under current Berne Convention interpretations create enforcement gaps against synthetic composition tools trained on copyrighted works.
- Legacy System Integration Costs:Publishers with decades-old rights databases face prohibitive data migration expenses to achieve ISO 9001 certification standards for automated licensing platforms.
Strategic Opportunities
- Indian Market Liberalization:Copyright Board rate-setting reforms and IP appellate tribunal streamlining are reducing clearance friction for Western catalog penetration into Bollywood synchronization markets.
- Gaming Interactive Audio:Adaptive music systems in triple-A game development are creating new performance rights categories requiring specialized micro-licensing infrastructure absent from standard PRO agreements.
- Brazilian Regulatory Harmonization:ECAD restructuring under ANCINE oversight is consolidating previously fragmented municipal collecting societies, enabling scalable blanket licensing for streaming platform market entry.
Industry Challenges
- Metadata Standardization Deficits:Inconsistent ISWC and ISRC application across territorial registries forces manual reconciliation of ownership claims, delaying payment distributions and eroding creator trust.
- Cross-Border Enforcement Gaps:Jurisdictional limitations in China's NMPA administrative procedures leave foreign rights holders without effective remedies against unlicensed cover versions distributed through short-video platforms.
Report Scope
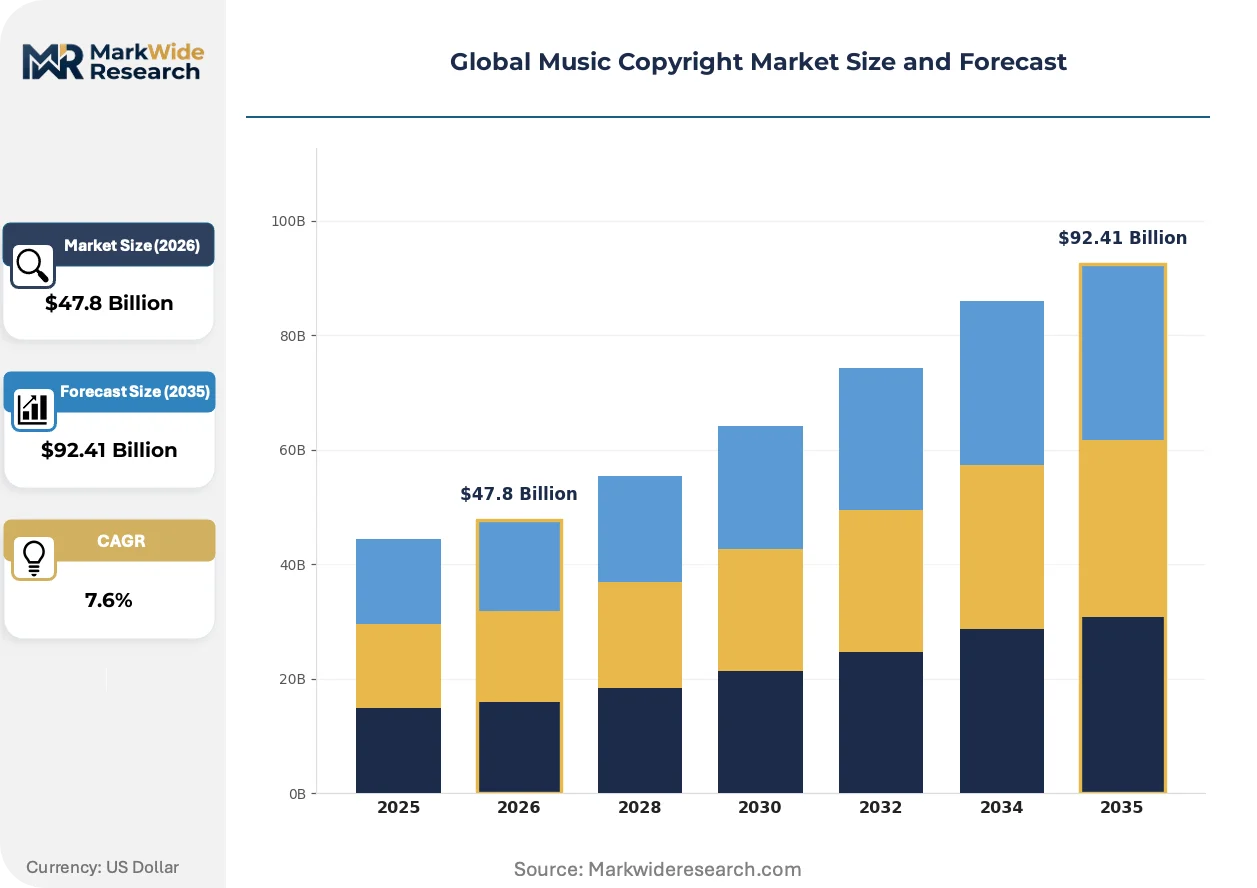
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Music Copyright Market |
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $92.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | License Type: Mechanical, Synchronization, Performance, Print, Digital End User: Broadcasting Stations, Streaming Services, Music Publishers, Advertising Agencies, Event Organizers Distribution Channel: Digital Platforms, Physical Retailers, Direct Licensing, Collecting Societies, Online Marketplaces Application: Film and TV, Video Games, Live Performances, Commercials, Podcasts |
| Companies Covered | Universal Music Publishing Group, Sony Music Publishing, Warner Chappell Music, BMG Rights Management, Kobalt Music Group, Audio Network Limited, Concord, Downtown Music Holdings, Global Music Rights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Music Copyright Market Shifts & Advancements
Rights administration infrastructure is fragmenting between centralized collecting societies and direct licensing technology stacks, creating parallel ecosystems with incompatible data standards and diverging creator remuneration models.
Automated rights-matching algorithms are miniaturizing the clearance workflow for user-generated content platforms. TikTok and Instagram Reels deploy audio fingerprinting systems that identify copyrighted material within seconds of upload. This compression is displacing traditional notice-and-takedown procedures with real-time licensing negotiations that bypass PRO intermediaries entirely.
South Korea's Ministry of Culture, Sports and Tourism has implemented K-content export certification requirements mandating standardized licensing documentation for music incorporated in drama and variety programming distributed through Netflix and Disney+. Domestic publishers must now maintain bilingual contract repositories and automated translation protocols, raising operational barriers for smaller catalog holders unable to absorb compliance costs.
Buyer concentration among the five dominant streaming platforms has compressed synchronization licensing negotiations from quarterly cycles to project-by-project bidding. Music supervisors at Netflix, Amazon Studios, and Apple TV+ now demand exclusive territory carve-outs and shorter option periods than traditional film studio procurement allowed. This pattern is most visible in Los Angeles and London production clusters where supervisor roles have shifted from creative curation to rights clearance optimization.
Global Music Copyright Market Segmentation
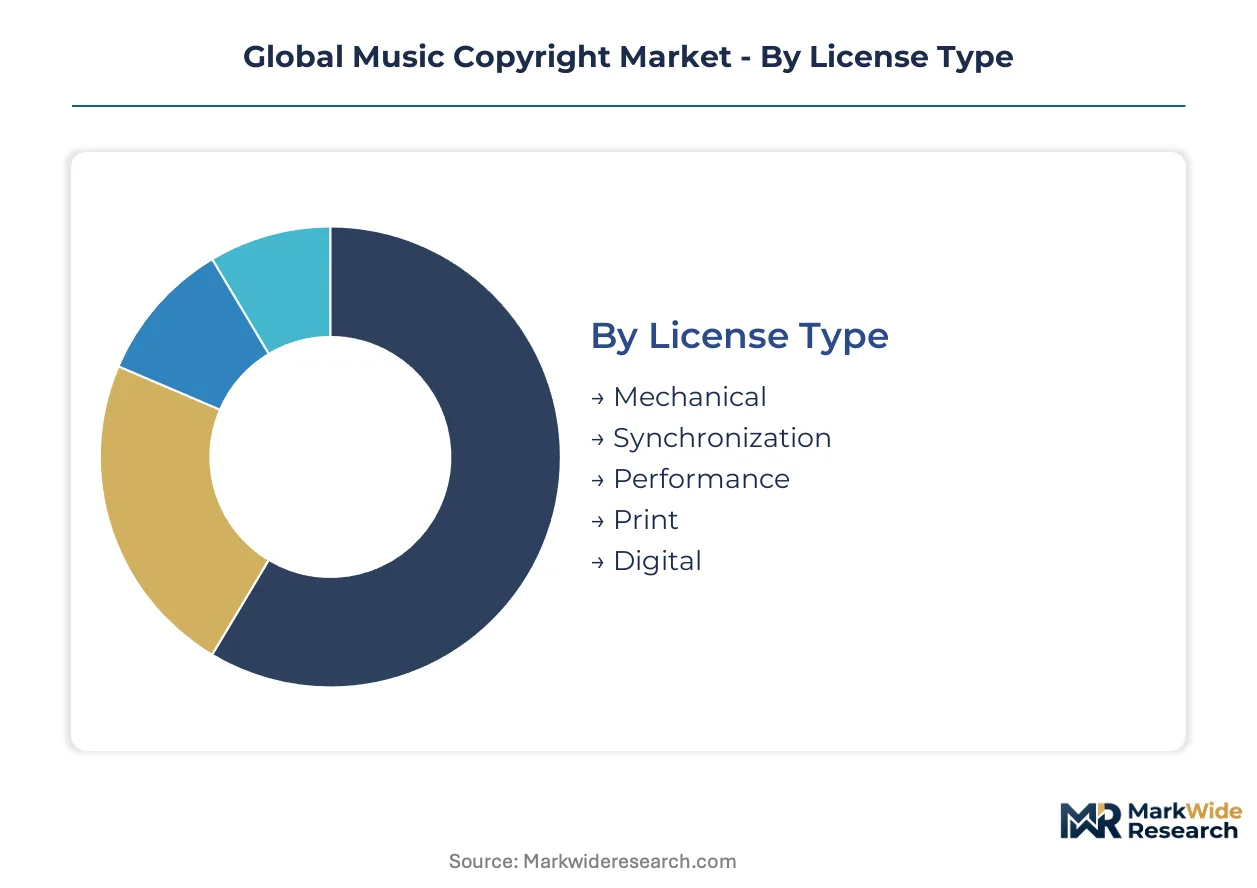
Segmentation in music copyright reveals how licensing economics fragment across use cases, distribution methods, and territorial enforcement regimes. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
License Type:
Synchronization licenses face the most acute substitution pressure from AI-generated music tools and stock audio libraries, while mechanical and performance rights retain stronger legal moats through statutory frameworks.
- Mechanical:Covers the reproduction and distribution of musical compositions across physical and digital formats. Demand concentrates in streaming service mechanical royalty pools in the United States and Germany, where statutory rate-setting by the U.S. Copyright Royalty Board and German GEMA maintain predictable revenue corridors despite platform negotiation leverage.
- Synchronization:Grants rights to pair music with visual media including film, television, and advertising. Original content production by Netflix and Disney+ in South Korea and the United Kingdom is multiplying license volumes, though compressed clearance timelines are squeezing publisher margins.
- Performance:Administered through long-established collecting societies with entrenched broadcaster relationships. PRO infrastructure in France and Japan retains structural advantages through mandatory licensing obligations.
- Print:Encompasses sheet music and lyric reproduction rights. Educational institutions and worship organizations in Italy and Spain sustain residual demand amid digital score platform displacement.
- Digital:Aggregates streaming, download, and interactive audio rights. Platform liability frameworks under the EU Digital Services Act are fragmenting administration between direct licensing stacks and traditional society structures.
Mechanical retains volume leadership; synchronization holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-scale licensors with dedicated rights departments from mid-market entities reliant on blanket licenses.
- Broadcasting Stations:Traditional radio and television operators with mature PRO relationships and predictable repertoire licensing. Public broadcasters in the United Kingdom and Canada anchor demand through statutory license obligations.
- Streaming Services:Video-on-demand and audio platforms negotiating direct publisher deals. Spotify and Apple Music in Sweden and the United States are expanding mechanical licensing footprints while resisting rate increases.
- Music Publishers:Catalog holders administering rights across multiple license types. Major publishers in the United States and Japan leverage synchronization depth against performance society fragmentation.
- Advertising Agencies:High-velocity users requiring rapid clearance for campaign deployment. Creative agencies in France and Brazil face compressed timelines as supervisor roles shift toward rights optimization.
- Event Organizers:Live performance venues and festival operators. Stadium operators in Australia and Mexico navigate territorial society complexity for touring artist repertoire.
Streaming services command the premium pricing tier; advertising agencies drive the most volatile demand spikes.
Distribution Channel:
Supply concentration favors technology-native platforms over legacy society infrastructure in markets with regulatory harmonization.
- Digital Platforms:Automated rights-matching systems deployed by TikTok and Instagram Reels. Audio fingerprinting compression in the United States and South Korea is displacing traditional notice-and-takedown procedures.
- Physical Retailers:Diminishing channel for mechanical reproduction rights. Vinyl resurgence in Germany and Japan sustains niche manufacturing licensing.
- Direct Licensing:Publisher-to-user agreements bypassing collecting society intermediaries. Major publishers in the United Kingdom and Netherlands are building proprietary infrastructure.
- Collecting Societies:Territorial exclusivity mandates in France and Germany force parallel administrative relationships. ECAD restructuring in Brazil under ANCINE oversight is consolidating previously fragmented municipal structures.
- Online Marketplaces:Secondary licensing for production music and stock audio. Platform growth in India and Indonesia is exposing rights verification gaps.
Collecting societies retain territorial enforcement advantages; digital platforms are gaining share fastest through real-time matching technology.
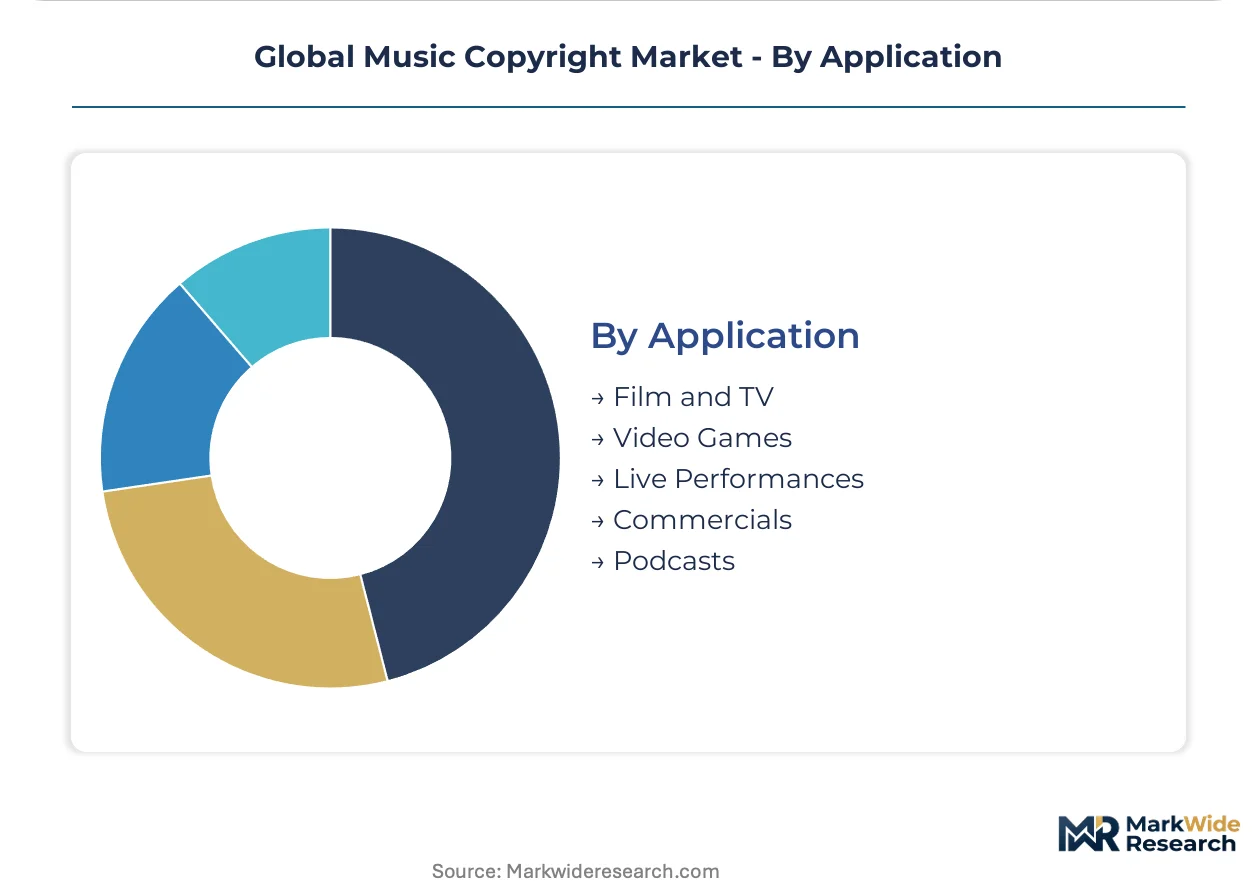
Application:
Customer type divergence separates project-based procurement from recurring licensing relationships.
- Film and TV:Synchronization licensing for theatrical and streaming distribution. Production clusters in Los Angeles and London are shifting supervisor roles from creative curation to clearance optimization.
- Video Games:Adaptive music systems creating new performance rights categories. Triple-A development studios in Japan and Canada require specialized micro-licensing infrastructure.
- Live Performances:Venue and touring rights administered through territorial PROs. Festival operators in Belgium and Portugal face complex multi-territory clearance.
- Commercials:High-value, short-duration licenses with exclusive territory demands. Advertising production in South Korea and Mexico is multiplying synchronization volumes.
- Podcasts:Emerging category with unsettled mechanical and performance rights treatment. Platform growth in the United States and Australia is outpacing licensing framework adaptation.
Film and TV sustains the largest revenue pool; video games are climbing the fastest as interactive audio complexity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streaming platform procurement teams in the United States concentrate synchronization licensing negotiations, while collecting societies in Germany and South Korea administer performance rights through statutory frameworks. This buyer-seller geography shapes clearance timelines and royalty structures across territories.
United States
Netflix and Disney+ production slates in Los Angeles multiply synchronization volumes for original content. The U.S. Copyright Office sets mechanical royalty rates through Copyright Royalty Board proceedings that streaming services resist. Nashville's music publishing corridor anchors catalog administration for country and pop repertoire.
Germany
GEMA administers performance and mechanical rights through territorial exclusivity mandates that fragment cross-border licensing. The EU Digital Services Act imposes direct licensing obligations on user-upload platforms operating across member states. Berlin's startup ecosystem incubates blockchain royalty-tracking ventures challenging society infrastructure.
South Korea
K-content export certification requirements from the Ministry of Culture, Sports and Tourism mandate bilingual licensing documentation for drama and variety programming. Netflix and Disney+ original production in Seoul compresses clearance timelines from months to weeks. Gangnam's entertainment agencies dominate K-pop catalog administration for global synchronization markets.
United Kingdom
PRS for Music and PPL administer performance rights through joint licensing initiatives that reduce broadcaster compliance overhead. The IPO's copyright tribunal streamlines rate disputes between platforms and rights holders. London's production supervisor cluster has shifted from creative curation to rights clearance optimization for streaming originals.
Brazil
ECAD restructuring under ANCINE oversight consolidates previously fragmented municipal collecting societies into scalable blanket licensing frameworks. Streaming platform market entry accelerates as administrative friction declines. São Paulo's advertising production sector drives volatile synchronization demand for commercial campaigns.
Global Music Copyright Market Competitive Landscape
Player mix skews toward diversified entertainment conglomerates with catalog depth advantages over technology-native entrants. Three global publishers control the majority of high-value synchronization repertoire through decades of songwriter acquisitions. Strategic archetypes separate catalog aggregators with film-television relationships from direct-licensing technology stacks and specialized micro-licensing platforms. Competitive moves center on proprietary royalty-tracking infrastructure investment and exclusive territory carve-outs in streaming negotiations.
Within the conglomerate tier, Universal Music Publishing Group and Sony Music Publishing exemplify archetypes built on catalog breadth and direct licensing infrastructure respectively. Warner Chappell Music occupies a position emphasizing proprietary systems that reduce clearance friction. Among independent specialists, Kobalt Music Group and BMG Rights Management represent alternative models challenging traditional collecting society intermediation through technology-first administration.
| Leading Market Players |
|---|
| Universal Music Publishing Group |
| Sony Music Publishing |
| Warner Chappell Music |
| BMG Rights Management |
| Kobalt Music Group |
| Audio Network Limited |
| Concord |
| Downtown Music Holdings |
| Global Music Rights |
| Others |
Supply & Pricing Matrix
Clearance timeline compression from ninety-day cycles to fourteen-day windows concentrates pricing power with streaming platform procurement teams in Los Angeles and Seoul, while fragmenting royalty administration across competing technology stacks. This acceleration rewards publishers with ISO 9001-certified automated licensing infrastructure and penalizes legacy operators dependent on manual society clearances.
Pricing Analysis
Cost-plus contracts indexed to U.S. Copyright Royalty Board mechanical rate proceedings dominate streaming mechanical licensing, with rate floors tied to statutory minima and ceilings negotiated against platform market power. Three-tier pricing structure across premium catalog, standard repertoire, and economy production music separates major publisher synchronization rates from independent catalog and stock audio alternatives. Pricing pressure stems from buyer concentration among five dominant streaming platforms demanding exclusive territory carve-outs. Advertising agencies in São Paulo and Mexico City exhibit highest price sensitivity due to compressed campaign deployment windows, while Netflix and Disney+ original production teams in Seoul show lowest sensitivity for premium K-pop synchronization rights.
Supply Chain Analysis
GEMA territorial exclusivity mandates in Germany create chokepoints forcing parallel administrative relationships for cross-border repertoire licensing. Geographic supply concentration centers on the United States for catalog depth, South Korea for K-content export infrastructure, and the United Kingdom for joint PRO licensing initiatives. Raw material dependencies include songwriter contract pipelines, audio fingerprinting technology licenses, and bilingual documentation systems for K-content certification. Single-source vulnerability runs through collecting society fragmentation in France and Germany, where territorial mandates prevent consolidated administration. Distribution runs through digital platform direct licensing stacks displacing traditional society intermediation, with TikTok and Instagram Reels deploying real-time rights-matching algorithms that bypass PRO infrastructure entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Royalty administration as a recurring service layer expands faster than underlying catalog acquisition economics, creating attach opportunities for technology-native platforms with automated clearance infrastructure. Publishers and collecting societies must reposition around post-licensing revenue optimization rather than front-end clearance fees alone.
For Market Incumbents: Compound catalog depth advantages through exclusive territory carve-outs in streaming negotiations, while investing in proprietary royalty-tracking systems that reduce clearance friction against technology-native entrants. Defend position by accelerating ISO 9001 certification timelines to match Warner Chappell Music's infrastructure lead, and deepen backward integration into audio fingerprinting technology to displace third-party rights-matching dependencies. For New Entrants and Emerging Players: Micro-licensing infrastructure gaps for adaptive music systems in triple-A game development represent the most penetrable white-space target, as standard PRO agreements lack interactive audio categories. Target Brazilian market entry through ECAD restructuring tailwinds, where ANCINE consolidation of municipal societies creates scalable blanket licensing opportunities absent entrenched competitor relationships. Go-to-market angle: specialized gaming audio administration partnerships with Tokyo and Vancouver development studios. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because territorial exclusivity mandates in Germany and France create durable moats for licensed collecting society operators despite technology disruption. Acquisition target archetype: mid-tier publishers with under-monetized synchronization depth in K-content and Bollywood markets. Signal to watch: Copyright Board rate-setting reforms in India accelerating Western catalog penetration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Royalty Tracking Deployment | Distributed ledger verification reduces attribution disputes for catalog assets with complex multi-territory ownership chains. |
| K-Content Export Certification Investment | Bilingual contract repositories and automated translation protocols capture Netflix and Disney+ original production demand in Seoul. |
| Direct Licensing Stack Development | Publisher-to-user agreements bypass GEMA and PRS intermediaries, capturing margin otherwise lost to society administration fees. |
| Gaming Audio Micro-Licensing Infrastructure | Specialized adaptive music rights categories address triple-A studio procurement needs absent from standard PRO agreements. |
| ECAD Restructuring Partnership | ANCINE-consolidated blanket licensing frameworks enable scalable streaming platform market entry across Brazilian territories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across music publishing executives, streaming platform procurement leads, collecting society administrators, K-content export certification officers, and advertising agency music supervisors. Secondary validation drew from U.S. Copyright Office rate proceedings, EU Digital Services Act implementation documentation, South Korean Ministry of Culture export certification requirements, and mechanical royalty tribunal filings. Bottom-up triangulation across license-type transaction volumes and top-down validation against publisher revenue disclosures anchored market sizing.
Across the analysis window, the analytical framework modeled segmentation dimensions including license type, end-user category, distribution channel structure, and territorial regulatory cluster. CAGRs were derived from trend extrapolation against statutory rate-setting proceedings and platform expansion trajectories. Forecast inputs incorporated streaming original content production slates from Netflix and Disney+, K-content export volume certification data, and blockchain royalty-tracking adoption curves in German startup ecosystems.
Underlying assumptions cover sustained streaming platform original content investment, EU Article 17 implementation consistency, and K-content global distribution expansion, with deviation risk concentrated in AI-generated music authorship threshold rulings and collecting society fragmentation persistence. Practitioners should keep alternative scenarios live as regulatory harmonization in Brazil and India proceeds and generative audio tool classification standards crystallize.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Global Advertising Agency Software Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
In-Flight Advertising Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market