
 Global Cross Platform and Mobile Advertising Market | 2026-2036
Global Cross Platform and Mobile Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cross Platform and Mobile Advertising Market Foresight
ISO 27001 certification is redrawing vendor eligibility for enterprise advertising contracts, filtering out platforms lacking audited information-security management. Alphabet Inc. leverages its search and YouTube inventory to sustain dominance in programmatic video. Meta Platforms Inc. anchors its position through Instagram and Facebook's first-party data graph, while The Trade Desk competes via independent demand-side technology that navigates cookie deprecation.
Cross platform and mobile advertising encompasses the delivery of promotional content across smartphone, tablet, desktop, connected television, and wearable interfaces through real-time bidding protocols and deterministic or probabilistic identity resolution. Its primary commercial purpose is to attribute consumer engagement across touchpoints and optimize return on ad spend through automated media buying. Video ad formats command premium inventory rates as connected television scales, while native formats embed within content feeds to bypass banner blindness. Cost Per Mille pricing models remain standard for brand awareness campaigns, though Cost Per Action structures are gaining traction where performance accountability is paramount.
FCC oversight of telecommunications infrastructure affects mobile ad delivery latency and location-data accuracy, while GDPR and the EU AI Act constrain automated decision-making in European targeting. India's TRAI guidelines on unsolicited commercial communication shape how push notifications and SMS campaigns operate in that jurisdiction. Stakeholders must monitor regulatory divergence across the United States, European Union, and Asia-Pacific as compliance investments become a competitive differentiator rather than a cost center.
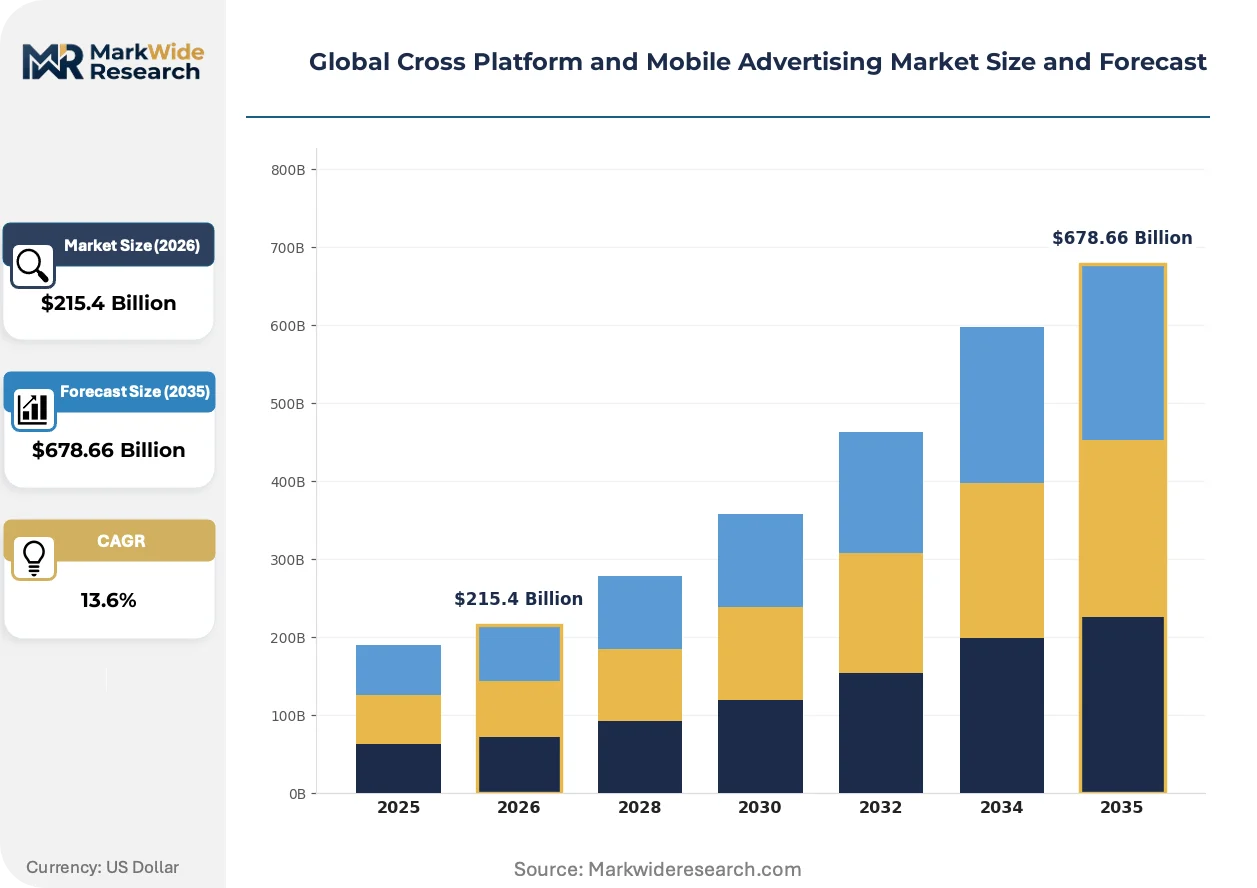
Market Dynamics
Privacy regulations and the deprecation of third-party identifiers are restructuring how advertisers target, measure, and value inventory across mobile and connected television environments. This shift elevates first-party data assets and authenticated identity graphs as the primary currency for programmatic trading.
Growth Catalysts
- Retail Media Networks:Walmart and Amazon are capturing brand budgets through closed-loop attribution, diverting spend from traditional publishers into commerce-integrated ad placements.
- GDPR and CCPA Enforcement:Stricter consent requirements are accelerating investment in consent management platforms and privacy-preserving measurement techniques across European and Californian campaigns.
- Connected Television Scale:Smart TV penetration in the United States, India, and Brazil is expanding addressable video inventory beyond mobile screens into living-room environments.
Market Restraints
- Identifier Deprecation:Apple's App Tracking Transparency and Google's Privacy Sandbox are degrading deterministic attribution, forcing probabilistic modeling with higher measurement variance.
- Supply Concentration:Programmatic inventory flows through a handful of dominant exchanges, creating auction dynamics that squeeze independent publisher yield.
- Technical Latency:FCC spectrum management and 5G deployment gaps in rural United States markets introduce delivery delays that degrade real-time bidding performance.
Strategic Opportunities
- India's App Ecosystem:Jio's affordable data plans and UPI-enabled commerce are creating addressable audiences in Tier-2 and Tier-3 cities previously unreachable through English-language campaigns.
- EU AI Act Compliance Services:Automated decision-making audits and algorithmic transparency tools represent a services white space as European enforcement intensifies.
- Audio-Visual Convergence:Podcast and streaming audio platforms are integrating with video demand-side platforms, enabling unified cross-format campaign planning.
Industry Challenges
- ISO 27001 Certification Timelines:Enterprise procurement mandates require audited information security management, disqualifying vendors with immature compliance programs from RFP processes.
- Legacy SSP-DSP Integration:Header bidding wrappers and proprietary auction mechanics create technical debt that slows unified reporting and frequency management across platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cross Platform and Mobile Advertising Market |
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $678.66 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile, Desktop, Connected TV, Wearables, Smart Speakers Ad Format: Display, Video, Native, Audio, Rich Media, Interactive Industry Vertical: Consumer Electronics, Consumer Packaged Goods, Telecommunications, Education, Entertainment, Transportation Pricing Model: Cost Per Click, Cost Per Mille, Cost Per Action, Cost Per Install, Programmatic Direct |
| Companies Covered | Alphabet Inc. (Google), Meta Platforms Inc., Apple Inc., Microsoft Corporation, Amazon Advertising, The Trade Desk, AppLovin Corporation, InMobi, Unity Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cross Platform and Mobile Advertising Market Shifts & Advancements
Authenticated identity resolution is displacing cookie-based targeting as the foundational infrastructure for cross-device measurement. This transition favors platforms with logged-in user bases and direct publisher relationships over intermediaries dependent on probabilistic matching.
Clean room technology is fragmenting how advertisers access and analyze consumer data. Brands with substantial first-party assets are adopting privacy-enhancing computation to join datasets without raw data sharing. Retailers and financial services firms are deploying these environments fastest, compressing the competitive position of traditional data brokers who lack comparable authenticated reach.
The EU AI Act is constraining automated targeting algorithms in European campaigns. Risk classification of profiling systems requires human oversight for high-risk applications, increasing operational overhead for programmatic platforms. Advertisers serving sensitive categories in France and Germany are restructuring campaign workflows to embed manual review checkpoints before algorithmic bidding executes.
Agency holding companies are unbundling programmatic trading desks from media planning functions. Brands in the United States and United Kingdom are building in-house buying capabilities or contracting directly with independent demand-side technology, disintermediating traditional agency intermediaries. This reconfiguration is most visible among CPG and automotive advertisers with sufficient transaction volume to justify dedicated platform licensing.
Global Cross Platform and Mobile Advertising Market Segmentation
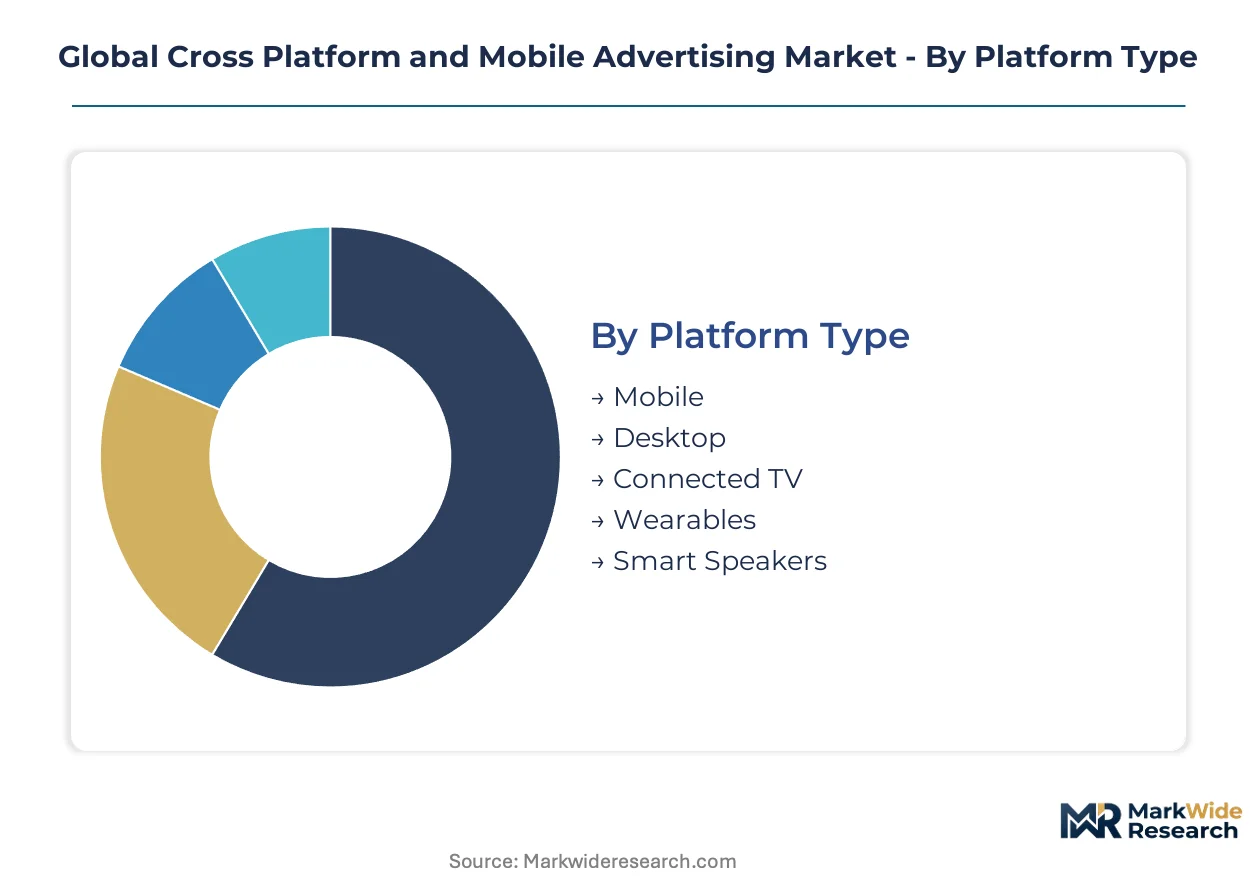
Segmentation in cross-platform advertising reveals how inventory value, measurement fidelity, and buyer sophistication vary across technical environments. Platform type and ad format determine addressable audience scale, while pricing model selection reflects campaign objectives ranging from brand awareness to direct response optimization.
Platform Type:
Mobile inventory dominates domestic consumption in India and Brazil, whereas Connected TV and Desktop segments skew toward export-led demand from multinational advertisers targeting developed markets.
- Mobile:Smartphone inventory commands the deepest liquidity pools through in-app and mobile web placements. Demand concentrates in India, Indonesia, and Nigeria where Jio and similar carriers have collapsed data costs; India's TRAI regulations on unsolicited commercial communication constrain push notification formats here.
- Connected TV:Smart television placements integrate programmatic video into living-room environments with deterministic IP-based targeting. Demand concentrates in the United States and United Kingdom where streaming subscription fatigue has accelerated ad-supported tier adoption; FCC spectrum management affects delivery latency in rural American markets.
- Desktop:Browser-based inventory retains strength in B2B and financial services campaigns requiring detailed creative real estate. Primarily serves professional audiences in Germany, Japan, and South Korea during business hours.
- Wearables:Watch and fitness band placements enable glanceable notifications with strict creative constraints. Early demand from health insurers and fitness brands in Australia and Switzerland.
- Smart Speakers:Voice-activated audio ads leverage ambient computing penetration in English-speaking households. Inventory scarcity limits scale to the United States and United Kingdom.
Mobile holds the largest share; momentum sits with Connected TV as living-room addressability expands.
Ad Format:
Video and native formats command premium rate cards due to engagement depth, while display and audio trade at efficiency-focused CPMs suitable for high-frequency retargeting.
- Video:Sight-sound-motion inventory spans pre-roll, mid-roll, and vertical short-form placements with completion-rate optimization. Demand concentrates in connected television and mobile environments; GDPR consent requirements complicate personalized sequencing in European campaigns.
- Native:Feed-embedded units mimic editorial content to bypass banner blindness through contextual relevance. Demand concentrates in news aggregators and social platforms; the EU AI Act constrains algorithmic personalization for sensitive categories in France and Germany.
- Display:Standard banner and interstitial units provide broad reach at commoditized pricing. Remains foundational for retargeting and brand safety blocking in programmatic open auctions.
- Audio:Streaming music and podcast placements enable screen-free engagement during commute and exercise contexts. Expanding most quickly in Brazil and Mexico alongside podcast platform growth.
- Rich Media:Expandable and interactive units incorporate gesture, tilt, and haptic feedback for creative differentiation. Premium pricing limits deployment to automotive and luxury campaigns.
- Interactive:Playable ads and augmented reality experiences require user initiation and deliver engagement metrics beyond viewability. Concentrated in gaming and app install campaigns.
Video holds the largest share; momentum sits with Native as privacy constraints elevate contextual relevance.
Industry Vertical:
Consumer electronics and telecommunications advertisers maintain the highest programmatic sophistication, while education and transportation verticals lag in first-party data infrastructure.
- Consumer Electronics:Smartphone, laptop, and appliance manufacturers deploy cross-device sequencing to mirror product research journeys. Samsung and Apple retail media networks capture closed-loop attribution; demand concentrates in South Korea, China, and the United States.
- Telecommunications:Carriers and equipment vendors leverage subscriber data for lookalike modeling and churn prevention. India's Jio and China's China Mobile operate captive advertising ecosystems with deterministic targeting.
- Consumer Packaged Goods:FMCG brands prioritize reach and frequency over direct attribution due to retail intermediary separation. Walmart and Amazon retail media networks are disintermediating traditional publisher relationships here.
- Entertainment:Streaming services and studios deploy trailer and tune-in campaigns with day-part optimization. Connected TV inventory dominates theatrical release windows.
- Education:Universities and edtech platforms concentrate spending in desktop and mobile during enrollment periods. Seasonal demand spikes constrain year-round platform commitment.
- Transportation:Airlines and automotive brands balance brand storytelling with location-based proximity targeting. Ride-hailing apps operate competing retail media networks that capture endemic budgets.
Consumer Electronics holds the largest share; momentum sits with Consumer Packaged Goods as retail media networks expand.
Pricing Model:
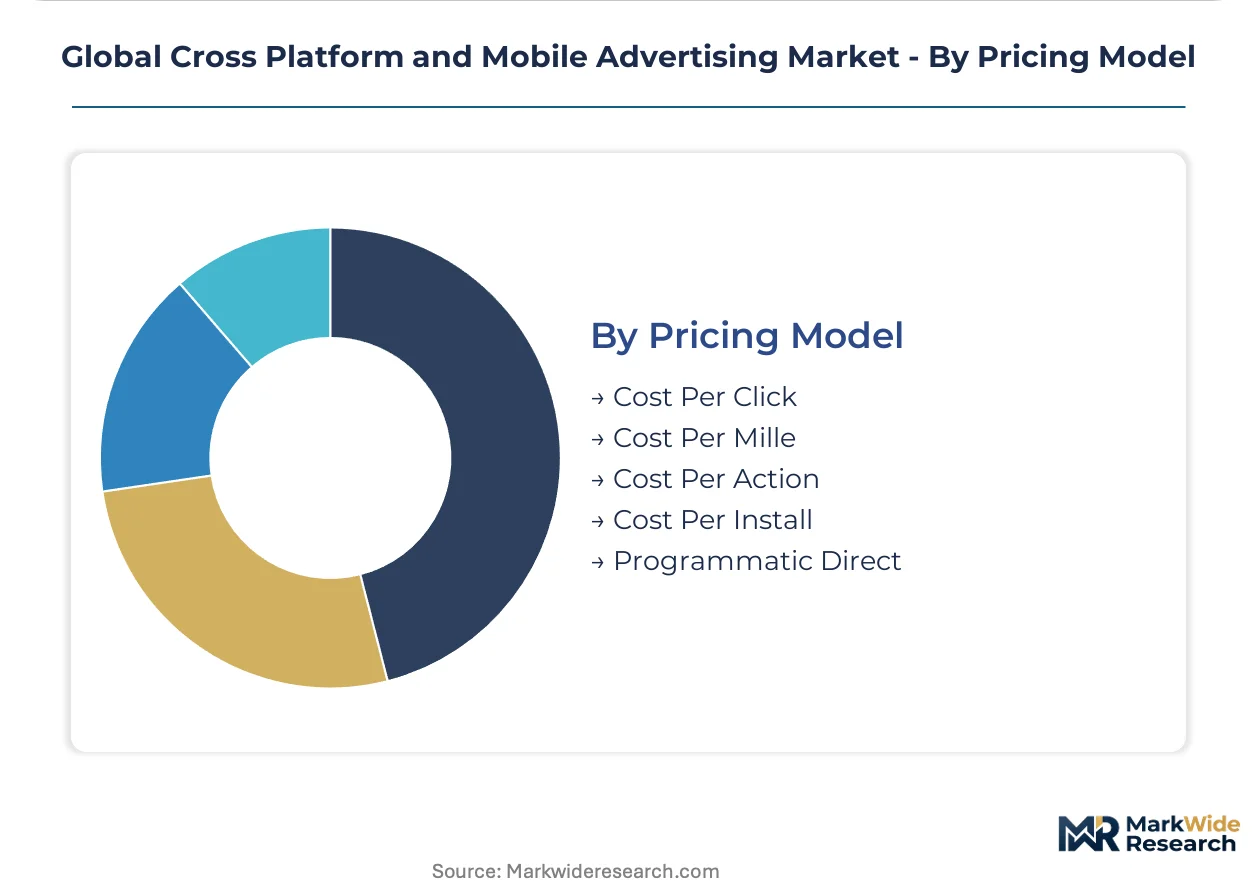
Cost Per Mille structures dominate brand awareness objectives, while performance advertisers migrate toward Cost Per Action and Cost Per Install to align spending with measurable outcomes.
- Cost Per Mille:Thousand-impression pricing remains the standard for upper-funnel campaigns where viewability and brand lift metrics supersede direct response. Preferred by CPG and automotive advertisers with extended purchase cycles.
- Cost Per Action:Outcome-based pricing ties payment to specified conversions—purchases, sign-ups, or qualified leads. Expanding most quickly among DTC brands and fintech apps with robust attribution infrastructure; Apple's App Tracking Transparency degrades deterministic measurement here.
- Cost Per Click:Engagement-based pricing persists in search and social environments where intent signals are strongest. Google and Meta auction mechanics optimize toward this objective.
- Cost Per Install:Mobile-specific pricing dominates gaming and utility app user acquisition with fraud detection as a critical vendor capability. Prevalent in India, Vietnam, and Brazil hyper-casual game markets.
- Programmatic Direct:Reserved inventory agreements guarantee placement quality and brand safety through private marketplace pipes. Preferred by pharmaceutical and financial services advertisers with regulatory compliance requirements.
Cost Per Mille holds the largest share; momentum sits with Cost Per Action as accountability pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable systems and 5G spectrum auctions are redrawing how advertising inventory flows across national boundaries. Data localization requirements and divergent privacy enforcement are fragmenting what was once a seamless global marketplace.
United States
FCC spectrum management governs 5G deployment density that determines mobile ad delivery latency in rural markets. Apple's App Tracking Transparency framework has degraded deterministic attribution for iOS campaigns, forcing probabilistic modeling. The San Francisco Bay Area and New York Metro anchor programmatic technology development, with independent demand-side platforms consolidating talent pools.
China
MIIT licensing requirements for commercial messaging platforms constrain push notification campaigns. SAMR antitrust scrutiny has fragmented super-app advertising dominance. The Yangtze River Delta and Pearl River Delta host the densest concentration of mobile commerce infrastructure, with retail media networks capturing closed-loop attribution.
India
TRAI guidelines on unsolicited commercial communication shape SMS and push notification deployment. Jio's affordable data plans have collapsed connectivity costs in Tier-2 and Tier-3 cities. Mumbai and Bangalore concentrate mobile advertising technology operations, with UPI-enabled commerce creating addressable audiences previously unreachable.
Germany
GDPR enforcement through CNIL-aligned state regulators constrains algorithmic personalization for sensitive categories. The EU AI Act risk classification requires human oversight for high-risk profiling applications. Berlin and Munich host programmatic platform engineering centers, with automotive advertisers restructuring workflows for manual review checkpoints.
Brazil
ANVISA and consumer protection frameworks govern health-related advertising claims. ANATEL spectrum allocation affects mobile video delivery quality in dense urban corridors. São Paulo anchors Latin American programmatic trading, with podcast platform growth expanding audio inventory availability.
Global Cross Platform and Mobile Advertising Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and data infrastructure dimensions. The market exhibits tiered concentration, with dominant platforms controlling authenticated identity graphs while independent intermediaries compete on transparency and measurement neutrality. Two strategic archetypes predominate: closed ecosystems leveraging first-party data assets, and independent infrastructure providers enabling cross-platform buying. Consolidation through strategic partnerships and vertical integration into clean room technology represent the dominant competitive vectors.
Within the closed ecosystem tier, Alphabet Inc. and Meta Platforms Inc. exemplify platforms that monetize logged-in user bases across search, video, and social environments. The Trade Desk occupies a position as an independent demand-side technology provider, navigating cookie deprecation through unified identity frameworks. These three anchors illustrate the structural tension between data-rich walled gardens and neutral intermediaries.
| Leading Market Players |
|---|
| Alphabet Inc. (Google) |
| Meta Platforms Inc. |
| Apple Inc. |
| Microsoft Corporation |
| Amazon Advertising |
| The Trade Desk |
| AppLovin Corporation |
| InMobi |
| Unity Software Inc. |
| Others |
Supply & Pricing Matrix
Authenticated identity graphs are displacing third-party cookie infrastructure as the primary currency for programmatic trading, simultaneously redrawing supply geography toward walled-garden platforms in the United States and China while compressing pricing power for independent intermediaries lacking comparable first-party data assets.
Pricing Analysis
Volume-discount tiering structures separate enterprise advertisers committing nine-figure annual minimums from mid-market buyers and self-serve entrants, with ISO 27001 certification and clean room integration serving as the primary price differentiation drivers. Pricing pressure stems from retail media networks capturing closed-loop attribution budgets previously directed to open-web publishers. Enterprise CPG and automotive advertisers demonstrate lowest price sensitivity due to brand safety requirements, while DTC brands and hyper-casual game developers operate at highest sensitivity with thin unit economics.
Supply Chain Analysis
Inventory lead times for premium connected television placements extend 30-90 days in the United States and United Kingdom due to supply scarcity, while mobile programmatic inventory clears in milliseconds through real-time bidding. Supply concentrates in the United States, China, and India where cloud infrastructure and carrier networks anchor delivery. The supply chain draws from submarine cable systems, 5G spectrum allocations, and data center capacity as critical inputs. Single-source vulnerability sits with Google's Privacy Sandbox timeline uncertainty. Distribution runs through demand-side platforms, supply-side platforms, and ad exchanges in sequential auction layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-party data engineering and privacy-preserving measurement represent the scarcest capabilities in this market, with vendors possessing authenticated identity graphs commanding valuation premiums over intermediaries dependent on probabilistic matching.
For Market Incumbents: Consolidate demand-side technology capabilities through acquisition of clean room specialists and consent management platforms to defend against independent intermediaries disintermediating agency trading desks. Prioritize ISO 27001 certification completion to maintain enterprise RFP eligibility as procurement mandates tighten. For New Entrants and Emerging Players: Anchor in India's Tier-2 and Tier-3 city app ecosystems where Jio's data cost collapse has created addressable audiences unreachable by English-language campaigns. Deploy UPI-enabled commerce attribution as the go-to-market wedge against established platforms lacking local payment integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap demand-side platforms possessing independent identity frameworks but lacking scaled publisher relationships. Long-term viability hinges on authenticated reach expansion rather than probabilistic workaround technology. The signal to watch is Apple's ATT framework enforcement intensity as a demand compression indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Technology Deployment | Enables privacy-preserving data collaboration for retail media networks competing with Amazon and Walmart. |
| Consent Management Platform Integration | Addresses GDPR and CCPA enforcement requirements across European and Californian campaign operations. |
| Connected TV Inventory Acquisition | Captures living-room addressability as streaming subscription fatigue accelerates ad-supported tier adoption. |
| In-House Trading Desk Buildout | Disintermediates agency holding companies for CPG and automotive advertisers with sufficient transaction volume. |
| Retail Media Network Partnership | Secures closed-loop attribution capabilities as commerce-integrated placements divert spend from traditional publishers. |
Research Methodology
Desk research of SEC 10-K filings, App Annie mobile intelligence, and hyperscaler capex disclosures preceded structured interviews with programmatic platform engineers, agency trading desk directors, brand marketing executives, and publisher revenue operations leads. Primary fieldwork combined with secondary validation across regulatory filings from the FCC, GDPR enforcement actions, and TRAI guidelines. Bottom-up inventory flow analysis triangulated against top-down advertising spend estimates.
Variance-decomposition across platform type, ad format, pricing model, and geographic regulatory cluster shaped the analytical framework. Modeled dimensions included authenticated versus probabilistic identity resolution, walled-garden versus open-web inventory, and deterministic versus modeled attribution pathways. CAGRs derived from segment-level growth rate reconciliation against macroeconomic advertising elasticity assumptions. Forecast inputs incorporated 5G deployment trajectories and privacy regulation enforcement intensity indices.
Decision-makers should treat outputs as directional under sustained App Tracking Transparency enforcement and EU AI Act risk classification assumptions; material deviation in regulatory timelines or identifier deprecation schedules would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
United States Marketing Agencies Market