
 Global Print Advertising Market | 2026-2036
Global Print Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Global Print Advertising Market Intelligence
The gap between premium and commodity print advertising is broadening as luxury advertisers demand heavier stock weights, spot varnishes, and bespoke finishing while mass-market buyers shift to lighter, cost-optimized formats. WPP leverages its integrated production networks to control premium print workflows end-to-end. Omnicom Group sustains scale advantages in newspaper insert campaigns across North American markets. Publicis Groupe differentiates through data-informed print placement that bridges offline creative with digital attribution models.
Print advertising encompasses paid messaging distributed through physically printed media including magazines, newspapers, brochures, and direct mail pieces, typically produced via offset lithography or digital inkjet processes on coated or uncoated paper stocks ranging from 60 to 400 gsm, serving brand awareness, direct response, and local promotional objectives for commercial advertisers. Magazine advertising occupies the most durable margin pool as glossy formats command premium rates from automotive and fashion clients despite circulation declines. Direct mail competes most intensely with digital channels, though personalized variable-data printing is reviving response rates in retail verticals. Newspaper classified advertising remains structurally mature, with revenue concentrated in legal notices and hyperlocal service listings that digital platforms have not fully replicated.
The US Federal Trade Commission enforces truth-in-advertising standards that extend to print claims, while the EU Green Deal's paper traceability requirements are pressuring publishers to certify recycled content percentages. India's Bureau of Indian Standards governs newsprint quality specifications that affect print reproduction fidelity for national campaigns. Stakeholders must monitor how extended producer responsibility frameworks for paper waste reshape cost structures and sourcing decisions across major publishing markets.
Market Dynamics
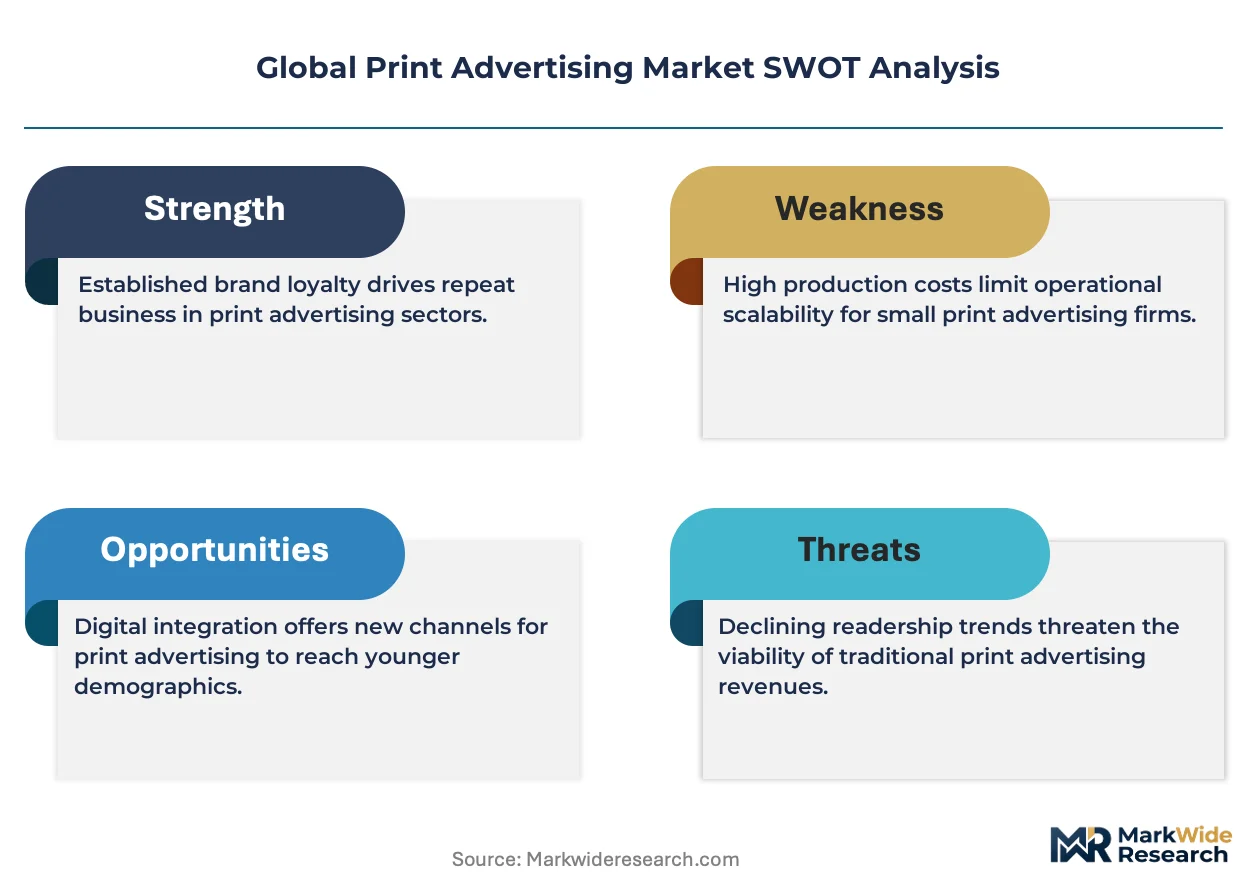
The EU Green Deal's paper traceability mandates are forcing publishers and agencies to reconfigure sourcing networks, while luxury advertisers' demand for tactile premium formats creates divergent cost structures between high-end and mass-market print workflows.
Growth Catalysts
- Luxury brand tactile storytelling:Automotive and fashion houses are expanding commitments to heavier stock weights and bespoke finishing, sustaining margin pools in glossy magazine formats despite circulation compression.
- EU Green Deal certification pull:The EU Green Deal's recycled content mandates are accelerating supplier certification adoption, creating competitive differentiation for publishers with verified chain-of-custody documentation.
- Variable-data printing revival:Personalized direct mail campaigns using digital inkjet processes are recovering response rates in retail verticals, narrowing the performance gap with digital channels.
Market Restraints
- Pulp cost volatility:Newsprint and coated paper input costs fluctuate with global pulp supply disruptions, compressing margins for newspaper classified advertisers operating on fixed-rate contracts.
- Digital substitution pressure:Programmatic display and social media advertising continue displacing mass-market print budgets, particularly among price-sensitive local service advertisers.
- REACH chemical compliance friction:EU REACH restrictions on certain inks and coatings are extending production timelines for European campaigns, adding regulatory overhead to cross-border print procurement.
Strategic Opportunities
- Rural India regional language expansion:Hindi, Tamil, and Marathi newspaper readership remains durable among non-urban consumers, offering advertisers access to audiences with limited digital penetration.
- CSRD sustainability disclosure integration:The EU Corporate Sustainability Reporting Directive is creating demand for print materials that document environmental credentials, opening placement opportunities in ESG-focused publications.
- AR-enabled print bridging:Augmented reality overlays on physical advertisements are converging with smartphone camera ubiquity, enabling new attribution models that connect offline creative to digital engagement metrics.
Industry Challenges
- Skilled press operator scarcity:Experienced technicians capable of managing complex spot varnish and die-cutting workflows on premium jobs are aging out of the workforce faster than training pipelines replenish.
- Multi-jurisdiction certification complexity:Publishers running campaigns across the US, EU, and India must simultaneously satisfy FTC truth-in-advertising standards, EU Green Deal traceability rules, and BIS newsprint quality specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Print Advertising Market |
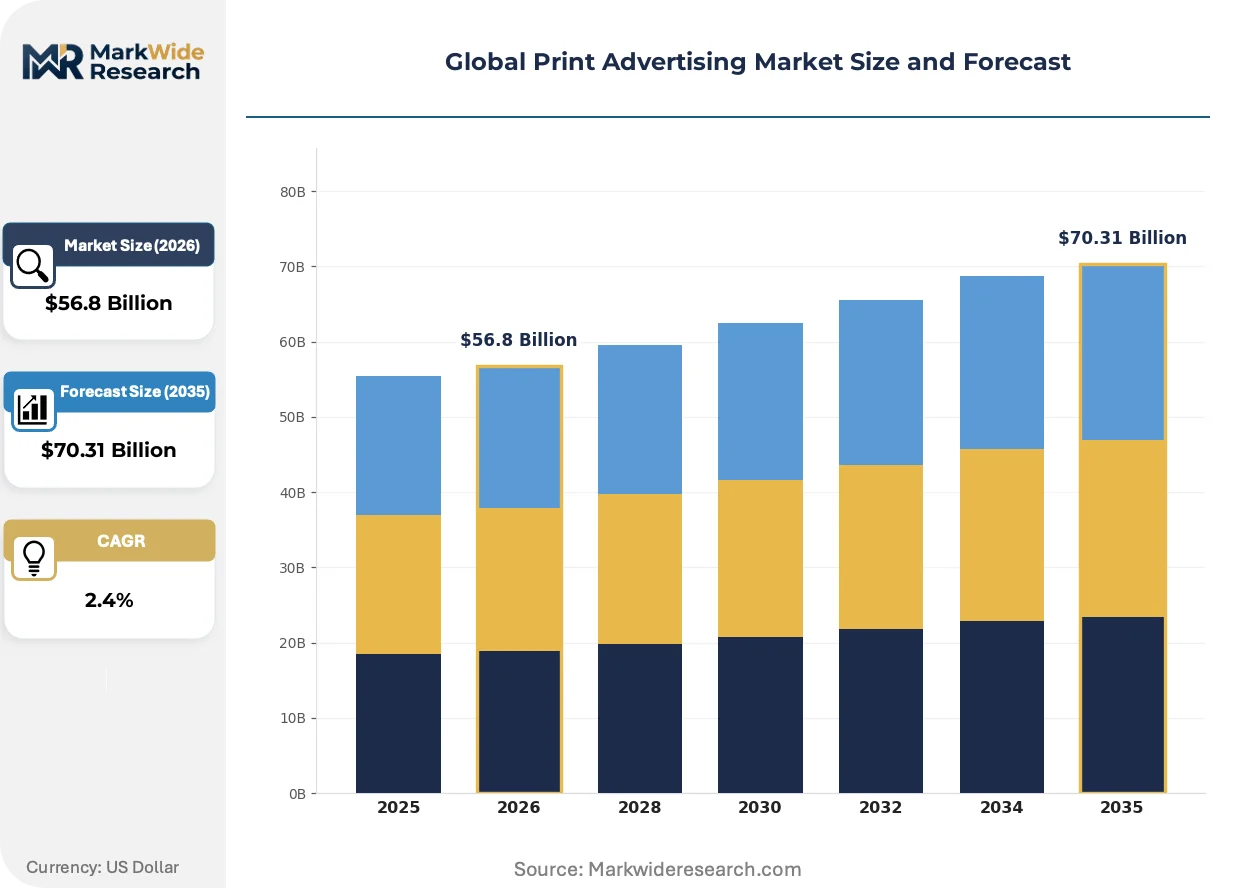
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $70.31 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Magazine, Newspaper, Brochure, Direct Mail Target Audience: Businesses, Consumers, Nonprofits, Government Ad Format: Display Ads, Classified Ads, Inserts, Coupons Industry Vertical: Retail, Automotive, Education, Healthcare |
| Companies Covered | Interpublic Group, Havas Worldwide, WPP, McCann Worldgroup, Ogilvy, Omnicom Group, Dentsu Group, BBDO Worldwide, Publicis Groupe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Print Advertising Market Strategic Shifts & Innovations
Print advertising workflows are being restructured by three intersecting forces: digital production technologies that compress lead times, regulatory frameworks that mandate supply chain transparency, and buyer behaviors that privilege measurable offline-to-online attribution.
Web-to-print automation platforms are converging with cloud-based prepress systems, enabling real-time proofing and reducing campaign launch cycles from weeks to days. Mid-market retailers and regional franchises are adopting these tools at accelerating rates. The structural consequence is converging with traditional agency production models, compressing margins for standalone prepress service providers.
The EU Green Deal's extended producer responsibility frameworks are mandating cradle-to-grave documentation for paper waste streams, compelling publishers to certify recycled content percentages and chain-of-custody protocols. Industrial consequence includes elevated compliance costs for smaller print houses lacking integrated sustainability officers. Magazine publishers serving automotive and luxury clients are responding fastest, embedding certification badges directly into creative layouts.
Attribution-driven media buying is displacing legacy circulation-based rate cards, with advertisers now demanding proof of engagement lift rather than guaranteed impressions. Programmatic print placement platforms are emerging to satisfy this requirement, particularly in direct mail verticals. The United States and United Kingdom represent the most visible geographies for this behavioral shift, where retail and financial services buyers lead adoption.
Global Print Advertising Market Segmentation
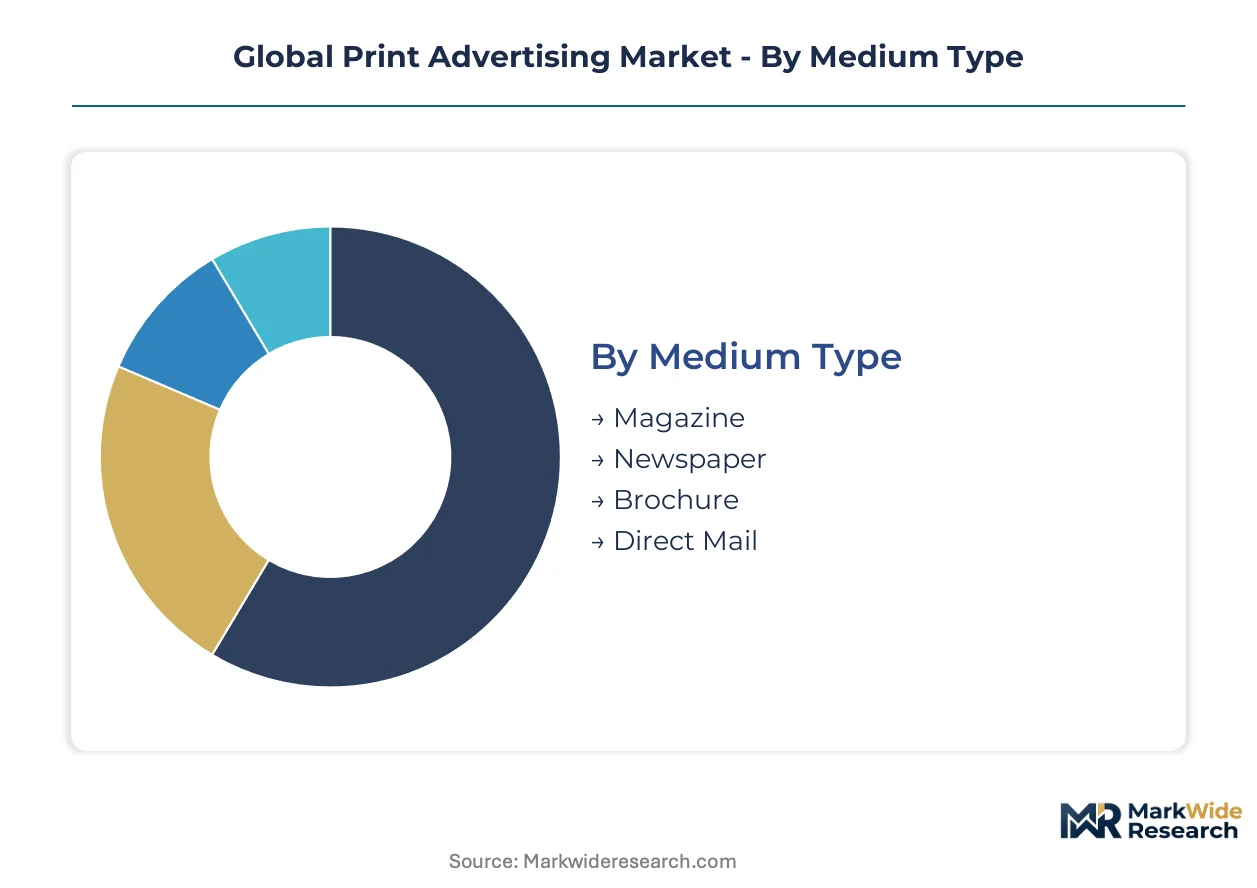
Print advertising segmentation reveals how budget allocation, creative specifications, and regulatory exposure vary dramatically across media channels and buyer profiles. Understanding these fault lines helps suppliers configure production assets and compliance frameworks for maximum yield.
Medium Type:
Cost tier separates premium tactile formats from commodity newsprint, with production complexity and margin structure diverging sharply between glossy magazines and daily newspapers.
- Magazine:Glossy coated stocks from 130 to 300 gsm support automotive and fashion advertisers demanding spot varnishes and bespoke finishing. Luxury brand commitments sustain durable margin pools despite circulation compression across North American and European markets.
- Newspaper:Uncoated newsprint ranging from 45 to 60 gsm serves high-frequency local messaging with rapid production cycles. Regional language titles in India sustain readership among rural consumers with limited digital penetration, offsetting classified advertising erosion elsewhere.
- Brochure:Multi-page saddle-stitched or perfect-bound formats enable detailed product storytelling for B2B and high-consideration consumer categories.
- Direct Mail:Variable-data digital inkjet personalization is reviving response rates in retail verticals through targeted household-level creative versioning.
Newspaper leads volumes today; direct mail is gaining share fastest through data-driven personalization capabilities.
Target Audience:
Application context determines creative complexity and compliance burden, with B2B campaigns requiring heavier documentation and consumer-facing work prioritizing visual impact.
- Businesses:B2B advertisers prioritize technical specifications and long-form content in trade publications and direct mail. Procurement teams negotiate annual rate commitments with publishers serving manufacturing and professional services verticals.
- Consumers:Mass-market campaigns emphasize emotional storytelling and promotional mechanics in magazines and newspaper inserts. Retail and CPG buyers dominate this segment with seasonal campaign calendars tied to holiday shopping patterns.
- Nonprofits:Cause-driven messaging relies on donated or discounted media space with stringent FTC truth-in-advertising compliance for fundraising claims.
- Government:Public service announcements and legal notices follow strict procurement protocols with mandatory print placement for transparency requirements.
Consumer targeting dominates revenue today; business-focused campaigns are expanding most quickly as account-based marketing extends into physical channels.
Ad Format:
Volume scale and attribution measurability separate high-unit insert campaigns from premium display placements with limited performance tracking.
- Display Ads:Full-page or fractional placements in editorial environments command rate premiums based on circulation audits. Automotive and fashion advertisers concentrate spending here for brand storytelling in glossy contexts.
- Classified Ads:Text-dense listings for legal notices, real estate, and employment remain structurally mature. Revenue concentrates in mandatory public filings that digital platforms have not fully displaced.
- Inserts:Freestanding preprints distributed within newspaper editions enable mass distribution with standalone creative control. Retail and grocery chains dominate volume with weekly circular programs.
- Coupons:Promotional tear-outs and digital-to-print redemption mechanisms bridge offline distribution with online transaction tracking.
Inserts lead volumes today; display ads retain the steepest expansion trajectory among premium advertisers seeking tactile differentiation.
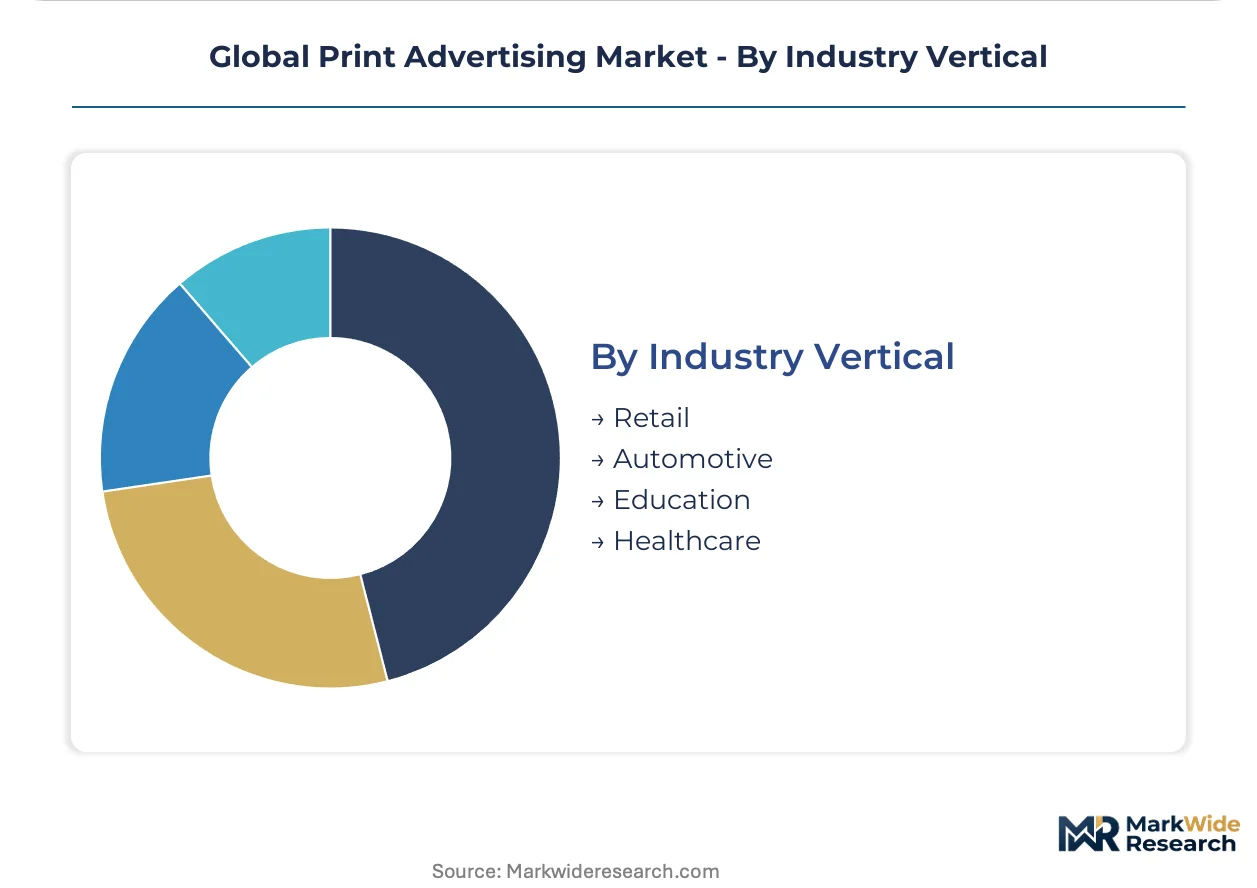
Industry Vertical:
Margin maturity and supply concentration shape how automotive, retail, education, and healthcare buyers negotiate production timelines and sustainability certifications.
- Retail:High-frequency promotional calendars drive newspaper insert and direct mail volume with compressed turnaround requirements. Variable-data printing adoption is highest here as personalization recovers response rates against digital competition.
- Automotive:Premium magazine placements with heavy stock weights and specialty finishes sustain above-average CPMs. OEM marketing teams demand EU Green Deal chain-of-custody documentation for sustainability reporting.
- Education:Seasonal enrollment campaigns in regional newspapers and direct mail target geographic catchment areas with family household targeting.
- Healthcare:Regulatory scrutiny from FDA and FTC constrains creative claims, with print serving compliance-heavy patient education and provider recruitment.
Retail dominates volume today; automotive is climbing the fastest on premium format expansion and sustainability certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India sustains the strongest print volume trajectory among major economies, while Germany confronts the steepest compliance cost escalation from EU Green Deal mandates. Regulatory divergence is fragmenting campaign execution standards across publishing markets.
United States
Newspaper insert campaigns and direct mail personalization drive resilient demand from retail and financial services advertisers. FTC truth-in-advertising enforcement constrains creative claims in fundraising and healthcare verticals. The Midwest corridor spanning Chicago and Detroit retains concentrated prepress and production infrastructure serving national circular programs.
Germany
Automotive OEM marketing sustains premium magazine commitments with heavy stock specifications and specialty finishing requirements. EU Green Deal chain-of-custody documentation mandates elevate compliance overhead for publishers serving luxury brand accounts. The Baden-Württemberg and Bavaria industrial clusters host specialized print houses certified for cradle-to-grave paper traceability.
India
Hindi, Tamil, and Marathi regional language newspapers maintain durable rural readership with limited digital platform competition. Bureau of Indian Standards newsprint quality specifications govern reproduction fidelity for national campaign distribution. Maharashtra and Gujarat publishing hubs concentrate vernacular title production serving advertisers targeting non-urban consumer bases.
United Kingdom
Magazine publishers serving fashion and automotive clients command rate premiums despite circulation compression across glossy formats. CSRD sustainability disclosure requirements are creating placement demand for ESG-focused editorial environments. London-based media buyers lead adoption of programmatic print placement platforms linking offline creative to digital attribution metrics.
Japan
Direct mail variable-data printing recovers response rates in retail verticals through targeted household-level creative versioning. METI industrial standards influence production quality benchmarks for premium tactile formats. The Kanto region surrounding Tokyo concentrates specialized finishing capabilities for luxury brand seasonal campaigns.
Global Print Advertising Market Key Industry Players
Top-tier vendors anchor integrated production networks, while mid-scale specialists concentrate on regional prepress and finishing workflows. The vendor base stratifies across holding company conglomerates, independent creative agencies, and technology-enabled production platforms. Strategic archetypes include end-to-end workflow integrators, data-informed placement optimizers, and sustainability certification specialists. Competitive positioning depends on backward integration into print production assets and cross-border compliance management capabilities.
Among holding company networks, WPP, Omnicom Group, and Publicis Groupe occupy positions spanning creative development through production execution. WPP exemplifies the integrated workflow archetype with captive control over premium print specifications. Omnicom Group represents scale advantages in high-volume newspaper insert distribution. Publicis Groupe sits within the data convergence tier bridging offline placement with digital attribution infrastructure.
| Leading Market Players |
|---|
| Interpublic Group |
| Havas Worldwide |
| WPP |
| McCann Worldgroup |
| Ogilvy |
| Omnicom Group |
| Dentsu Group |
| BBDO Worldwide |
| Publicis Groupe |
| Others |
Cost & Logistics Intelligence
Pulp cost volatility in Nordic and Canadian softwood markets cascades through coated paper pricing tiers, with luxury magazine advertisers absorbing premium stock premiums while mass-market newspaper buyers face margin compression from newsprint contract renegotiations.
Pricing Analysis
Capacity additions in Southeast Asian digital inkjet facilities are reshaping price floors for variable-data direct mail campaigns. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEMs demanding EU Green Deal chain-of-custody documentation from retail chains optimizing insert weights. Cost compression in newsprint classifieds is intensifying because fixed-rate municipal notice contracts lag pulp index movements. Retail grocery buyers exhibit highest price sensitivity; luxury fashion houses show least.
Supply Chain Analysis
EU Green Deal chain-of-custody certification gates access to automotive and luxury brand accounts, forcing publisher qualification investments. Paper sourcing concentrates in Finland, Sweden, and Canada for virgin pulp; India and Indonesia for recycled fiber stocks. Production feeds from global pulp exchanges, coated paper mills in Germany and Japan, and regional newsprint converters. Single-source vulnerability sits with Nordic pulp suppliers exposed to energy cost shocks. Distribution runs through holding company production networks, independent prepress houses, and web-to-print platforms serving mid-market retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Print advertising operates as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France run triple those in India, creating margin expansion for publishers with multi-jurisdiction certification infrastructure.
For Market Incumbents: Lock in premium magazine workflows through captive control of spot varnish and die-cutting capabilities before skilled press operator scarcity worsens. Secure chain-of-custody certification across EU, US, and Indian regulatory frameworks to defend against emerging sustainability-specialist competitors. Backward integration into recycled fiber sourcing hedges pulp cost volatility.
For New Entrants and Emerging Players: Launch via web-to-print automation platforms targeting mid-market retail franchises with compressed turnaround requirements. White-space concentrates in rural India regional language newspaper production, where digital penetration remains limited and BIS quality specifications create barrier entry. Go-to-market angle: variable-data personalization for direct mail verticals recovering response rates against digital channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU Green Deal compliance overhead exceeds standalone operator margins. Long-term viability favors vertically integrated networks spanning creative development through certified production execution. Target acquisition archetype: mid-scale prepress houses with established automotive or luxury brand relationships and existing FSC/PEFC certification. Signal to watch: pulp futures backwardation indicating sustained input cost pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Certification Investment | Chain-of-custody documentation unlocks automotive OEM marketing budgets in Germany. |
| Variable-Data Digital Inkjet Capacity Expansion | Personalized direct mail recovers retail response rates against programmatic display competition. |
| Regional Language Publishing Acquisition | Hindi and Tamil title portfolios access rural Indian consumer bases with durable readership. |
| Web-to-Print Platform Integration | Cloud-based prepress compression reduces campaign launch cycles for franchise retail networks. |
| Skilled Workforce Training Pipeline | Press operator development programs address aging-out technician scarcity in premium finishing workflows. |
Research Approach
Bottom-up advertiser spend modeling reconciled against top-down pulp and paper production tracking forms the analytical core of this study. Primary interviews with creative agency production directors, magazine publisher circulation managers, prepress house technical leads, and retail marketing procurement officers combined with secondary validation against FSC chain-of-custody databases, BIS newsprint quality specifications, and EU Green Deal regulatory filings. Top-down and bottom-up triangulation cross-checks holding company revenue disclosures against regional publisher rate card audits.
Historical trendline analysis of magazine rate card evolution, newspaper insert volume indices, and direct mail response rate benchmarks informs projection frameworks across the analysis window. Segmentation dimensions modeled include medium type, target audience, ad format, and industry vertical with geographic regulatory cluster overlays. CAGRs derive from regression-adjusted spend trajectories incorporating pulp futures curves and circulation audit compression rates. Forecast inputs incorporate EU Green Deal compliance cost escalations and India rural readership durability assumptions.
Several conditions sit outside the modeled scope, including extreme pulp supply disruptions from geopolitical conflict, rapid digital substitution acceleration beyond historical displacement rates, and unanticipated REACH chemical restriction expansions. Forecasts reflect documented assumptions about regulatory stability and luxury brand tactile format commitment persistence. A model refresh is warranted upon material change in EU extended producer responsibility enforcement intensity or India rural digital penetration inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market