
 Malaysia OOH and DOOH Market | 2026-2036
Malaysia OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia OOH and DOOH Market Insights
Buyer concentration among fast-moving consumer goods and telecommunications advertisers is hardening as procurement teams consolidate spend with fewer media owners. Big Tree Outdoor Sdn Bhd leverages its dominance across premium highway billboard inventories to sustain rate card premiums. JCDecaux competes through exclusive concession agreements at KLIA and major rail nodes. Wow Media Sdn Bhd differentiates via programmatic trading capabilities that attract data-driven buyers.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display surfaces deployed in public spaces, ranging from static vinyl-wrapped billboards to networked LED screens with real-time content management and audience measurement APIs. The primary commercial purpose is to capture consumer attention during transit, dwell, and purchase-intent moments outside residential environments. Digital displays within the media format dimension command expanding share as programmatic infrastructure matures, while static billboards retain utility in regulatory-constrained zones where LED permits face stricter scrutiny. Interactive and augmented reality formats under advertising type remain nascent but concentrate margin pools through premium creative licensing.
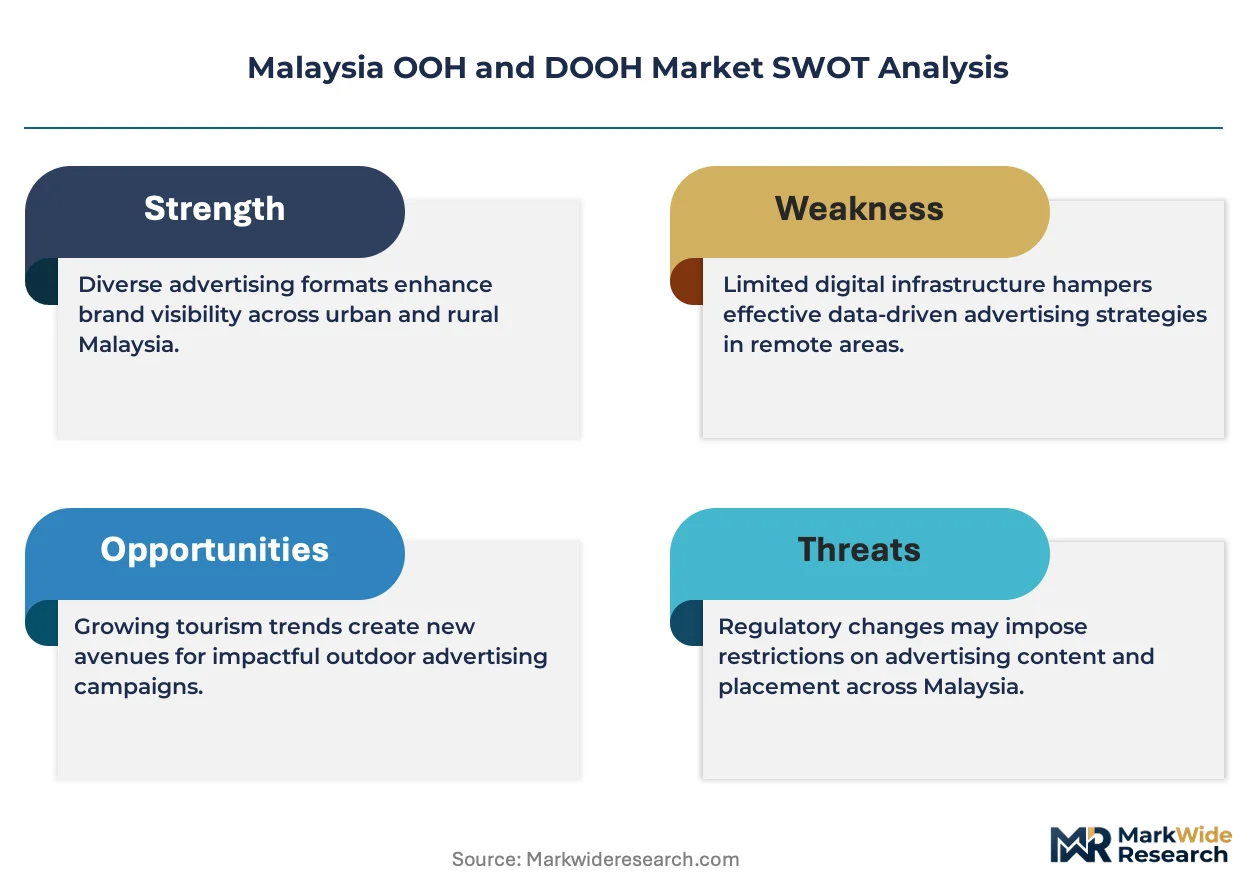
Malaysia's Communications and Multimedia Commission enforces content standards under the CMA 1998 that govern digital screen messaging, while local authority bylaws in Kuala Lumpur City Hall and Petaling Jaya City Council regulate physical structure sizing, illumination limits, and road safety setbacks. These overlapping frameworks elevate compliance costs for network operators while creating barriers against informal competitors. Stakeholders must monitor pending amendments to state-level planning guidelines that could liberalize or further constrain rooftop and transit shelter deployments.
Market Dynamics
Programmatic infrastructure is fragmenting media buying authority away from traditional outdoor specialists toward data science teams inside FMCG and telecom advertisers. This shift compresses planning cycles and rewards inventory with verified audience measurement over location prestige alone.
Growth Catalysts
- Communications and Multimedia Act compliance automation:Malaysia's MCMC content standards are driving investment in centralized creative approval platforms that accelerate campaign deployment timelines for network operators.
- Retail media convergence:Quick-service restaurants and supermarket chains are repurposing in-store digital screens as programmatic inventory, extending DOOH reach into purchase-intent moments.
- Transit corridor densification:Greater Kuala Lumpur's MRT and LRT expansion is creating new premium inventory nodes at interchange stations with extended dwell times.
Market Restraints
- LED permit scarcity:Kuala Lumpur City Hall illumination bylaws and Petaling Jaya setback rules restrict digital screen deployment in high-traffic zones where static vinyl faces lower regulatory barriers.
- Concentrated highway inventory:Premium billboard sites along the North-South Expressway and Federal Route 2 are controlled by a limited pool of concession holders, elevating entry costs for new network operators.
- Power infrastructure fragmentation:Uneven grid reliability across secondary cities forces operators to provision redundant electrical systems, raising opex for networks outside Klang Valley.
Strategic Opportunities
- Penang and Johor Bahru network buildout:Secondary metro areas lack the screen density of Greater Kuala Lumpur, offering first-mover positioning for programmatic-capable operators.
- Retail media API integration:Convergence of DOOH demand-side platforms with supermarket loyalty data enables closed-loop attribution for FMCG campaigns.
- State-level planning guideline liberalization:Pending amendments to Selangor and Penang structure regulations may relax rooftop and transit shelter deployment constraints.
Industry Challenges
- Programmatic trading talent scarcity:The shortage of data engineers familiar with OpenRTB protocols and audience measurement APIs limits network operators' trading desk capabilities.
- Legacy static contract renegotiation:Long-term concession agreements signed before digital conversion clauses require complex amendments to enable LED retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia OOH and DOOH Market |
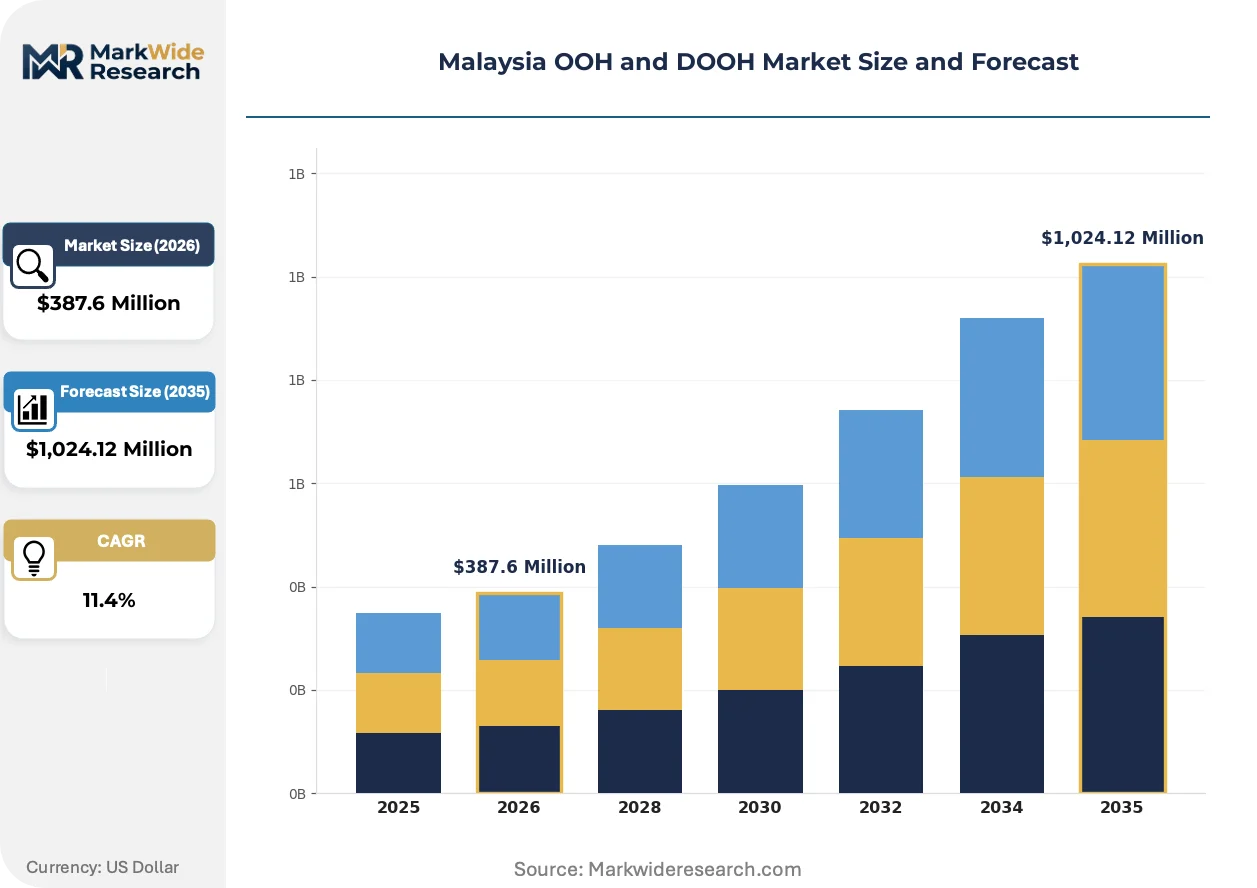
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Format: Billboards, Transit Advertising, Street Furniture, Digital Displays Advertising Type: Static Ads, Digital Ads, Interactive Ads, Augmented Reality Target Audience: Commuters, Tourists, Local Residents, Event Attendees Channel: On-Premise, Off-Premise, Mobile Advertising, Airport Advertising |
| Companies Covered | Big Tree Outdoor Sdn Bhd, PowerScreen Sdn Bhd, Redberry Sdn Bhd, Wow Media Sdn Bhd, Hakuhodo Malaysia Sdn Bhd, Brandavision Sdn Bhd, AsiaPac Net Media Limited, JCDecaux, Sky Blue Media, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia OOH and DOOH Market Trends and Innovations
Real-time audience measurement and automated trading infrastructure are displacing location-based rate cards as the primary currency for inventory valuation. Three developments are compressing the gap between outdoor exposure and digital attribution.
Programmatic DOOH platforms are decentralizing media buying authority from traditional outdoor agencies toward in-house data teams at FMCG and telecom advertisers. Nestlé and Unilever procurement units now execute direct platform integrations, compressing planning cycles from weeks to hours. This shift is fragmenting the buyer base and rewarding inventory with verified impression data over historical location premiums.
Malaysia's MCMC digital content standards under the CMA 1998 are tightening creative pre-approval requirements for networked screens. Operators must now maintain centralized compliance dashboards with audit trails for every creative rotation. Rail transit shelters and airport terminals face the strictest scrutiny, forcing JCDecaux and concessionaires to restructure content management workflows.
Buyer concentration among procurement consolidators is compressing rate card premiums for undifferentiated highway inventory. Telecom advertisers now bundle DOOH with mobile and digital video through unified agency-of-record structures, displacing standalone outdoor specialists. This consolidation is most visible in Greater Kuala Lumpur, where DiGi and Maxis execute programmatic guaranteed deals across multiple inventory sources.
Malaysia OOH and DOOH Market Segmentation
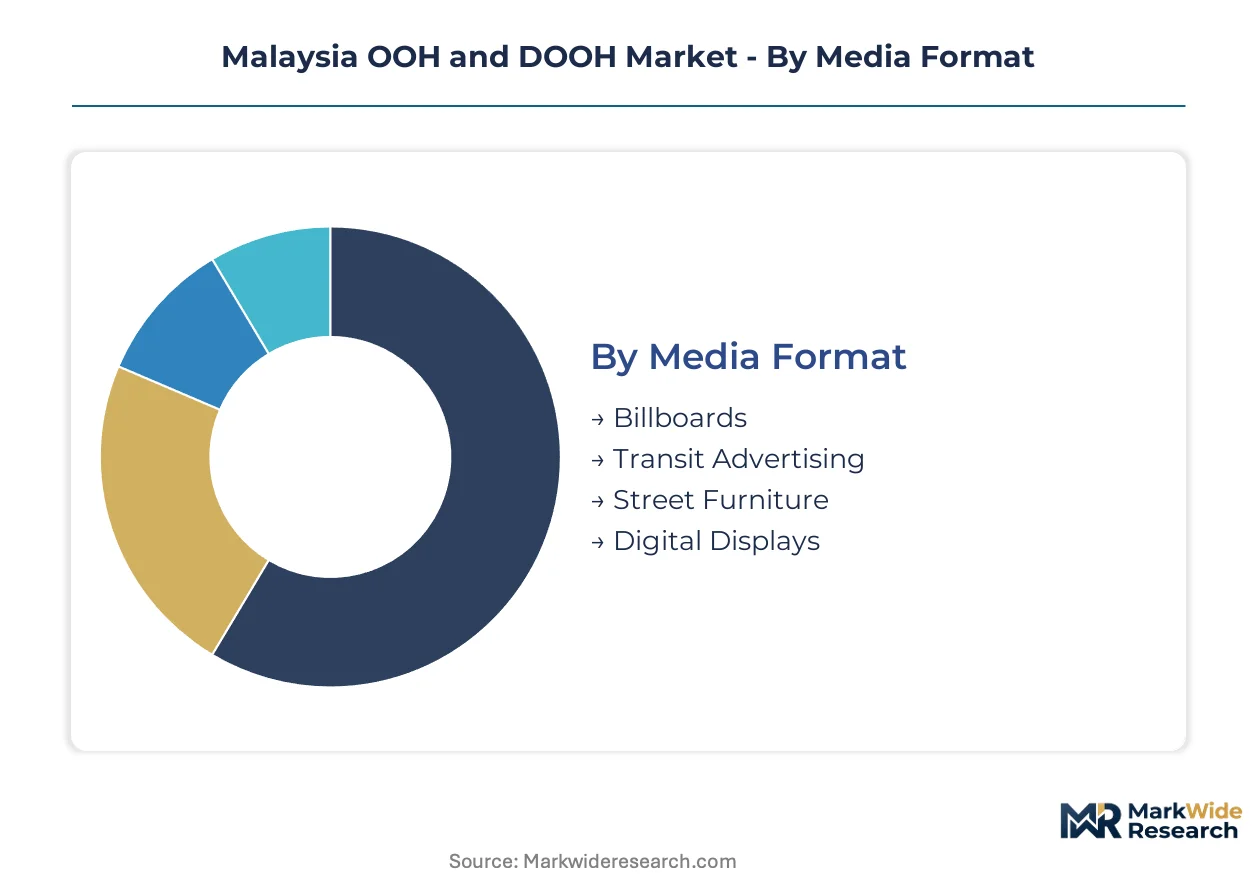
Segmentation in Malaysia's OOH and DOOH market reveals how supply-side constraints and demand fragmentation create divergent margin profiles across inventory types. Understanding these divisions helps operators align capital deployment with regulatory tolerance and advertiser procurement priorities.
Media Format:
Supply concentration across Malaysia's media format landscape tilts heavily toward legacy infrastructure, with digital conversion rates varying sharply by geography and permit availability.
- Billboards:Vinyl-wrapped and LED-enabled structures dominate highway corridors and urban arterials, with premium sites along the North-South Expressway commanding rate premiums. Procurement teams at FMCG advertisers consolidate spend with concession holders controlling Federal Route 2 inventory, squeezing margins for smaller operators.
- Digital Displays:Networked LED screens with real-time content management and audience measurement APIs are displacing static rate cards as the primary trading currency. Kuala Lumpur City Hall illumination bylaws restrict deployment in high-traffic zones, forcing operators toward secondary cities where permit scarcity is less acute.
- Transit Advertising:Rail shelter panels and MRT car cards capture commuter attention during extended dwell times at interchange stations. MRT and LRT expansion in Greater Kuala Lumpur is creating new premium inventory nodes, though concession agreements remain concentrated among established players.
- Street Furniture:Bus shelters, kiosks, and public seating with integrated advertising surfaces occupy pedestrian-dense zones. Petaling Jaya setback rules and road safety requirements elevate compliance costs, limiting network density outside central business districts.
Billboards absorb the bulk of installed capacity; Digital Displays are expanding most quickly.
Advertising Type:
Cost tier differentiation across advertising types separates premium creative licensing from commoditized static placements, with interactive formats capturing disproportionate margin pools despite limited scale.
- Static Ads:Printed vinyl and painted surfaces retain utility in regulatory-constrained zones where LED permits face stricter scrutiny. Long-term concession agreements signed before digital conversion clauses require complex amendments to enable retrofitting, locking operators into legacy revenue streams.
- Digital Ads:Programmatically traded screen inventory compresses planning cycles from weeks to hours, rewarding verified impression data over historical location premiums. Nestlé and Unilever procurement units now execute direct platform integrations, fragmenting the buyer base away from traditional outdoor agencies.
- Interactive Ads:Touch-enabled screens and QR-code triggered content extend dwell time metrics for attribution-hungry advertisers. Deployment concentrates in premium shopping districts and airport terminals where audience engagement justifies creative licensing fees.
- Augmented Reality:Smartphone-synced overlays and location-based AR experiences remain nascent but command the highest CPMs through novelty value and social amplification potential. Technical complexity and creative production costs limit adoption to flagship campaigns by telecommunications advertisers.
Static Ads retain the largest share of committed advertising spend; Augmented Reality is climbing the fastest by CPM growth rate.
Target Audience:
Application-driven segmentation aligns inventory positioning with transit patterns, dwell behaviors, and purchase-intent moments that vary by demographic and trip purpose.
- Commuters:Daily rail and bus passengers exhibit predictable route patterns that enable frequency capping and sequential messaging across network touchpoints. Quick-service restaurants target this segment with daypart-specific creative rotations during morning and evening rush windows.
- Tourists:International arrivals at KLIA and land border crossings respond to multilingual creative and currency conversion triggers. JCDecaux's exclusive concession agreements at airport terminals capture this high-value audience with extended dwell times.
- Local Residents:Neighborhood-level exposure through street furniture and community retail generates repeated impression frequency for brand building. Supermarket chains repurposing in-store digital screens extend DOOH reach into purchase-intent moments for this segment.
- Event Attendees:Concert, sports, and festival crowds enable temporary inventory activation with premium dynamic pricing. Pop-up digital installations around Bukit Jalil National Stadium and KL Convention Centre monetize episodic demand spikes.
Commuters absorb the bulk of network impressions; Event Attendees are gaining share fastest as temporary activation formats proliferate.
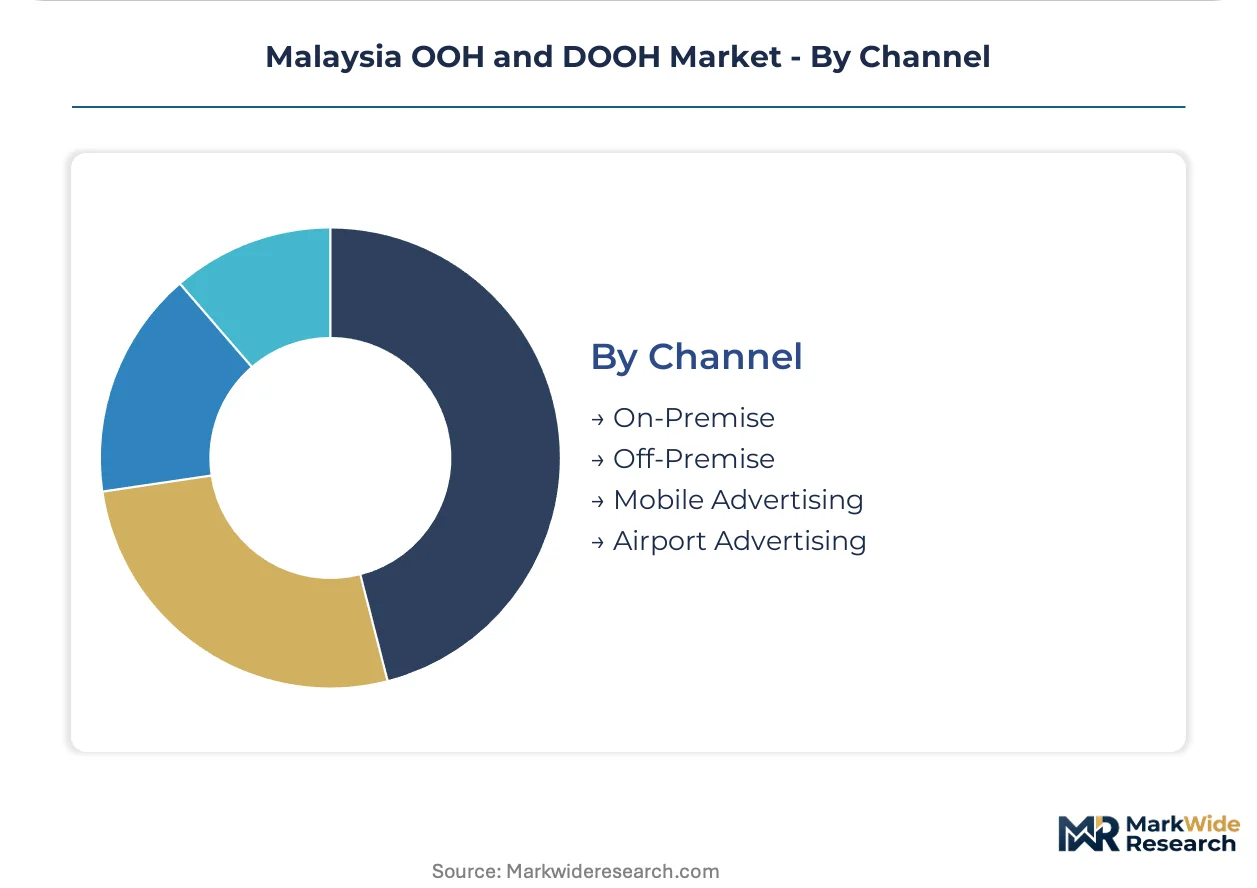
Channel:
Customer type segmentation distinguishes between venue-controlled inventory and programmatically accessible networks, with convergence trends blurring traditional boundaries.
- On-Premise:Retail-owned screens within supermarkets, convenience stores, and quick-service restaurants function as closed networks with proprietary audience data. API integration with DOOH demand-side platforms is enabling programmatic access to this inventory for FMCG campaigns.
- Off-Premise:Public space billboards, transit shelters, and street furniture operate as open networks traded through media owners and programmatic platforms. Rate card premiums for undifferentiated highway inventory are compressing as procurement consolidators bundle DOOH with mobile and digital video.
- Mobile Advertising:Vehicle-wrapped fleets and digital screens mounted on buses, taxis, and delivery vehicles extend reach into residential neighborhoods. Grid reliability fragmentation across secondary cities forces operators to provision redundant electrical systems, raising opex for networks outside Klang Valley.
- Airport Advertising:KLIA and secondary airport terminals offer captive audiences with extended dwell times and high disposable income profiles. MCMC digital content standards under the CMA 1998 impose the strictest creative pre-approval requirements on this channel, forcing concessionaires to maintain centralized compliance dashboards.
Off-Premise retains the largest share of trading volume; On-Premise is expanding most quickly as retail media convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser procurement consolidation in Greater Kuala Lumpur is driving network expansion into secondary metros where screen density remains below saturation thresholds.
Greater Kuala Lumpur
MRT and LRT interchange stations generate premium inventory nodes with extended commuter dwell times. Kuala Lumpur City Hall illumination bylaws restrict LED deployment in high-traffic zones, pushing operators toward static formats on Federal Route 2 corridors. Bukit Bintang and KLCC shopping districts host the densest concentration of programmatic-capable screens.
Selangor
Petaling Jaya setback rules and road safety requirements elevate compliance costs for street furniture networks. Shah Alam and Subang Jaya corridors attract quick-service restaurant advertisers targeting suburban commuter flows. Pending amendments to state-level planning guidelines may relax rooftop deployment constraints.
Penang
George Town heritage zone regulations limit digital screen sizing in UNESCO-protected districts. Bayan Lepas industrial corridors and Gurney Drive commercial strips offer first-mover positioning for programmatic operators. The state's tourism-dependent economy drives demand for multilingual creative at ferry terminals and airport access roads.
Johor Bahru
Cross-border traffic from Singapore sustains premium rate cards at Causeway-linked inventory nodes. Iskandar Malaysia development zones are attracting retail media convergence from supermarket chains expanding in-store digital networks. Grid reliability constraints force operators to provision redundant electrical systems.
Sabah and Sarawak
Kota Kinabalu and Kuching lack the screen density of peninsular metros, creating whitespace for highway billboard operators. State-level infrastructure investment is improving arterial road connectivity to secondary towns. Power infrastructure fragmentation raises operational expenditure for networks outside coastal urban cores.
Malaysia OOH and DOOH Market Competitive Landscape
Established operators occupy the premium highway and transit concession tier; emerging entrants pursue programmatic trading capabilities and retail media integration. Market structure tilts toward consolidation around exclusive concession agreements at KLIA and major rail nodes. Three archetypes dominate: legacy billboard concessionaires with long-term highway contracts, transit shelter specialists with municipal exclusivity, and data-driven platforms trading programmatic inventory. Competitive moves center on LED retrofitting of static assets and API integrations with FMCG demand-side platforms.
Within the legacy concessionaire tier, Big Tree Outdoor Sdn Bhd anchors premium highway inventory positioning across the North-South Expressway. JCDecaux represents the transit-exclusive archetype through its KLIA and rail node agreements. Wow Media Sdn Bhd exemplifies the programmatic-capable operator segment attracting data-science procurement teams from telecommunications advertisers.
| Leading Market Players |
|---|
| Big Tree Outdoor Sdn Bhd |
| PowerScreen Sdn Bhd |
| Redberry Sdn Bhd |
| Wow Media Sdn Bhd |
| Hakuhodo Malaysia Sdn Bhd |
| Brandavision Sdn Bhd |
| AsiaPac Net Media Limited |
| JCDecaux |
| Sky Blue Media |
| Others |
Pricing and Supply Chain Analysis
Programmatic trading infrastructure is compressing rate card premiums while simultaneously concentrating procurement authority among data-science teams at FMCG and telecommunications advertisers. This technological shift elevates inventory with verified audience measurement over historical location prestige, reshaping margin economics across static and digital formats while feeding consolidation pressure on undifferentiated highway inventory.
Pricing Analysis
Volume concentration in static billboards contrasts with margin expansion in programmatic digital displays. Rate cards stratify across premium highway concessions, standard transit shelter networks, and economy-tier street furniture based on permit scarcity and audience verification capabilities. Pricing pressure stems from procurement consolidation as Nestlé and Unilever execute direct platform integrations, compressing margins for undifferentiated inventory. Quick-service restaurant advertisers exhibit highest price sensitivity due to thin operating margins, while telecommunications advertisers prioritize verified impression data over cost efficiency.
Supply Chain Analysis
LED module supply rests on Chinese and South Korean semiconductor manufacturers, with control system software anchored in US and European technology providers. Physical structure fabrication draws from Malaysian steel fabricators and regional aluminum extruders, while content management platforms hinge on cloud infrastructure from hyperscale providers. Single-source vulnerability concentrates in premium LED driver components subject to export licensing fluctuations. Distribution runs through exclusive concession agreements at KLIA and major rail nodes, supplemented by programmatic platform integrations for retail media networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED permit scarcity across Kuala Lumpur City Hall and Petaling Jaya jurisdictions props rate card premiums for compliant digital inventory, constraining supply expansion and sustaining pricing power for established concession holders.
For Market Incumbents: Anchor defensive positioning through exclusive concession renewals at MRT interchange stations and KLIA terminals while accelerating LED retrofitting of static assets before regulatory windows narrow. Vertical integration into centralized compliance dashboards addresses MCMC content standard tightening, while API integrations with FMCG demand-side platforms counter procurement consolidation threats from in-house data teams. For New Entrants and Emerging Players: Retail media API partnerships offer the most penetrable entry vector, enabling programmatic access to supermarket and quick-service restaurant screen networks without competing for scarce outdoor permits. Penang and Johor Bahru secondary metros present whitespace for screen density buildout, particularly in Bayan Lepas industrial corridors and Iskandar Malaysia development zones where established operators lack presence. For Investors and Strategic Acquirers: Exit pathways concentrate in programmatic-capable operators with retail media integration and verified audience measurement infrastructure. Long-term viability favors networks with diversified inventory across transit, retail, and airport channels rather than pure-play highway billboard positions. Regulatory liberalization signals in Selangor and Penang state planning guidelines warrant monitoring as inflection indicators for rooftop and transit shelter deployment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Direct API connections with Nestlé and Unilever procurement systems compress planning cycles and lock in recurring revenue streams. |
| LED Retrofitting of Static Assets | Conversion of Federal Route 2 vinyl billboards before concession renegotiation deadlines captures digital rate premiums under existing permits. |
| Retail Media Network Expansion | Supermarket chain partnerships extend DOOH reach into purchase-intent moments with closed-loop attribution for FMCG campaigns. |
| Compliance Dashboard Investment | Centralized creative approval platforms with MCMC audit trails accelerate deployment timelines for rail and airport inventory. |
| Secondary Metro Buildout | Penang and Johor Bahru screen density expansion captures first-mover positioning ahead of established operator network extension. |
Research Methodology
Independent corroboration across network operator executives, FMCG procurement leads, and municipal planning officers underwrites the qualitative findings on permit scarcity and pricing dynamics. Primary interviews with JCDecaux concessionaires, Big Tree Outdoor site managers, and Wow Media trading desk engineers combined with secondary validation from MCMC regulatory filings, Kuala Lumpur City Hall illumination bylaws, and MRT Corp expansion disclosures. Bottom-up triangulation across individual screen inventory counts and top-down reconciliation against aggregate advertising expenditure estimates anchored market sizing.
Comparable-period anchoring to pre-pandemic transit ridership baselines and post-recovery commuter flow patterns structured the projection horizon. Segmentation modeling spanned media format, advertising type, target audience, and channel dimensions with industry-specific treatment of programmatic trading penetration rates. CAGRs derived from regression analysis of historical concession agreement values, LED permit issuance trends, and retail media API adoption curves across the analysis window.
Caveats apply where MCMC content standard amendments or state-level planning guideline shifts could materially shift the outlook for digital screen deployment economics. Forecasts reflect assumptions on transit corridor densification timelines, retail media convergence velocity, and power infrastructure reliability improvements in secondary cities. A small set of named triggers—regulatory liberalization signals, procurement consolidation acceleration, and programmatic talent pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
In-Flight Advertising Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Out of Home Advertising Market