
 Adtech Market | 2026-2036
Adtech Market Size, Share, and Industry Trends Forecast 2026-2036
Adtech Market Analysis
North American data center expansion for real-time bidding infrastructure is reconfiguring latency benchmarks across the Adtech ecosystem. Alphabet Inc. leverages its search and YouTube inventory to sustain dominance in programmatic video. The Trade Desk anchors independent demand-side platform competition through its Unified ID initiative. Amazon.com, Inc. competes aggressively in retail media, using first-party commerce data to differentiate sponsored product placements from conventional display.
Adtech encompasses software platforms, data management tools, and automated transaction infrastructure that match advertiser demand with publisher supply through algorithmic decisioning, typically executing impressions within 100 milliseconds per bid request. Its primary commercial purpose is to optimize media allocation efficiency and measurable return on ad spend across fragmented digital channels. Programmatic advertising leads transaction volume by automating insertion order workflows, while connected TV inventory within the channel dimension represents the fastest-expanding margin pool as linear budgets migrate to addressable streaming environments. Demand-side platforms concentrate R&D spending on identity resolution, whereas supply-side platforms specialize in yield optimization for publisher inventory.
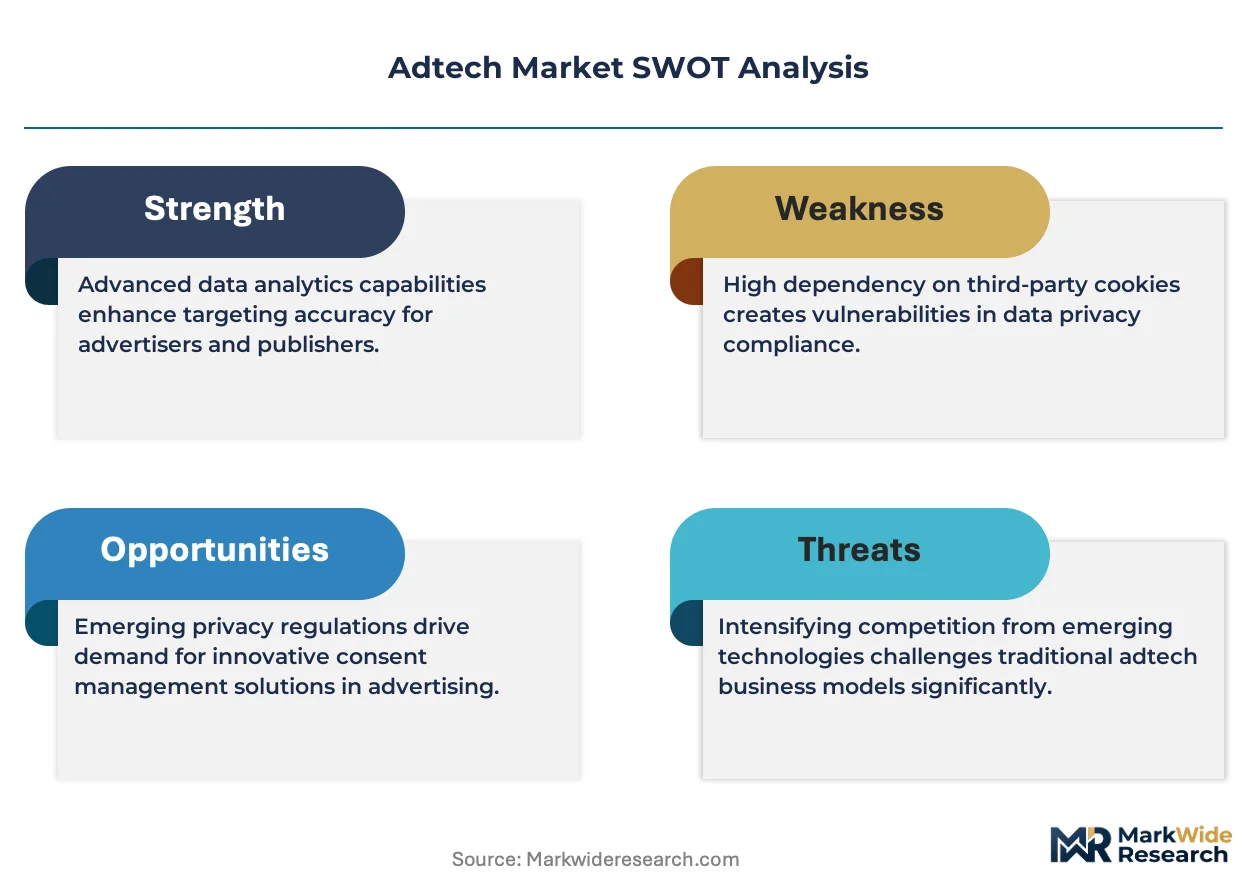
The Federal Trade Commission scrutinizes data broker practices and opaque auction mechanics, while the EU AI Act imposes risk-classification requirements on algorithmic ad targeting systems. California's Consumer Privacy Act and emerging state-level privacy statutes fragment compliance obligations for national ad campaigns. Stakeholders must monitor regulatory fragmentation between federal inaction and state-level privacy enforcement when architecting cross-platform data strategies.
Market Dynamics
Programmatic infrastructure is compressing transaction latency below 100 milliseconds per bid request, forcing demand-side and supply-side platforms to re-architect data center placement and edge computing strategies.
Growth Catalysts
- Connected TV inventory migration:Linear television budgets are shifting to addressable streaming environments, expanding programmatic video transaction volumes.
- GDPR enforcement maturation:EU data governance requirements are standardizing consent management frameworks that reduce compliance friction for cross-border campaigns.
- Retail media networks:E-commerce platforms are deploying first-party commerce data to capture sponsored product placement budgets previously allocated to conventional display.
Market Restraints
- Identity resolution fragmentation:Cookie deprecation has splintered addressability standards across Safari, Chrome, and Firefox implementations.
- Data center energy costs:Real-time bidding infrastructure requires continuous compute scaling, exposing operators to electricity price volatility in Northern Virginia and Frankfurt clusters.
- EU AI Act risk classification:Algorithmic ad targeting systems face mandatory conformity assessments that extend deployment timelines.
Strategic Opportunities
- Privacy-preserving measurement:Clean room architectures and differential privacy techniques are opening attribution capabilities without individual-level data sharing.
- Audio and podcast programmatic:Digital audio inventory remains under-automated relative to video and display, presenting yield optimization white space.
- Commerce media convergence:Retailers are building demand-side platform capabilities that merge closed-loop transaction data with open-web prospecting.
Industry Challenges
- Technical talent scarcity:Specialized engineering for low-latency auction mechanics and machine learning model serving commands premium compensation.
- Legacy system integration:Publisher ad servers and advertiser order management systems require costly API reconciliation with modern programmatic stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adtech Market |
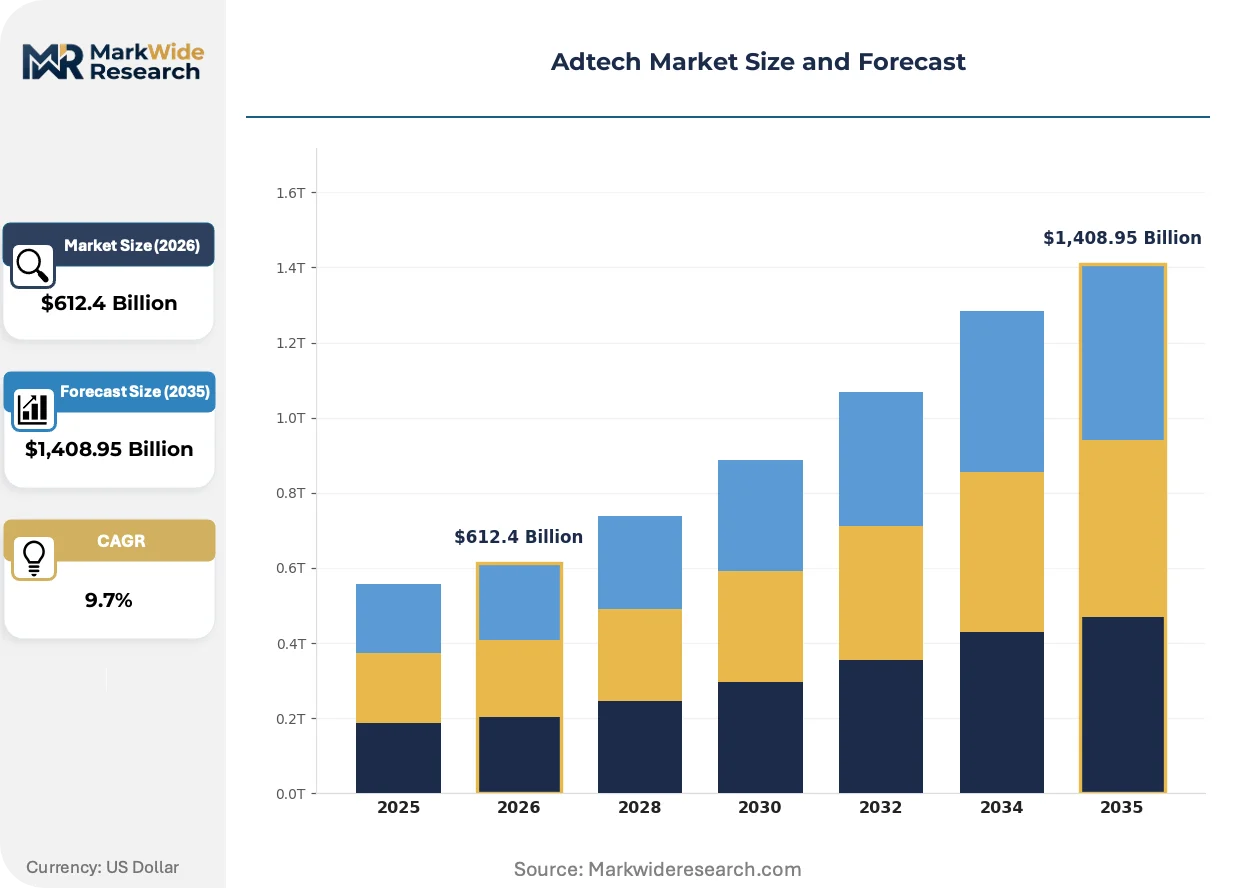
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,408.95 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Demand-Side Platform, Supply-Side Platform, Ad Exchange, Ad Network Technology: Programmatic Advertising, Real-Time Bidding, Display Advertising, Video Advertising End User: Advertising Agencies, Publishers, Brands, E-commerce Platforms Channel: Mobile, Desktop, Social Media, Connected TV |
| Companies Covered | Alphabet Inc., The Trade Desk, Amazon.com, Inc., AppLovin, Magnite, Adobe Inc., Microsoft Corporation, RTB House, System1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adtech Market Emerging Trajectories
Artificial intelligence is compressing decision cycles across the ad transaction stack, from bid prediction to creative optimization, while privacy-preserving technologies reconstitute measurement methodologies.
Server-side header bidding is collapsing client-side latency overhead that previously degraded mobile web user experience. Premium publishers in the United States and United Kingdom are migrating auction logic to cloud infrastructure, reducing page-load friction that had suppressed programmatic CPMs. This compression is reallocating technical resources from latency mitigation toward yield intelligence and audience segmentation.
The EU AI Act imposes risk-tiered obligations on algorithmic systems used for behavioral profiling and ad targeting. High-risk classification triggers mandatory conformity assessments, documentation requirements, and human oversight protocols that extend vendor procurement cycles. Demand-side platforms serving EU campaigns are restructuring product roadmaps to segregate AI-driven features by risk tier.
Buyer concentration among retail media networks is restructuring agency-client relationships and media planning workflows. Brands are establishing direct commercial terms with Amazon, Walmart, and Target that bypass traditional agency trading desk intermediation. This disintermediation is most pronounced in consumer packaged goods verticals, where closed-loop sales attribution commands budget allocation priority over reach-based planning.
Adtech Market Segmentation
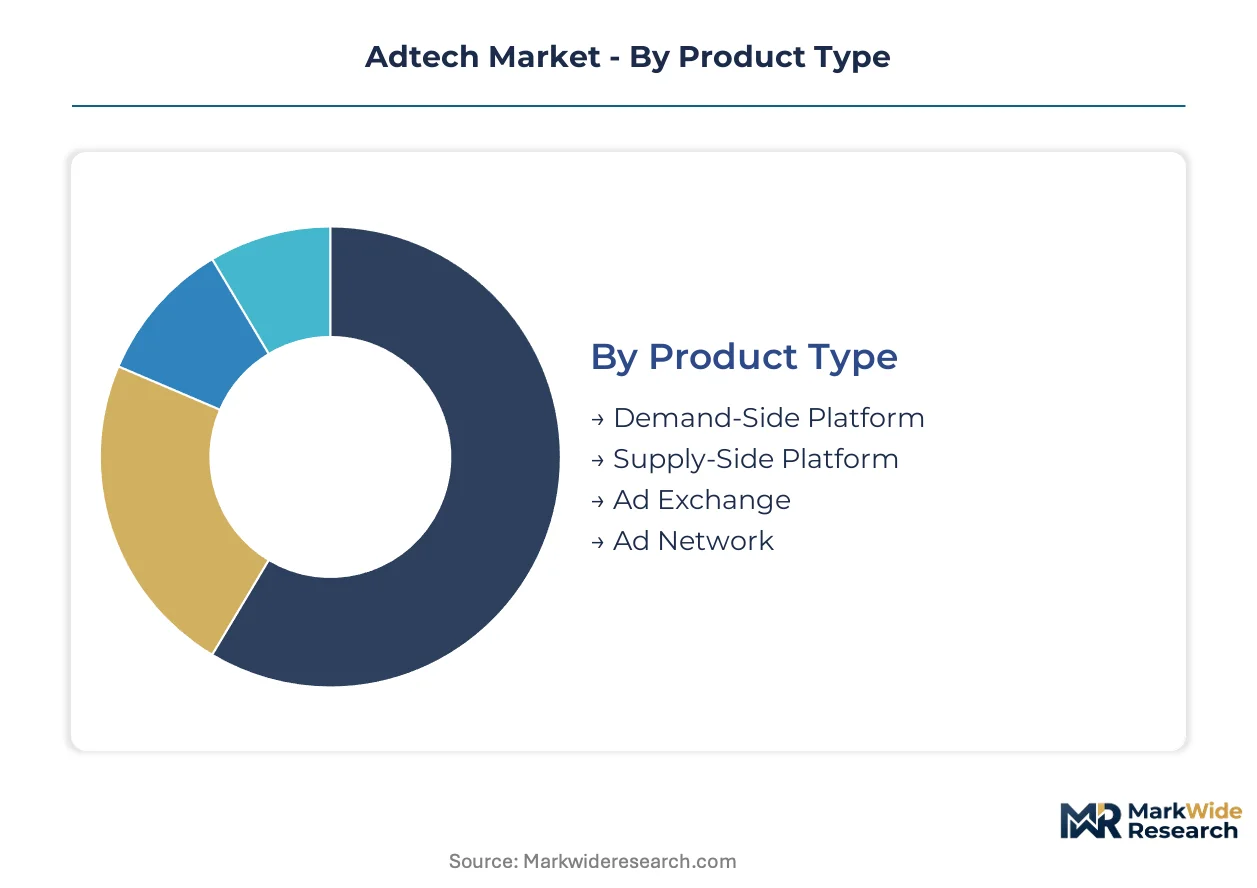
Adtech segmentation reveals how infrastructure layers, transaction mechanisms, and inventory channels allocate budget flows across the programmatic ecosystem. Platform specialization and channel fragmentation create distinct margin pools that vendors target with differentiated technical architectures.
Product Type:
Platform architectures span the full advertiser-to-publisher transaction chain, with each layer commanding different data processing requirements and revenue models.
- Demand-Side Platform:Software interfaces enabling advertisers and agencies to automate media buying across multiple inventory sources through algorithmic bid optimization. Advertiser consolidation around unified buying workflows concentrates R&D investment in identity resolution and cross-channel frequency management.
- Supply-Side Platform:Publisher-facing technology that aggregates inventory, manages yield optimization, and routes impressions to auction infrastructure. Header bidding proliferation and server-side migration are accelerating platform consolidation among premium publishers seeking latency reduction.
- Ad Exchange:Neutral auction infrastructure matching buy-side bid requests with sell-side inventory through real-time price discovery. Open exchange liquidity pools face competitive pressure from private marketplace alternatives offering inventory exclusivity.
- Ad Network:Curated inventory aggregation historically bundling remnant publisher supply with advertiser demand through direct sales relationships. Network models are pivoting toward vertical specialization and first-party data partnerships to differentiate against programmatic infrastructure.
The dominant share belongs to Demand-Side Platforms, while Supply-Side Platforms are closing the gap fastest through header bidding consolidation and cloud infrastructure migration.
Technology:
Transaction automation intensity varies by technical approach, with latency requirements and creative formats shaping infrastructure investment priorities.
- Programmatic Advertising:Automated media buying workflows replacing manual insertion orders through algorithmic decisioning and API-based campaign management. E-commerce platform budget migration toward retail media networks is expanding programmatic transaction volumes beyond traditional display.
- Real-Time Bidding:Impression-level auction mechanics executing bid requests within sub-100-millisecond windows through distributed data center infrastructure. Edge computing deployment and server-side header bidding are compressing latency benchmarks across Northern Virginia and Frankfurt clusters.
- Display Advertising:Static and rich media creative formats served through web and mobile browser environments. Cookie deprecation and Safari ITP restrictions are forcing identity resolution innovation toward probabilistic matching and clean room architectures.
- Video Advertising:Streaming and in-stream creative formats commanding premium CPMs through completion rate optimization and viewability verification. Connected TV inventory within this segment is expanding most quickly as linear television budgets migrate to addressable streaming environments.
Programmatic Advertising holds the largest deployment base, though Video Advertising is gaining share fastest through CTV inventory premiumization.
End User:
Customer archetypes exhibit divergent technical sophistication, with direct brand investment reshaping traditional agency intermediary roles.
- Advertising Agencies:Trading desks and media planning organizations managing cross-channel budget allocation on behalf of brand clients. Agency holding companies are consolidating technology licenses to defend margin position against in-housing trends.
- Publishers:Content owners monetizing audience attention through direct sales, programmatic pipes, and subscription hybrid models. Premium publishers are building first-party data assets to reduce dependency on third-party identity graphs.
- Brands:Direct advertisers establishing in-house programmatic capabilities and direct commercial terms with retail media networks. Consumer packaged goods verticals are leading disintermediation of traditional agency trading desk relationships.
- E-commerce Platforms:Retailers deploying closed-loop attribution infrastructure to capture sponsored product placement budgets. Amazon, Walmart, and Target are building demand-side platform capabilities merging commerce data with open-web prospecting.
Advertising Agencies retain the largest serviceable base, yet E-commerce Platforms are climbing the fastest through retail media network budget capture.
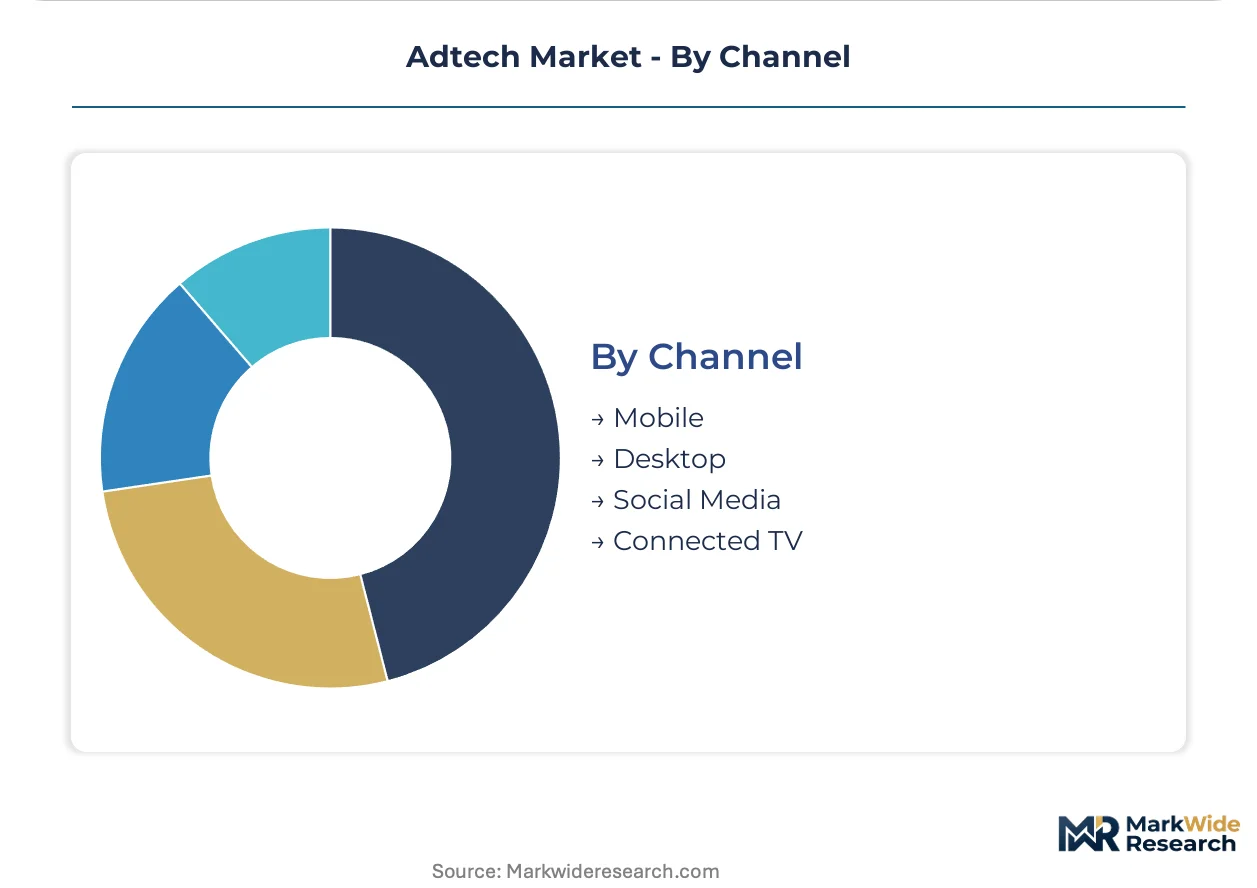
Channel:
Device and environment fragmentation creates distinct addressability challenges, with inventory scarcity driving pricing stratification.
- Mobile:Smartphone and tablet inventory characterized by in-app and mobile web environments with identifier deprecation challenges. Apple's ATT framework and Google's Privacy Sandbox are forcing measurement innovation toward aggregated attribution.
- Desktop:Traditional web browser inventory with mature programmatic infrastructure but declining session duration relative to mobile. Cookie-based targeting persistence in Chrome sustains addressability advantages over Safari and Firefox implementations.
- Social Media:Walled-garden environments with native first-party data and self-service advertising interfaces. Platform concentration among Meta, TikTok, and Snap is capturing direct-response budgets through closed-loop conversion optimization.
- Connected TV:Streaming television inventory delivered through smart TVs, streaming devices, and set-top boxes with addressable advertising capabilities. Linear budget migration and scarce premium inventory are commanding the steepest CPM expansion trajectory.
Mobile maintains the broadest reach footprint, while Connected TV is gaining share fastest through linear television budget displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center clusters in Northern Virginia and Frankfurt anchor real-time bidding infrastructure, while retail media networks concentrate advertising technology investment in specific metropolitan zones. Regulatory divergence between jurisdictions is fragmenting compliance architectures for cross-border campaigns.
United States
Connected TV inventory migration and retail media network expansion drive programmatic budget concentration. The Federal Trade Commission scrutinizes data broker practices and opaque auction mechanics through enforcement actions. Northern Virginia's data center corridor processes sub-100-millisecond bid requests for domestic streaming inventory.
Germany
GDPR enforcement maturation and consent management standardization reduce compliance friction for cross-border campaigns. The EU AI Act imposes risk-classification requirements on algorithmic ad targeting systems deployed in the federal territory. Frankfurt's financial and technology hub hosts edge computing infrastructure serving Central European bid volumes.
United Kingdom
Post-Brexit data adequacy arrangements and independent Information Commissioner's Office enforcement reshape cross-border data flows. The Digital Markets, Competition and Consumers Act introduces new platform accountability requirements. London's advertising technology cluster concentrates demand-side platform R&D and publisher yield optimization specialists.
China
E-commerce platform advertising and short-form video inventory expansion accelerate programmatic infrastructure deployment. The Personal Information Protection Law and Data Security Law impose localization and cross-border transfer restrictions. Shenzhen and Hangzhou technology corridors develop closed-loop attribution systems for domestic retail media networks.
India
Mobile-first digital consumption and over-the-top streaming growth expand addressable inventory pools. The Digital Personal Data Protection Act establishes consent frameworks for behavioral advertising. Mumbai and Bangalore advertising technology clusters focus on vernacular language creative optimization and regional publisher monetization.
Adtech Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in identity resolution and yield optimization. The vendor base separates between walled-garden operators with captive inventory and independent intermediaries competing on cross-platform neutrality. Three archetypes dominate: search and social conglomerates with first-party data moats, independent demand-side platforms betting on unified identity standards, and retail media networks leveraging closed-loop commerce data. Consolidation pressure concentrates through header bidding proliferation and server-side infrastructure migration, while strategic partnerships between publishers and clean room providers accelerate.
Within the independent platform tier, The Trade Desk and Magnite exemplify demand-side and supply-side specialization respectively, each anchoring distinct positions in the programmatic transaction chain. Alphabet Inc. represents the integrated conglomerate archetype, combining search inventory dominance with video platform scale. These three entities illustrate how competitive positioning diverges between neutrality-focused intermediaries and inventory-captive operators.
| Leading Market Players |
|---|
| Alphabet Inc. |
| The Trade Desk |
| Amazon.com, Inc. |
| AppLovin |
| Magnite |
| Adobe Inc. |
| Microsoft Corporation |
| RTB House |
| System1 |
| Others |
Supply Flow & Price Mechanics
EU AI Act risk classification for algorithmic ad targeting systems determines both the premium commanded by compliant infrastructure tiers and the geographic clustering of real-time bidding data centers. Pricing tier spreads widen where conformity assessment burdens extend deployment timelines, while supply chain shape follows regulatory chokepoints rather than pure latency optimization.
Pricing Analysis
GDPR enforcement maturation dictates the pricing tier structure across consent management platforms and clean room architectures. Three-tier pricing separates enterprise-grade compliance bundles from mid-market SaaS tiers and basic consent banner tools. Price differentiation rests on certification depth and cross-border data governance capabilities. Cost compression in the mid-tier is intensifying because retail media networks are absorbing budgets previously allocated to open-web display. Brand direct advertisers exhibit the highest price sensitivity, whereas agency holding companies prioritize interoperability over per-seat licensing costs.
Supply Chain Analysis
Export-control restrictions on advanced AI accelerators and cloud infrastructure limit data center expansion in certain jurisdictions, reshaping where real-time bidding compute clusters deploy. Supply concentrates in the United States, Germany, and Ireland for primary auction infrastructure, with edge nodes extending into India and Singapore for latency-sensitive mobile inventory. Raw material dependencies include specialized GPUs for machine learning inference, subsea fiber capacity for cross-border bid routing, and renewable power purchase agreements for carbon-neutral compute claims. Single-source vulnerability sits with NVIDIA's dominance in training-grade silicon. Distribution runs through hyperscaler marketplaces and direct enterprise licensing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adtech platform economics are approaching an interoperability inflection as Unified ID and Privacy Sandbox implementations force reconciliation between competing identity graphs. The shift from cookie-based to authenticated targeting is restructuring which intermediaries capture margin.
For Market Incumbents: Build data moats around first-party commerce relationships and closed-loop attribution capabilities. Consolidate header bidding infrastructure through server-side migration to reduce client-side latency overhead. The Trade Desk's Unified ID initiative and Amazon's retail media network represent the primary competitive threats to open-web neutrality. Vertical integration into clean room technology and differential privacy tooling offers defensive positioning against regulatory fragmentation.
For New Entrants and Emerging Players: Pursue audio and podcast programmatic inventory as the most penetrable white space, given under-automation relative to video and display. Target mid-market publishers in India and Southeast Asia where vernacular language creative optimization remains underserved. Commerce media convergence presents a go-to-market angle through retail data partnerships that bypass established demand-side platform intermediation.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by elevating compliance infrastructure from cost center to competitive differentiator. Long-term viability favors platforms with demonstrated conformity assessment completion and human-in-the-loop oversight architectures. Acquisition target archetypes include specialized identity resolution vendors and yield optimization engineers serving premium publisher segments. The signal to watch is FTC enforcement intensity around data broker transparency and auction mechanics disclosure.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Header Bidding Migration | Reduces mobile web latency for publishers competing with walled-garden environments. |
| Clean Room Architecture Deployment | Enables privacy-preserving measurement without individual-level data sharing across parties. |
| Retail Media Network Expansion | Captures closed-loop attribution budgets from consumer packaged goods advertisers. |
| Unified ID Interoperability Investment | Secures addressability alternatives as Chrome deprecates third-party cookies. |
| Edge Computing Infrastructure Buildout | Compresses sub-100-millisecond bid request processing for streaming inventory. |
Methodological Framework
Desk research of SEC filings, hyperscaler capex disclosures, and App Annie mobile advertising intelligence preceded structured interviews with demand-side platform product managers, supply-side platform yield engineers, agency trading desk directors, and retail media network monetization leads. Primary fieldwork combined with secondary validation across regulatory filings from the FTC, EU AI Act implementation guidance, and state-level privacy statute tracking. Bottom-up sizing of programmatic transaction volumes triangulated against top-down advertising spend allocation surveys.
Assumptions held constant include prevailing regulatory enforcement intensity, continued linear television budget migration to connected TV, and stable identity resolution fragmentation across browser implementations. The analytical framework modeled segmentation across platform type, transaction automation intensity, inventory channel, and end-user archetype throughout the forecast period. CAGRs derived from regression analysis of historical programmatic spend growth against macroeconomic indicators and technology adoption curves. Industry-specific inputs included real-time bidding volume data and retail media network revenue disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by retail media networks to build demand-side platform capabilities would shift outcomes. Material shifts in GDPR enforcement intensity or EU AI Act risk-tier reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market