
 Online Action Games Market | 2026-2036
Online Action Games Market Size, Share, and Industry Trends Forecast 2026-2036
Online Action Games Market Analytics
Multi-source engine licensing is realigning how studios build online action games. Epic Games leverages its Unreal Engine ecosystem to anchor development pipelines across third-party studios. Tencent sustains dominance through captive control of Riot Games and Supercell portfolio assets. Sony Interactive Entertainment competes by vertically integrating hardware-software-live service stacks around its PlayStation Network infrastructure.
Online action games constitute real-time interactive entertainment software requiring sub-50 millisecond latency architecture, persistent server meshes, and anti-cheat kernel-level integration for competitive integrity. These systems monetize through battle pass cycles, cosmetic microtransactions, and sponsored tournament prize pools rather than unit sales. Battle Royale formats now occupy the largest revenue pool, while Cloud Gaming represents the fastest-expanding platform segment as 5G edge networks reduce input lag. First-Person Shooter titles concentrate the highest professional esports viewership, creating premium advertising inventory that Mobile platforms increasingly capture through thumb-optimized control schemes.
FDA content guidelines for neurological impact disclosures, China's MIIT anti-addiction mandates, and the EU Digital Services Act's algorithmic transparency requirements collectively reshape product design cycles and regional go-to-market sequencing. South Korea's GRAC rating board imposes additional server location rules for youth-accessible titles, directly affecting data center capex decisions. Stakeholders must monitor how fragmentation between national age-verification standards alters cross-border tournament eligibility and in-game purchase tax treatment.
Market Dynamics
Cloud gaming infrastructure is fragmenting platform control, forcing publishers to rebuild latency-dependent netcode for edge-distributed architectures while maintaining anti-cheat integrity across heterogeneous server environments.
Growth Catalysts
- 5G Edge Deployment:Telecom carriers in Southeast Asia are financing mobile esports tournaments to drive data consumption, creating captive distribution channels for competitive titles.
- MIIT Anti-Addiction Framework:China's youth gaming restrictions are accelerating adult-oriented monetization redesigns that export to other markets with aging player bases.
- Kernel-Level Anti-Cheat Mandates:Tournament organizers now require hardware-trusted execution environments, elevating technical barriers that favor established engine licensees.
Market Restraints
- Server Mesh Capex Concentration:Persistent world architectures require hyperscale data center commitments that concentrate in Northern Virginia, Frankfurt, and Singapore, creating single-point-of-failure risk.
- Input Latency Physics:Sub-50 millisecond competitive thresholds exclude satellite and rural fiber deployments, permanently capping addressable audience in low-infrastructure geographies.
- GRAC Server Localization:South Korea's rating board mandates domestic data residency for youth-accessible titles, duplicating infrastructure costs without proportional revenue offset.
Strategic Opportunities
- Brazil-Mexico Demand Pockets:Latin America's competitive shooter audience is expanding faster than localized server supply, creating first-mover advantage for Portuguese-Spanish hybrid content.
- Battle Pass Convergence:Cosmetic microtransaction systems are merging with streaming platform subscriptions, enabling cross-media monetization through character skin licensing.
- FDA Neurological Disclosure Pathway:Voluntary content labeling for sensory impact could preempt regulatory friction in North American markets while differentiating premium titles.
Industry Challenges
- Netcode Engineering Scarcity:Real-time multiplayer systems programming expertise concentrates in legacy studio clusters, constraining indie development of competitive-grade titles.
- Cross-Border Tax Treatment:In-game purchase VAT harmonization remains unresolved between EU member states, complicating tournament prize pool structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Action Games Market |
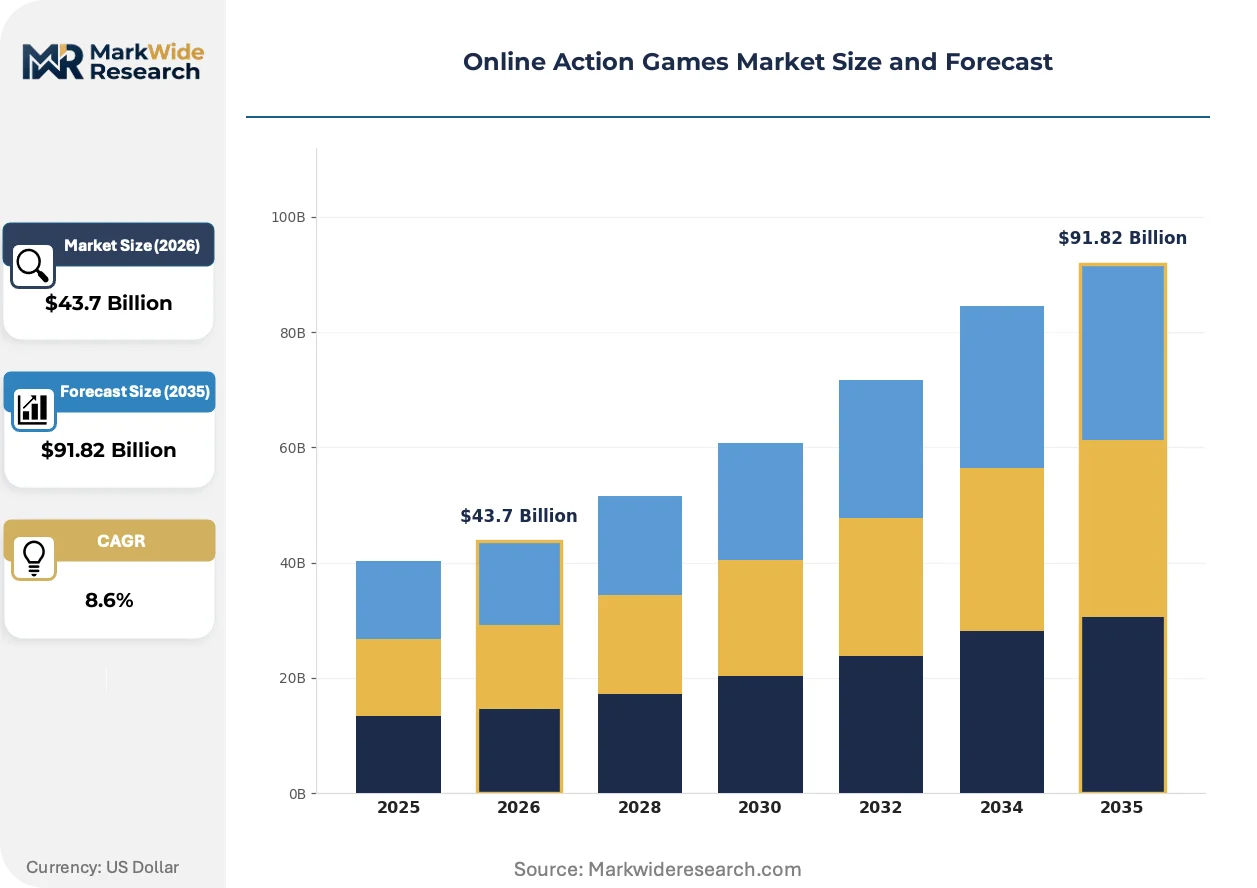
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Battle Royale, First-Person Shooter, Multiplayer Online Battle Arena, Platformer Game Mode: Co-op, Competitive, Solo, Team-Based Platform: PC, Console, Mobile, Cloud Gaming User Demographic: Casual Gamers, Professional Gamers, Teens, Adults |
| Companies Covered | Tencent, Sony Interactive Entertainment, Activision Blizzard, Electronic Arts, Ubisoft Entertainment, Nintendo, Capcom, Konami, Epic Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Action Games Market Evolving Landscape
Interactive entertainment software is reconfiguring around three simultaneous shifts: infrastructure disaggregation, algorithmic transparency mandates, and consumption pattern fragmentation across device types.
Procedural animation middleware is modularizing character rigging pipelines, allowing smaller studios to license motion-matching systems previously captive to AAA internal tools. Indie developers in Eastern Europe and Southeast Asia are adopting these systems fastest, compressing the competitive gap between mid-tier and premium production values. Asset store distribution is modularizing what was once proprietary technical art capability.
EU Digital Services Act algorithmic transparency requirements are forcing recommendation engine disclosures for youth-targeted content, directly affecting matchmaking system documentation. Publishers must now audit competitive ranking algorithms for explainability, adding compliance layers to live service operations. Mobile battle royale titles face the steepest retrofit costs due to opaque engagement-optimization systems.
Thumb-optimized control schemes are capturing professional esports viewership previously concentrated on mouse-keyboard inputs, rotating advertising inventory value toward mobile-first tournament broadcasts. Sponsors are reallocating spend from PC-centric leagues to thumb-optimized mobile competitions in India and Southeast Asia. This behavioral pivot is compressing hardware sponsorship cycles while expanding cosmetic microtransaction addressable markets.
Online Action Games Market Segmentation
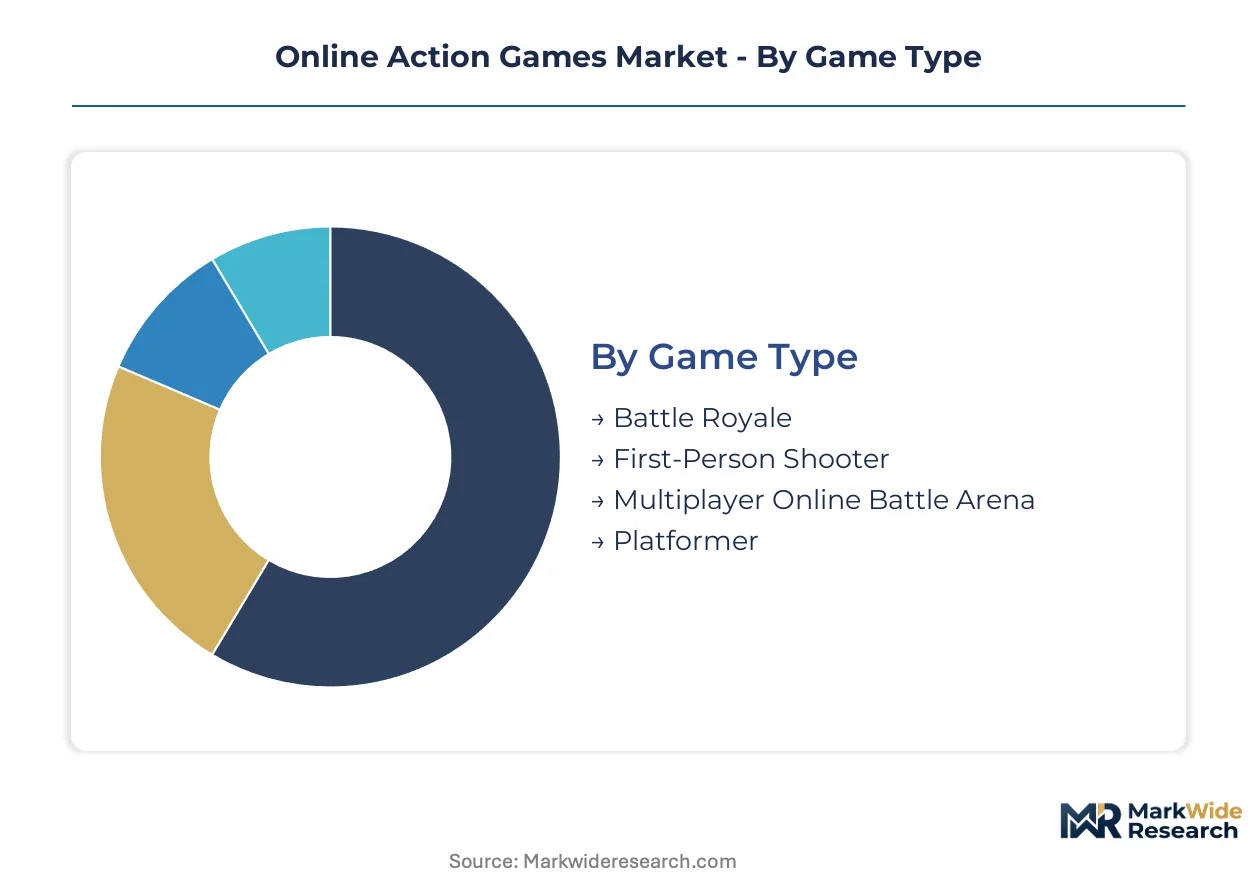
Online action games require distinct technical architectures, monetization systems, and compliance frameworks across each segment. Publishers sequence regional launches based on how specific game types and platforms intersect with local regulatory burdens.
Game Type:
Battle Royale titles face the heaviest certification load from China's MIIT anti-addiction framework and South Korea's GRAC rating protocols, while First-Person Shooters trigger FDA neurological disclosure discussions in North American markets.
- Battle Royale:Persistent server meshes support 100-player concurrent sessions with shrinking play zones. Demand concentrates in Brazil and Mexico where localized server supply lags audience growth, constrained by hyperscale data center capex requirements in Northern Virginia and Frankfurt clusters.
- First-Person Shooter:Sub-50 millisecond latency thresholds demand kernel-level anti-cheat integration and hardware-trusted execution environments. Professional esports viewership concentrates here, driving premium advertising inventory that sponsors now redirect toward mobile-optimized broadcasts in India and Southeast Asia.
- Multiplayer Online Battle Arena:Thumb-optimized control schemes are displacing mouse-keyboard inputs for this format in mobile-first markets.
- Platformer:Lower server infrastructure requirements attract indie developers using procedural animation middleware from Eastern European asset stores.
Battle Royale sits at the top of the volume ranking, with First-Person Shooter climbing the fastest.
Game Mode:
Cost tier separation distinguishes segments: Competitive modes demand the highest ongoing netcode engineering investment, while Solo modes minimize persistent server mesh commitments.
- Competitive:Ranked matchmaking systems now require algorithmic transparency documentation under EU Digital Services Act mandates, adding compliance layers to live service operations.
- Team-Based:Telecom carriers in Southeast Asia finance tournaments for this mode to drive 5G data consumption, creating captive distribution channels.
- Co-op:Adult-oriented monetization redesigns from China's MIIT restrictions are exporting to aging player bases in other markets.
- Solo:Cloud gaming edge architectures reduce input lag sufficiently for single-player progression systems without competitive integrity requirements.
Team-Based captures the largest addressable audience, with Competitive expanding most quickly.
Platform:
Application context determines infrastructure strategy: mobile platforms prioritize thumb-optimized control schemes and GRAC server localization, while PC platforms concentrate netcode engineering expertise.
- Mobile:5G edge networks are reducing input lag below competitive thresholds, rotating advertising inventory value toward thumb-optimized tournament broadcasts. This platform faces steepest EU Digital Services Act retrofit costs due to opaque engagement-optimization systems.
- Cloud Gaming:Edge-distributed architectures fragment platform control, forcing publishers to rebuild latency-dependent netcode while maintaining anti-cheat integrity across heterogeneous server environments.
- PC:Mouse-keyboard inputs retain professional esports concentration in legacy markets, though sponsor spend is compressing.
- Console:Sony Interactive Entertainment vertically integrates hardware-software-live service stacks around PlayStation Network infrastructure.
Mobile sits at the top of the volume ranking, with Cloud Gaming gaining share fastest.
User Demographic:
Customer type dictates regulatory exposure and monetization system design, with Teens triggering the most stringent multi-jurisdictional compliance requirements.
- Adults:China's MIIT youth restrictions accelerated monetization redesigns targeting this segment, with battle pass cycles and cosmetic microtransactions replacing unit sales. Adult-oriented systems now export to other markets with aging player bases.
- Professional Gamers:Tournament organizers mandate hardware-trusted execution environments and kernel-level anti-cheat, elevating technical barriers that favor established engine licensees.
- Teens:South Korea's GRAC rating board imposes domestic data residency rules, duplicating infrastructure costs without proportional revenue offset.
- Casual Gamers:Procedural animation middleware from asset stores enables mid-tier studios to compress production value gaps.
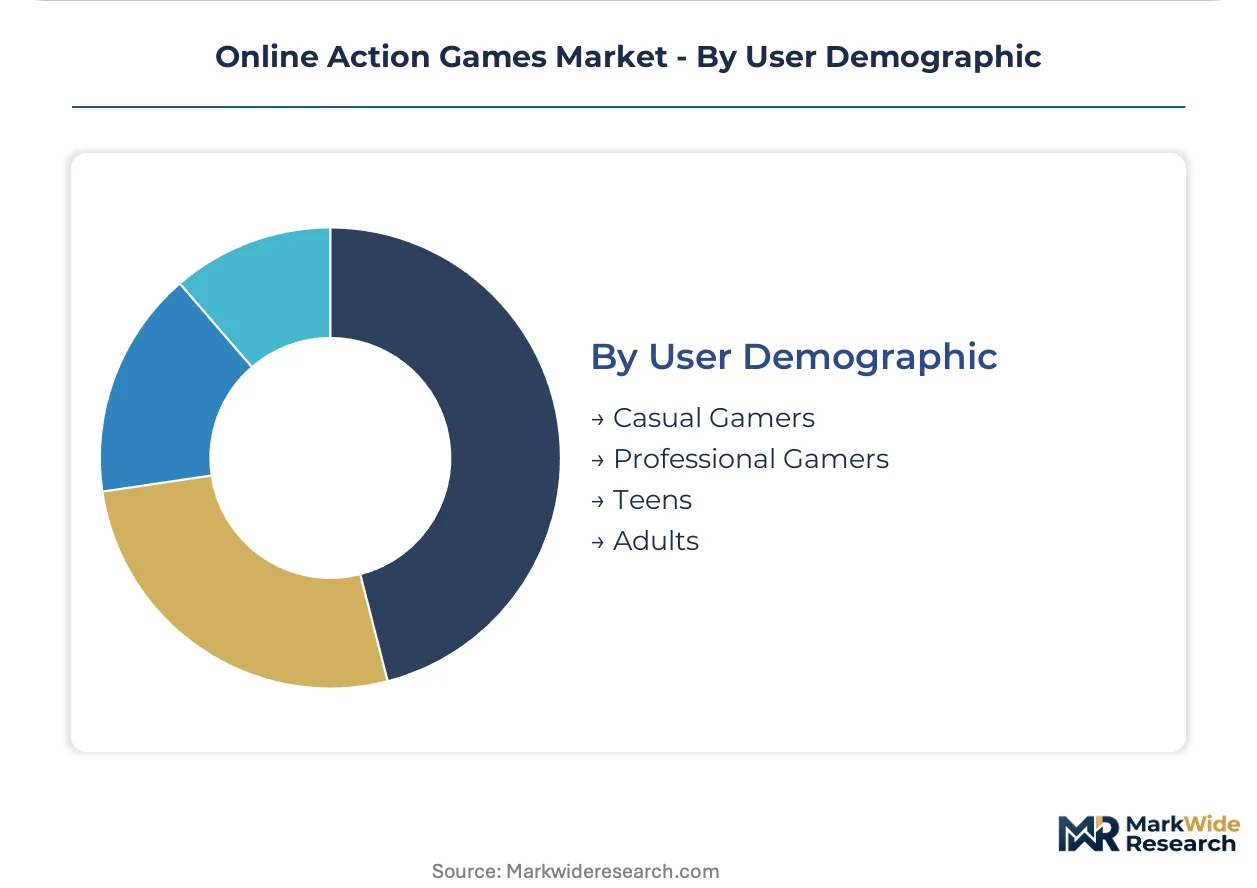
Adults sit at the top of the volume ranking, with Professional Gamers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Publishers arbitrage compliance costs by routing live service operations through jurisdictions with lighter youth gaming restrictions, while tournament infrastructure concentrates where 5G edge deployment outpaces regulatory burden.
United States
FDA neurological disclosure discussions are reshaping content labeling for competitive shooters with high sensory impact. Tournament organizers in Los Angeles and Austin now mandate hardware-trusted execution environments for professional leagues. Northern Virginia's hyperscale data center cluster hosts the majority of persistent server meshes for cross-border Battle Royale sessions.
China
MIIT anti-addiction mandates force publishers to redesign monetization systems around adult player bases. Beijing and Shanghai studios accelerate export of these adult-oriented systems to aging demographics in Japan and South Korea. The Yangtze River Delta concentration of engine licensees dominates Unreal and Unity middleware customization for compliance-heavy markets.
Brazil
Portuguese-Spanish hybrid content demand for competitive shooters outpaces localized server supply in São Paulo and Rio de Janeiro state clusters. Telecom carriers finance mobile esports tournaments to drive 5G data consumption in these metros. The gap between audience growth and hyperscale infrastructure investment creates first-mover positioning for publishers with edge-distributed architectures.
South Korea
GRAC rating board mandates duplicate infrastructure costs through domestic data residency rules for youth-accessible titles. Seoul Capital Area studios concentrate kernel-level anti-cheat engineering expertise. Busan-Ulsan carriers experiment with sub-20 millisecond edge nodes for mobile esports broadcasts targeting professional gamer demographics.
Germany
EU Digital Services Act algorithmic transparency requirements force matchmaking system documentation for youth-targeted competitive modes. Frankfurt's data center concentration anchors persistent world architectures for Central European audiences. Bavaria-based middleware vendors supply procedural animation systems to mid-tier studios compressing production value gaps.
Online Action Games Market Competitive Landscape
Established producers occupy the standard tier through captive engine ecosystems and hardware-software integration; emerging entrants pursue cloud-native architectures and regional compliance specialization. The market structures around three archetypes: vertically integrated platform holders, multi-studio portfolio aggregators, and engine-licensing middleware anchors. Dominant competitive moves include strategic partnerships with telecom carriers for 5G edge distribution and portfolio diversification into adult-oriented monetization systems.
Within the vertically integrated tier, Sony Interactive Entertainment and Nintendo exemplify hardware-software-live service stack control. Tencent occupies a position as the multi-studio aggregator archetype through captive holdings. Epic Games anchors the engine-licensing vector, leveraging Unreal ecosystem penetration across third-party development pipelines.
| Leading Market Players |
|---|
| Tencent |
| Sony Interactive Entertainment |
| Activision Blizzard |
| Electronic Arts |
| Ubisoft Entertainment |
| Nintendo |
| Capcom |
| Konami |
| Epic Games |
| Others |
Value Network & Pricing Analysis
Hyperscale data center capex in Northern Virginia, Frankfurt, and Singapore clusters flows downstream through tiered licensing structures that stratify engine access costs across premium, standard, and economy developer tiers. Publishers absorb these infrastructure commitments through battle pass monetization cycles that shift unit-sale dependency toward recurring cosmetic microtransaction revenue.
Pricing Analysis
Input-cost pass-through from kernel-level anti-cheat engineering and persistent server mesh operations stratifies pricing across premium, standard, and economy licensing tiers. Price differentiation rests on certification grade for MIIT compliance and hardware-trusted execution environment integration. Pricing pressure intensifies as cloud gaming edge deployment fragments platform control and forces netcode rebuilds. Indie developers exhibit highest price sensitivity due to concentrated netcode engineering scarcity, while vertically integrated platform holders absorb cost compression through captive hardware-software stacks.
Supply Chain Analysis
Logistics and freight cost dynamics for physical hardware components concentrate supply chain gravity in China, South Korea, and Taiwan for semiconductor fabrication and server component manufacturing. Raw material dependencies span advanced silicon wafers, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability persists in EUV lithography equipment tethered to ASML's Dutch production. Distribution runs through hyperscale cloud provider procurement channels and direct-to-publisher server farm deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in online action games hinges on cloud infrastructure cost-down trajectories and the premium-tier shift toward adult-oriented monetization systems exported from China's MIIT redesigns.
For Market Incumbents: Anchor competitive position through backward integration into kernel-level anti-cheat engineering and captive control of 5G edge node partnerships with Southeast Asian telecom carriers. Threat substitution from cloud-native entrants with distributed server architectures demands hyperscale data center capacity addition in São Paulo and Mexico City clusters. Certification investment in FDA neurological disclosure pathways differentiates premium titles from regulatory-exposed competitors. For New Entrants and Emerging Players: Cloud-native netcode middleware built for heterogeneous edge environments offers entry into Brazil-Mexico competitive shooter demand pockets where localized server supply lags audience growth. The most penetrable white-space sits in Portuguese-Spanish hybrid content for mobile-first tournaments. Go-to-market execution should prioritize telecom carrier co-financing arrangements that drive 5G data consumption through sponsored prize pools. For Investors and Strategic Acquirers: Consolidation pressure builds where netcode engineering scarcity concentrates in legacy Seoul Capital Area and Los Angeles studio clusters. Long-term viability favors acquisition targets with proprietary procedural animation middleware and GRAC-compliant server localization capabilities. The signal to watch is MIIT regulatory export velocity as adult-oriented monetization systems migrate to aging player bases in Japan and South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Edge Infrastructure Partnership | Telecom carriers in São Paulo and Bangkok finance tournaments to drive data consumption. |
| Kernel-Level Anti-Cheat Certification | Hardware-trusted execution environments elevate technical barriers favoring established engine licensees. |
| Adult-Oriented Monetization Redesign | MIIT-compliant systems export to aging demographics in Japan and South Korea markets. |
| Procedural Animation Middleware Licensing | Eastern European asset stores compress production value gaps for mid-tier studios. |
| GRAC Server Localization Compliance | Domestic data residency rules in Seoul duplicate infrastructure costs for youth-accessible titles. |
Research Methodology
Multiple input streams — primary interviews with live service operations directors, platform engineering leads, and esports tournament organizers; secondary validation through SEC filings, hyperscaler capex disclosures, and MIIT regulatory filings; plus customs data on server hardware imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured netcode engineering scarcity patterns and 5G edge deployment timelines. Secondary sources included GRAC rating board decisions, EU Digital Services Act implementation guidance, and FDA neurological impact disclosure discussions.
Historical revenue trajectories were cross-referenced against panel input from publisher monetization strategists to anchor projections across the analysis window. Segmentation dimensions modeled include game type, platform architecture, user demographic, and regional regulatory cluster. CAGRs were derived from elasticity modeling of battle pass cycle adoption and cosmetic microtransaction penetration rates. Industry-specific forecast inputs captured cloud gaming latency threshold improvements and anti-cheat hardware integration cost curves.
The model holds under sustained 5G edge deployment and stable MIIT regulatory export patterns; deviation in hyperscale data center concentration risk or GRAC server localization mandate expansion would shift infrastructure cost assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Sports Nutrition Market
Sports & Fitness
North America Fitness Rings Market
Sports & Fitness
Europe Spectator Sports Market
Sports & Fitness
Spain Artificial Turf Market
Sports & Fitness
Ladderball Market
Sports & Fitness
Parallel Bars Market
Sports & Fitness
Spain Horse Riding Equipment Market
Sports & Fitness
Connected Gym Equipment Market
Sports & Fitness
Sponge Wrestling Mat Market
Sports & Fitness
United States Running Gear Market
Sports & Fitness
Esports Management Software Market
Sports & Fitness
Europe Stand-Up Paddleboard Market
Sports & Fitness
North America Fantasy Sports Market
Sports & Fitness
Sports Team and Clubs Market
Sports & Fitness
United States Archery Equipment Market
Sports & Fitness
Juggling Clubs Market