
 Spain Horse Riding Equipment Market | 2026-2036
Spain Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Horse Riding Equipment Market Insights
Aftermarket service revenue from saddle fitting and tack refurbishment is reshaping profit pools across the Spain horse riding equipment landscape. HKM Sports Equipment leverages its vertical integration into leather sourcing to sustain margin control across Iberian distribution. Zaldi anchors its position through specialized dressage and jumping saddle craftsmanship from its Basque Country workshops. Colonial Saddlery competes on heritage brand strength within Spanish classical riding traditions.
Horse riding equipment comprises saddles, bridles, protective gear, and stable accessories engineered to ASTM F1163 and EN 1384 safety standards, with leather conditioning and tree-width fitting as critical performance parameters for rider-horse biomechanical alignment. Saddles and bridles retain the dominant value share given replacement cycles tied to horse welfare regulations, while synthetic material segments gain ground among recreational riders seeking weather-resistant maintenance profiles. Professional riders and trainers concentrate demand for premium leather construction through specialty stores and trade show channels.
Spain's Royal Equestrian Federation mandates CE-marked protective headgear and periodic equipment inspection protocols that elevate compliance costs for domestic manufacturers and importers alike. The national consumer affairs authority enforces textile labeling requirements on wool blankets and neoprene boots sold through online retail channels. Stakeholders must monitor pending EU animal welfare directives that could extend traceability requirements to leather supply chains originating outside the single market.
Market Dynamics
Spain's Royal Equestrian Federation tightened safety certification standards for competition gear, forcing domestic manufacturers and importers to absorb elevated compliance costs while professional centers in Andalusia accelerate equipment procurement cycles.
Growth Catalysts
- CE-marked protective headgear mandates:Spain's national consumer affairs authority enforces mandatory certification for helmets sold through e-commerce channels, expanding addressable market for compliant domestic producers.
- Andalusian equestrian center expansion:Professional training facilities across Seville and Córdoba provinces are scaling herd sizes and rider throughput, driving replacement demand for saddles and bridles tied to horse welfare regulations.
- Synthetic material adoption:Recreational riders in Madrid and Barcelona metropolitan areas favor weather-resistant neoprene boots and polyurethane tack for reduced maintenance intensity versus traditional leather.
Market Restraints
- Leather supply concentration:Premium saddle manufacturers depend on tanneries clustered in Jerez de la Frontera, creating vulnerability to raw hide price volatility and seasonal availability constraints.
- EU animal welfare directive uncertainty:Pending traceability requirements for leather originating outside the single market threaten to extend certification timelines and elevate import documentation burdens.
- Technical limitation in tree-width fitting:Biomechanical alignment between rider and horse requires skilled saddle fitters, and certified technician scarcity limits premium product penetration in Galicia and northern regions.
Strategic Opportunities
- Aftermarket service unbundling:Saddle fitting and tack refurbishment revenue streams are capturing margin pools previously absorbed by equipment sales, with Basque Country workshops developing subscription-based maintenance contracts.
- Recreational rider segment expansion:Urban riding schools in Valencia and Málaga are onboarding first-time adult learners, creating demand entry points for mid-tier synthetic construction.
- ASTM F1163 standard convergence:Alignment between Spanish competition rules and US safety protocols enables export qualification for domestic manufacturers targeting North American specialty retailers.
Industry Challenges
- Certified saddle fitter shortage:The Royal Equestrian Federation's technician credentialing program graduates fewer than fifty specialists annually, creating bottlenecks for premium leather saddle distribution in Extremadura and Castilla-La Mancha.
- Multi-channel compliance fragmentation:Textile labeling requirements for wool blankets and stable accessories differ between physical tack shops and online marketplaces, forcing inventory segmentation that elevates working capital requirements for Madrid-based distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Horse Riding Equipment Market |
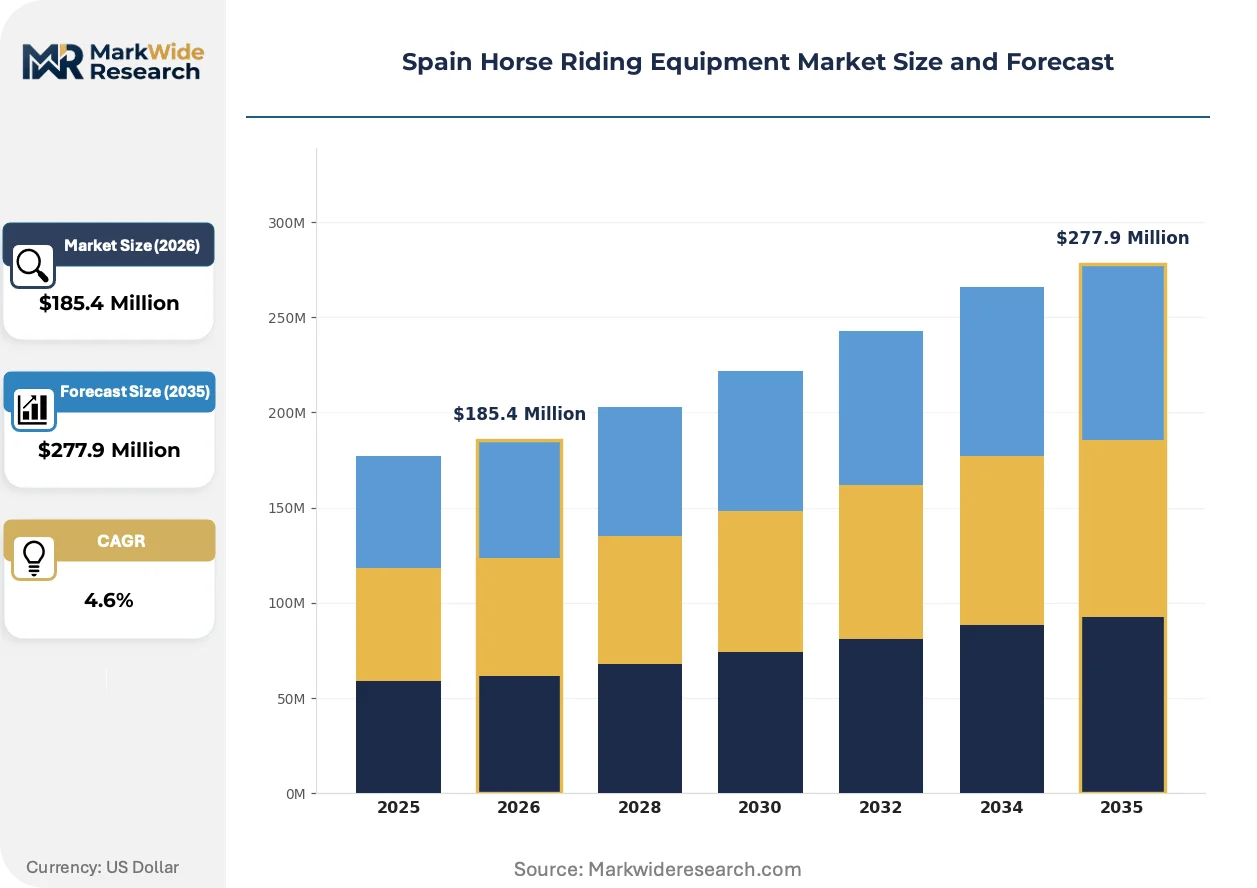
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $277.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Stirrups, Horse Blankets Material: Leather, Synthetic, Wool, Neoprene End User: Professional Riders, Recreational Riders, Trainers, Institutions Distribution Channel: Online Retail, Specialty Stores, Distributors, Trade Shows |
| Companies Covered | HKM Sports Equipment, Mountain Horse, Zaldi, Colonial Saddlery, Ariat International, Decathlon, CAVALLO Albert Sahle, Georg Kieffer Sattlerwarenfabrik, Dainese, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Horse Riding Equipment Market Trends and Innovations
Material science advances and regulatory harmonization pressures are compressing traditional equipment lifecycles while reshaping how Spanish manufacturers compete across price tiers and distribution channels.
3D-printed saddle tree technologies utilizing carbon fiber reinforced polymers are rendering obsolete conventional wooden and fiberglass constructions that dominated Spanish craftsmanship for decades. Professional dressage trainers in Seville and Madrid are adopting these customizable frames at accelerated replacement cycles. The shift is compressing premium product development timelines from eighteen months to under eight weeks for prototype-to-production.
REACH regulation amendments governing chromium VI limits in leather tanning processes are forcing Jerez de la Frontera tanneries to retrofit wastewater treatment infrastructure. Spanish saddle manufacturers sourcing domestically face eighteen-to-twenty-four month compliance transition periods. Premium leather construction segments are responding by accelerating vegetable-tanned hide procurement from certified Italian suppliers.
Subscription-based equipment maintenance contracts are displacing transactional resale models across Andalusian professional centers. Basque Country manufacturers are piloting direct-to-stable service programs that bundle fitting, conditioning, and refurbishment. This behavioral pivot is most visible in Cádiz province, where competition yards now prioritize total cost-of-ownership metrics over upfront capital expenditure in vendor selection.
Spain Horse Riding Equipment Market Segmentation
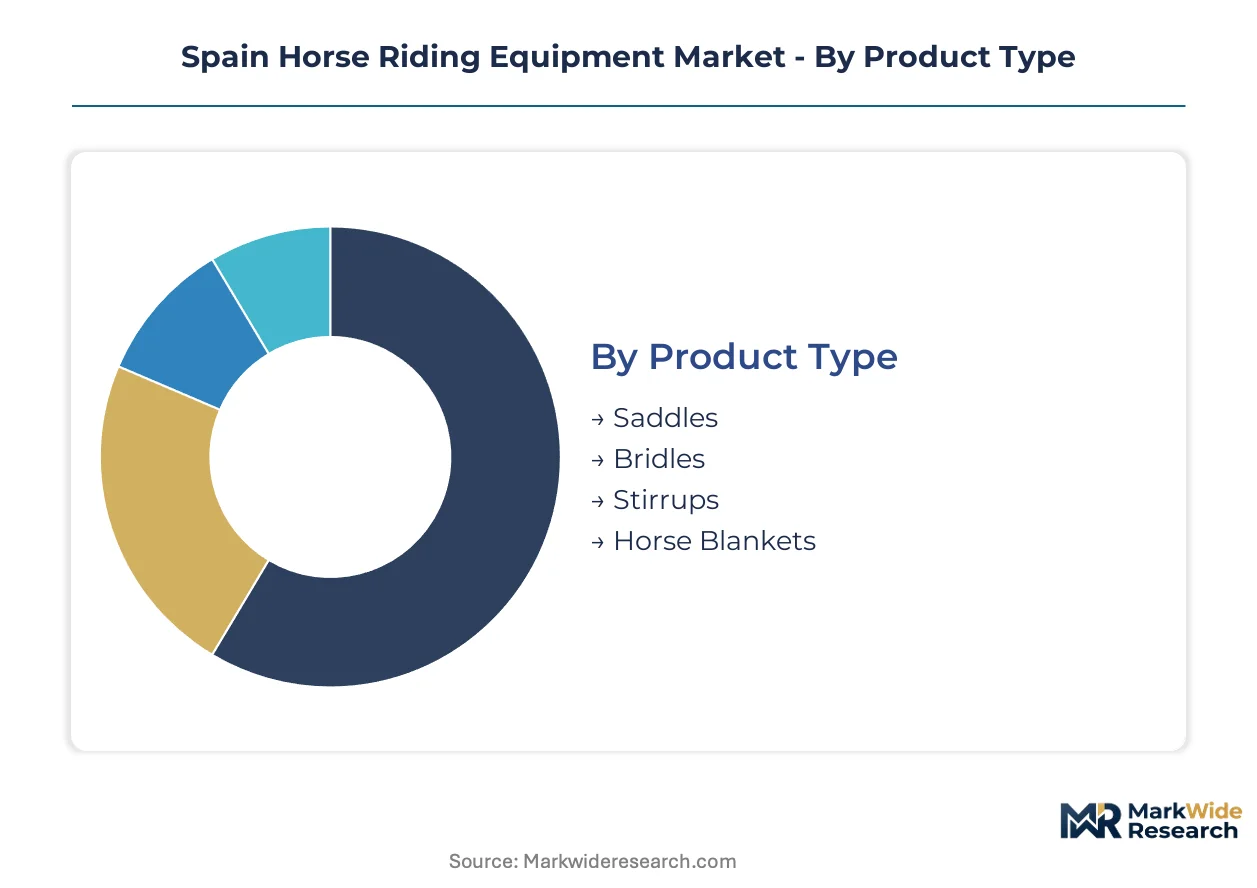
Equipment replacement cycles vary dramatically across Spain's equestrian market, with competition gear facing mandatory retirement timelines while recreational accessories endure until functional failure. Understanding these velocity differences enables inventory positioning and margin capture across distinct buyer behaviors.
Product Type:
Saddles turn over slowest due to fitting complexity and capital intensity, while protective accessories cycle fastest on safety mandate compliance.
- Saddles:Wooden and carbon fiber reinforced polymer trees form the structural core, with Jerez de la Frontera tanneries supplying premium leather for dressage and jumping configurations. Professional centers in Seville and Córdoba provinces absorb the bulk of replacement demand as Spain's Royal Equestrian Federation tightens welfare-linked equipment inspection protocols.
- Bridles:Headstall and bit assemblies incorporate stainless steel hardware with leather or synthetic browbands and nosebands. Recreational riders in Madrid and Barcelona metropolitan areas favor bitless and anatomical designs that reduce pressure point concentration.
- Stirrups:Aluminum and composite iron constructions with rubber tread surfaces dominate safety-focused procurement. Urban riding schools in Valencia prioritize lightweight materials for novice rider confidence.
- Horse Blankets:Wool and synthetic fill layers with waterproof outer shells protect against Andalusian temperature variation. Institutional buyers in Extremadura concentrate volume demand for stable inventory standardization.
Saddles dominate installed base. Bridles are where expansion concentrates.
Material:
Cost tier stratification separates heritage leather craftsmanship from maintenance-reducing synthetics across price-sensitive recreational segments.
- Leather:Vegetable-tanned hides from certified Italian suppliers are displacing Jerez-sourced material as REACH chromium VI amendments force domestic tannery infrastructure retrofits. Professional riders and trainers sustain premium demand through specialty store channels.
- Synthetic:Polyurethane and biothane constructions offer weather resistance that reduces conditioning labor for time-constrained recreational owners. Madrid suppliers are scaling endurance tack production for trail riding growth.
- Wool:Natural fiber blankets and pad linings provide moisture-wicking performance valued in classical training traditions. Spain's national consumer affairs authority enforces textile labeling requirements that elevate compliance burdens for online retail distribution.
- Neoprene:Closed-cell polymer boots and girth sleeves deliver impact protection with hose-clean convenience. First-time adult learners at Málaga urban schools favor these low-maintenance entry points.
Leather commands margin concentration. Synthetic materials are climbing the fastest.
End User:
Application intensity separates high-frequency competition users from sporadic recreational participants with diverging service expectations.
- Professional Riders:Competition athletes require ASTM F1163 and EN 1384 certified gear with documented inspection histories for federation compliance. Basque Country workshops capture this segment through specialized craftsmanship and direct fitting relationships.
- Recreational Riders:Weekend and leisure participants prioritize capital efficiency and maintenance simplicity over performance optimization. Subscription-based maintenance contracts from Andalusian service providers are displacing transactional resale models.
- Trainers:Instruction professionals balance durability demands across multiple horse-rider combinations with procurement cost control. Certified saddle fitter scarcity in Galicia and northern regions limits premium product penetration.
- Institutions:Equestrian centers and riding schools standardize equipment fleets to reduce per-horse fitting complexity. Cádiz province competition yards now prioritize total cost-of-ownership metrics over upfront capital expenditure.
Professional riders anchor premium pricing. Recreational riders represent the steepest expansion trajectory.
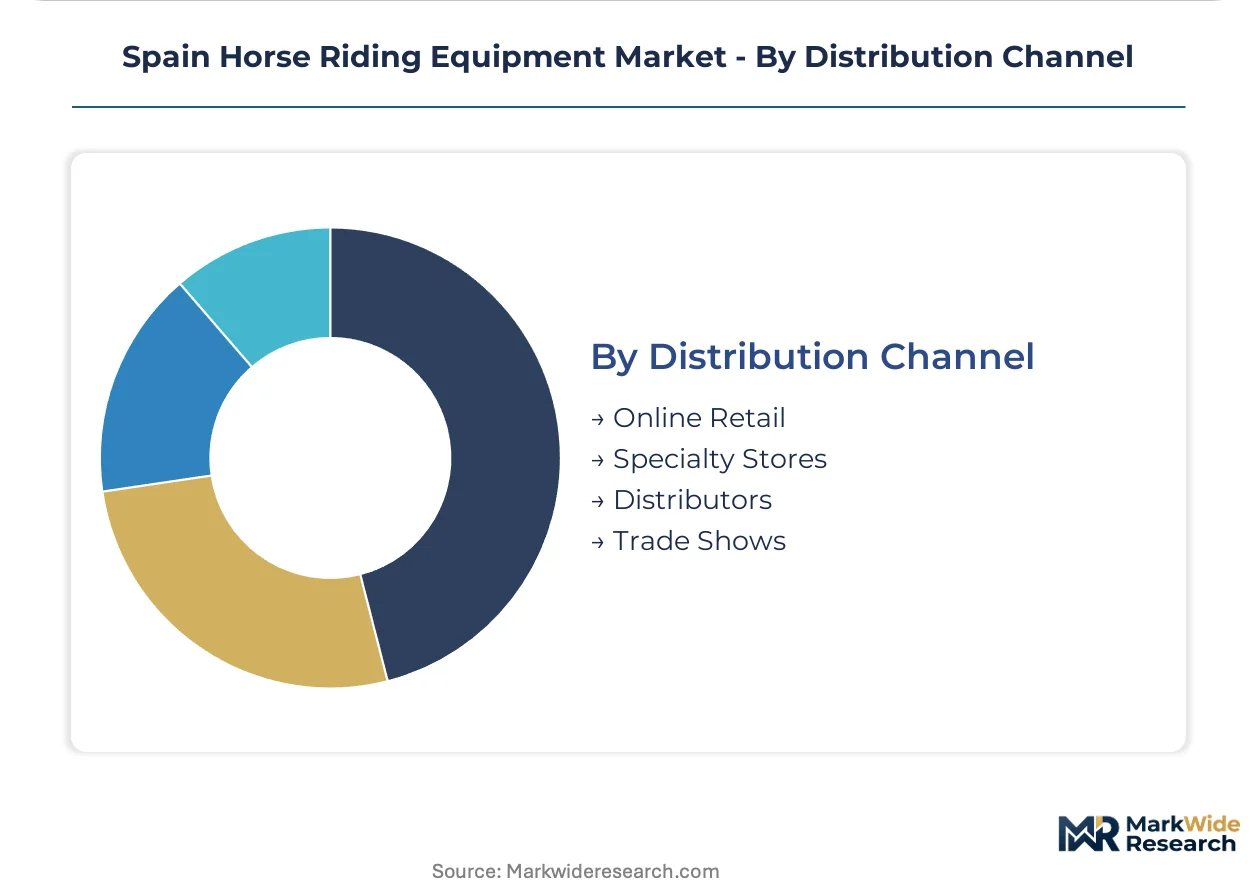
Distribution Channel:
Customer type concentration determines channel viability, with technical fitting requirements protecting physical retail against digital displacement.
- Online Retail:E-commerce platforms capture accessory and replacement part volume where sizing standardization eliminates fitting risk. CE-marked protective headgear mandates for helmets sold through digital channels expand addressable market for compliant domestic producers.
- Specialty Stores:Tack shops with in-house fitters sustain saddle and bridle dominance through biomechanical alignment services. Inventory segmentation between physical and online channels elevates working capital requirements for Madrid-based distributors.
- Distributors:Regional wholesalers bridge manufacturer scale with fragmented retail access across Castilla-La Mancha and Extremadura. Multi-channel compliance fragmentation forces textile labeling differentiation that complicates inventory management.
- Trade Shows:SICAB Seville and Madrid Horse Week concentrate annual procurement decisions for professional centers with demonstration and fitting access. 3D-printed saddle tree technologies compress prototype-to-production timelines for exhibition launch cycles.
Specialty stores retain saddle volume. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusia consumes competition-grade leather saddles at triple the per-capita intensity of Madrid, where recreational riders favor synthetic endurance tack for trail riding convenience.
Andalusia
Professional equestrian centers across Seville and Córdoba provinces drive concentrated demand for dressage and jumping saddles. Spain's Royal Equestrian Federation mandates CE-marked protective headgear and periodic equipment inspections that accelerate replacement cycles. Jerez de la Frontera tanneries supply premium leather to Basque Country workshops serving this high-performance segment.
Madrid
Metropolitan recreational riders prioritize weather-resistant polyurethane tack and neoprene boots for reduced maintenance labor. The national consumer affairs authority enforces textile labeling requirements on wool blankets sold through online retail channels. Madrid-based distributors face working capital pressure from inventory segmentation between physical tack shops and e-commerce platforms.
Basque Country
Specialized saddle craftsmanship anchors premium pricing for professional riders requiring ASTM F1163 certified competition gear. REACH regulation amendments on chromium VI limits force domestic tanneries into eighteen-to-twenty-four month compliance transitions. Zaldi workshops in this region pilot subscription-based maintenance contracts bundling fitting and refurbishment services.
Valencia
Urban riding schools onboard first-time adult learners seeking mid-tier synthetic construction entry points. Certified saddle fitter scarcity limits premium leather product penetration despite recreational segment expansion. Málaga metropolitan facilities favor lightweight aluminum stirrups for novice rider confidence building.
Catalonia
Barcelona-area recreational riders exhibit strong preference for anatomical bridles reducing pressure point concentration. The Royal Equestrian Federation's technician credentialing program graduates fewer than fifty specialists annually, creating distribution bottlenecks. Trade show concentration at SICAB Seville and Madrid Horse Week drives annual procurement decisions for competition yards.
Spain Horse Riding Equipment Market Competitive Landscape
Capability concentration sits with heritage craftsmanship specialists; scale advantage sits with diversified sporting goods manufacturers. The vendor base stratifies into three tiers: vertically integrated leather processors controlling upstream tannery access, regional workshops competing on fitting expertise, and mass-market retailers capturing recreational accessory volume. Dominant competitive moves include backward integration into captive leather supply and unbundling of aftermarket service revenue from equipment sales.
Within the heritage specialist tier, Zaldi and Colonial Saddlery exemplify positioning anchored in geographic craft traditions. Zaldi occupies a position representing Basque Country saddle-making expertise, while Colonial Saddlery exemplifies brand strength tied to Spanish classical riding heritage. HKM Sports Equipment represents the diversified sporting goods archetype with upstream control over leather sourcing. These three players illustrate the structural split between craftsmanship-focused workshops and scale-driven equipment suppliers.
| Leading Market Players |
|---|
| HKM Sports Equipment |
| Mountain Horse |
| Zaldi |
| Colonial Saddlery |
| Ariat International |
| Decathlon |
| CAVALLO Albert Sahle |
| Georg Kieffer Sattlerwarenfabrik |
| Dainese |
| Others |
Pricing and Supply Chain Analysis
REACH chromium VI amendment exposure determines both tiered pricing spreads across leather grades and supply chain restructuring toward Italian vegetable-tanned alternatives. Domestic tanneries in Jerez de la Frontera face eighteen-to-twenty-four month compliance transitions that compress margins for premium saddle manufacturers while accelerating procurement from certified external suppliers.
Pricing Analysis
Long-term offtake contracts between Basque Country workshops and Andalusian professional centers anchor premium leather saddle pricing, while spot-market transactions dominate synthetic tack sales to recreational riders. Price differentiation separates ASTM F1163-certified competition gear from uncertified recreational accessories, with brand heritage from Jerez craftsmanship commanding additional premiums. Pricing pressure stems from REACH compliance costs forcing domestic tannery infrastructure retrofits. Recreational riders exhibit highest price sensitivity, prioritizing capital efficiency over performance optimization.
Supply Chain Analysis
Raw hide feedstock draws from Spanish domestic herds and certified Italian tanneries, with carbon fiber reinforced polymers for saddle trees sourced from specialized European composite manufacturers. Leather conditioning chemicals and stainless steel hardware components rest on German and French supplier relationships. Single-source vulnerability concentrates in Jerez de la Frontera tannery capacity for premium vegetable-tanned hides. Distribution runs through specialty tack shops with in-house fitters, supported by regional wholesalers bridging manufacturer scale with fragmented retail access across Castilla-La Mancha and Extremadura.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based maintenance contracts for saddle fitting and tack refurbishment are expanding faster than equipment sales, creating service-attach revenue pools that reshape vendor economics across the Spain horse riding equipment landscape.
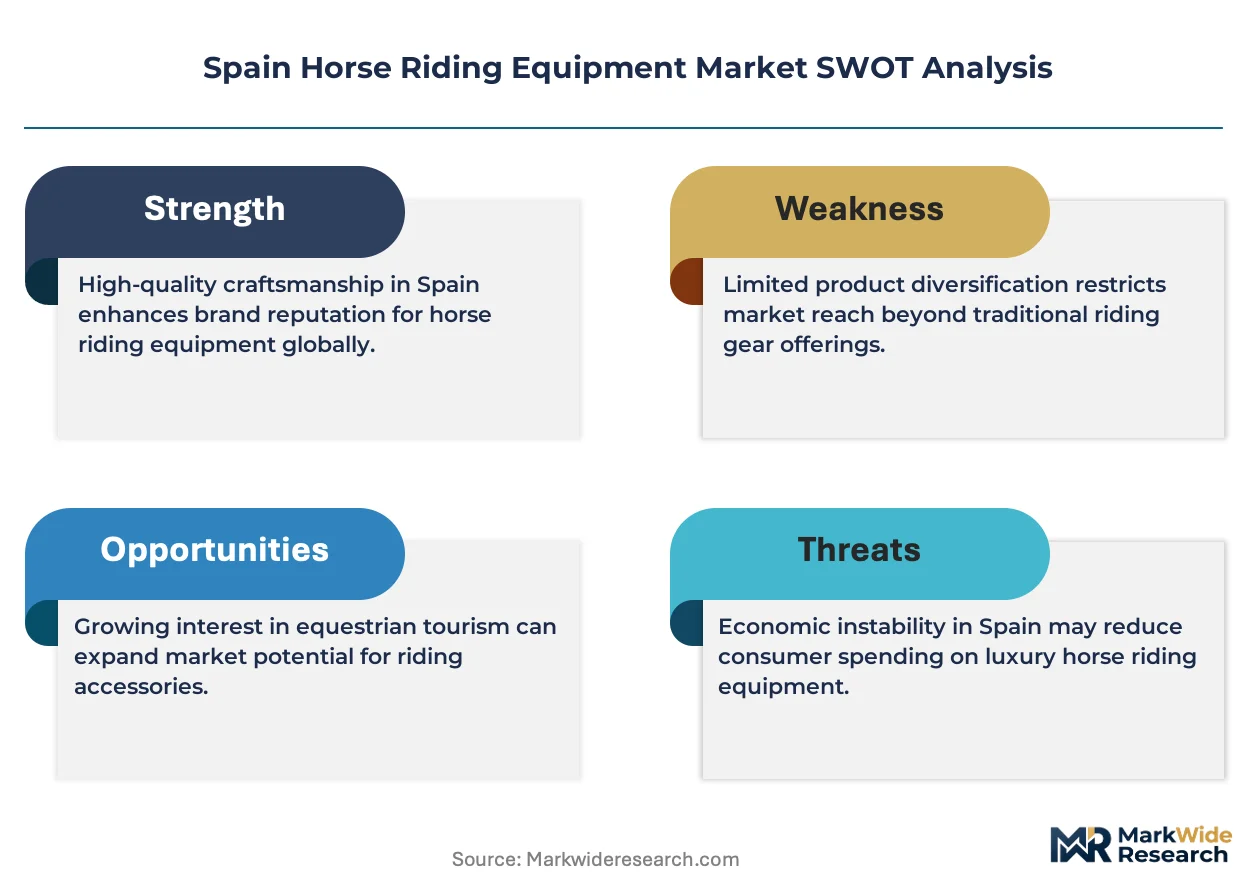
For Market Incumbents: Build certification moats around Royal Equestrian Federation technician credentialing programs that graduate fewer than fifty specialists annually. Basque Country workshops should deepen captive leather supply relationships with Italian tanneries ahead of REACH chromium VI enforcement deadlines. Colonial Saddlery can leverage heritage brand strength to anchor direct-to-stable service programs that bundle fitting and refurbishment. For New Entrants and Emerging Players: Galicia and northern regions exhibit certified saddle fitter scarcity that limits premium product penetration and creates white-space for mid-tier synthetic construction targeting first-time adult learners. Valencia urban riding schools onboarding novice riders represent the most penetrable segment for lightweight aluminum stirrups and neoprene entry points. A mobile fitting service model can bypass specialty shop channel concentration. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors vertically integrated players with upstream tannery control. Long-term viability over the coming decade hinges on service revenue unbundling rather than pure equipment manufacturing. Watch for EU animal welfare directive finalization as the signal indicating traceability requirement intensity and import documentation burden elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Capacity | Secures vegetable-tanned hide supply from Italian certified suppliers ahead of REACH enforcement. |
| Subscription-Based Maintenance Contracts | Captures recurring revenue from Andalusian professional centers prioritizing total cost-of-ownership metrics. |
| 3D-Printed Saddle Tree Prototyping | Compresses development timelines from eighteen months to under eight weeks for exhibition launch cycles. |
| CE Marking Pathway Investment | Expands addressable market for protective headgear through e-commerce channels under national consumer affairs authority mandates. |
| Direct-to-Stable Service Programs | Bypasses specialty shop channel fragmentation while capturing fitting and refurbishment margin pools. |
Research Methodology
Operator-level perspectives from saddle fitters, equestrian center procurement managers, tannery operations directors, and Royal Equestrian Federation compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from Spain's national consumer affairs authority textile labeling enforcement records, EU REACH amendment documentation, and federation equipment inspection protocols. Bottom-up demand modeling across product type, material, end user, and distribution channel segments triangulated against top-down market sizing from customs trade data and regional distributor shipment records.
Scenario-bracketing around regulatory implementation timelines and synthetic material adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, construction material, rider application intensity, and geographic demand cluster. CAGRs derived from replacement cycle velocity differentials between competition-grade and recreational equipment, with inputs from horse population trends and professional center expansion pipelines.
Practitioners should monitor EU animal welfare directive finalization and domestic tannery compliance transition progress for early signals requiring forecast revision. Cross-checking against Royal Equestrian Federation equipment registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gym Shoes Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Sandbells Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Global Stand-Up Paddleboard Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Air Sports Equipment Market