
 Sponge Wrestling Mat Market | 2026-2036
Sponge Wrestling Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Sponge Wrestling Mat Market Insights
The capital-intensity gap between automated foam-bonding lines and manual lamination setups is collapsing. Dollamur leverages captive manufacturing in Texas to control raw EVA sourcing costs across its competition-grade lineup. Resilite Sports Products anchors its position through deep specialization in custom-cut school district orders with district-specific color matching. Taishan Sports Industry Group competes on export scale, operating bonded-polyethylene facilities that supply wrestling federations across Asia and Eastern Europe.
A sponge wrestling mat is a multi-layer bonded-foam platform engineered with specified compression deflection ratings, typically constructed from closed-cell EVA or polyethylene foam laminated to a vinyl or carpet surface, designed to absorb impact energy during grappling and takedown maneuvers. The primary commercial purpose centers on reducing traumatic injury incidence while providing consistent coefficient-of-friction performance for footwork and ground engagement. Competition mats command premium positioning due to federation certification requirements, while training mats sustain volume leadership through replacement cycles in high school and collegiate programs. Portable mats represent the fastest-expanding category as rental-event operators and pop-up tournament organizers seek rapid-deployment surfacing without permanent installation infrastructure.
FCC guidelines on synthetic material emissions intersect with state athletic association procurement rules in the US, pushing manufacturers toward low-VOC adhesive systems and third-party flame-resistance testing. EPA regulations on polyurethane and PVC processing chemicals further constrain formulation choices, particularly for domestic producers serving public institutional buyers. Stakeholders must monitor evolving certification harmonization between NFHS standards and international federation protocols to determine whether single-certification products can capture cross-border tournament supply contracts without redundant testing expenditure.
Market Dynamics
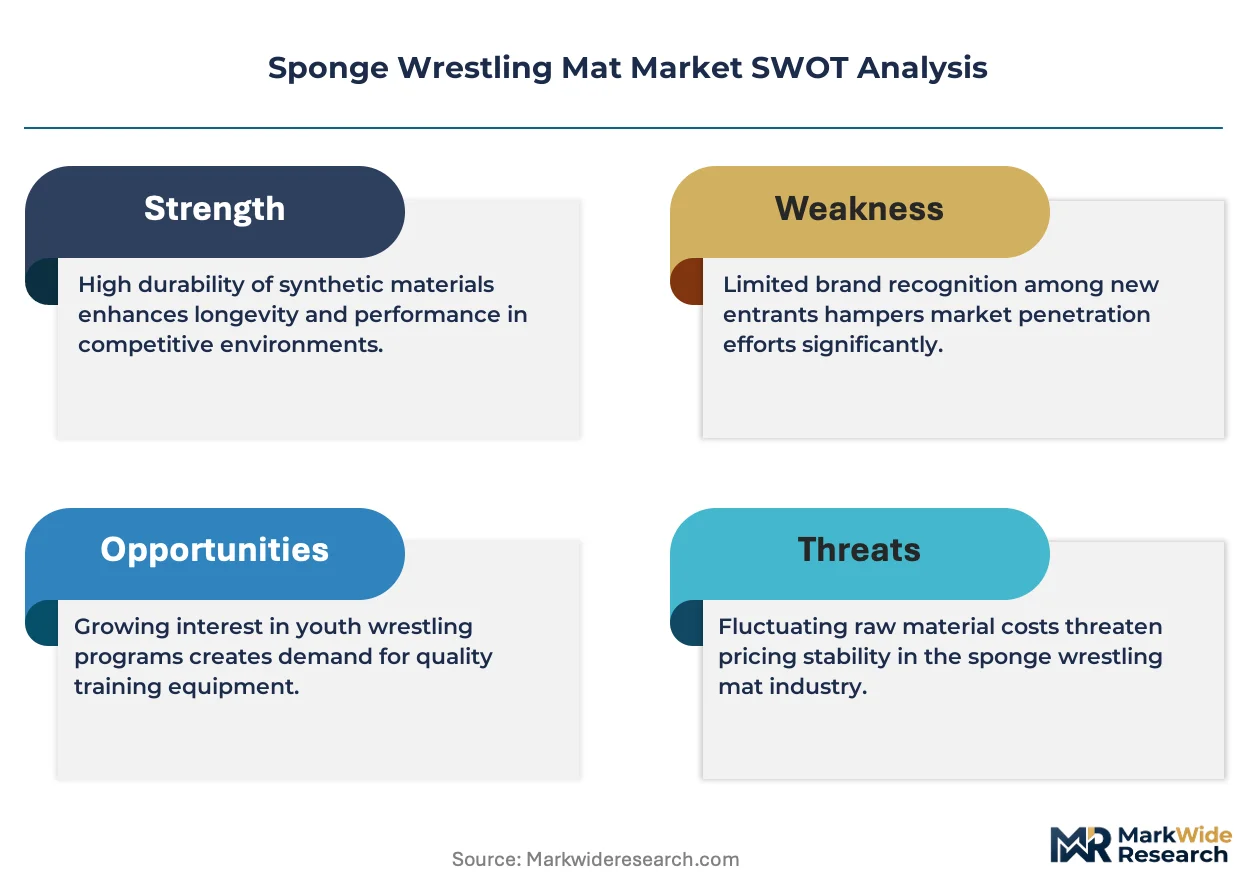
Foam-bonding automation is collapsing the capital barrier between premium competition-grade mats and mass-market training surfaces, forcing incumbents to defend margin through captive raw material sourcing rather than manufacturing scale alone.
Growth Catalysts
- NFHS Certification Mandates:State interscholastic leagues across the United States now require federation-certified surfacing for sanctioned events, creating pull-through demand for compliant mat replacements in high school athletic programs.
- Closed-Cell EVA Formulation Advances:Cross-linked polyethylene foam variants deliver superior compression deflection ratings and extended service life, elevating durability expectations among collegiate athletic departments.
- Pop-Up Tournament Economics:Rental-event operators and independent tournament organizers drive portable mat category expansion as rapid-deployment surfacing eliminates permanent installation infrastructure costs.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene-vinyl acetate and polyethylene resin prices fluctuate with crude oil indices, compressing margin predictability for foam-lamination specialists without backward integration into polymer supply.
- Adhesive Regulatory Friction:EPA constraints on polyurethane and PVC processing chemicals limit formulation flexibility for domestic producers serving public institutional buyers subject to low-VOC procurement rules.
- Geographic Supply Concentration:Bonded-polyethylene manufacturing capacity clusters in East Asian export hubs, exposing tournament supply contracts to freight cost spikes and customs processing delays.
Strategic Opportunities
- India School Infrastructure Buildout:Central government physical education mandates and district-level sports facility investments create first-mover positioning for certified mat suppliers in underpenetrated state athletic associations.
- Modular Rental Channel Expansion:Equipment-leasing platforms and event-service marketplaces enable asset-light market entry without traditional distributor relationships or territory-exclusive dealer networks.
- Harmonized Certification Arbitrage:Manufacturers achieving dual NFHS and United World Wrestling compliance can capture cross-border tournament supply contracts without redundant third-party testing expenditure.
Industry Challenges
- Multi-Federation Compliance Timelines:Divergent flame-resistance testing protocols between domestic state associations and international federations extend product validation cycles and delay revenue recognition on new mat introductions.
- Skilled Foam-Bonding Technician Scarcity:Automated lamination lines still require specialized calibration expertise for compression-deflection consistency, constraining production ramp rates during seasonal demand surges.
- Legacy Vinyl Surface Integration:School districts with existing carpet-bonded mat installations face subfloor compatibility assessment costs when upgrading to closed-cell foam platforms, slowing replacement cycle velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sponge Wrestling Mat Market |
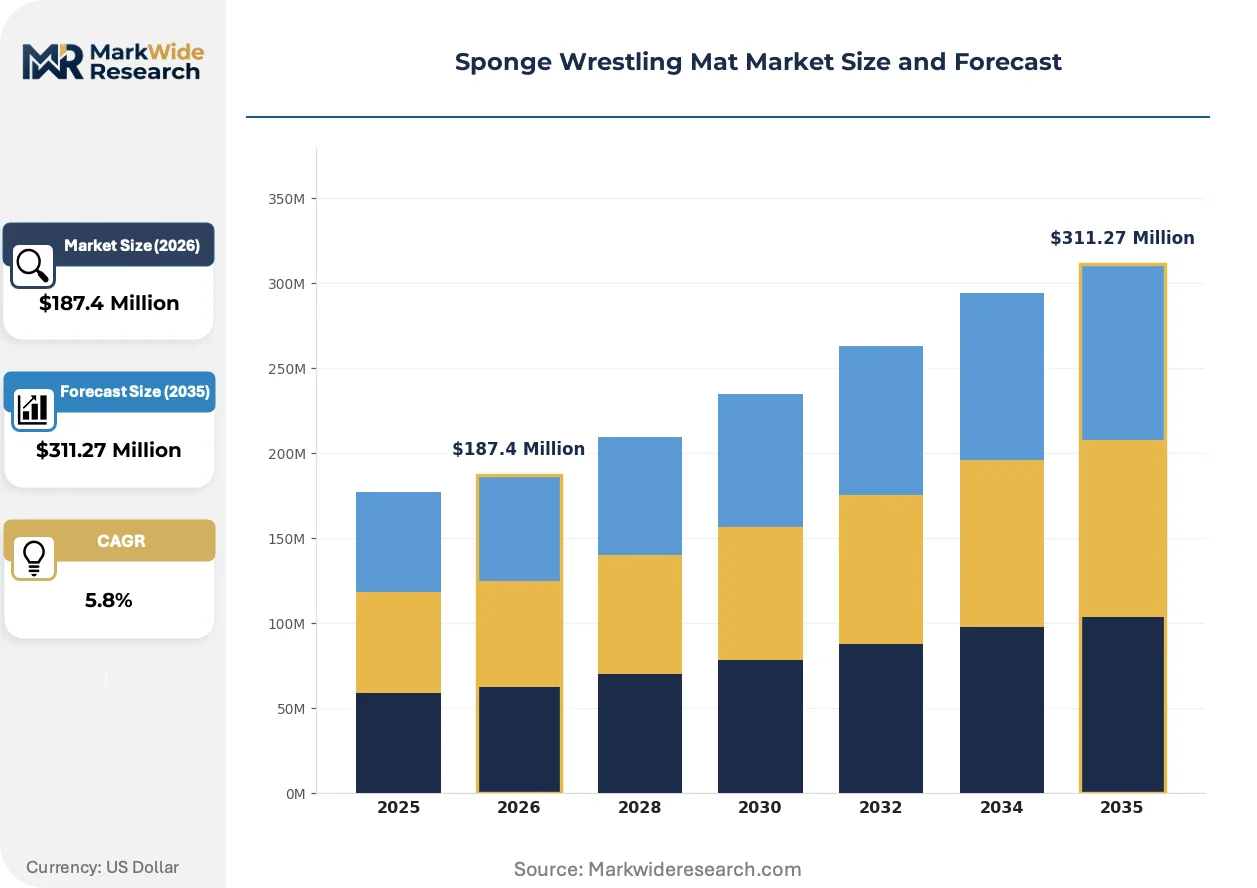
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Competition Mats, Training Mats, Portable Mats, Customized Mats Thickness: 1 inch, 2 inches, 3 inches, 4 inches Material: EVA Foam, PVC, Polyethylene, Rubber End Use: Schools, Gyms, Wrestling Clubs, Home Use |
| Companies Covered | Dollamur, Tiffin Mats, Resilite Sports Products, Roll Out Mat, Taishan Sports Industry Group, Crown Gym Mats, Zebra Mats, EZ Flex Sports Mats, Greatmats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sponge Wrestling Mat Market Trends and Innovations
Material science advances and procurement model fragmentation are simultaneously elevating performance specifications and compressing traditional distribution hierarchies in wrestling surfacing supply.
Thermoplastic polyurethane surface layers are decomposing the historical vinyl-carpet dichotomy in competition-grade mats. NCAA programs and Olympic training centers adopt TPU-laminated platforms for superior coefficient-of-friction consistency across humidity conditions. This technology is decomposing price premiums previously commanded by legacy vinyl-bonded products with identical foam cores.
REACH restrictions on phthalate plasticizers and short-chain chlorinated paraffins force reformulation of surface coatings and adhesive binders across European Union member states. Domestic manufacturers serving institutional buyers must maintain parallel inventory streams or absorb certification costs for dual-compliant product lines. Competition mat suppliers with existing third-party flame-resistance documentation capture accelerated procurement decisions from risk-averse municipal purchasers.
Direct-to-athletic-department contracting supplants traditional equipment distributor intermediation for volume replacement orders. Collegiate procurement officers leverage cooperative purchasing agreements and state-contract pricing vehicles to bypass regional dealer markups. This pattern concentrates most visibly in Texas and California, where consolidated university system purchasing commands dedicated manufacturer account management and custom color-matching services without distributor margin stacking.
Sponge Wrestling Mat Market Segmentation
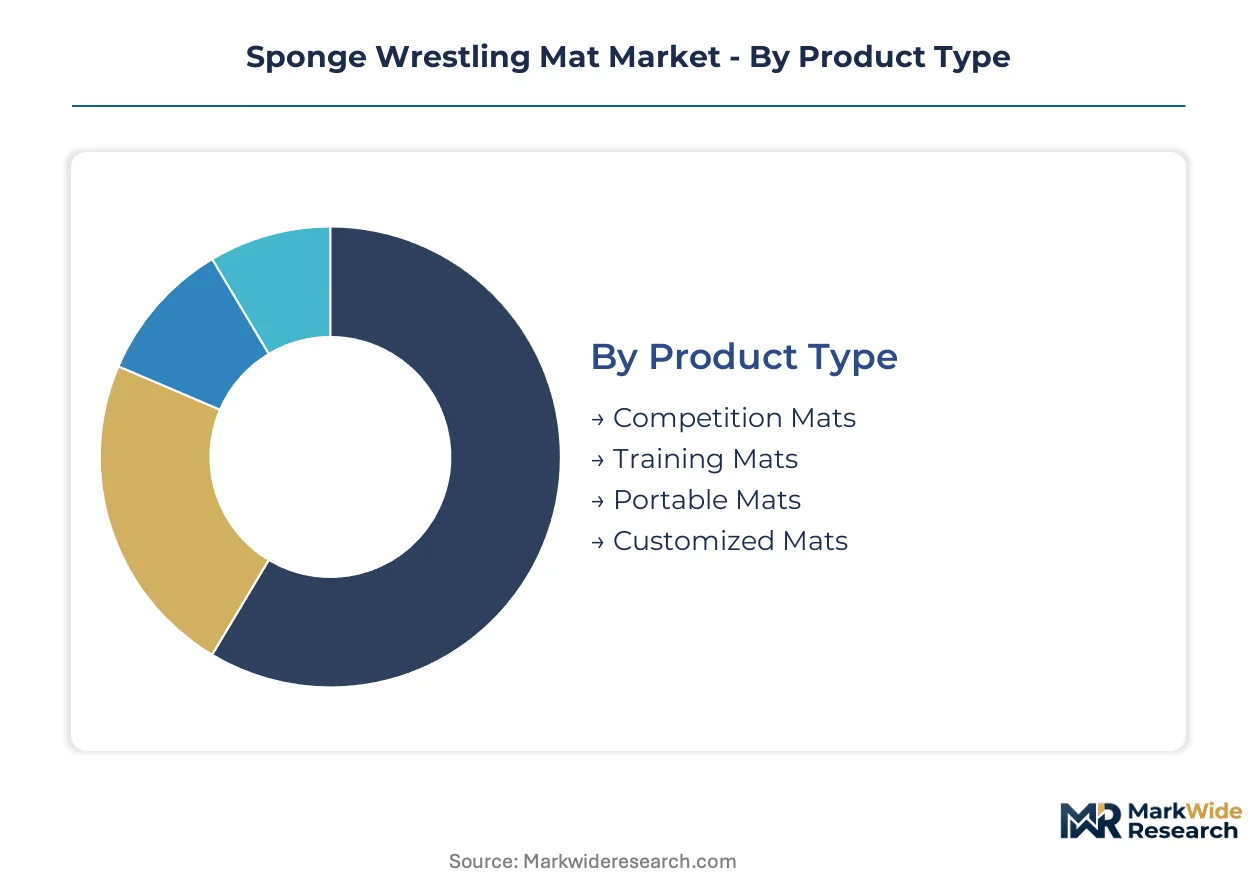
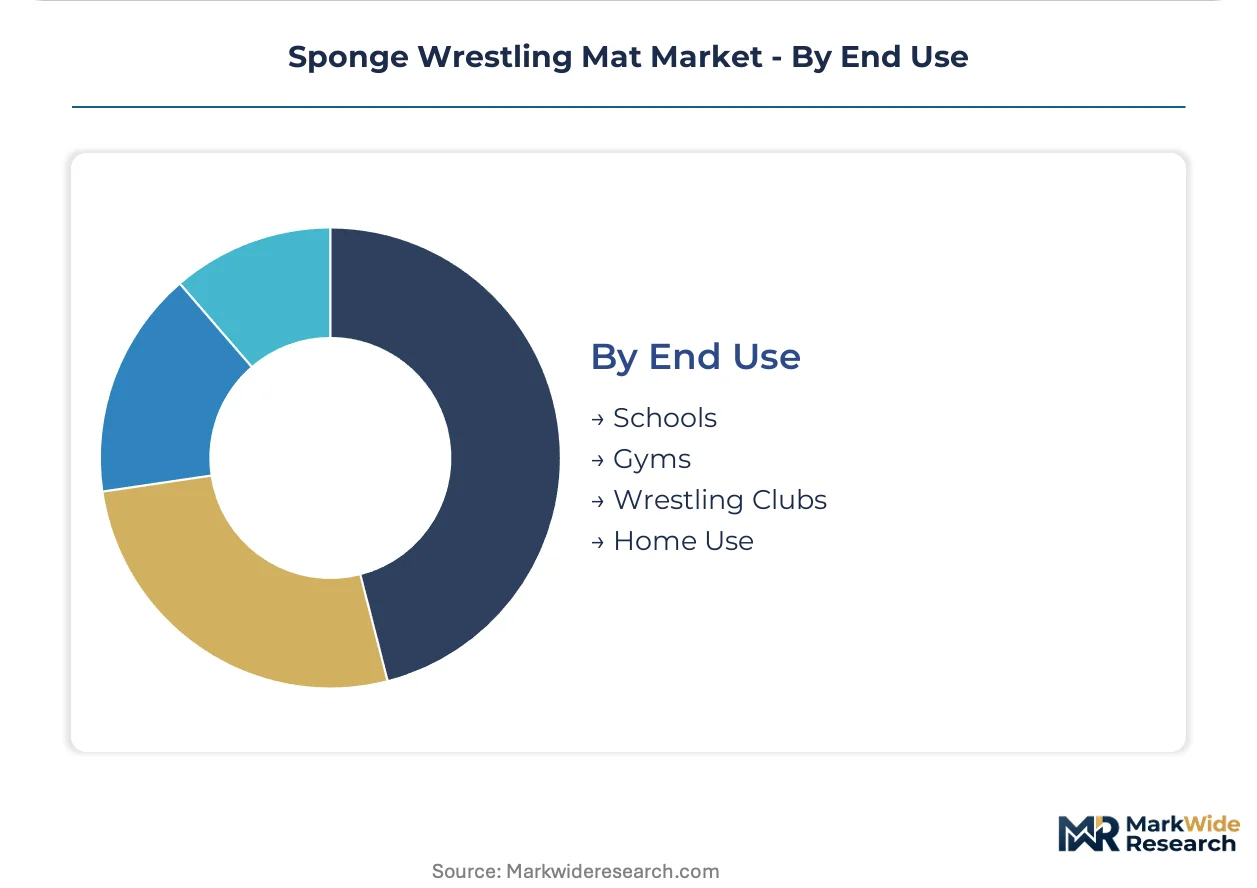
Wrestling mat procurement splits sharply between institutional buyers with certification mandates and consumer segments prioritizing portability and price. Understanding these fault lines reveals where margin pools concentrate and which formulation investments yield durable competitive position.
Product Type:
Competition-grade platforms dominate export-led manufacturing from bonded-polyethylene facilities in Asia, while training and portable variants sustain higher domestic production shares in North America.
- Competition Mats:Multi-layer bonded-foam platforms with federation-certified compression deflection ratings and vinyl or thermoplastic polyurethane surfaces. Demand concentrates in United States collegiate athletic departments and state interscholastic leagues where NFHS mandates drive replacement cycles.
- Training Mats:Standardized foam-laminated surfaces without full certification documentation, serving high school practice rooms and club facilities. Volume leadership in this segment reflects shorter replacement intervals and district-level bulk procurement.
- Portable Mats:Rapid-deployment roll-out or foldable designs for rental-event operators.
- Customized Mats:District-specific color matching and logo integration for school identity programs.
Competition mats command the established base. The steepest expansion runs through portable mats.
Thickness:
Cost tier stratification separates premium collegiate specifications from economy options for youth programs and home installations.
- 2 inches:The institutional standard for high school and collegiate competition, balancing impact absorption with storage logistics. United States state athletic associations specify this thickness for sanctioned events, creating procurement pull-through.
- 4 inches:Maximum cushioning platforms for Olympic training centers and professional facilities with dedicated mat rooms. Premium positioning reflects specialized foam-bonding requirements and extended service life expectations.
- 1 inch:Economy option for temporary installations and budget-constrained programs.
- 3 inches:Intermediate specification for club facilities seeking enhanced protection without full competition-grade investment.
Two-inch specifications anchor institutional volume. Four-inch platforms gain share fastest in elite training infrastructure.
Material:
Supply concentration in ethylene-vinyl acetate and polyethylene resin markets exposes margin structures to petrochemical feedstock volatility.
- EVA Foam:Closed-cell cross-linked formulations deliver specified compression deflection ratings and consistent coefficient-of-friction performance. United States manufacturers with captive raw material sourcing defend position against import competition.
- Polyethylene:Bonded variants from East Asian export hubs supply wrestling federations across Asia and Eastern Europe with cost-optimized durability.
- PVC:Surface coating and backing material subject to EPA processing chemical constraints.
- Rubber:Alternative core material for specialized anti-fatigue applications in multi-use gymnasium conversions.
EVA foam retains the installed base. Polyethylene platforms climb fastest in export-led tournament supply contracts.
End Use:
Customer type fragmentation separates institutional procurement officers with cooperative purchasing agreements from individual consumers seeking direct-to-retail channels.
- Schools:Public district and private institutional buyers subject to state-contract pricing vehicles and low-VOC procurement rules. United States consolidated university systems command dedicated manufacturer account management.
- Wrestling Clubs:Independent training facilities and regional academy networks with flexible specification requirements and price-sensitive replacement timing.
- Gyms:Multi-use fitness centers converting space for grappling programs.
- Home Use:Individual athletes and families purchasing through equipment-leasing platforms or direct retail.
Schools dominate established revenue. Wrestling clubs show the steepest expansion trajectory as private academy networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where NFHS certification mandates and consolidated university system purchasing command premium positioning, while East Asian export hubs compete on bonded-polyethylene scale with compressed margin structures.
United States
State interscholastic leagues and collegiate athletic departments drive procurement volume through federation-certified replacement cycles. EPA constraints on polyurethane and PVC processing chemicals shape formulation choices for domestic producers serving public institutional buyers. Texas hosts captive EVA sourcing operations that supply competition-grade platforms across the South and Midwest.
China
Bonded-polyethylene manufacturing capacity clusters in export-oriented facilities serving wrestling federations across Asia and Eastern Europe. MIIT industrial standards and GB certification requirements govern foam-lamination quality for domestic consumption. Shandong Province anchors production scale for tournament supply contracts with freight-advantaged port access.
Germany
REACH restrictions on phthalate plasticizers and short-chain chlorinated paraffins force reformulation of surface coatings and adhesive binders for EU institutional buyers. ECHA compliance documentation accelerates procurement decisions from risk-averse municipal purchasers. Bavaria hosts specialized calibration facilities for compression-deflection testing equipment.
India
Central government physical education mandates and district-level sports facility investments create first-mover positioning for certified mat suppliers in underpenetrated state athletic associations. BIS quality certification requirements and DGFT import regulations shape competitive dynamics for domestic versus foreign suppliers. Maharashtra and Gujarat host emerging distribution networks for school infrastructure buildout.
Japan
Olympic training centers and collegiate wrestling programs sustain demand for maximum-cushioning four-inch platforms with specialized foam-bonding requirements. METI industrial policy and JIS standards govern material specifications for institutional procurement. Kanto region concentration around Tokyo anchors premium-tier distribution for elite athletic infrastructure.
Sponge Wrestling Mat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated foam-bonding lines collapsing historical capital barriers between premium competition-grade and mass-market training surfaces. The vendor base stratifies into three tiers: domestic specialists with captive raw material sourcing, East Asian scale exporters with bonded-polyethylene facilities, and regional custom-fabricators serving district-specific orders. Consolidated university system purchasing and cooperative pricing vehicles concentrate volume with account-managed suppliers, while equipment-leasing platforms enable asset-light entry for portable mat rental operators. Dominant competitive moves include backward integration into polymer supply and direct-to-athletic-department contracting that bypasses traditional distributor markups.
Among North American specialists, Dollamur and Resilite Sports Products exemplify divergent positioning archetypes. Dollamur represents the captive-sourcing model with Texas-based manufacturing control over raw EVA costs. Resilite Sports Products occupies the custom-fabrication tier with district-specific color matching and school identity program specialization. Taishan Sports Industry Group anchors the export-scale archetype from Chinese bonded-polyethylene facilities supplying wrestling federations across Asia and Eastern Europe.
| Leading Market Players |
|---|
| Dollamur |
| Tiffin Mats |
| Resilite Sports Products |
| Roll Out Mat |
| Taishan Sports Industry Group |
| Crown Gym Mats |
| Zebra Mats |
| EZ Flex Sports Mats |
| Greatmats |
| Others |
Pricing and Supply Chain Analysis
Automated foam-bonding lines in Texas and Shandong Province compress unit economics across certification tiers, concentrating margin defense among manufacturers with captive EVA sourcing or bonded-polyethylene export scale. This capacity consolidation simultaneously elevates price floors for federation-certified competition mats and erodes premiums on standardized training surfaces.
Pricing Analysis
The customization-premium spread separates district-specific color-matched orders from standard-cut training mats by certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels reflects NFHS documentation requirements, with collegiate athletic departments least sensitive and club facilities most responsive to replacement-cycle timing. Cost compression in training-grade surfaces is intensifying because East Asian bonded-polyethylene imports erode domestic manufacturer share in non-certified segments.
Supply Chain Analysis
Inventory lead times for closed-cell EVA formulations stretch from Texas petrochemical corridors to lamination facilities, while bonded-polyethylene platforms ship from Shandong Province with freight-advantaged port access. Raw material flows draw from ethylene-vinyl acetate resin markets, vinyl surface coating suppliers, and low-VOC adhesive compounders. Single-source vulnerability concentrates in East Asian export hubs exposed to customs processing delays. Distribution runs through cooperative purchasing agreements and state-contract pricing vehicles for institutional buyers, with equipment-leasing platforms emerging for portable mat rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in cyclical recovery driven by NFHS-mandated replacement cycles in United States high school athletic programs. Procurement officers are consolidating volume through cooperative agreements, compressing distributor margins while elevating manufacturer account-management requirements.
For Market Incumbents: Fortify captive EVA sourcing positions in Texas petrochemical corridors against bonded-polyethylene import competition from Shandong Province. Deepen certification investment for dual NFHS and United World Wrestling compliance to capture cross-border tournament contracts without redundant testing expenditure. Prioritize direct-to-athletic-department contracting that bypasses regional dealer markups in Texas and California consolidated university systems.
For New Entrants and Emerging Players: Lead with modular rental channel expansion targeting pop-up tournament operators and independent event organizers seeking rapid-deployment surfacing without permanent installation infrastructure. Maharashtra and Gujarat school infrastructure buildout offers first-mover positioning in underpenetrated Indian state athletic associations. Asset-light market entry through equipment-leasing platforms avoids territory-exclusive dealer network requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with installed base replacement cycles in collegiate athletic departments and state interscholastic leagues. Long-term viability over the next decade hinges on backward integration into polymer supply and harmonized certification portfolios. Watch for EPA regulatory tightening on polyurethane processing chemicals as an inflection indicator favoring domestic producers with compliant formulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVA Supply | Captive raw material sourcing in Texas defends margin against bonded-polyethylene import competition. |
| Dual Certification Investment | NFHS and United World Wrestling compliance eliminates redundant testing for cross-border tournament contracts. |
| Direct-to-Institutional Contracting | Bypassing distributor markups concentrates volume with cooperative purchasing agreements in consolidated university systems. |
| Modular Rental Platform Launch | Equipment-leasing marketplaces enable asset-light entry for pop-up tournament and rental-event operators. |
| Low-VOC Formulation Transition | EPA-compliant adhesive systems secure procurement from public institutional buyers subject to emissions regulations. |
Research Methodology
Desk research of customs trade data, state athletic association procurement records, and federation certification documentation preceded structured interviews with foam-lamination plant managers, collegiate athletic department procurement officers, and equipment-leasing platform operators. Primary fieldwork with EVA resin suppliers and bonded-polyethylene exporters validated secondary findings on cost structures and capacity utilization. Bottom-up unit economics modeling triangulated against top-down market sizing from import-export statistics and institutional purchasing databases.
Variance-decomposition across product type, thickness specification, material formulation, and end-use customer segments shaped the analytical framework over the projection horizon. CAGRs were derived from replacement-cycle velocity in high school and collegiate programs, export-led tournament supply contract growth, and portable mat rental channel expansion. Industry-specific inputs included NFHS certification mandate adoption timelines, EPA regulatory trajectory on processing chemicals, and petrochemical feedstock price sensitivity indices.
Underlying assumptions cover continued state interscholastic league enforcement of federation-certified surfacing standards, with deviation risk concentrated in petrochemical feedstock volatility and customs processing disruptions at East Asian export hubs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market