
 Esports Management Software Market | 2026-2036
Esports Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Esports Management Software Market Foresight
The shift from fragmented single-vendor tournament tools toward unified multi-source platform ecosystems is hardening across the esports management software value chain. SENET leverages cloud-native architecture to anchor enterprise-grade tournament operations for large-scale event organizers. Battlefy sustains developer-facing API depth that competes directly with legacy bracket infrastructure providers. PlayVS specializes in scholastic league management, dominating the North American high school and collegiate contracting channel.
Esports management software comprises integrated digital platforms that coordinate competitive gaming operations through match scheduling algorithms, real-time performance telemetry ingestion, and automated prize distribution smart contracts. These systems serve commercial purpose by reducing tournament administrative overhead, standardizing competitive integrity protocols, and enabling monetization through broadcast rights management and sponsorship attribution. Tournament Management functionality leads current deployment value given its centrality to revenue-generating event operations, while Game Analytics represents the fastest-expanding segment as teams invest in player performance optimization. Cloud-Based delivery models occupy the dominant position across customer tiers, though Hybrid architectures are gaining traction among security-conscious professional organizations operating multi-million dollar prize pools.
FCC guidelines on broadcast content classification and emerging state-level esports wagering regulations in jurisdictions like Nevada and New Jersey shape platform compliance requirements for streaming integrations and financial transaction modules. GDPR and emerging state privacy frameworks constrain how player biometric data and behavioral analytics may be collected, stored, and monetized across tournament management databases. Stakeholders must monitor regulatory divergence between entertainment classification and sports governance regimes to anticipate compliance cost trajectories and platform feature roadmaps.
Market Dynamics
The migration from on-premise tournament infrastructure to cloud-native delivery models is compressing deployment timelines and reshaping procurement economics across collegiate programs, independent organizers, and professional leagues.
Growth Catalysts
- GDPR Article 9 constraints on biometric data:European tournament operators are investing in compliant analytics platforms that process player performance telemetry without capturing protected health data, creating procurement pull for privacy-certified software vendors.
- API-first architecture:Developer ecosystems around tournament bracket engines are enabling third-party broadcast integrations and sponsorship attribution modules that expand platform monetization capacity beyond core licensing revenue.
- Nevada esports wagering regulations:State-level legalization of competitive gaming betting is mandating real-time match integrity monitoring and automated anomaly detection systems that tournament management platforms must embed to serve licensed operators.
Market Restraints
- Cloud infrastructure concentration:Tournament platform uptime dependencies on hyperscale providers in Virginia and Frankfurt create single-point-of-failure exposure for million-dollar prize pool events requiring contractual redundancy clauses.
- Blockchain transaction volatility:Smart contract prize distribution modules face gas fee unpredictability on Ethereum mainnet, forcing operators to maintain dual rails with traditional payment processors and eroding automation savings.
- Biometric sensor integration costs:Professional teams demand heart-rate and eye-tracking telemetry ingestion that requires specialized hardware procurement and calibration expertise not available in standardized SaaS tiers.
Strategic Opportunities
- Japan scholastic esports expansion:METI-backed digital education initiatives are opening procurement channels for tournament management platforms adapted to compulsory school league structures with localized compliance frameworks.
- AI-assisted match adjudication:Convergence of computer vision and natural language processing is enabling automated referee support for rule enforcement in complex multiplayer titles, reducing human official costs for large-scale events.
- India mobile-first tournament penetration:Low PC ownership rates and TRAI data cost reductions are creating white space for cloud-streamed tournament platforms serving Battlegrounds Mobile India and similar titles through smartphone-native interfaces.
Industry Challenges
- Multi-title API standardization:Game publishers maintain incompatible data export formats for match telemetry, forcing platform developers to maintain fragmented integration pipelines that delay feature parity across supported titles.
- Live operations talent scarcity:Tournament execution requires hybrid competencies spanning broadcast production, competitive ruleset adjudication, and real-time technical troubleshooting that training pipelines have not scaled to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esports Management Software Market |
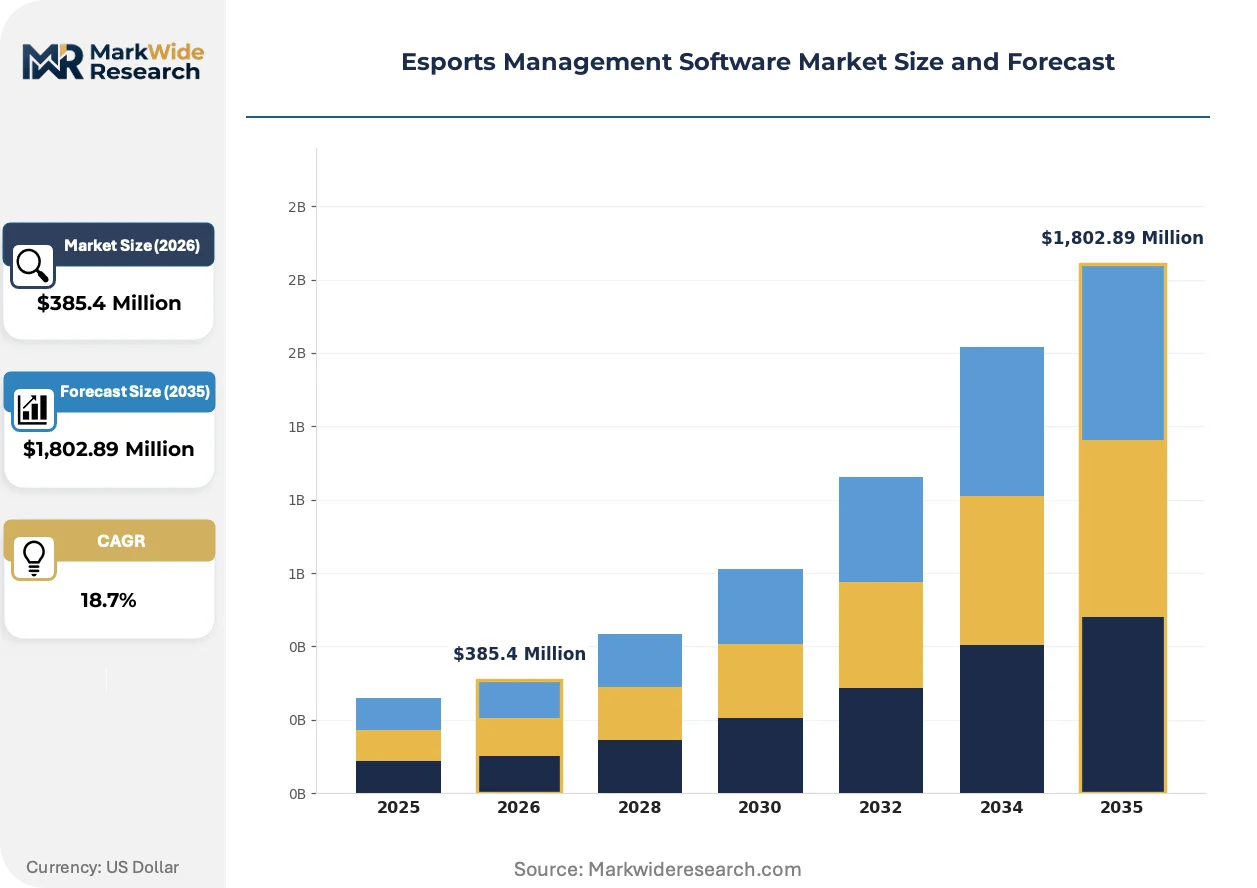
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Team Management, Tournament Management, Game Analytics, Fan Engagement End User: Professional Teams, Amateur Teams, Event Organizers, Streaming Platforms Delivery Model: Cloud-Based, On-Premises, Hybrid, Subscription-Based Feature: Match Scheduling, Performance Tracking, Revenue Management, Community Tools |
| Companies Covered | SENET, Battlefy, PlayVS, Challengermode, Award Pool, rSchoolToday, Siriusnet, ggLeap, Digitain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esports Management Software Market Shifts & Advancements
Real-time data streaming architectures and automated compliance tooling are displacing manual tournament administration workflows across the competitive gaming value chain. Platform vendors are embedding machine learning modules that compress operational overhead while expanding monetization surface area.
Edge computing nodes deployed at venue locations are electrifying latency-sensitive match adjudication and spectator broadcast synchronization. Large-scale tournament organizers in Los Angeles and Stockholm are adopting localized processing clusters that reduce round-trip delays for frame-perfect competitive integrity verification. This infrastructure shift is enabling synchronous multi-venue events that previously required centralized data center dependency.
EU AI Act risk classification requirements are mandating algorithmic transparency documentation for automated matchmaking and anti-cheat systems deployed in European tournaments. Platform providers must now maintain technical file repositories demonstrating human oversight mechanisms for AI-driven competitive decisions. German and French league operators are front-loading compliance costs to secure early mover positioning ahead of enforcement timelines.
Collegiate athletic departments are consolidating vendor relationships through multi-year enterprise agreements that bundle tournament management with academic program tracking and scholarship administration. Procurement committees at Texas and California universities are replacing point solutions with integrated platforms that serve competitive operations and institutional reporting requirements through unified data layers. This pattern concentrates contract value with vendors demonstrating FERPA-compliant student data handling and NCAA eligibility integration capabilities.
Esports Management Software Market Segmentation
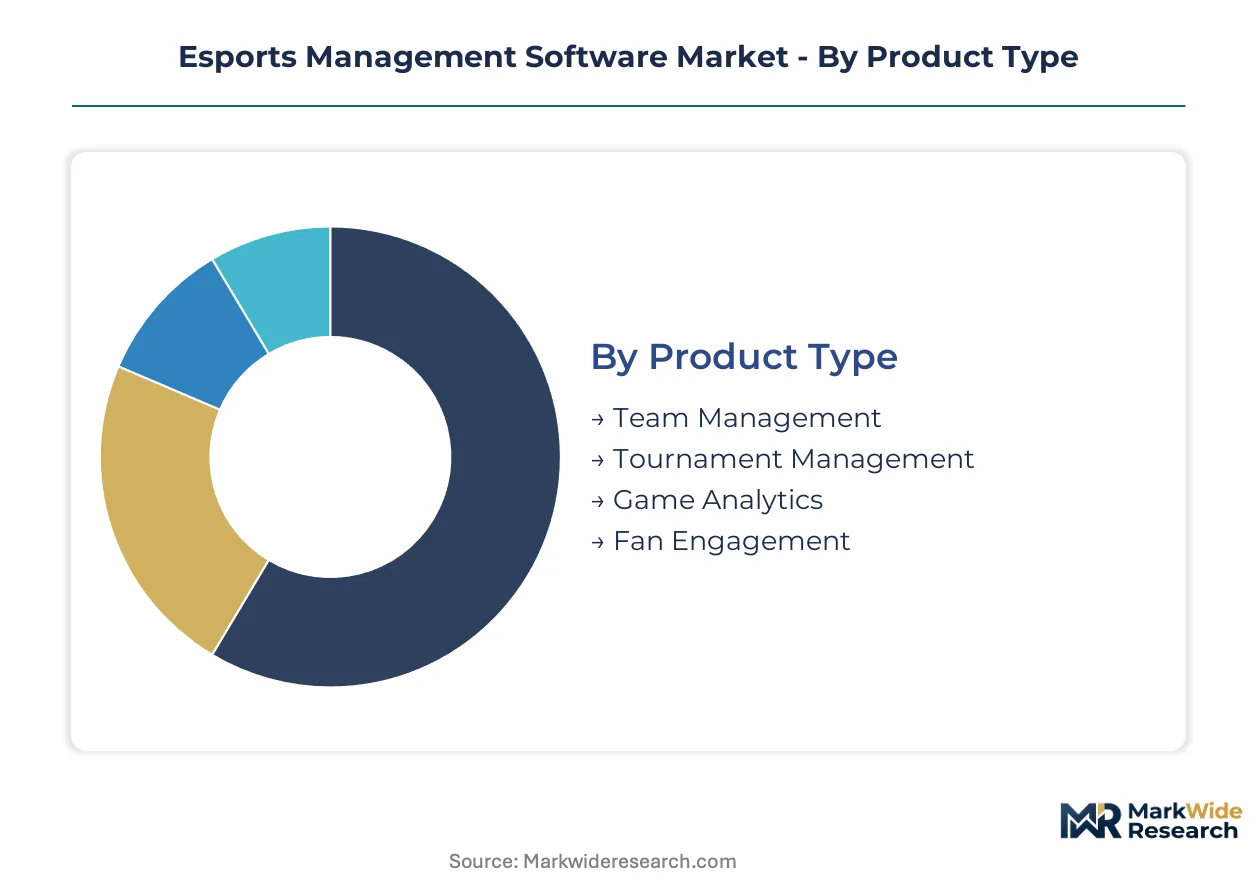
Esports management software segments reflect divergent procurement economics between revenue-generating tournament operations and cost-center team administration functions. Platform vendors architect tiered product strategies that align subscription pricing with the monetization potential of each user category.
Product Type:
Tournament Management commands premium pricing given its direct linkage to prize pool administration and broadcast revenue, while Team Management spreads across volume tiers serving amateur and professional organizations with differentiated feature depth.
- Tournament Management:Bracket engines, match scheduling algorithms, and automated prize distribution smart contracts anchor enterprise contracts. Large-scale event organizers in the United States and Germany drive procurement for platforms handling million-dollar prize pools with real-time integrity monitoring.
- Game Analytics:Player performance telemetry ingestion and biometric data visualization represent the steepest expansion trajectory as professional teams invest in competitive optimization. GDPR Article 9 constraints in Europe are shaping privacy-compliant platform architectures that process telemetry without capturing protected health data.
- Team Management:Roster administration, contract tracking, and scrim coordination tools serve volume markets across collegiate and amateur tiers.
- Fan Engagement:Community moderation, content distribution, and sponsorship attribution modules extend platform monetization beyond core operations.
Today's leader: Tournament Management. Tomorrow's challenger: Game Analytics.
End User:
Procurement authority concentrates with organizations possessing direct revenue streams from competitive operations, while cost-sensitive amateur segments drive platform self-service adoption and API-first integration strategies.
- Event Organizers:Enterprise-grade platforms with real-time match adjudication and broadcast synchronization anchor the highest contract values. Nevada-licensed wagering operators mandate integrity monitoring integrations that reshape vendor qualification requirements.
- Professional Teams:Performance optimization suites with biometric sensor ingestion and scouting database integration command premium subscriptions. European organizations navigate GDPR constraints on player behavioral analytics that constrain data monetization pathways.
- Streaming Platforms:Tournament broadcast rights holders require API depth for real-time overlay generation and sponsorship attribution tracking.
- Amateur Teams:Self-service tiers with reduced feature depth serve volume markets through freemium conversion funnels.
Revenue concentrates with Event Organizers. Growth accelerates fastest among Professional Teams.
Delivery Model:
Cloud-native architectures displace on-premise tournament infrastructure across procurement tiers, though security-conscious professional leagues maintain hybrid deployments for multi-million dollar competitive integrity requirements.
- Cloud-Based:Hyperscale delivery dominates collegiate and independent organizer procurement, compressing deployment timelines from months to days. Concentrated infrastructure dependencies in Virginia and Frankfurt create contractual redundancy requirements for high-stakes events.
- Hybrid:Localized processing clusters at venue locations serve latency-sensitive match adjudication for synchronous multi-venue tournaments. Stockholm and Los Angeles organizers deploy edge computing nodes that reduce round-trip delays for frame-perfect integrity verification.
- On-Premises:Legacy tournament operators in regulated wagering jurisdictions maintain captive infrastructure for compliance isolation.
- Subscription-Based:Recurring revenue architectures align vendor incentives with customer success across tiered feature access levels.
Cloud-Based deployments capture current volume. Hybrid architectures gain share fastest among security-sensitive professional tiers.
Feature:
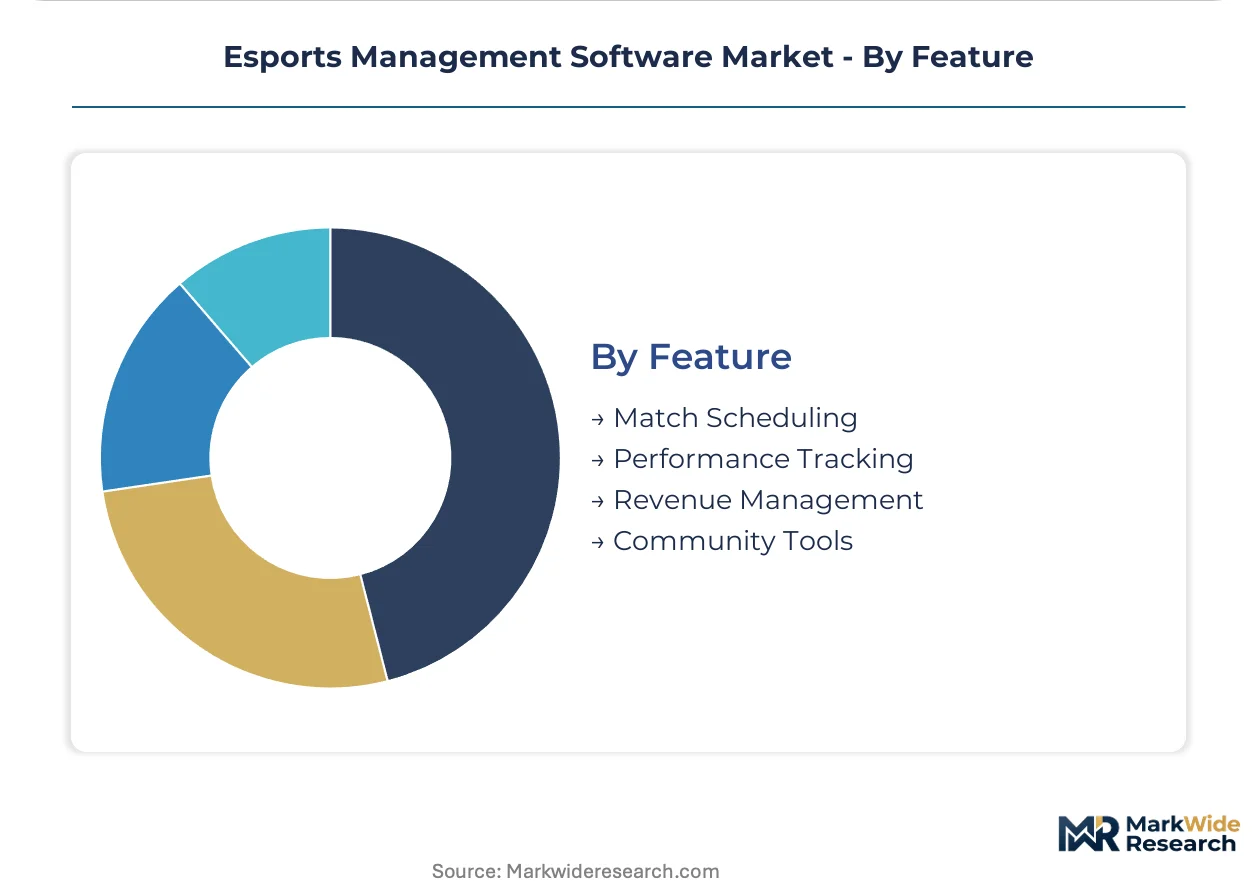
Core operational functionality anchors initial platform adoption, while monetization-enabling modules drive expansion revenue and competitive differentiation in mature procurement relationships.
- Match Scheduling:Algorithmic bracket generation and real-time resiliency protocols form the foundational capability across all platform tiers. API standardization gaps between game publishers force vendors to maintain fragmented integration pipelines that delay feature parity.
- Revenue Management:Sponsorship attribution, broadcast rights tracking, and prize pool administration command premium module pricing. EU AI Act documentation requirements for automated financial algorithms are front-loading compliance costs for European tournament operators.
- Performance Tracking:Telemetry ingestion and statistical visualization serve team-facing use cases with biometric sensor integration costs limiting standardized SaaS penetration.
- Community Tools:Moderation automation and fan engagement analytics extend platform stickiness beyond competitive operations.
Match Scheduling anchors platform stickiness. Revenue Management expands contract value fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the esports management software demand map through its concentration of tournament organizers, professional team headquarters, and broadcast production facilities. The United States, Germany, China, Japan, and India concentrate platform procurement across collegiate programs, independent leagues, and wagering-licensed operators. Regulatory divergence between entertainment classification and sports governance regimes shapes compliance cost trajectories in each jurisdiction.
United States
Collegiate athletic departments in Texas and California drive enterprise platform contracting with multi-year agreements bundling tournament operations and academic tracking. FCC broadcast content guidelines and Nevada wagering regulations mandate integrity monitoring integrations for licensed operators. Los Angeles tournament organizers deploy edge computing clusters at venue locations to reduce latency for frame-perfect match adjudication.
Germany
Professional leagues in Berlin and Hamburg procure privacy-certified analytics platforms that process player telemetry without capturing GDPR Article 9 protected health data. The EU AI Act mandates algorithmic transparency documentation for automated matchmaking systems, front-loading compliance costs for platform providers. Frankfurt's hyperscale infrastructure concentration creates contractual redundancy requirements for million-dollar prize pool events.
China
Mobile-first tournament penetration accelerates in low-PC-ownership regions where cloud-streamed platforms serve smartphone-native competitive gaming interfaces. The country's national data governance frameworks constrain cross-border player biometric data transfers, forcing localized platform architectures. Shanghai and Shenzhen organizers lead adoption of real-time broadcast synchronization systems for synchronous multi-venue events.
Japan
METI-backed digital education initiatives open procurement channels for tournament management platforms adapted to compulsory school league structures. Osaka and Tokyo scholastic operators demand localized compliance frameworks for student data handling within integrated academic and competitive operations. The country's national esports federation classification standards shape platform feature roadmaps for amateur-to-professional pipeline management.
India
TRAI data cost reductions and low PC ownership rates create white space for cloud-streamed tournament platforms serving mobile-native competitive titles. Bangalore and Mumbai independent organizers drive volume adoption through self-service tiers with API-first integration strategies. The country's national education technology procurement programs are beginning to incorporate esports league management into digital campus infrastructure specifications.
Esports Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized verticals and geographic niches. The vendor base stratifies across enterprise-grade tournament operators, scholastic-focused platforms, and developer-facing API infrastructure providers. Three archetypes dominate: cloud-native architecture specialists, scholastic league management platforms, and legacy bracket engine modernizers. Competitive moves concentrate on strategic partnerships with game publishers and API ecosystem expansion to embed third-party broadcast and sponsorship modules.
Within the cloud-native tier, SENET anchors enterprise-grade tournament operations for large-scale event organizers. Battlefy exemplifies developer-facing API depth that competes with legacy bracket infrastructure. PlayVS occupies the scholastic specialization vector, dominating North American high school and collegiate contracting channels through FERPA-compliant student data handling capabilities.
| Leading Market Players |
|---|
| SENET |
| Battlefy |
| PlayVS |
| Challengermode |
| Award Pool |
| rSchoolToday |
| Siriusnet |
| ggLeap |
| Digitain |
| Others |
Supply & Pricing Matrix
Cloud-native architecture outsourcing anchors supply positioning while compressing platform development costs and subscription pricing flexibility across vendor tiers. Tournament operators in Nevada and New Jersey negotiate SaaS contracts that bundle integrity monitoring modules with base licensing, while European organizers absorb GDPR compliance premiums that widen pricing spreads between privacy-certified and standard tiers.
Pricing Analysis
Input-cost pass-through from hyperscale cloud infrastructure providers in Virginia and Frankfurt shapes subscription tiering across the market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise tournament organizers with million-dollar prize pool requirements from collegiate programs and amateur teams. Pricing pressure stems from API standardization gaps that force vendors to maintain fragmented integration pipelines, eroding margin leverage. Amateur teams and independent organizers exhibit highest price sensitivity, while wagering-licensed operators accept premium pricing for compliance-embedded modules.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Frankfurt, and Singapore anchor hub-and-spoke delivery patterns for edge computing nodes deployed at tournament venues. Software development draws from engineering talent pools in the United States, Germany, and India, with cloud infrastructure provisioning concentrated through hyperscale providers. Single-source vulnerability in AWS and Azure concentration creates contractual redundancy requirements for high-stakes events. Distribution runs through direct enterprise sales for professional tiers and self-service web portals for volume amateur adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Nevada wagering legalization and EU AI Act enforcement timelines accelerate procurement for compliance-embedded platforms.
For Market Incumbents: Deepen API ecosystem control through publisher partnership exclusives that lock in telemetry integration pipelines before standardization efforts mature. Fortify against emerging cloud-native entrants by embedding FERPA-compliant student data handling that scholastic procurement committees now mandate. Expand vertical integration into edge computing hardware provisioning for synchronous multi-venue tournament operators. For New Entrants and Emerging Players: Begin with white-space penetration in India's mobile-first tournament infrastructure where TRAI data cost reductions and low PC ownership create unserved demand. Target Japanese compulsory school league structures where METI-backed digital education initiatives open procurement channels absent entrenched competitors. Pursue API-first integration strategies that bypass direct platform competition through broadcast overlay and sponsorship attribution modules. For Investors and Strategic Acquirers: Roll-up economics work for privacy-certified platform specialists because GDPR Article 9 constraints and EU AI Act documentation requirements create compliance moats that generalist vendors cannot replicate. Five-to-ten year viability hinges on tournament wagering legalization momentum across additional state jurisdictions. Monitor Nevada and New Jersey licensing velocity as the inflection signal for integrity monitoring module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API depth with game publisher telemetry systems anchors competitive differentiation for tournament operators. |
| Strategic Partnership | Wagering license holders in Nevada mandate integrity monitoring partnerships that reshape vendor qualification requirements. |
| Geographic Expansion | Japanese scholastic league structures offer procurement channels through METI-backed digital education initiatives. |
| Acquisition of Specialist Firm | Biometric sensor calibration expertise addresses hardware integration gaps beyond standardized SaaS tiers. |
| Product Launch | AI-assisted match adjudication modules reduce human official costs for large-scale multiplayer events. |
Research Methodology
Bottom-up collegiate and professional team modeling reconciled against top-down cloud infrastructure provisioning tracking forms the analytical core of this study. Primary interviews with tournament operations directors, esports program administrators at Texas and California universities, CTOs at platform vendors, and wagering compliance officers combined with secondary validation from SEC filings of publicly traded gaming companies, FCC broadcast content guidelines, and state regulatory filings from Nevada and New Jersey. Triangulation across deployment model adoption rates and end-user procurement patterns anchored volume estimates.
Historical trendline analysis of SaaS subscription growth across cloud-native tournament platforms informed projection modeling across the analysis window. Segmentation dimensions include product type, end-user category, delivery model architecture, and regional regulatory framework cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating collegiate program expansion rates and wagering legalization momentum. Industry-specific inputs encompass API integration pipeline development timelines and edge computing node deployment patterns at multi-venue events.
Several conditions sit outside the modeled scope, including speculative federal esports wagering legislation and game publisher API standardization breakthroughs. Forecasts reflect assumptions about continued hyperscale cloud infrastructure availability and state-level regulatory divergence patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Online Fitness Market
Sports & Fitness
Europe Kickboxing Equipment Market
Sports & Fitness
Gear Bicycle Market
Sports & Fitness
Elliptical Trainers Market
Sports & Fitness
China Fitness Rings Market
Sports & Fitness
Europe Spectator Sports Market
Sports & Fitness
Middle East and Africa Sports Nutrition Market
Sports & Fitness
L-Carnitine Supplements Market
Sports & Fitness
US Sports Flooring Market
Sports & Fitness
Fantasy Sports Market
Sports & Fitness
Golf Ball Market
Sports & Fitness
Treadmill Desks Market
Sports & Fitness
Wireless Health and Fitness Devices Market
Sports & Fitness
Carbon Fiber Badminton Racket Market
Sports & Fitness
Smart Fitness Trainer Market
Sports & Fitness
Bike Saddles Market