
 North America Fantasy Sports Market | 2026-2036
North America Fantasy Sports Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fantasy Sports Market Analytics
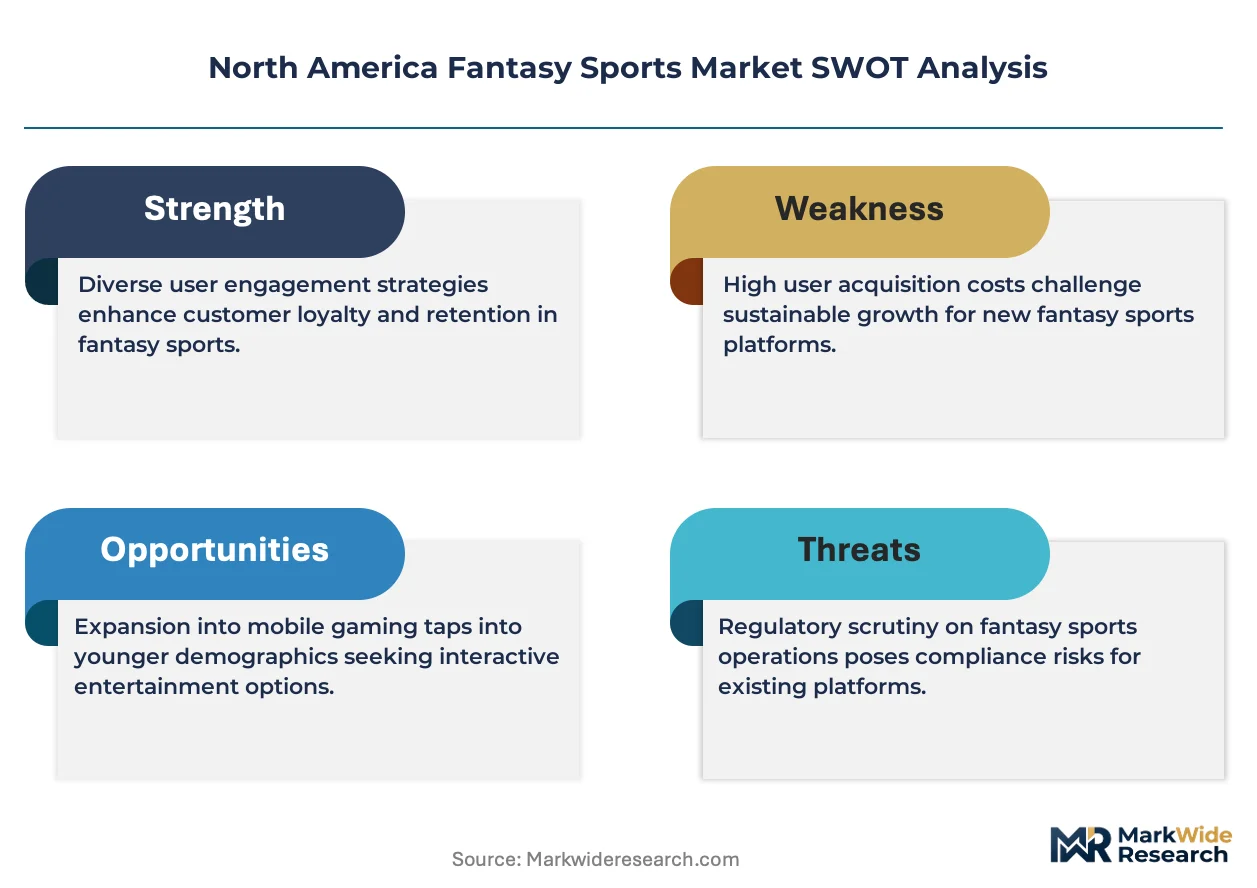
Artificial intelligence-driven predictive analytics is realigning player engagement economics across the North America fantasy sports landscape. DraftKings Inc. leverages machine learning models to personalize contest recommendations and extend session duration. FanDuel anchors its competitive position through proprietary scoring algorithms and real-time data feeds. Yahoo Fantasy Sports differentiates via integrated media ecosystems that bind fantasy gameplay to live sports consumption.
North America fantasy sports comprises digital platforms that host competitive contests where participants assemble virtual rosters of real-world athletes, with scoring derived from live statistical performance across professional leagues. These platforms operate on real-time data pipelines processing box scores, injury reports, and weather conditions to calculate points and determine contest outcomes. Daily Fantasy Sports commands the fastest expansion trajectory as shorter contest cycles attract time-constrained participants and enable higher entry-frequency monetization. Mobile App deployment dominates platform type distribution, reflecting smartphone-native user behavior and push-notification re-engagement mechanics that desktop channels cannot replicate.
The Federal Wire Act and state-level gaming commissions—including the Nevada Gaming Control Board and New Jersey Division of Gaming Enforcement—create a patchwork compliance environment that dictates where platforms may legally operate and how they must segregate player funds. The Unlawful Internet Gambling Enforcement Act shapes payment processing architectures, forcing operators to build specialized banking relationships for contest entry and prize distribution. Stakeholders must monitor pending state legislative sessions and tribal compact negotiations that could abruptly expand or contract addressable geographic markets.
Market Dynamics
State-level legalization of online sports betting is fragmenting addressable markets across the United States and Canada, forcing platforms to rebuild compliance architectures for each jurisdiction while tribal gaming compacts add negotiation complexity.
Growth Catalysts
- Mobile App Deployment:Smartphone-native interfaces with push-notification re-engagement mechanics capture time-constrained participants who abandon desktop channels.
- Daily Fantasy Sports Format:Shorter contest cycles enable higher entry-frequency monetization and attract casual players seeking immediate outcomes.
- Artificial Intelligence Integration:Machine learning models personalize contest recommendations and extend session duration through predictive player behavior analysis.
Market Restraints
- Regulatory Fragmentation:The Federal Wire Act and state-level gaming commissions create a patchwork compliance environment that restricts cross-border operations.
- Payment Processing Constraints:The Unlawful Internet Gambling Enforcement Act forces operators to build specialized banking relationships for contest entry and prize distribution.
- Tribal Compact Negotiations:Sovereign gaming agreements in California, Florida, and Oklahoma limit platform access to substantial player pools.
Strategic Opportunities
- Texas Market Opening:Pending legislative sessions in Austin could unlock the second-largest U.S. state population for platform expansion.
- Real-Time Data Convergence:Integration of live statistical feeds with wearable biometric sensors creates next-generation scoring mechanics.
- Social Betting Features:Peer-to-peer contest formats and league-based communities drive organic user acquisition through network effects.
Industry Challenges
- Responsible Gaming Compliance:State mandates for deposit limits, cooling-off periods, and self-exclusion protocols require continuous platform engineering investment.
- Data Latency Requirements:Sub-second scoring updates demand expensive low-latency data infrastructure that smaller operators cannot replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fantasy Sports Market |
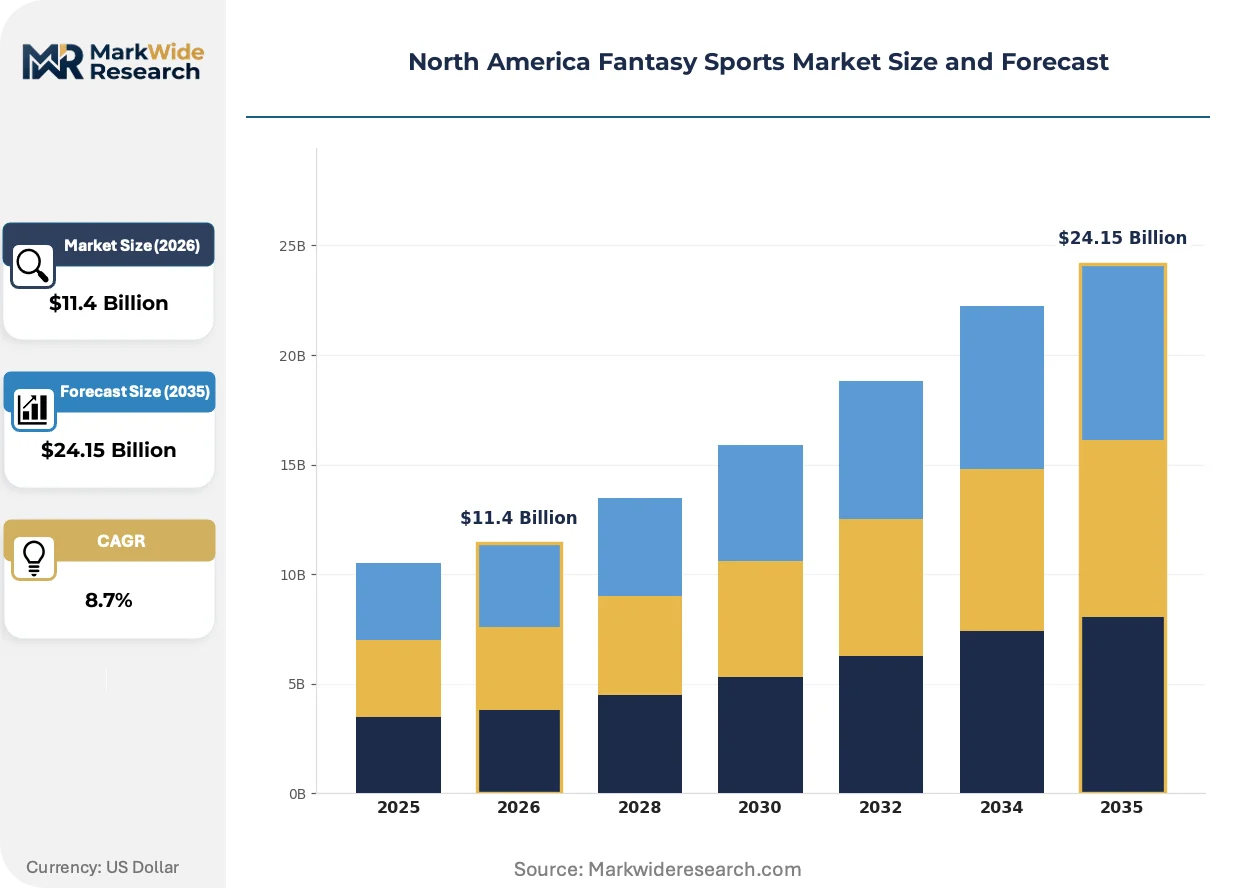
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Website, Mobile App, Social Media, Desktop Application Game Type: Daily Fantasy Sports, Season-long Fantasy Sports, Auction-based Fantasy Sports, Peer-to-Peer Fantasy Sports Customer Segment: Casual Players, Professional Players, Leagues, Teams Monetization Model: Entry Fee, Subscription Fee, Advertising Revenue, Sponsorship Deals |
| Companies Covered | DraftKings Inc., FanDuel, Yahoo Fantasy Sports, CBS Sports, ESPN, NBC Sports, Fox Sports, FantasyPros, PrizePicks, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fantasy Sports Market Evolving Landscape
Real-time data pipelines and artificial intelligence are compressing contest design cycles while regulatory technology investments reshape platform operating costs.
Machine learning-driven predictive analytics is expanding into player retention economics across North American fantasy sports platforms. Operators deploy recommendation engines that surface personalized contest formats based on historical entry patterns and risk tolerance profiles. Casual player segments in California and New York adopt these curated experiences at accelerating rates, compressing the gap between session initiation and monetary conversion.
The Unlawful Internet Gambling Enforcement Act continues forcing payment architecture redesigns across U.S.-facing platforms. Operators must segregate player funds from operational accounts and maintain specialized banking relationships that survive compliance audits. Daily Fantasy Sports providers in New Jersey and Pennsylvania invest most heavily in alternative payment rails including digital wallets and prepaid card networks.
Social gameplay mechanics are displacing solitary contest entry as the dominant engagement model. Peer-to-peer leagues and friend-group challenges replace anonymous large-field tournaments among younger demographic cohorts. Texas and Florida player bases demonstrate strongest affinity for community-driven formats that emphasize bragging rights over prize maximization.
North America Fantasy Sports Market Segmentation
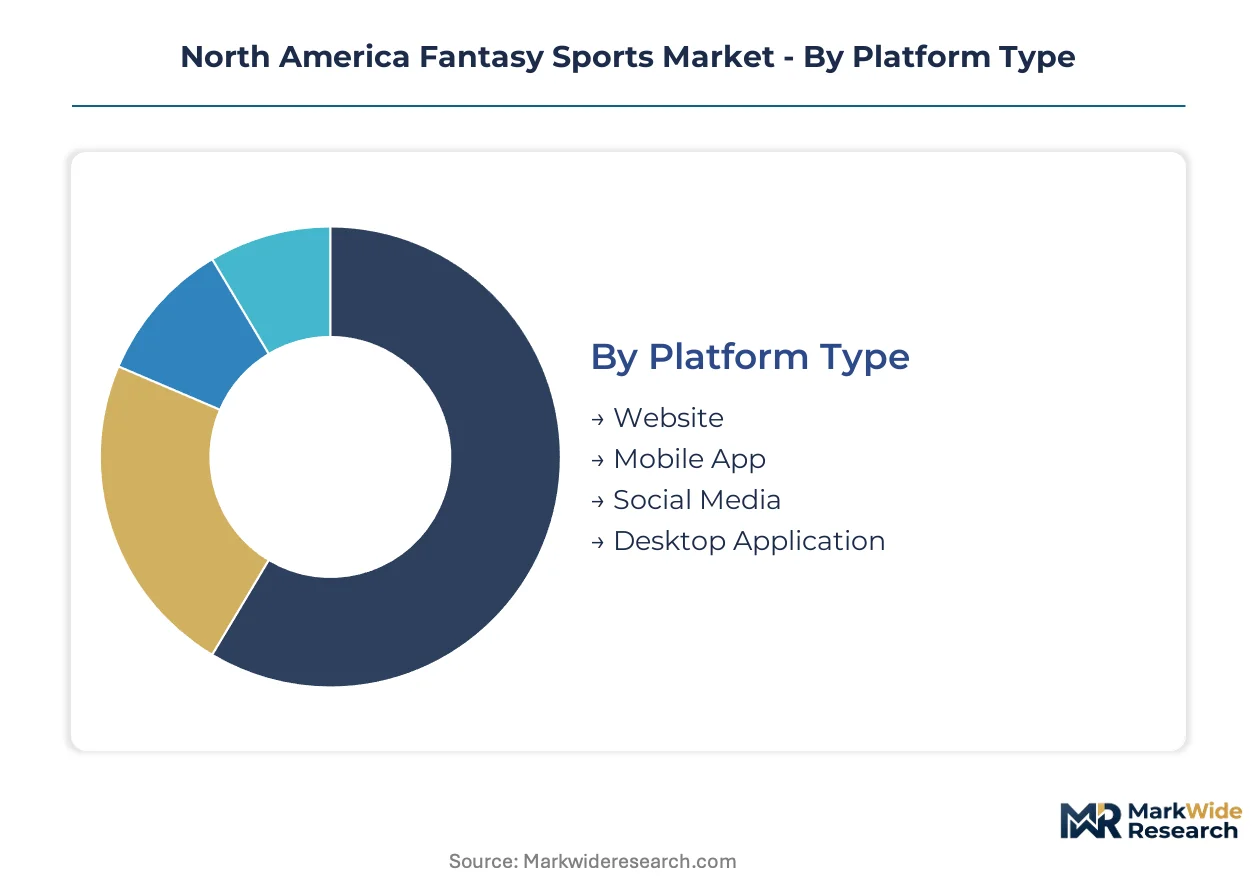
Platform architecture and game format selection directly determine customer lifetime value and regulatory exposure in North American fantasy sports. Segmentation reveals how mobile-native interfaces and compressed contest cycles capture casual player wallets while subscription models stabilize revenue against seasonal sports volatility.
Platform Type:
Device choice reflects player time constraints and re-engagement sensitivity more than demographic profile.
- Mobile App:Smartphone-native interfaces deploy push-notification mechanics to recapture fragmented attention spans. California and New York player bases show highest session frequency on iOS and Android deployments, driven by commute-time entry patterns and real-time injury alert responses.
- Website:Browser-based access retains professional players who demand multi-tab research capabilities and spreadsheet integration for lineup optimization. Desktop research workflows concentrate entry volume among high-stakes participants in Texas and Illinois.
- Social Media:Embedded contest formats within Meta and X ecosystems lower acquisition friction through friend-network invitations. Younger demographics in Florida adopt these entry points for low-stakes peer leagues.
- Desktop Application:Downloaded clients serve power users requiring offline draft preparation and advanced statistical modeling tools. Niche adoption persists among legacy season-long commissioners.
Volume sits with Mobile App; growth tilts toward Social Media.
Game Type:
Contest duration structures player risk tolerance and platform rake economics.
- Daily Fantasy Sports:Single-day or single-week contest cycles compress outcome timelines and multiply annual entry frequency. Casual players in California and New York drive fastest adoption curves for this format, attracted by immediate gratification and lower bankroll commitment.
- Season-long Fantasy Sports:Multi-month roster management binds participants through draft preparation, waiver wire activity, and playoff brackets. Traditional leagues dominate Texas social circles where commissioner culture and trophy traditions sustain engagement across NFL and MLB calendars.
- Auction-based Fantasy Sports:Salary cap bidding mechanics replace snake drafts with real-time player valuation auctions. Niche adoption concentrates among experienced players seeking deeper strategic complexity.
- Peer-to-Peer Fantasy Sports:Direct head-to-head contests between known opponents emphasize social stakes over prize pools. Friend-group challenges expand most quickly in Florida and Georgia through organic network referrals.
Season-long Fantasy Sports holds volume leadership; Daily Fantasy Sports claims the steepest expansion trajectory.
Customer Segment:
Engagement depth and monetization potential diverge sharply across player sophistication tiers.
- Casual Players:Low-frequency entrants with small bankrolls and limited research investment. This segment concentrates in California and New York where mobile convenience drives impulse entry during major sporting events.
- Professional Players:High-volume entrants deploying algorithmic lineup optimization and bankroll management. Texas hosts the densest concentration of these players due to favorable tax treatment and established DFS infrastructure.
- Leagues:Organized private groups with recurring seasonal commitments and pooled prize structures. Corporate leagues in Illinois and Pennsylvania sustain platform stickiness through workplace social dynamics.
- Teams:Franchise-branded fantasy experiences tied to official NBA, NFL, and MLB club partnerships. Sponsored contests deepen fan engagement for team-specific player bases.
Professional Players generate highest per-capita revenue; Casual Players deliver the broadest addressable base.
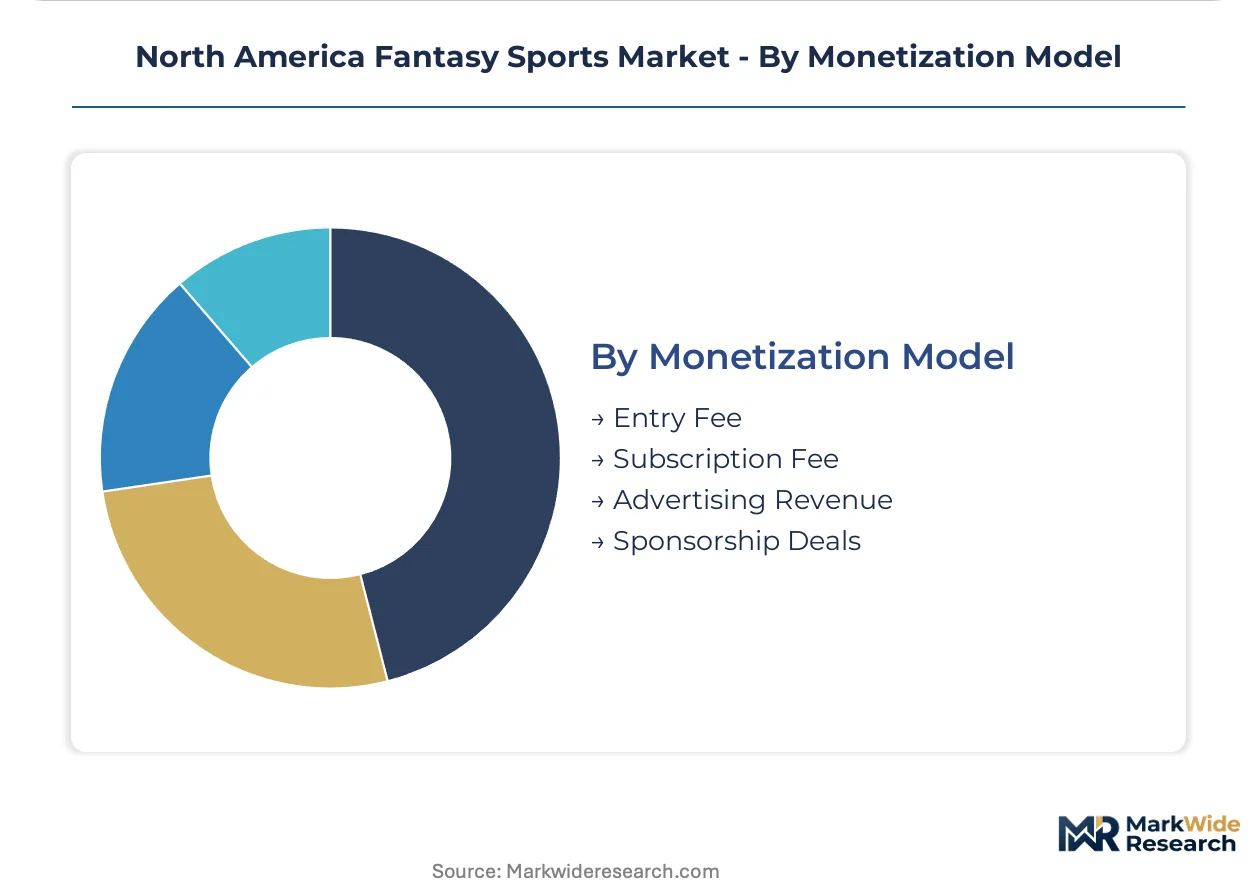
Monetization Model:
Revenue architecture balances transaction friction against predictability of cash flows.
- Entry Fee:Per-contest rake models dominate Daily Fantasy Sports, capturing percentage of prize pools with each transaction. This model concentrates revenue in high-frequency casual player segments.
- Subscription Fee:Monthly or annual premium tiers unlock advanced analytics, lineup optimizers, and reduced transaction fees. Professional players in Texas and Illinois show highest conversion to recurring payment structures.
- Advertising Revenue:Sponsored content and display placements monetize free-to-play user bases. Sportsbook and beverage brands target California and New York impressions during NFL season peaks.
- Sponsorship Deals:League and team partnerships embed branded contests and exclusive prize experiences. Official NFL and NBA affiliations command premium placement in platform marketing.
Entry Fee models capture transaction volume; Subscription Fee structures gain share among retention-focused operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform participation concentrates in the United States where state-level regulatory openings and mobile penetration sustain the deepest player pools. Canada and Mexico present adjacent expansion corridors with distinct compliance requirements and adoption curves.
United States
California, Texas, and New York host the largest active user bases where mobile-first entry patterns dominate commute-time engagement. The Federal Wire Act and state gaming commissions—including the Nevada Gaming Control Board and New Jersey Division of Gaming Enforcement—enforce segregated fund requirements and cross-border restrictions. Greater Boston and the Pacific Northwest sustain concentrated professional player communities with algorithmic lineup optimization practices.
Canada
Ontario and Quebec drive provincial adoption through regulated single-game sports betting frameworks launched in 2022. Health Canada and provincial lottery corporations administer compliance while the Criminal Code exemptions for skill-based contests enable DFS platform operations. Toronto and Vancouver clusters concentrate advertising expenditure and partnership activations with NHL and NBA franchises.
Mexico
Mexico City Metro and Nuevo León exhibit emerging demand among smartphone-native demographics following 2021 federal gaming law modernizations. The Secretariat of the Interior and state-level gaming authorities license operators under consolidated regulatory frameworks. Jalisco and the Bajío Region demonstrate fastest mobile download velocity for fantasy football applications during NFL season windows.
North America Fantasy Sports Market Competitive Landscape
Strategic partnerships dominate the current landscape as platforms secure exclusive data rights and league affiliations to differentiate real-time scoring capabilities. The vendor structure consolidates around three integrated sportsbook-fantasy hybrids and a tier of specialized DFS operators, with long-tail fragmentation among season-long hosting services. Archetypes include vertically integrated media-gaming conglomerates, pure-play daily fantasy specialists, and legacy broadcasters extending digital engagement tools. Portfolio diversification and technology licensing represent the primary competitive vectors as operators expand into adjacent wagering formats and predictive analytics services.
Within the vertically integrated tier, DraftKings Inc. and FanDuel exemplify scale-driven platform economics where real-time data convergence and personalized recommendation engines anchor customer retention strategies. Yahoo Fantasy Sports occupies a distinct position binding fantasy gameplay to integrated media ecosystems and live sports consumption patterns.
| Leading Market Players |
|---|
| DraftKings Inc. |
| FanDuel |
| Yahoo Fantasy Sports |
| CBS Sports |
| ESPN |
| NBC Sports |
| Fox Sports |
| FantasyPros |
| PrizePicks |
| Others |
Value Network & Pricing Analysis
Casual player concentration in California and New York drives the dominant entry-fee transactional model, where per-contest rake structures capture fragmented, impulse-driven demand that subscription tiers cannot consolidate. This buyer archetype's price sensitivity forces operators to absorb data infrastructure costs rather than pass them through, compressing margins on high-frequency, low-stakes transactions.
Pricing Analysis
High-volume casual segments trade margin for liquidity while professional players in Texas sustain premium subscription tiers. Entry-fee rake models dominate Daily Fantasy Sports, with price differentiation resting on analytics depth and lineup optimization tool access. Pricing pressure stems from escalating real-time data licensing costs that operators struggle to recoup from price-sensitive entrants. Casual players exhibit highest price sensitivity; professional segments tolerate recurring fees for competitive tooling.
Supply Chain Analysis
Direct-to-platform app stores and proprietary mobile infrastructure handle hyperscale user demand across iOS and Android ecosystems. Data pipeline concentration centers on the United States, Canada, and United Kingdom for live statistical feeds and injury reporting. Raw material dependencies include real-time sports data APIs, cloud computing infrastructure, and push-notification delivery networks. Supply chain risk runs through single-source vulnerability in exclusive league data partnerships with the NFL, NBA, and MLB. Distribution feeds from app store ecosystems and direct mobile web channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory licensing scarcity props pricing power as state-level approvals lag platform technology deployment, creating artificial supply constraints that sustain incumbent margins despite competitive pressure.
For Market Incumbents: Deepen proprietary data integration through exclusive league partnerships that lock out competitor access to real-time scoring feeds. Fortify compliance architecture against Federal Wire Act reinterpretation risks that could fragment interstate contest pools. Anchor retention through AI-driven personalization that casual players cannot replicate without equivalent infrastructure investment. For New Entrants and Emerging Players: Launch via embedded social media distribution that bypasses app store acquisition costs and leverages organic network effects. White-space concentration sits in peer-to-peer league formats across Texas and Florida where tribal compact restrictions limit established operator penetration. Target corporate workplace leagues in Illinois and Pennsylvania through B2B sales motion with HR wellness budgets. For Investors and Strategic Acquirers: The window for entry favors technology-licensing specialists with real-time data pipeline capabilities over pure-play contest operators. Long-term viability hinges on regulatory technology moats and exclusive content relationships rather than user base scale alone. Watch pending tribal gaming compact renegotiations in California as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive League Data Partnership | Locks real-time scoring access against competitor replication through NFL, NBA, or MLB affiliation. |
| Regulatory Technology Investment | Builds compliance automation that survives state gaming commission audits and accelerates geographic expansion. |
| AI Personalization Engine Deployment | Extends session duration through DraftKings-style machine learning recommendation systems. |
| Social Betting Feature Integration | Captures Florida and Georgia demand for peer-to-peer contest formats over anonymous tournaments. |
| Alternative Payment Rail Development | Reduces UIGEA exposure through digital wallet and prepaid card infrastructure in New Jersey and Pennsylvania. |
Research Methodology
Multi-period observation of state legislative calendars, player fund segregation requirements, and mobile download velocity anchored the trend analysis, supplemented by interviews with platform compliance officers, daily fantasy sports product managers, state gaming commission regulators, and sports data feed procurement leads. Secondary validation drew from Federal Wire Act interpretations, state gaming enforcement division filings, SEC 10-K disclosures by listed operators, and app store analytics platforms. Bottom-up contest volume modeling triangulated against top-down advertising expenditure estimates.
Segment-weighting across platform type, game format, customer sophistication tier, and monetization model structured the analytical framework over the projection horizon. CAGRs derived from cohort-based user acquisition cost trajectories and lifetime value retention curves across casual and professional player segments. Real-time data infrastructure cost curves and state-level regulatory opening probabilities served as industry-specific forecast inputs.
Pending tribal compact renegotiations, Federal Wire Act enforcement shifts, and payment processor relationship stability are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding state legalization velocity and mobile penetration saturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Fantasy Sports Market
Sports Analytics
Youth Sports Software Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
India Fantasy Sports Market