
 Product Life Cycle Management (PLM) Market | 2026-2036
Product Life Cycle Management (PLM) Market Size, Share, and Industry Trends Forecast 2026-2036
Product Life Cycle Management (PLM) Market Analysis
Carbon-intensive server infrastructure is shifting toward low-energy cloud data centers across major PLM deployments. Siemens anchors European industrial software through deep manufacturing domain expertise. PTC leverages its IoT-integrated platform architecture to differentiate in connected product environments. Autodesk competes on design-centric workflows that extend from concept engineering through manufacturing handoff.
Product Life Cycle Management comprises software systems, services, and methodologies governing a product's evolution from conceptual design through retirement, typically incorporating version control, bill-of-materials management, and cross-functional workflow orchestration across distributed engineering teams. Its primary commercial purpose centers on compressing development cycles while ensuring regulatory traceability and supply chain synchronization. Cloud Services represent the fastest-expanding delivery mode as manufacturers abandon capital-intensive on-premise installations. The Pharmaceuticals application segment commands premium pricing due to FDA and EMA validation requirements that demand audit-ready documentation trails. AI technology integration is creating new margin pools in predictive maintenance and generative design automation.
FDA 21 CFR Part 11 and EU MDR frameworks mandate electronic records integrity that directly expands validated PLM system requirements in medical device and pharmaceutical sectors. China's NMPA and GB standards are tightening product data localization rules that reshape cloud deployment architectures for multinational manufacturers. Germany's KBA enforces type-approval documentation standards that automotive suppliers must embed within PLM workflows. Stakeholders must evaluate sovereign data requirements against platform interoperability before committing to regional hosting strategies.
Market Dynamics
Cloud-native architectures are displacing on-premise legacy systems as aerospace and automotive manufacturers prioritize scalable digital infrastructure for complex component traceability. This structural shift compresses deployment timelines while demanding sovereign data compliance across fragmented regulatory jurisdictions.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records integrity mandates in medical device and pharmaceutical sectors expand validated PLM system requirements, creating audit-ready documentation obligations that only specialized platforms satisfy.
- Generative design automation:AI technology integration creates new margin pools by compressing concept-to-prototype cycles for industrial machinery producers seeking competitive speed advantages.
- Germany's automotive supplier density:KBA type-approval documentation standards enforce embedded PLM workflows, anchoring regional deployment intensity among tier-one component manufacturers.
Market Restraints
- Legacy system lock-in:Capital-intensive on-premise installations create switching costs that delay cloud migration timelines for established manufacturing enterprises.
- Data localization mandates:China's NMPA and GB standards tighten product data residency rules, forcing architectural fragmentation that increases operational complexity for multinational deployments.
- Skills scarcity:Shortage of engineers proficient in both manufacturing domain expertise and cloud architecture limits implementation velocity across mid-market manufacturers.
Strategic Opportunities
- EU AI Act compliance:Risk-based AI system classification creates demand for traceability infrastructure that PLM platforms can extend into algorithm governance workflows.
- Pharmaceuticals application expansion:EMA validation requirements beyond FDA jurisdictions open premium pricing segments in European generic drug manufacturing.
- IoT-integrated predictive maintenance:Convergence of sensor telemetry with PLM asset records enables outcome-based service contracts for industrial equipment OEMs.
Industry Challenges
- Multi-tenant security certification:Achieving ISO 27001 and SOC 2 compliance for cloud-native architectures extends sales cycles with risk-averse aerospace and defense contractors.
- Cross-platform interoperability:Siemens, PTC, and Autodesk data formats resist standardization, forcing costly middleware development for enterprises with heterogeneous supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Life Cycle Management (PLM) Market |
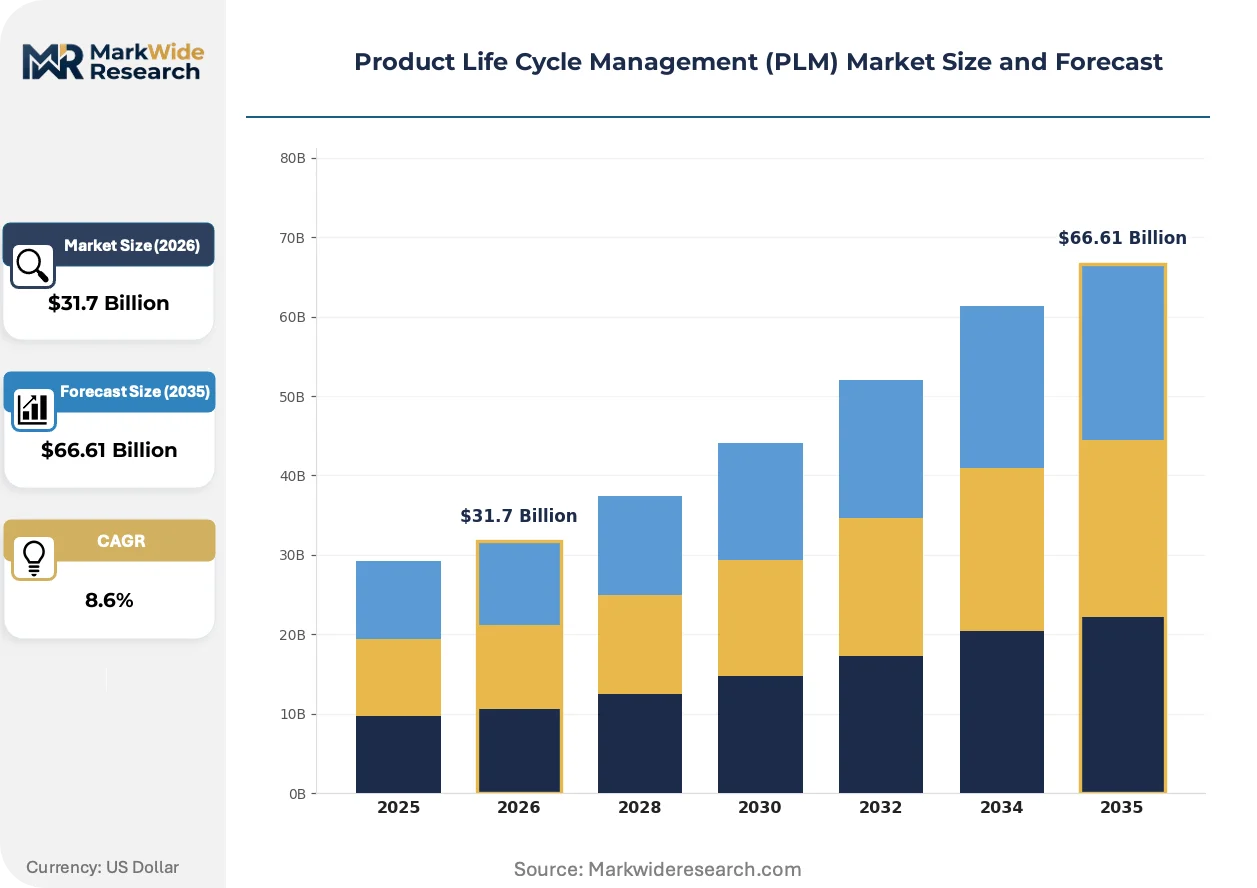
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $66.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Consulting, Integrated Solutions, Cloud Services Application: Aerospace, Consumer Electronics, Automotive, Pharmaceuticals End User: Manufacturers, Retailers, Suppliers, Service Providers Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Aras, Arena Solutions, Siemens, Autodesk, Centric Software, PTC, Propel, Oracle, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
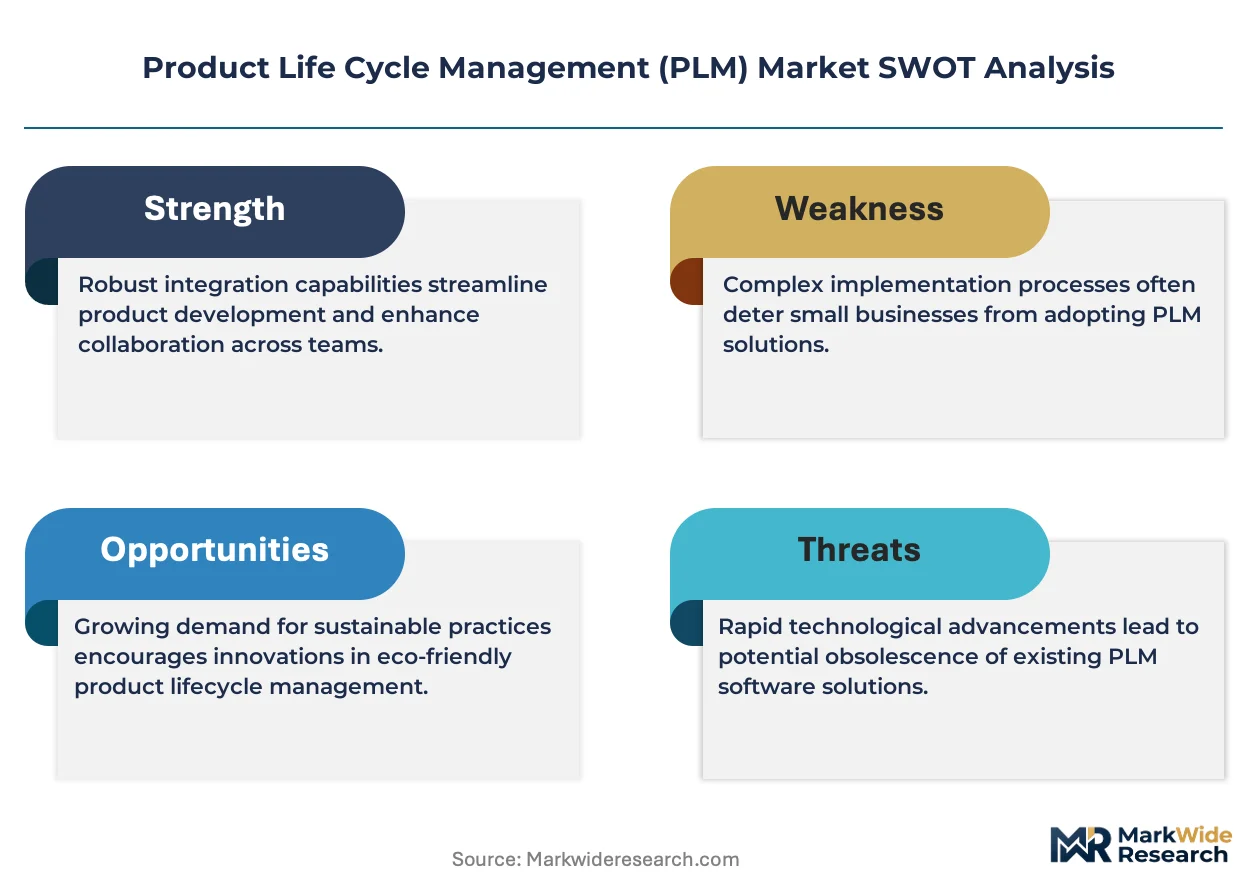
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Life Cycle Management (PLM) Market Emerging Trajectories
Digital thread architectures are actively reshaping how manufacturers connect engineering design to field performance data. This convergence demands platform capabilities that span previously siloed enterprise systems.
Digital twin technology is expanding into operational environments by creating real-time virtual replicas of physical assets. Automotive OEMs in Germany and aerospace manufacturers in the US are deploying these models at accelerating velocity. This capability is compressing warranty cost exposure by enabling predictive intervention before field failures materialize.
EU MDR framework implementation tightens post-market surveillance documentation requirements for medical device manufacturers. The regulation mandates systematic traceability from design inputs through adverse event reporting. Class III implantable device producers face the steepest compliance burden, driving consolidation toward validated PLM providers with established quality management module expertise.
Subscription pricing models are replacing perpetual license structures across mid-market manufacturing segments. Channel partners and direct sales teams now emphasize annual recurring revenue arrangements that bundle implementation services. This shift is most visible among US-based industrial machinery producers seeking to convert capital expenditure into operational expenditure for balance sheet flexibility.
Product Life Cycle Management (PLM) Market Segmentation
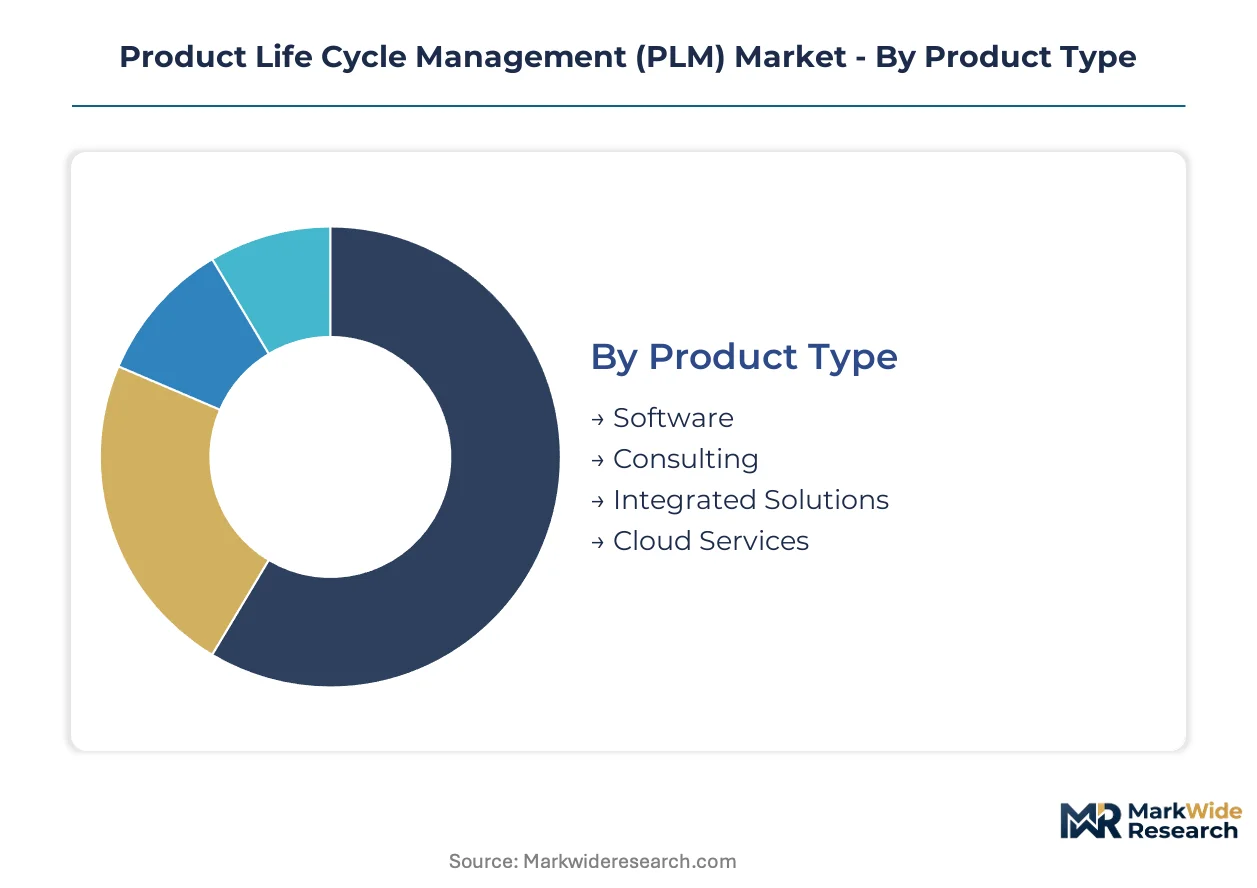
PLM procurement patterns diverge sharply by capital commitment and technical sophistication. Enterprises with heavy compliance burdens gravitate toward integrated stacks, while cost-sensitive mid-market players favor modular cloud deployments.
Product Type:
Capital intensity varies enormously across delivery modes, with perpetual on-premise licenses demanding seven-figure upfront commitments versus pay-as-you-grow cloud subscriptions.
- Software:Core PLM platforms manage version control, bill-of-materials hierarchies, and engineering change orders through centralized repositories. German automotive OEMs anchor demand here, driven by KBA type-approval documentation mandates that require immutable audit trails.
- Cloud Services:Multi-tenant architectures eliminate data center capital expenditure while enabling elastic compute for simulation workloads. Aerospace manufacturers in the US are migrating fastest, prioritizing scalable infrastructure for complex component traceability across distributed supplier networks.
- Consulting:Implementation partners configure workflows and migrate legacy data. Demand concentrates among mid-market manufacturers lacking internal cloud architecture expertise.
- Integrated Solutions:Bundled hardware-software stacks combining edge devices with PLM backbones. Industrial machinery producers favor these for factory-floor connectivity.
Most installed capacity flows through Software. Expansion is steepest in Cloud Services.
Application:
Regulatory burden intensity determines pricing power, with medical-adjacent sectors commanding premiums for validated systems.
- Pharmaceuticals:Validated PLM environments satisfy FDA 21 CFR Part 11 and EMA requirements for electronic records integrity. Batch genealogy, deviation tracking, and audit-ready documentation drive deployment decisions. Generic drug manufacturers in India are accelerating adoption as CDSCO alignment with ICH guidelines tightens.
- Aerospace:AS9100 quality standards and FAA airworthiness directives mandate component-level traceability from raw material through field service. Defense contractors prioritize on-premise or sovereign-hosted architectures to satisfy ITAR data residency constraints.
- Automotive:Electrification programs compress development cycles while expanding software-defined vehicle complexity. Tier-one suppliers embed PLM workflows to synchronize with OEM platform timelines.
- Consumer Electronics:Rapid product refresh cycles demand agile change management. Design-centric workflows dominate procurement criteria over compliance modules.
Pharmaceuticals captures the highest margin per seat. Aerospace is gaining share fastest on defense modernization programs.
End User:
Supply chain position shapes functional requirements, with upstream players prioritizing engineering collaboration and downstream entities focusing on service lifecycle management.
- Manufacturers:OEMs and contract manufacturers constitute the core installed base, spanning discrete and process industries. Original equipment producers in Japan leverage METI-supported digital transformation subsidies to upgrade legacy PDM systems.
- Suppliers:Tier-two and tier-three component vendors adopt PLM primarily for OEM-mandated data exchange compliance. Cost pressure favors SaaS delivery over capital-intensive perpetual licenses.
- Service Providers:Maintenance and aftermarket operators utilize PLM asset records to optimize spare parts forecasting and field service scheduling.
- Retailers:Private-label product developers employ lightweight PLM modules for supplier qualification and quality management, typically at lower functionality tiers than industrial deployments.
Manufacturers host the deepest feature utilization. Suppliers are expanding most quickly as OEMs enforce digital thread connectivity mandates.
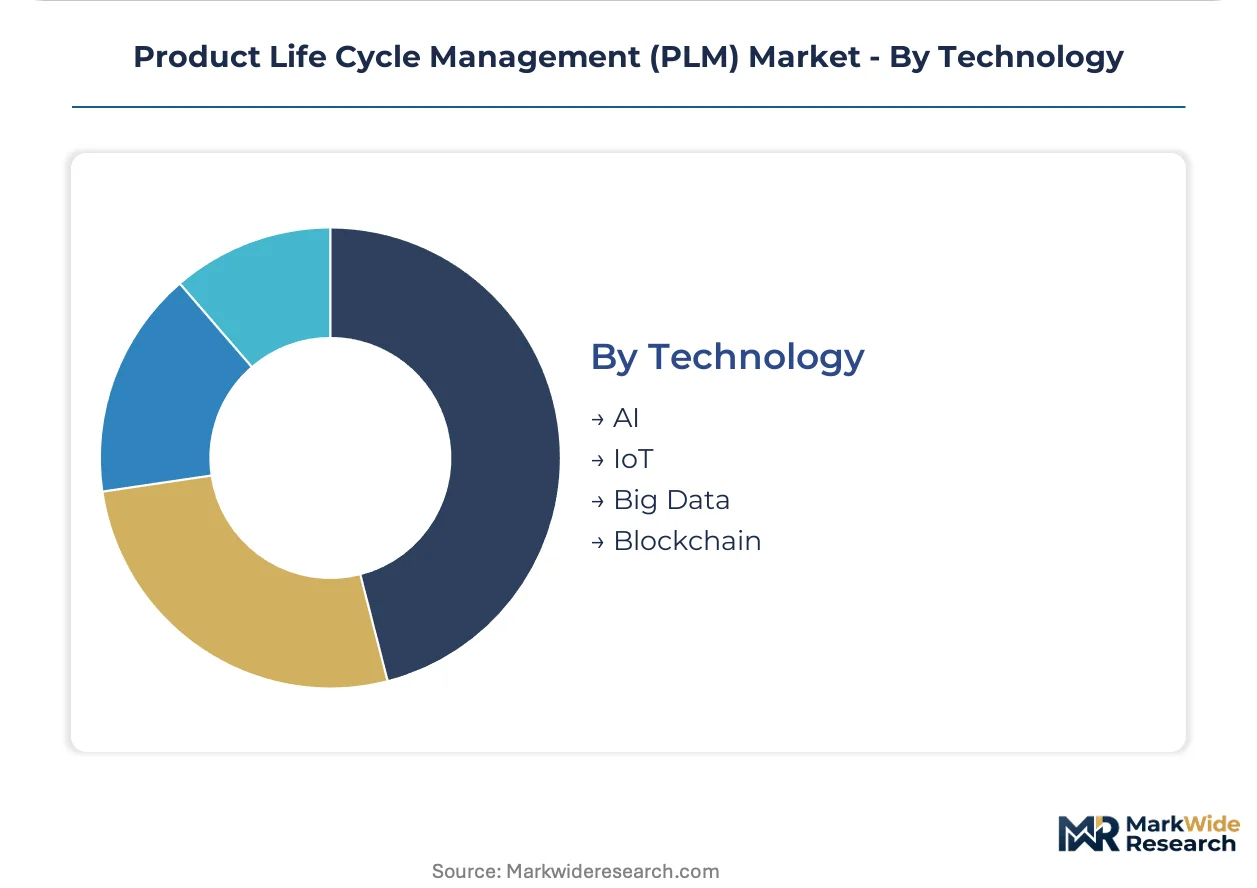
Technology:
Integration complexity and data infrastructure readiness determine which emerging technologies achieve production deployment versus pilot purgatory.
- AI:Generative design automation compresses concept-to-prototype cycles by exploring solution spaces beyond human engineering intuition. Predictive maintenance algorithms consume PLM asset records to forecast component degradation.
- IoT:Sensor telemetry from fielded products closes the loop between design assumptions and operational reality. Digital twin fidelity depends on real-time data ingestion architectures.
- Big Data:Cross-program analytics identify systemic quality patterns across product generations. Storage and compute economics favor cloud-native deployments for petabyte-scale engineering datasets.
- Blockchain:Distributed ledger prototypes address counterfeit component verification and immutable audit trails, though transaction throughput limitations constrain mainstream adoption.
IoT anchors current integration spending. AI is climbing the fastest as EU AI Act traceability requirements create compliance-driven demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier density anchors PLM deployment intensity across manufacturing verticals, with tier-one component manufacturers embedding validated workflows to satisfy KBA type-approval documentation standards.
Germany
Automotive OEMs and industrial machinery producers drive enterprise PLM adoption at scale. KBA type-approval documentation standards enforce embedded PLM workflows among tier-one suppliers. Stuttgart and Munich host the deepest concentrations of validated system deployments for electrification program synchronization.
United States
Aerospace manufacturers and defense contractors prioritize sovereign-hosted architectures for complex component traceability. FAA airworthiness directives and ITAR data residency constraints shape procurement decisions. Seattle and Dallas-Fort Worth clusters exhibit the fastest cloud migration velocity for distributed supplier network management.
China
Domestic automotive electrification and industrial equipment modernization expand PLM requirements among state-linked manufacturers. NMPA and GB standards tighten product data localization rules that reshape cloud deployment architectures. Shanghai and Shenzhen anchor regional implementation intensity for multinational manufacturing subsidiaries.
India
Generic drug manufacturers accelerate validated PLM adoption as CDSCO alignment with ICH guidelines tightens audit-ready documentation obligations. PLI scheme subsidies for medical device and pharmaceutical production expand addressable market scope. Hyderabad and Ahmedabad clusters concentrate deployment activity among contract research and manufacturing organizations.
Japan
Original equipment producers leverage METI-supported digital transformation subsidies to upgrade legacy PDM systems toward cloud-native architectures. Automotive and precision machinery sectors dominate procurement volumes. Nagoya and Osaka industrial corridors exhibit the strongest migration momentum for simulation-integrated PLM environments.
Product Life Cycle Management (PLM) Market Vendor Landscape
Global majors compete with regional champions across platform architecture philosophies, with consolidated incumbents defending integrated stack positions against cloud-native challengers. Siemens, Dassault Systèmes, and PTC occupy the upper tier through manufacturing domain depth and aerospace-automotive certification heritage. Mid-market specialization and vertical-specific workflow optimization represent the two dominant competitive vectors.
Among the established industrial software majors, Siemens anchors European manufacturing workflows through deep domain expertise in automotive and machinery sectors. Autodesk exemplifies design-centric platform positioning that extends from concept engineering through manufacturing handoff. PTC occupies a distinct position through IoT-integrated architectures that serve connected product environments and predictive maintenance applications.
| Leading Market Players |
|---|
| Aras |
| Arena Solutions |
| Siemens |
| Autodesk |
| Centric Software |
| PTC |
| Propel |
| Oracle |
| Dassault Systèmes |
| Others |
Supply Flow & Price Mechanics
Validated-system premiums versus commodity SaaS tiers bifurcate PLM procurement, with FDA 21 CFR Part 11 compliance commanding threefold pricing multiples over unvalidated cloud deployments while concentrating supply chain influence among Siemens, Dassault Systèmes, and PTC in Germany and the United States.
Pricing Analysis
Input-cost pass-through from sovereign data center buildouts and ISO 27001 certification overhead flows disproportionately into subscription rates for aerospace and pharmaceutical deployments. SaaS-tiered pricing stratifies across premium validated tiers, standard multi-tenant cloud, and economy self-service modules, with FDA and EMA certification levels driving the steepest price differentiation. Cost compression in mid-market manufacturing SaaS is intensifying because Autodesk and Arena Solutions compete aggressively on implementation speed. Tier-two automotive suppliers exhibit the highest price sensitivity, while Class III medical device producers accept premium pricing without negotiation.
Supply Chain Analysis
China's NMPA data localization mandates and India's PLI scheme domestic-content rules are reshaping sourcing architectures for multinational PLM vendors, forcing regional hosting partnerships and in-country development centers. Software development and cloud infrastructure provision concentrate in the United States, Germany, and India, with implementation consulting drawing from Eastern European talent pools. Raw material dependencies center on semiconductor compute hardware, subsea fiber connectivity, and specialized engineering labor. Single-source vulnerability runs through hyperscaler cloud platforms for multi-tenant deployments. Distribution runs through direct enterprise sales teams and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native migration and AI module attach rates present a margin-expansion trajectory, with automated implementation tooling compressing delivery costs while predictive maintenance subscriptions capture recurring premium tiers.
For Market Incumbents: To counter cloud-native challengers like Aras and Arena Solutions, Siemens and PTC should deepen sovereign hosting footprints in China and India to satisfy NMPA and CDSCO data residency mandates. Certification investment in EU AI Act traceability modules offers defensive differentiation against modular entrants. For New Entrants and Emerging Players: Launch via vertical-specific SaaS templates targeting mid-market industrial machinery producers in Japan and Germany, where METI and KBA documentation requirements create compliance-driven demand with lower incumbent switching costs. White-space concentration sits in pharmaceutical contract manufacturing organizations in India seeking validated systems without seven-figure perpetual license commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with IoT-integrated platform specialists possessing live digital twin deployments in automotive and aerospace accounts. Long-term viability favors vendors with outcome-based service contract revenue exceeding thirty percent of total bookings. Watch FDA 21 CFR Part 11 audit enforcement intensity as the inflection signal for validated-system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | NMPA and KBA data residency rules force regional infrastructure investment in China and Germany. |
| AI Traceability Module Development | EU AI Act risk-classification requirements create compliance-driven attach-rate opportunities in medical devices. |
| Digital Twin Platform Integration | Automotive OEMs in Stuttgart and Munich demand real-time virtual replicas for electrification program synchronization. |
| Mid-Market SaaS Template Launch | Japanese machinery producers leverage METI subsidies to abandon legacy PDM systems for cloud-native alternatives. |
| Validation Services Acquisition | FDA 21 CFR Part 11 expertise scarcity in India and Europe supports rollup strategies for specialized consultancies. |
Methodological Framework
Multiple input streams — primary interviews with PLM implementation directors, cloud procurement officers, and regulatory affairs leads at pharmaceutical and aerospace manufacturers; secondary validation against FDA 510(k) filings, EMA submission databases, and hyperscaler regional capex disclosures; plus customs data on industrial software trade flows — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Historical adoption curves from automotive electrification programs and pharmaceutical generic manufacturing expansions were cross-referenced against panel input from tier-one supplier procurement teams to anchor trajectory assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale, vertical compliance intensity, integration complexity tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration curves and validated against disclosed booking growth from listed industrial software majors. Forecast inputs incorporated sovereign data center buildout timelines and AI module attach-rate assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NMPA enforcement actions or ITAR restriction expansions affecting defense contractor cloud migration. Forecasts reflect documented assumptions on subscription pricing convergence and mid-market SaaS penetration ceilings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Latin America IT Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Master Data Management Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Chile ICT Market